
 Fiber Optics Market | 2026-2036
Fiber Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optics Market Analysis
The EU F-Gas Regulation is hardening emission thresholds for fluorinated gas use in fiber preform manufacturing, elevating capital requirements for new entrants. Corning Incorporated sustains its position through captive supply of high-purity synthetic silica and vertical control over the draw tower process. Prysmian Group anchors European supply security with integrated cable-and-systems production across multiple continental hubs. Yangtze Optical Fibre and Cable Joint Stock Limited Company dominates volume production for China's domestic 5G backhaul and rural broadband buildouts.
Fiber optics refers to flexible glass or plastic filaments engineered to transmit light signals with minimal attenuation, typically specified by core diameters ranging from 8 to 62.5 micrometers and loss budgets below 0.2 dB per kilometer at 1550 nanometer wavelength. These waveguides serve as the physical backbone for high-capacity data transmission across telecommunications, sensing, and medical illumination systems. Single mode fiber commands the largest revenue share in long-haul and submarine cable systems where dispersion control determines performance economics. Multi-mode fiber competes aggressively in data center interconnects under 500 meters, where cost-per-transceiver advantages outweigh bandwidth-distance limitations. Photonic integrated circuit technology is displacing discrete component architectures in coherent transceivers, compressing form factors while multiplying channel densities.
The US FCC enforces broadband deployment benchmarks that directly shape carrier capex cycles and fiber strand commitments. China's MIIT governs national standards for optical cable durability and connector interoperability under GB specifications. Japan's METI coordinates R&D consortia targeting next-generation hollow-core fiber for ultra-low latency financial networks. Stakeholders must monitor regulatory calibration of domestic content requirements, as these rules increasingly determine supplier qualification timelines and contract eligibility across major procurement programs.
Market Dynamics
Data center operators are expanding fiber deployments to support AI-driven compute workloads, creating a demand surge that is reshaping supplier capacity allocation and preform manufacturing priorities across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Tightening emission thresholds for fluorinated gas use in fiber preform manufacturing are accelerating capital investment in cleaner production technologies among European suppliers.
- 5G backhaul buildouts:China's national broadband expansion programs continue to drive cable procurement volumes for rural connectivity and mobile infrastructure.
- Photonic integrated circuits:This technology is compressing transceiver form factors while multiplying channel densities in coherent optical systems.
Market Restraints
- High-purity synthetic silica supply:Captive production of this critical input concentrates among vertically integrated incumbents, limiting new entrant access.
- Submarine cable system lead times:Multi-year deployment cycles and specialized vessel requirements create capital lock-in that deters speculative capacity expansion.
- Hollow-core fiber maturity gap:Ultra-low latency promises remain constrained by manufacturing yield challenges and connector compatibility limitations.
Strategic Opportunities
- Medical illumination systems:Flexible fiber bundles for surgical and diagnostic applications represent an underpenetrated vertical with premium pricing potential.
- Japan METI R&D consortia:Government-coordinated development programs for next-generation fiber technologies offer funding pathways for specialized suppliers.
- Direct-to-hyperscale contracting:Bypassing traditional distributor networks allows manufacturers to capture margin from data center operators with standardized specifications.
Industry Challenges
- Preform manufacturing expertise:Specialized chemical vapor deposition technicians remain scarce relative to expansion timelines, constraining output scaling.
- GB standard certification:China's mandatory optical cable durability and connector interoperability testing creates extended qualification periods for foreign suppliers.
- Legacy multi-mode infrastructure:Data center operators face complex migration paths when upgrading from OM3/OM4 to single-mode architectures for 400G+ speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optics Market |
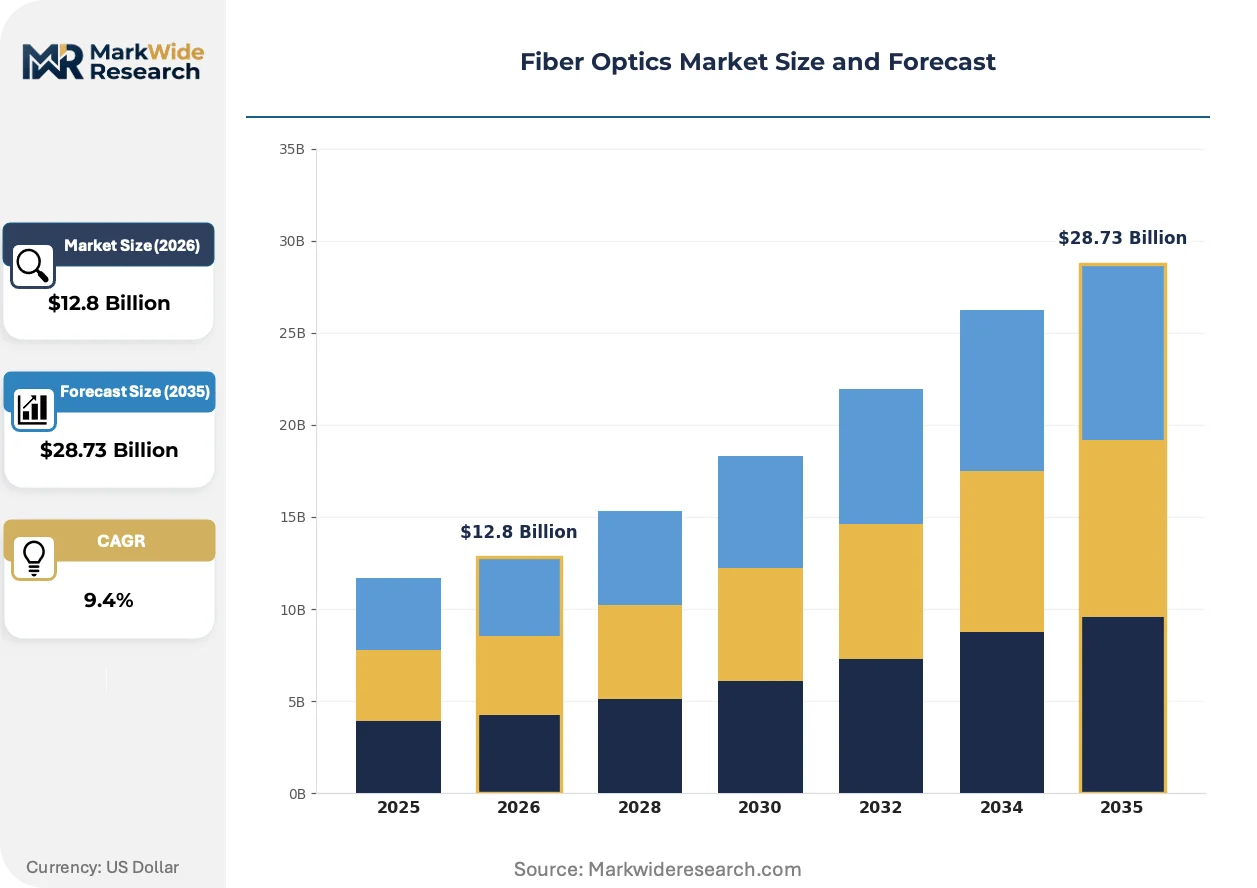
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Mode, Multi-Mode, Specialty Fiber, Loose Tube End User: Telecommunications, Data Centers, IT Services, Military Application: Telecommunication Network, Broadband, Industrial Automation, Medical Imaging Technology: Active Optical Cable, Optical Amplifier, Photonic Integrated Circuit, Wavelength Division Multiplexing |
| Companies Covered | Corning Incorporated, Prysmian Group, Sumitomo Electric Industries, Ltd., Fujikura Ltd., Yangtze Optical Fibre and Cable Joint Stock Limited Company, Furukawa Electric Co. Ltd., YOFC, LS Cable & System Ltd., CommScope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optics Market Emerging Trajectories
Photonic integration and hollow-core fiber development are compressing traditional component boundaries while regulatory pressure on manufacturing emissions intensifies process innovation requirements.
Photonic integrated circuit technology is overtaking discrete component architectures in coherent transceivers. Cloud providers and telecom carriers are adopting these compact modules for 400G and 800G line-side applications. This convergence is collapsing supplier tiers and shifting value capture toward semiconductor foundries with silicon photonics capability.
REACH chemical restrictions and the EU F-Gas Regulation are tightening compliance burdens on European fiber preform manufacturers. These frameworks are elevating capital requirements for emission control systems and alternative precursor chemistry development. Suppliers with captive synthetic silica production and established environmental management systems are securing preferential qualification status under procurement sustainability scorecards.
Hyperscale buyers are consolidating optical cable procurement through direct master service agreements rather than tiered distributor networks. This channel compression is eliminating margin layers for regional distributors while rewarding manufacturers with global logistics capability and standardized product platforms. The shift is most visible in North American and European data center markets where specification uniformity enables volume consolidation.
Fiber Optics Market Segmentation
Segmentation in fiber optics reveals how technical specifications, deployment environments, and integration architectures fragment demand across incompatible procurement criteria. Buyers optimize for attenuation budgets, bend radius tolerance, or transceiver interoperability depending on infrastructure scale and latency requirements.
Product Type:
Cost tier separates buyers seeking premium performance from those prioritizing installation flexibility and field termination speed.
- Single Mode:Engineered with 8-10 micrometer core diameters and germanium-doped silica cladding to minimize chromatic dispersion across 1550 nanometer transmission windows. Long-haul carriers and submarine cable operators in China and the United States specify this grade for transoceanic routes where signal regeneration costs dominate lifecycle economics.
- Multi-Mode:Larger 50-62.5 micrometer cores support multiple propagation paths using lower-cost vertical-cavity surface-emitting laser transceivers. Hyperscale data center operators in Ashburn, Frankfurt, and Singapore deploy OM4 and OM5 variants for spine-leaf architectures under 500 meters where cost-per-link outweighs bandwidth-distance constraints.
- Specialty Fiber:Polarization-maintaining and radiation-hardened variants serve aerospace and nuclear sensing applications with extreme environmental tolerance requirements.
- Loose Tube:Gel-filled buffer structures protect stranded fibers from moisture and mechanical stress in outdoor aerial and direct-buried deployments across rural broadband programs.
Volume sits with Single Mode; growth tilts toward Multi-Mode.
End User:
Application maturity determines whether buyers specify standardized cable assemblies or demand custom-engineered connectivity solutions.
- Telecommunications:Incumbent carriers and mobile network operators procure massive fiber counts for 5G fronthaul, backhaul, and passive optical network access layers. China's MIIT-mandated gigabit city programs and the United States FCC broadband deployment benchmarks drive recurring strand commitments with 20-year depreciation horizons.
- Data Centers:Cloud providers and colocation operators source pre-terminated trunk cables and breakout modules for rapid rack-and-stack deployment. Direct-to-manufacturer contracting bypasses distributor markups where specification uniformity enables volume consolidation across North American and European facilities.
- IT Services:Systems integrators and managed service providers bundle fiber connectivity with switching infrastructure for enterprise campus and metro area network refreshes.
- Military:Defense procurement programs specify tactical cable reels and harsh-environment connectors for battlefield communications and avionics data buses under MIL-STD qualification protocols.
Telecommunications commands installed base; Data Centers are climbing the fastest.
Application:
Regulatory intensity varies sharply across verticals, with healthcare and critical infrastructure facing mandatory certification regimes that consumer broadband avoids.
- Telecommunication Network:Core, metro, and access layer fiber installations carry 99.999% availability requirements with diverse route redundancy. Submarine cable systems linking Japan, the United Kingdom, and Brazil require specialized armored cable designs and dedicated fleet installation contracts spanning multi-year deployment cycles.
- Broadband:Government-subsidized rural connectivity programs in India, Germany, and Australia prioritize cost-per-passed-premise metrics over technical performance headroom. China's national broadband expansion continues driving cable procurement volumes for village-level fiber-to-the-home connections.
- Industrial Automation:Factory floor fiber networks resist electromagnetic interference from welding equipment and variable frequency drives in automotive and semiconductor manufacturing plants.
- Medical Imaging:Bundled fiber optic light guides and coherent imaging fibers enable endoscopic visualization and laser surgical systems with biocompatibility and sterilization tolerance requirements.
Telecommunication Network absorbs capital; Medical Imaging offers steepest expansion trajectory.
Technology:
Integration depth separates discrete component suppliers from semiconductor foundries capturing value through silicon photonics convergence.
- Active Optical Cable:Factory-terminated transceiver-to-cable assemblies eliminate field splicing for data center interconnects and high-performance computing clusters. Intel, Broadcom, and Marvell dominate the electrical-to-optical conversion chipsets embedded in these plug-and-play links.
- Photonic Integrated Circuit:Monolithic silicon or indium phosphide platforms integrate lasers, modulators, and detectors for coherent 400G and 800G transceivers. Cloud providers and telecom carriers in Japan and the United States are adopting these compact modules, collapsing traditional supplier tiers and shifting value toward semiconductor fabrication capacity.
- Optical Amplifier:Erbium-doped fiber amplifiers and Raman amplification systems extend unrepeatered transmission distances across submarine and terrestrial long-haul routes.
- Wavelength Division Multiplexing:Dense and coarse multiplexing technologies multiply single-fiber capacity through orthogonal wavelength channels in carrier backbone networks.
Optical Amplifier anchors legacy infrastructure; Photonic Integrated Circuit is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate preform manufacturing capacity, drawing foreign joint ventures and domestic champions into clustered supply chains. Tax incentives for high-technology imports accelerate equipment refresh cycles across coastal provinces.
United States
FCC broadband deployment benchmarks mandate carrier capital expenditure cycles that directly shape fiber strand procurement volumes. The Infrastructure Investment and Jobs Act subsidizes rural connectivity programs prioritizing fiber-to-the-home over fixed wireless alternatives. Greater Dallas-Fort Worth hosts dense clusters of hyperscale data center campuses where direct-to-manufacturer contracting bypasses traditional distribution channels.
China
MIIT-mandated gigabit city programs and 5G backhaul buildouts sustain massive cable procurement for rural broadband expansion. GB standard certification for optical cable durability creates extended qualification timelines that favor incumbent suppliers with established testing relationships. Wuhan anchors domestic volume production, leveraging captive synthetic silica supply and integrated draw tower operations.
Germany
EU F-Gas Regulation tightening forces emission control investments across preform manufacturing facilities serving European carrier markets. REACH chemical restrictions elevate compliance burdens for alternative precursor chemistry development. Ruhr industrial corridor cable plants integrate sheathing and armoring operations with continental logistics hubs.
Japan
METI-coordinated R&D consortia target hollow-core fiber development for ultra-low latency financial network applications. JIS standards govern connector interoperability in submarine cable landing stations linking Tokyo-Osaka corridors to transpacific routes. Nagoya-Chubu manufacturing clusters specialize in polarization-maintaining fiber for aerospace sensing systems.
India
BharatNet rural broadband subsidies prioritize cost-per-passed-premise metrics in village-level fiber-to-the-home deployments. TRAI mandates on right-of-way clearance accelerate metro fiber ring construction in tier-1 cities. Chennai-Bengaluru industrial corridor attracts sheathing and cable assembly investments serving Middle East export markets.
Fiber Optics Market Vendor Landscape
North American and European producers anchor one tier; East Asian specialists hold manufacturing scale advantages in preform and draw tower operations. The vendor base separates into three distinct strata: vertically integrated incumbents with captive synthetic silica supply, regional cable assemblers dependent on merchant preform sources, and semiconductor foundries capturing value through silicon photonics convergence. Strategic moves concentrate on backward integration into high-purity material production and direct contracting relationships with hyperscale data center operators.
Among vertically integrated incumbents, Corning Incorporated and Prysmian Group exemplify archetypes combining captive material supply with continental manufacturing footprints. Yangtze Optical Fibre and Cable Joint Stock Limited Company occupies a position representing volume-driven production scale serving domestic Chinese infrastructure programs. These three anchors illustrate divergent competitive positioning: technology leadership through materials science, supply security through geographic diversification, and cost optimization through integrated national market capture.
| Leading Market Players |
|---|
| Corning Incorporated |
| Prysmian Group |
| Sumitomo Electric Industries, Ltd. |
| Fujikura Ltd. |
| Yangtze Optical Fibre and Cable Joint Stock Limited Company |
| Furukawa Electric Co. Ltd. |
| YOFC |
| LS Cable & System Ltd. |
| CommScope |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation hardens emission thresholds for fluorinated gas use in fiber preform manufacturing, gating qualified supply access and elevating premium-tier pricing for compliant European production. Buyers seeking sustainability-certified cable face extended lead times and cost premiums, while spot inventory from non-compliant sources trades at discounts.
Pricing Analysis
Short lead-time premiums separate urgent hyperscale data center deployments from standard carrier procurement cycles with 90-day buffers. Contract-based long-term offtake dominates submarine and terrestrial backbone projects, while spot transactions serve emergency restoration and small-batch enterprise needs. Price differentiation hinges on GB standard certification tier and captive synthetic silica supply. Cost compression in multi-mode fiber intensifies as merchant preform sources expand, squeezing regional cable assemblers. Enterprise IT services buyers exhibit highest price sensitivity; submarine cable operators show least, prioritizing 25-year lifecycle reliability over unit cost.
Supply Chain Analysis
China's MIIT domestic-content mandates for national broadband programs reshape sourcing, favoring Wuhan-based suppliers with integrated draw tower operations. Manufacturing gravity centers on China, the United States, and Japan for preform and fiber drawing; Germany and India anchor cable sheathing and assembly. The chain rests on high-purity synthetic silica, germanium tetrachloride precursors, and specialized chemical vapor deposition equipment. Single-source vulnerability concentrates in synthetic silica supply controlled by vertically integrated incumbents. Distribution runs through direct master service agreements with hyperscale operators, bypassing traditional distributor tiers in North American and European data center corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber optics market sits in a technology-transition phase as photonic integrated circuits displace discrete component architectures in coherent transceivers, collapsing supplier tiers and shifting value capture toward semiconductor fabrication.
For Market Incumbents: Anchor market position through captive synthetic silica supply expansion and backward integration into preform manufacturing. Defend against silicon photonics foundries by deepening relationships with hyperscale data center operators through direct contracting. Prioritize emission-control technology investment to maintain EU procurement qualification under tightening F-Gas thresholds.
For New Entrants and Emerging Players: The price-point gap between premium single-mode submarine cable and economy-tier rural broadband fiber creates entry space for mid-market specialists. Target India's BharatNet village connectivity programs and Germany's subsidized rural fiber-to-the-home buildouts where specification tolerance enables competitive positioning. Pursue medical illumination systems as a white-space vertical with premium pricing and lower certification barriers than telecom infrastructure.
For Investors and Strategic Acquirers: METI-coordinated hollow-core fiber consortium funding announcements are the leading indicator that ultra-low latency financial network applications are approaching commercial viability. Frame long-term viability around 5-10 year infrastructure replacement cycles and data center AI workload expansion. Target acquisition profiles featuring captive material supply and established hyperscale direct relationships. Watch for GB standard certification timeline compression as a signal of foreign supplier qualification easing in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Silica | Secures critical input supply against merchant preform price volatility and F-Gas compliance costs. |
| Direct-to-Hyperscale Contracting | Bypasses distributor margin capture in Ashburn, Frankfurt, and Singapore data center corridors. |
| Photonic Integrated Circuit Platform Development | Captures value shift from discrete transceivers toward silicon foundry-based coherent modules. |
| Hollow-Core Fiber R&D Consortium Participation | Positions for ultra-low latency financial network specifications through METI-coordinated programs. |
| Medical Illumination Vertical Expansion | Diversifies revenue into surgical fiber bundles with premium pricing and lower regulatory barriers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fiber preform manufacturing executives, hyperscale data center procurement officers, submarine cable system engineers, and carrier network planning directors combined with FCC broadband deployment reports, MIIT gigabit city program disclosures, EU F-Gas Regulation compliance databases, and SEC 10-K filings from listed suppliers. Bottom-up fiber strand demand modeling and top-down cable revenue estimates underwent cross-validation.
Data-stream reconciliation across shipment volumes, preform production capacity, and carrier capital expenditure disclosures shaped the analytical framework. Segmentation dimensions modeled include fiber type, end-use vertical, application environment, and technology integration depth. CAGRs derived from regression analysis of historical procurement patterns and infrastructure deployment schedules. Forecast inputs incorporated AI-driven data center interconnect demand projections and rural broadband subsidy program commitments.
Inputs from carrier procurement databases and hyperscaler capital expenditure disclosures were available through the study window; gaps in real-time preform inventory levels and merchant silica spot pricing introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented infrastructure deployment schedules and regulatory compliance timelines. Risks of tariff escalation on Chinese optical cable imports or hollow-core fiber manufacturing yield breakthroughs could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Smart Photochromic Lenses Market
Optics
Smart Glass Market
Optics
Liquid Crystal on Silicon Market
Optics
MEMS Mirrors Market
Optics
Optical Fiber Raw Material Market
Optics
Excimer Laser Market
Optics
Polymeric Optical Fiber Market
Optics
Beam Combining Optics Market
Optics
Fiber Optic Switch Market
Optics
AR and VR Lens Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Optical Measuring Systems Market
Optics
US Photonics Market
Optics
Picosecond Lasers Market
Optics
Digital Holographic Microscopy Market
Optics
Smartphone Camera Lenses Market