
 Beam Expanders Market | 2026-2036
Beam Expanders Market Size, Share, and Industry Trends Forecast 2026-2036
Beam Expanders Market Analysis
Semiconductor equipment makers is reorganizing demand away from legacy industrial laser integrators toward precision lithography and metrology specialists. Jenoptik AG leverages its vertical integration in optical glass and coatings to dominate EUV-grade beam expander supply. Thorlabs, Inc. sustains broad catalog coverage across research and industrial segments with standardized Galilean designs. Edmund Optics Inc. competes on rapid customization turnaround for defense and aerospace qualification programs.
A beam expander is an optical assembly that enlarges the diameter of a collimated laser beam while reducing its divergence angle, typically employing Galilean or Keplerian lens configurations with wavefront error specifications below lambda over ten. The device serves to protect downstream optical components from power density damage and to improve focusing characteristics in material processing and remote sensing systems. Galilean and telecentric types anchor current revenue owing to their compact form factor and absence of internal focal points that would induce air breakdown at high pulse energies. Variable beam expanders represent the fastest-expanding category as adaptive manufacturing lines require real-time spot size adjustment without mechanical changeover. Fiber-optic and free-space technology segments split the market between telecommunications trunk lines and stand-alone industrial laser systems, with margin pools concentrating in free-space assemblies for defense-directed energy applications.
FDA laser product performance standards govern medical device beam expander safety in the United States, while the EU Machinery Directive and CE marking requirements enforce laser classification and interlock protocols across European industrial installations. China's SAMR administers GB standards for industrial laser equipment that increasingly reference IEC 60825-1 international safety benchmarks. Stakeholders must monitor divergence between national laser safety certification regimes and the pace of semiconductor capital expenditure cycles to align capacity planning with qualification timelines.
Market Dynamics
Semiconductor lithography equipment manufacturers are consolidating procurement around EUV-grade beam expanders, compressing qualification timelines and displacing legacy industrial laser integrators from premium supply tiers.
Growth Catalysts
- EUV lithography ramp:Flat-panel display and battery cell manufacturing lines in East Asian precision optics clusters are scaling procurement of Galilean and telecentric configurations for next-generation node production.
- China's dual carbon goals:Stricter energy efficiency mandates under SAMR-administered GB standards are accelerating replacement cycles in industrial laser installations.
- Germany's laser safety standards:Tighter interlock and classification protocols under the EU Machinery Directive are forcing upgrade demand across legacy European industrial bases.
Market Restraints
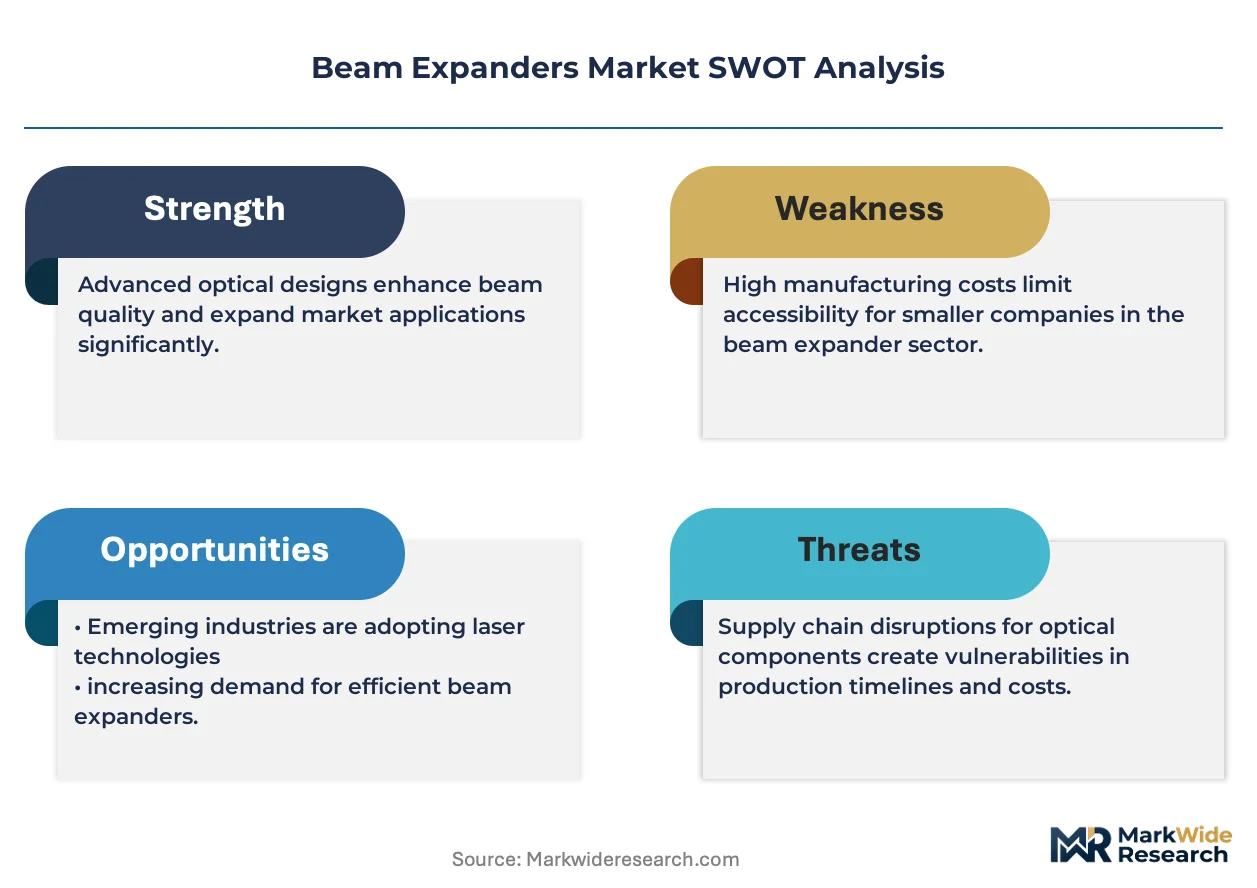
- Optical glass supply concentration:High-purity fused silica and calcium fluoride sourcing remains captive to a narrow supplier base in Japan and Germany, amplifying input cost volatility.
- EUV coating technical barriers:Multilayer dielectric specifications below lambda over twenty remain beyond reach for second-tier coating houses, consolidating production among vertically integrated specialists.
- Qualification timeline friction:FDA laser product performance standards and CE marking cycles extend eighteen to thirty-six months, freezing out speculative capacity additions.
Strategic Opportunities
- Defense-directed energy applications:Free-space beam expander assemblies for high-energy laser weapon programs represent an underpenetrated margin pool with qualification barriers protecting incumbent positions.
- Variable configuration demand:Adaptive manufacturing lines requiring real-time spot size adjustment without mechanical changeover are creating white space for motorized zoom designs.
- IEC 60825-1 harmonization:China's progressive alignment of GB standards with international safety benchmarks is streamlining export pathways for qualified suppliers.
Industry Challenges
- Wavefront metrology talent scarcity:Specialized optical engineers capable of interferometric testing at sub-nanometer precision command premium compensation and extended recruitment cycles.
- Cleanroom capex intensity:EUV-grade assembly requires Class 1000 or better environments, with facility investments running into tens of millions per production line.
- Legacy system integration friction:Keplerian designs with internal focal points persist in installed industrial laser bases, complicating retrofit pathways for Galilean replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beam Expanders Market |
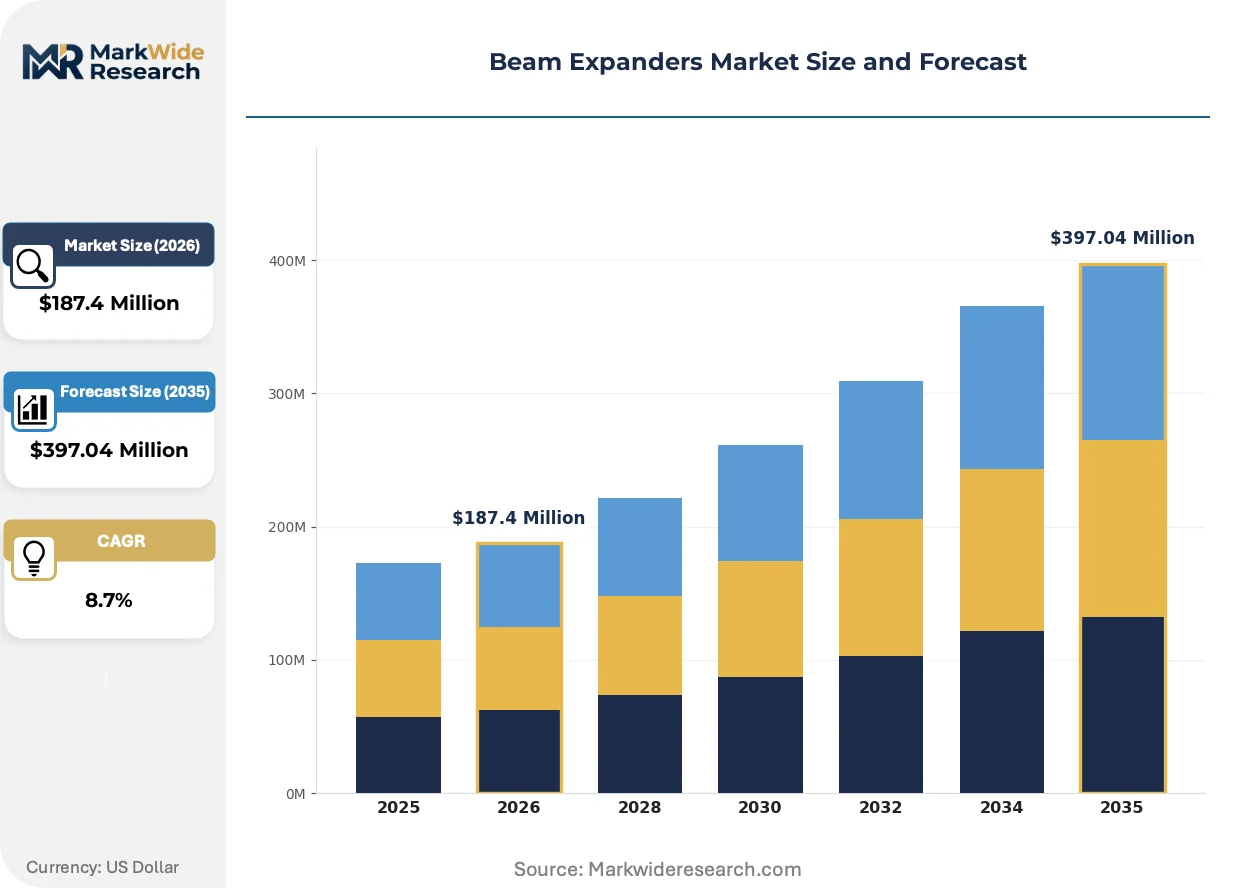
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Telecentric, Galilean, Keplerian, Variable Application: Optical Communication, Laser Material Processing, Medical Devices, Defense End User: Aerospace, Automotive, Research Institutions, Industrial Technology: Active, Passive, Fiber-Optic, Free-Space |
| Companies Covered | Jenoptik AG, Excelitas, Thorlabs, Inc., Qioptiq Photonics GmbH & Co. KG, Sill Optics GmbH, Newport Corporation, Coherent Inc., OptoSigma Corporation, Edmund Optics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beam Expanders Market Emerging Trajectories
Active alignment and adaptive optics are compressing traditional assembly methodologies while variable beam expander architectures capture disproportionate development investment across precision optics clusters.
Variable beam expander technology is bifurcating the product landscape between fixed-configuration commodity units and motorized zoom assemblies capable of real-time divergence adjustment. Semiconductor capital equipment buyers are specifying the latter for adaptive lithography lines, forcing fixed-design suppliers toward industrial laser aftermarket maintenance pools. The structural consequence is a pricing spread that separates telecommunication trunk line applications from defense-directed energy programs by an order of magnitude.
REACH and RoHS substance restrictions are tightening permissible material palettes for optical coatings and housing alloys across European industrial installations. Manufacturers are reformulating multilayer stacks to eliminate hexavalent chromium and cadmium-based processes, extending qualification timelines but creating defensible positions for early compliant suppliers. Medical device beam expander segments face the steepest compliance burden under the EU MDR, with notified body backlogs delaying market entry.
Buyer concentration among semiconductor lithography OEMs is compressing vendor negotiation cycles and unbundling after-sales service from hardware procurement. Flat-panel display manufacturers in South Korea and Taiwan are consolidating supplier panels to three qualified sources per component category, displacing catalog distributors from premium tier access. This pattern is most visible in EUV-grade procurement, where direct OEM relationships now dominate legacy integrator channels.
Beam Expanders Market Segmentation
Beam expander procurement channels diverge sharply by performance tier, with semiconductor lithography OEMs demanding direct qualification while industrial laser integrators rely on catalog distributors. Understanding these channel dynamics illuminates where margin pools concentrate and where commoditization pressures intensify.
Type:
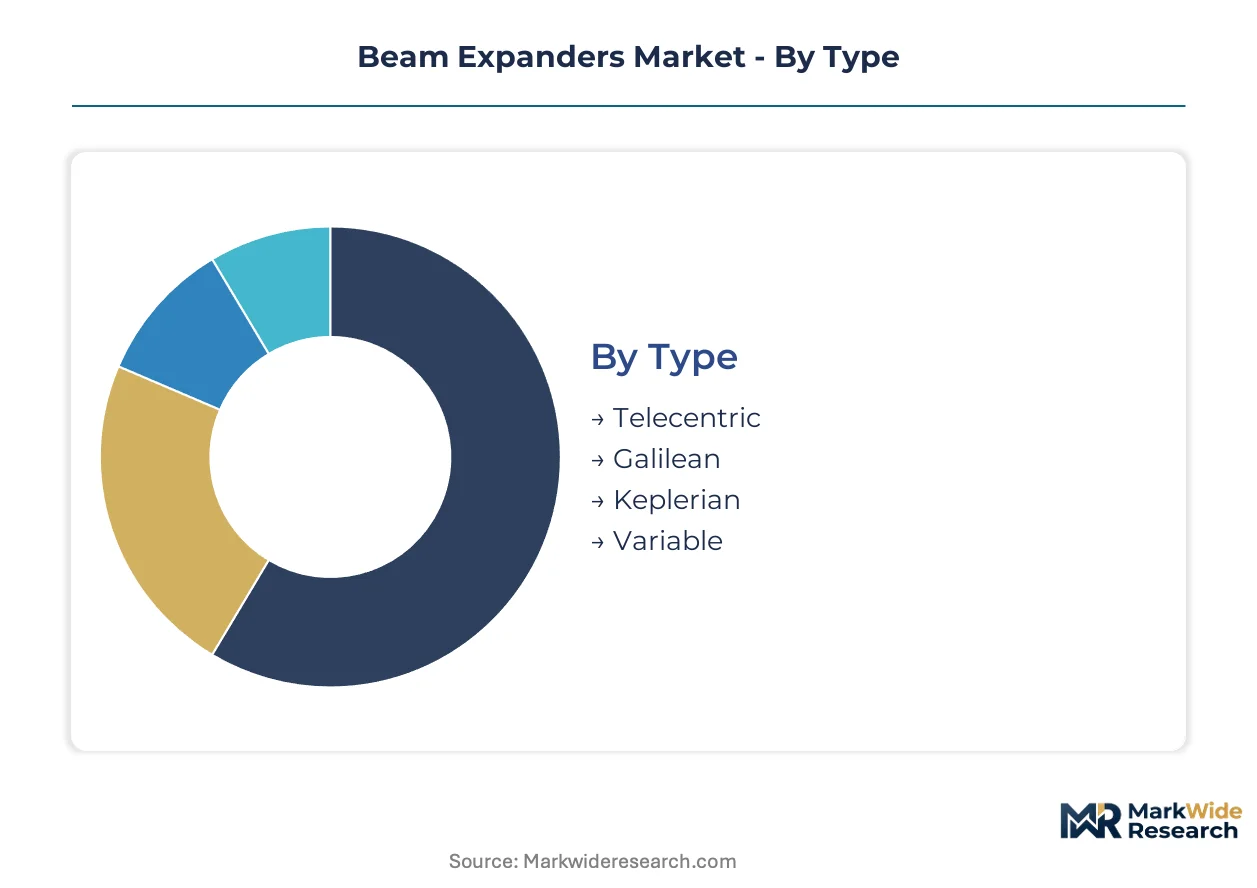
Galilean and telecentric configurations flow through precision optics specialists serving EUV lithography OEMs, while Keplerian designs persist in aftermarket industrial channels and variable units target adaptive manufacturing lines requiring real-time adjustment.
- Telecentric:Maintains constant magnification across working distance through compound lens arrangements with pupil telecentricity. Demand concentrates in flat-panel display manufacturing lines in South Korea and Taiwan, where SAMR-administered GB standards for industrial laser equipment are accelerating replacement cycles under China's dual carbon goals.
- Galilean:Employs negative followed by positive lens elements without internal focal points, eliminating air breakdown risk at high pulse energies. Semiconductor lithography equipment manufacturers in Germany and Japan are consolidating procurement around these configurations for EUV and DUV systems, compressing qualification timelines.
- Keplerian:Uses two positive focal length lenses with an intermediate focal point, requiring careful thermal management in high-power applications.
- Variable:Motorized zoom assemblies enable real-time divergence adjustment without mechanical changeover.
Galilean designs dominate installed base in semiconductor capital equipment. Variable configurations are where expansion concentrates, climbing the fastest as adaptive manufacturing lines proliferate.
Application:
Cost tier stratification separates defense-directed energy programs with qualification-protected margins from telecommunications trunk line applications facing commoditization.
- Laser Material Processing:Protects downstream optics from power density damage while improving focusing characteristics for cutting, welding, and additive manufacturing. Industrial laser installations across Germany are forcing upgrade demand under tighter EU Machinery Directive interlock protocols.
- Defense:Free-space assemblies for high-energy laser weapon programs command premium pricing due to extended qualification barriers and captive supply relationships.
- Optical Communication:Fiber-optic beam expanders serve telecommunications trunk lines with standardized performance specifications.
- Medical Devices:FDA laser product performance standards govern safety requirements, with EU MDR notified body backlogs delaying market entry for reformulated coating processes.
Laser material processing anchors volume demand. Defense applications are where margin expansion concentrates.
End User:
Customer type determines specification stringency, with aerospace and research institutions demanding interferometric testing at sub-nanometer precision while industrial buyers prioritize catalog availability.
- Industrial:Flat-panel display and battery cell manufacturing lines in East Asian precision optics clusters scale procurement of Galilean and telecentric types. China's SAMR-administered GB standards increasingly reference IEC 60825-1 international safety benchmarks, streamlining export pathways for qualified suppliers.
- Research Institutions:Require wavefront error specifications below lambda over ten for metrology and spectroscopy applications.
- Aerospace:Defense-directed energy programs and remote sensing systems specify free-space assemblies with multilayer dielectric coatings.
- Automotive:Battery cell manufacturing lines adopt beam expanders for laser welding in electric vehicle production.
Industrial end users dominate shipment volumes. Research institutions are where specification premiums concentrate.
Technology:
Supply concentration in high-purity fused silica and calcium fluoride sourcing from Japan and Germany amplifies input cost volatility across technology segments.
- Free-Space:Stand-alone assemblies for industrial laser systems and defense applications require Class 1000 or better cleanroom assembly environments. Multilayer dielectric specifications below lambda over twenty remain beyond reach for second-tier coating houses, consolidating production among specialists with backward integration into optical glass.
- Fiber-Optic:Integrates with telecommunications trunk lines and medical device systems.
- Passive:Fixed-configuration designs serve established industrial laser bases with standardized divergence requirements.
- Active:Incorporates adaptive optics and motorized alignment for real-time wavefront correction.
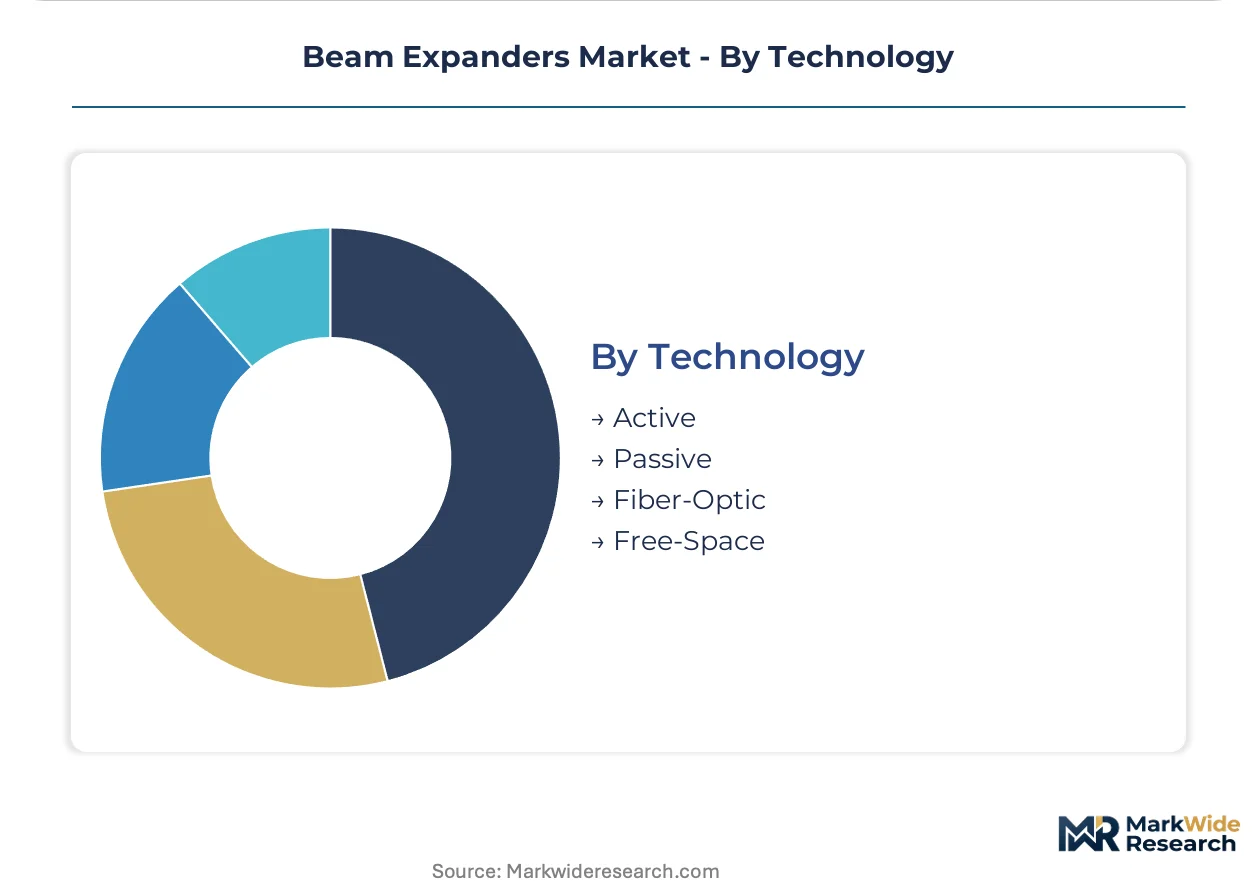
Passive technology dominates legacy installed base. Active configurations are where development investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's optical logistics corridors channel precision glass substrates into German lithography supply chains. Taiwan's Hsinchu Science Park rail links connect fused silica foundries to EUV assembly cleanrooms. Japan's Kansai International Airport freight terminals expedite calcium fluoride crystal shipments for semiconductor capital equipment.
United States
Defense-directed energy programs at Kirtland Air Force Base and Lawrence Livermore National Laboratory sustain demand for free-space beam expander assemblies. FDA laser product performance standards govern medical device safety requirements for surgical and dermatological applications. The Pacific Northwest precision optics cluster around Portland anchors high-volume production for industrial laser integrators serving battery cell manufacturing lines.
Germany
EUV lithography equipment manufacturers in Oberkochen and Jena consolidate procurement around Galilean configurations with wavefront specifications below lambda over ten. The EU Machinery Directive and tighter interlock protocols under national laser safety standards force upgrade demand across legacy industrial installations. The Baden-Württemberg precision optics corridor concentrates coating houses with backward integration into optical glass production.
China
Flat-panel display manufacturing lines in Suzhou and Shenzhen scale procurement of telecentric beam expanders for next-generation OLED production. SAMR-administered GB standards for industrial laser equipment increasingly reference IEC 60825-1 international safety benchmarks under dual carbon goals. The Yangtze River Delta precision optics cluster serves domestic battery cell manufacturing capacity for electric vehicle supply chains.
Japan
High-purity fused silica and calcium fluoride sourcing from Hokkaido and Kyushu remains captive to vertically integrated suppliers serving lithography OEMs. METI industrial policy prioritizes domestic semiconductor capital equipment supply chain resilience. The Chubu region around Nagoya concentrates precision glass fabricators with Class 1000 cleanroom assembly capabilities.
South Korea
Display manufacturers in Gyeonggi Province consolidate supplier panels to three qualified sources per beam expander component category. MFDS medical device regulations and KOSHA industrial safety standards govern laser equipment certification timelines. The Busan-Ulsan corridor hosts battery cell manufacturing lines adopting laser welding systems for electric vehicle production.
Beam Expanders Market Vendor Landscape
Concentration sits with vertically integrated specialists controlling optical glass melting and multilayer dielectric coating capabilities. The vendor base stratifies between EUV-grade qualification holders serving lithography OEMs and catalog distributors supplying industrial laser aftermarket maintenance. Three archetypes dominate: precision lithography specialists with captive substrate supply, broad-line photonics distributors with rapid customization turnaround, and defense-aerospace qualification holders with extended certification timelines. Capacity expansion and strategic partnerships represent the dominant competitive moves, with coating houses investing in Class 1000 cleanrooms and assembly specialists licensing wavefront metrology IP.
Among German-based precision optics fabricators, Jenoptik AG and Qioptiq Photonics GmbH & Co. KG occupy positions within the vertically integrated specialist tier, while Thorlabs, Inc. represents the broad-catalog archetype with standardized Galilean design coverage. These three entities exemplify the structural division between direct OEM relationships and distributor-mediated industrial channels.
| Leading Market Players |
|---|
| Jenoptik AG |
| Excelitas |
| Thorlabs, Inc. |
| Qioptiq Photonics GmbH & Co. KG |
| Sill Optics GmbH |
| Newport Corporation |
| Coherent Inc. |
| OptoSigma Corporation |
| Edmund Optics Inc. |
| Others |
Supply Flow & Price Mechanics
FDA laser product performance standards and CE marking protocols gate both supply qualification and price differentiation simultaneously, extending eighteen to thirty-six month timelines that freeze out speculative capacity and stratify vendors into protected premium tiers versus exposed commodity pools.
Pricing Analysis
Volume-discount tiering structures separate semiconductor lithography OEM direct procurement from catalog distributor channels by an order of magnitude, with Galilean and telecentric configurations commanding certification-grade premiums while Keplerian aftermarket units face commoditization. Price differentiation rests on EUV-grade wavefront specifications below lambda over ten and backward integration into optical glass melting. Pricing pressure stems from buyer consolidation to three qualified sources per component category in South Korea and Taiwan. Industrial laser integrators exhibit highest price sensitivity; defense-directed energy programs show lowest.
Supply Chain Analysis
Inbound logistics costs through the Port of Rotterdam and Kansai International Airport freight terminals amplify input volatility for high-purity fused silica and calcium fluoride sourced from Hokkaido and Kyushu. Raw material dependencies center on Japanese and German optical glass substrates, multilayer dielectric coatings, and precision-machined aluminum housings. Single-source vulnerability concentrates in vertically integrated coating houses with Class 1000 cleanroom capabilities. Distribution runs through precision optics specialists serving EUV lithography OEMs and catalog distributors supplying industrial laser maintenance pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beam expander demand sits in early-cycle expansion as EUV lithography ramp and adaptive manufacturing line proliferation extend addressable application scope beyond legacy industrial laser bases.
For Market Incumbents: Compound qualification-protected positions by deepening backward integration into calcium fluoride crystal growth and securing direct OEM relationships with lithography equipment manufacturers in Germany and Japan. Accelerate capacity additions in the Baden-Württemberg precision optics corridor to preempt second-tier coating house catch-up. Threat vector: motorized zoom variable designs displacing fixed-configuration installed base.
For New Entrants and Emerging Players: Aftermarket service-layer gaps in legacy Keplerian system retrofit and wavefront metrology talent provision offer white-space entry points. Target battery cell manufacturing lines in the Yangtze River Delta and Busan-Ulsan corridor where SAMR-administered GB standards accelerate replacement cycles. Go-to-market angle: rapid customization turnaround for defense-aerospace qualification programs.
For Investors and Strategic Acquirers: China's progressive IEC 60825-1 harmonization reshapes the acquisition landscape by streamlining export pathways for qualified suppliers. Long-term viability favors vertically integrated specialists with captive substrate supply and Class 1000 cleanroom assets. Signal to watch: semiconductor capital expenditure cycle inflection and notified body backlog resolution under EU MDR.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Glass | Captive supply of high-purity fused silica insulates against Japanese and German sourcing volatility. |
| Class 1000 Cleanroom Capacity Expansion | EUV-grade assembly environments command qualification barriers protecting premium margin pools. |
| Motorized Zoom Variable Design Launch | Adaptive manufacturing line demand creates pricing separation from fixed-configuration commodity units. |
| Defense-Aerospace Qualification Investment | Extended certification timelines under FDA and EU Machinery Directive protect incumbent positions. |
| East Asian Precision Optics Cluster Partnership | Direct relationships with South Korean and Taiwanese display manufacturers displace catalog distributors. |
Methodological Framework
A standing panel of semiconductor lithography procurement directors, industrial laser system integrators, precision optics coating specialists, and defense program engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA laser product performance standard filings, EU Machinery Directive CE marking databases, SAMR GB standard publications, and SEC 10-K disclosures from listed photonics suppliers. Bottom-up shipment estimates triangulated against top-down capital expenditure absorption models.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include beam expander type, application end-use, technology architecture, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating semiconductor equipment capital intensity and industrial laser replacement cycle dynamics. Industry-specific inputs encompass wavefront metrology talent availability and cleanroom facility investment pipelines.
Material uncertainties — EUV lithography node transition delays, optical glass supply disruptions, and divergence between national laser safety certification regimes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding qualification timeline friction and buyer consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Global Semiconductor Lasers Market
Optics
Smartphone Camera Lenses Market
Optics
Global Enhanced Vision System Market
Optics
Global Fiber Optic Sensors Market
Optics
Smart Vision Systems Market
Optics
Optical Profilometer Market
Optics
Anti Glare Film Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Polymeric Optical Fiber Market
Optics
North America Optical Imaging Market
Optics
Liquid Crystal on Silicon Market
Optics
Anomaloscope Market
Optics
India Laser Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Solid State Lasers Market
Optics
EUV Pellicle Market