
 Fiber Optic Switch Market | 2026-2036
Fiber Optic Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Switch Market Foresight
ISO 9001 certification for optical component manufacturing is bifurcating the vendor landscape into qualified suppliers and second-tier assemblers. Huawei Technologies leverages captive semiconductor fabrication to sustain cost advantages across Asia-Pacific deployments. Cisco Systems anchors enterprise channel relationships through embedded security modules in its fiber switch portfolio. Nokia Corporation differentiates via Bell Labs heritage in submarine cable switching systems.
A fiber optic switch routes optical signals between multiple pathways without electro-optical conversion, typically operating at wavelengths from 1260 nm to 1625 nm with insertion loss below 1 dB for single-mode configurations. Solid-state and MEMS technologies command premium positioning due to nanosecond switching speeds and minimal mechanical wear. Telecommunication networks remain the mature revenue base while data center applications represent the fastest-expanding segment, driven by hyperscale buildouts requiring port densities exceeding 400 Gbps per lane. Cloud data facilities and internet service providers collectively concentrate procurement volume, creating margin pools around software-defined orchestration layers.
REACH restrictions on hazardous substances in electronic components and the EU AI Act's infrastructure transparency mandates shape product design cycles for European deployments. FCC Part 15 emissions compliance and NHTSA-connected vehicle standards influence switch specifications for US telecommunications and automotive-integrated networks. Stakeholders must monitor how emerging GB standards from China's MIIT and evolving CE marking requirements under the EU Green Deal reshape qualification timelines and regional competitive access.
Market Dynamics
Hyperscale data center buildouts are compressing procurement cycles and forcing vendors to absorb software-defined orchestration capabilities that previously resided in separate network management layers. This structural pull toward integrated optical-electrical control planes is redrawing competitive boundaries between component suppliers and system integrators.
Growth Catalysts
- CSRD disclosure mandates:European data center operators must document network infrastructure energy efficiency, creating procurement preference for switches with embedded telemetry and power monitoring.
- Cloud facility densification:Hyperscalers in Frankfurt Rhine-Main and surrounding industrial zones are specifying 800 Gbps-ready backplanes, pulling demand for solid-state switching technologies with nanosecond latency.
- MIIT GB standards evolution:China's updated national standards for optical communication equipment are accelerating domestic qualification timelines and creating parallel certification tracks for multinational vendors.
Market Restraints
- Indium phosphide supply concentration:Foundry capacity for photonic integrated circuits concentrates among a handful of Asian contract manufacturers, exposing lead time volatility.
- REACH substance restrictions:ECHA limitations on cadmium and lead in electronic components force redesign cycles that extend product qualification by 8-14 months for European deployments.
- Silicon photonics substitution threat:CMOS-compatible optical engines are capturing lower-speed interconnect segments below 100 Gbps, compressing addressable market for discrete fiber switches.
Strategic Opportunities
- Submarine cable system refresh:Bell Labs heritage in wet-plant switching creates white space for vendors with proven deep-water reliability to capture transatlantic and transpacific upgrade cycles.
- Automotive-integrated fiber networks:NHTSA-connected vehicle standards are mandating deterministic latency for sensor fusion backbones, opening specification battles in Detroit and Stuttgart manufacturing clusters.
- Software-defined optical layer convergence:Integration of ROADM functionality with packet-optical switching enables new service models for regional internet exchange points.
Industry Challenges
- ISO 9001 certification bottlenecks:Optical component manufacturing audits require specialized assessor availability that stretches qualification timelines for second-tier assemblers.
- Legacy SONET/SDH integration friction:Incumbent telecom operators in mature markets maintain substantial embedded bases that resist migration to packet-optical control planes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Switch Market |
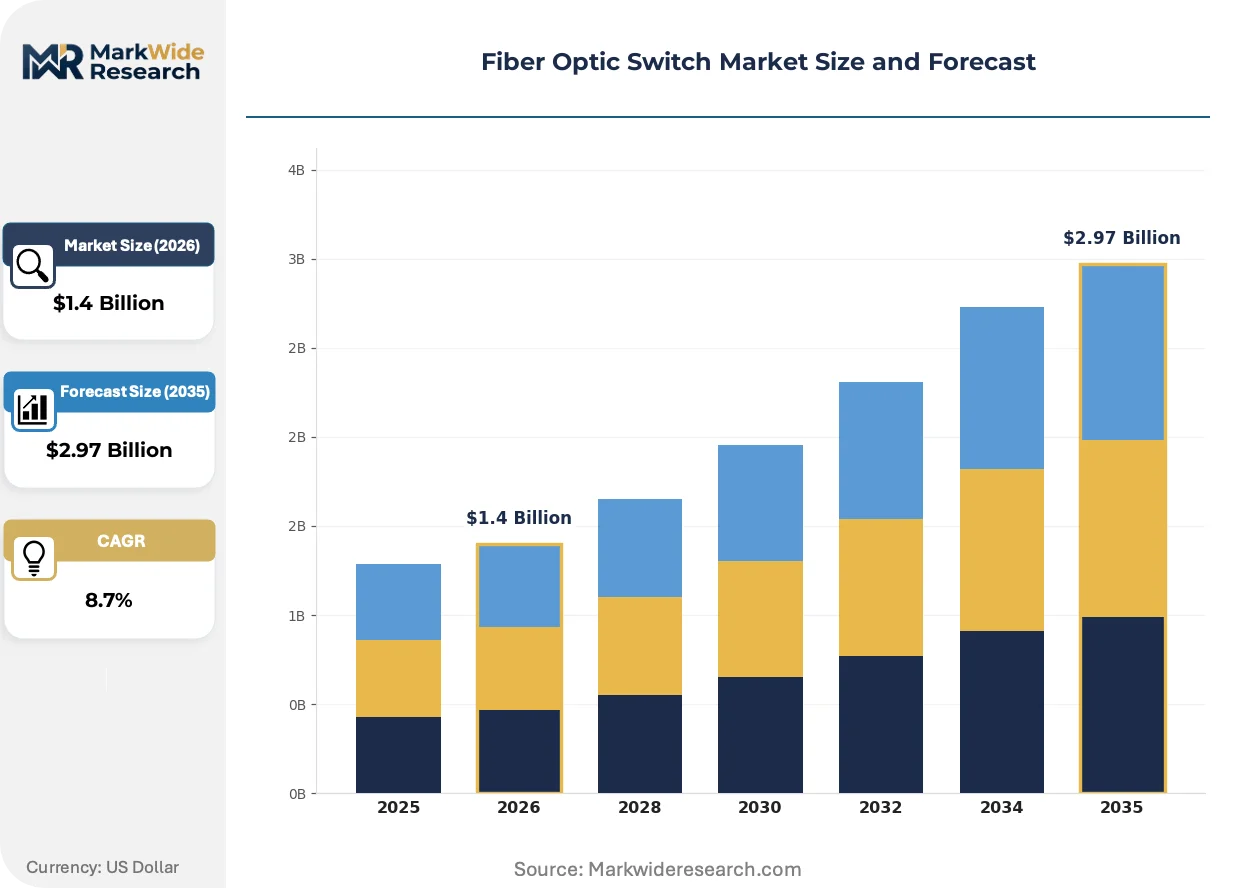
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Solid State, MEMS, Liquid Crystal, Thermo-Optic Technology: Planar Lightwave Circuit, Micro-Electro-Mechanical Systems, Electro-Optic, Thermo-Optic Switching, Liquid Crystal Switching Application: Telecommunication Networks, Data Centers, Sensor Networks, Military Communications, Test & Measurement End User: Internet Service Providers, Cloud Data Facilities, Research Laboratories, Defense Agencies, Broadcast Companies |
| Companies Covered | Huawei Technologies, Nokia Corporation, Cisco Systems, Lenovo ThinkSystem, Extreme Networks, Arista Networks, H3C Technologies, Dell Technologies, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Switch Market Shifts & Advancements
Optical switching architectures are fragmenting into specialized layers optimized for either ultra-low latency or massive port density, with software abstraction attempting to unify heterogeneous physical implementations. This technical bifurcation is forcing vendors to choose depth over breadth in their engineering investments.
Co-packaged optics is decomposing traditional pluggable transceiver architectures by embedding photonic engines directly adjacent to switch ASICs. Cloud data facilities in Ashburn, Virginia and Singapore are piloting 51.2 Tbps switching fabrics with co-packaged designs that eliminate front-panel optical connectors. This integration is decomposing the historical boundary between switch and transceiver procurement, compressing vendor margins on standalone optical components.
EU AI Act infrastructure transparency requirements are mandating detailed documentation of network latency and throughput for high-risk AI systems deployed in European data centers. Operators must demonstrate deterministic optical path performance, creating specification pressure for switches with guaranteed jitter profiles. German automotive and pharmaceutical clusters are driving early compliance investment ahead of enforcement timelines.
Hyperscale buyers are consolidating procurement through direct vendor relationships that bypass traditional distribution channels for high-volume optical interconnect. Internet exchange operators in Amsterdam, London, and Tokyo are forming buying consortia to negotiate firmware customization and extended warranty terms. This concentration is most visible among cloud data facilities requiring port densities exceeding 400 Gbps per lane, where volume commitments secure preferential engineering support.
Fiber Optic Switch Market Segmentation
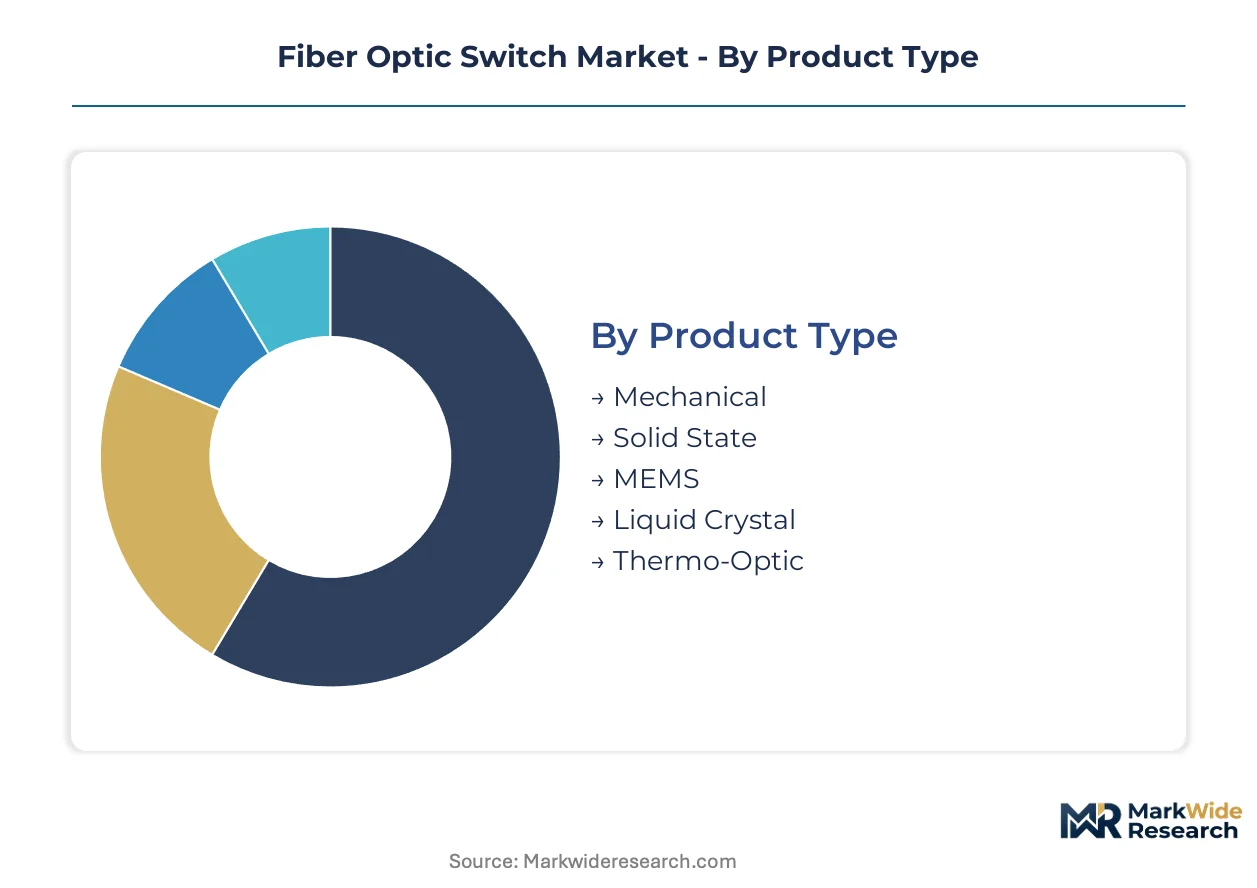
Segmentation in the fiber optic switch market reveals distinct procurement patterns across technology tiers and end-use verticals. Buyers in Frankfurt Rhine-Main data centers prioritize solid-state architectures for latency-sensitive workloads, while submarine cable operators demand mechanical reliability for wet-plant environments.
Product Type:
Domestic production concentrates on mechanical switches for legacy telecom refresh cycles, whereas solid-state and MEMS variants flow through export channels serving hyperscale cloud buildouts.
- Solid State:Nanosecond switching speeds eliminate mechanical wear in high-cycle environments. Demand clusters in Germany's Frankfurt Rhine-Main cloud corridor where hyperscalers specify 800 Gbps-ready backplanes with embedded telemetry for CSRD compliance.
- MEMS:Micro-mirror arrays achieve port counts exceeding 1000x1000 with insertion loss below 1 dB. Procurement from Ashburn, Virginia and Singapore facilities pilots co-packaged 51.2 Tbps switching fabrics that eliminate front-panel optical connectors.
- Mechanical:Proven deep-water reliability sustains submarine cable upgrade cycles across transatlantic routes.
- Liquid Crystal:Polarization-independent switching suits laboratory environments with variable input conditions.
- Thermo-Optic:Silicon-based waveguide heating enables cost-effective low-port-count configurations for test equipment.
Solid state commands the established base. The steepest expansion runs through MEMS.
Technology:
Cost tiers separate premium photonic integration from commodity thermo-optic alternatives, with planar lightwave circuits anchoring mid-range enterprise deployments.
- Planar Lightwave Circuit:Lithographically defined waveguides on silicon substrates enable wafer-scale manufacturing with tight process control. Volume procurement from internet exchange consortia in Amsterdam, London, and Tokyo secures firmware customization for software-defined orchestration layers.
- Micro-Electro-Mechanical Systems:Electrostatically actuated micro-mirrors achieve nanosecond repositioning with minimal power dissipation. Deployment in NHTSA-connected vehicle sensor fusion backbones mandates deterministic latency specifications from Detroit and Stuttgart manufacturing clusters.
- Electro-Optic:Lithium niobate crystals enable sub-nanosecond switching for quantum communication testbeds.
- Thermo-Optic Switching:Resistive heating of silica waveguides trades speed for simplicity in academic research settings.
- Liquid Crystal Switching:Electric-field reorientation of nematic phases supports polarization-diverse routing in coherent detection systems.
Planar lightwave circuit technology anchors the revenue base. Electro-optic architectures are climbing the fastest in emerging quantum networking applications.
Application:
Customer type stratification separates volume-driven cloud procurement from specification-heavy defense contracts, with data center applications commanding premium pricing for telemetry integration.
- Data Centers:Hyperscale buildouts require port densities exceeding 400 Gbps per lane with guaranteed jitter profiles for EU AI Act compliance. German automotive and pharmaceutical clusters drive early investment in deterministic optical path documentation ahead of enforcement timelines.
- Telecommunication Networks:Legacy SONET/SDH embedded bases in mature markets resist migration to packet-optical control planes. Incumbent operators maintain substantial mechanical switch inventories for circuit-protected core routes.
- Sensor Networks:Distributed acoustic sensing in oilfield infrastructure demands ruggedized hermetic packaging.
- Military Communications:Tempest shielding and anti-tamper coatings extend qualification cycles for defense agencies.
- Test & Measurement:Modular chassis configurations support rapid reconfiguration in R&D laboratories.
Telecommunication networks retain the installed base. Data center applications show the steepest volume trajectory.
End User:
Supply concentration among indium phosphide foundries shapes availability for internet service providers, while cloud data facilities leverage direct vendor relationships to bypass distribution channels.
- Cloud Data Facilities:Direct procurement consortia negotiate extended warranty terms and firmware customization unavailable through channel partners. Volume commitments from Ashburn, Singapore, and Frankfurt Rhine-Main clusters secure preferential engineering support for 800 Gbps migration roadmaps.
- Internet Service Providers:Regional network upgrades balance capital efficiency against latency commitments for enterprise SLA tiers. Procurement cycles compress as software-defined orchestration absorbs traditional network management layers.
- Research Laboratories:Non-recurring engineering subsidies support experimental switching architectures.
- Defense Agencies:ITAR-controlled shipments restrict vendor pools for classified deployments.
- Broadcast Companies:Synchronous routing requirements align with telecom infrastructure refresh timelines.
Internet service providers represent the broadest installed base. Cloud data facilities are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators and submarine cable consortiums concentrate procurement in five national markets. Each geography presents distinct regulatory hurdles and cluster-specific demand patterns.
United States
Hyperscale data center construction in Ashburn, Virginia and the Pacific Northwest drives demand for 800 Gbps-ready switching fabrics. FCC Part 15 emissions compliance shapes product qualification timelines for domestic deployments. Cloud facilities in Northern Virginia negotiate direct vendor relationships that bypass traditional distribution channels.
Germany
Frankfurt Rhine-Main data centers specify solid-state switches with embedded telemetry for CSRD disclosure mandates. ECHA REACH restrictions on hazardous substances extend European qualification cycles by 8-14 months. Automotive and pharmaceutical clusters in Stuttgart and Ludwigshafen invest early in EU AI Act compliance for deterministic optical path documentation.
China
MIIT GB standards evolution accelerates domestic qualification timelines for optical communication equipment. Updated national standards create parallel certification tracks that multinational vendors must navigate. Yangtze River Delta manufacturing hubs absorb volume production of planar lightwave circuit technologies.
Japan
Internet exchange operators in Tokyo form buying consortia to negotiate firmware customization and extended warranty terms. METI industrial policy supports domestic photonic integrated circuit foundry capacity. Kanto region hyperscalers pilot co-packaged 51.2 Tbps switching fabrics with embedded photonic engines.
Singapore
Submarine cable landing stations drive wet-plant switching procurement for transpacific upgrade cycles. Maritime infrastructure investments position the city-state as a relay point for transatlantic and Asia-Pacific cable systems. Data center operators specify MEMS-based architectures for port densities exceeding 1000x1000 configurations.
Fiber Optic Switch Market Competitive Landscape
Player mix skews toward integrated networking conglomerates with captive optical component supply. Consolidation around five to seven vertically structured vendors leaves limited room for pure-play specialists. Two strategic archetypes dominate: semiconductor-integrated platform owners and submarine-cable heritage specialists. Competitive moves center on co-packaged optics integration and direct hyperscale procurement relationships that displace channel-dependent rivals.
Among Asia-Pacific platform owners, Huawei Technologies and H3C Technologies exemplify the semiconductor-integrated archetype with captive fabrication advantages. Nokia Corporation occupies a position reflecting Bell Labs heritage in wet-plant reliability. Cisco Systems anchors the enterprise-centric tier through embedded security module differentiation. These three vendors represent distinct competitive vectors: cost-optimized volume production, submarine system credibility, and enterprise channel control.
| Leading Market Players |
|---|
| Huawei Technologies |
| Nokia Corporation |
| Cisco Systems |
| Lenovo ThinkSystem |
| Extreme Networks |
| Arista Networks |
| H3C Technologies |
| Dell Technologies |
| Juniper Networks |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with indium phosphide foundries lock in wafer supply and provide cost visibility for photonic integrated circuit production, insulating qualified vendors from spot-market volatility in Asian contract manufacturing. Hyperscale buyers in Ashburn and Frankfurt Rhine-Main leverage direct procurement relationships to compress margin pools around software-defined orchestration layers.
Pricing Analysis
Cost-plus contracts indexed to rare earth metal prices govern indium phosphide substrate procurement, with pass-through mechanisms for foundry utilization rates. Three-tier pricing structure across ISO 9001-certified premium, qualified standard, and uncertified economy levels separates vendor tiers. Pricing pressure stems from silicon photonics substitution in sub-100 Gbps interconnect segments. Cloud data facilities show lowest price sensitivity due to latency requirements, while regional internet service providers negotiate aggressively on per-port economics.
Supply Chain Analysis
Strategic stockpiling of indium phosphide substrates and specialized optical coatings buffers against foundry allocation volatility, contrasting with just-in-time preferences for planar lightwave circuit components. Supply concentrates in Taiwan, South Korea, and Japan for photonic integrated circuit fabrication, with China dominating planar lightwave circuit wafer processing. The chain draws from indium phosphide substrates, micro-mirror arrays, and hermetic packaging materials. Single-source vulnerability at indium phosphide foundries exposes lead time volatility. Distribution runs through direct hyperscale procurement channels that displace traditional optical component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
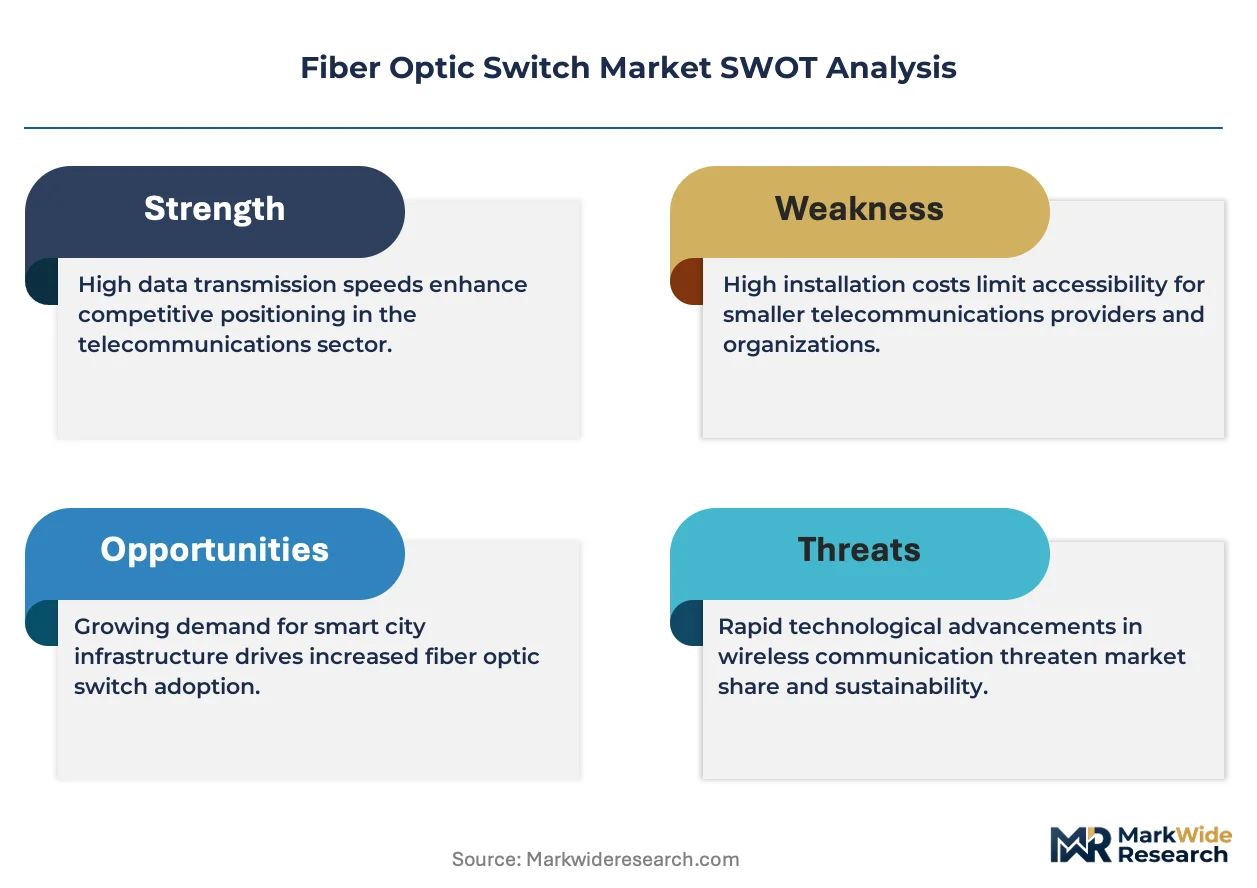
This market requires substitution defense against silicon photonics encroachment in lower-speed interconnect tiers, where CMOS-compatible optical engines threaten discrete fiber switch relevance.
For Market Incumbents: Shield core margin pools by deepening captive semiconductor fabrication capabilities in indium phosphide and silicon photonics parallel tracks. Accelerate ISO 9001 certification pipelines to bifurcate qualified supplier status from second-tier assemblers. Prioritize co-packaged optics integration to capture switch-ASIC boundary value before hyperscale buyers consolidate procurement further. For New Entrants and Emerging Players: EU AI Act compliance fast-tracks create specification white space for vendors offering deterministic latency documentation and embedded telemetry modules. Target German automotive and pharmaceutical clusters in Stuttgart and Ludwigshafen ahead of enforcement timelines. Enter through submarine cable wet-plant reliability credentials where Bell Labs heritage has not locked incumbency. For Investors and Strategic Acquirers: Photonic integrated circuit design houses with foundry relationships and software-defined orchestration IP represent the most defensible acquisition archetype. Long-term viability hinges on co-packaged optics transition completion and hyperscale direct relationship penetration. Watch for indium phosphide foundry utilization rates as inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Integration | Eliminates front-panel connectors and captures switch-ASIC boundary value in 51.2 Tbps fabrics. |
| ISO 9001 Certification Investment | Bifurcates vendor landscape into qualified suppliers and second-tier assemblers for European deployments. |
| Direct Hyperscale Procurement Relationship | Bypasses distribution channels and secures preferential engineering support for 800 Gbps roadmaps. |
| Submarine Cable Wet-Plant Qualification | Captures transatlantic and transpacific upgrade cycles through deep-water reliability credentials. |
| EU AI Act Compliance Module Development | Enables deterministic optical path documentation for high-risk AI systems in Frankfurt Rhine-Main clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with optical component procurement directors, hyperscale network architects, submarine cable system engineers, and regulatory compliance officers; and secondary validation through FCC Part 15 filings, ECHA REACH substance restriction updates, MIIT GB standard evolution notices, and hyperscaler capital expenditure disclosures. Bottom-up vendor shipment aggregation triangulated against top-down hyperscale facility buildout tracking.
Across the projection horizon, the analytical framework modeled technology type, application vertical, end-user category, and regional regulatory cluster segmentation. CAGRs derived from facility-level port density requirements and submarine cable system refresh cycles. Forecast inputs incorporated indium phosphide foundry capacity utilization and silicon photonics substitution velocity assumptions.
Underlying assumptions cover indium phosphide substrate supply stability and hyperscale direct procurement consolidation, with deviation risk concentrated in ECHA substance restriction expansion and MIIT domestic qualification acceleration. Revision becomes warranted when silicon photonics penetration in sub-100 Gbps segments crosses thresholds that compress discrete switch addressable market.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Smart Glass Market
Optics
Picosecond Lasers Market
Optics
US Photonics Market
Optics
Optical Imaging Market
Optics
Optical Gratings Market
Optics
Global Nanophotonics Market
Optics
Optical Lens for Mobile Phone Market
Optics
Fiber Optic Receiver Market
Optics
Fiber Optics Market
Optics
Polymeric Optical Fiber Market
Optics
APAC Smart Glass Market
Optics
Smart Vision Systems Market
Optics
Fiber-Optic Couplers Market
Optics
Fiber Optic Preform Market
Optics
Beam Expanders Market
Optics
Stroboscope Market