
 APAC Chemical Sensors Market | 2026-2036
APAC Chemical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Chemical Sensors Market Outlook
Environmental monitoring is decoupling from its historical status as a secondary application and is now commanding equal procurement priority alongside industrial manufacturing in APAC capital budgets. Honeywell International Inc. leverages its distributed sensing architecture to anchor large-scale refinery deployments across South Korea and Thailand. Siemens AG competes through integrated process-control platforms that embed chemical sensing into broader automation workflows. Bosch Sensortec GmbH specializes in miniaturized gas sensor modules for consumer and mobility applications, extending its reach beyond traditional industrial buyers.
Chemical sensors are transducer-based devices that detect and quantify specific analyte concentrations through electrochemical, optical, or thermal mechanisms, typically achieving detection thresholds in parts-per-million or parts-per-billion ranges depending on the sensing element and signal-conditioning architecture. Their primary commercial purpose is to enable real-time safety assurance, regulatory compliance verification, and process efficiency optimization across emission-intensive and quality-critical operations. Electrochemical sensors occupy the largest installed base due to mature manufacturing economics and broad gas-species coverage, while optical fiber technology represents the fastest-expanding segment as semiconductor fabs and pharmaceutical cleanrooms demand immunity to electromagnetic interference and drift-free stability. Gas sensors command premium pricing in hazardous-environment certifications, whereas thick film sensors compete on cost in high-volume water quality testing instrumentation.
China's MEE enforces increasingly stringent emission monitoring standards for heavy industry, directly expanding the addressable market for certified sensor systems. Japan's METI coordinates national sensor technology roadmaps that channel R&D subsidies toward low-power, high-selectivity devices for hydrogen economy infrastructure. South Korea's MFDS and KOSHA frameworks govern workplace chemical exposure limits, creating recurring replacement demand for calibrated personal and area monitors. Stakeholders must weigh certification reciprocity across these regulatory regimes when configuring regional product portfolios and service networks.
Market Dynamics
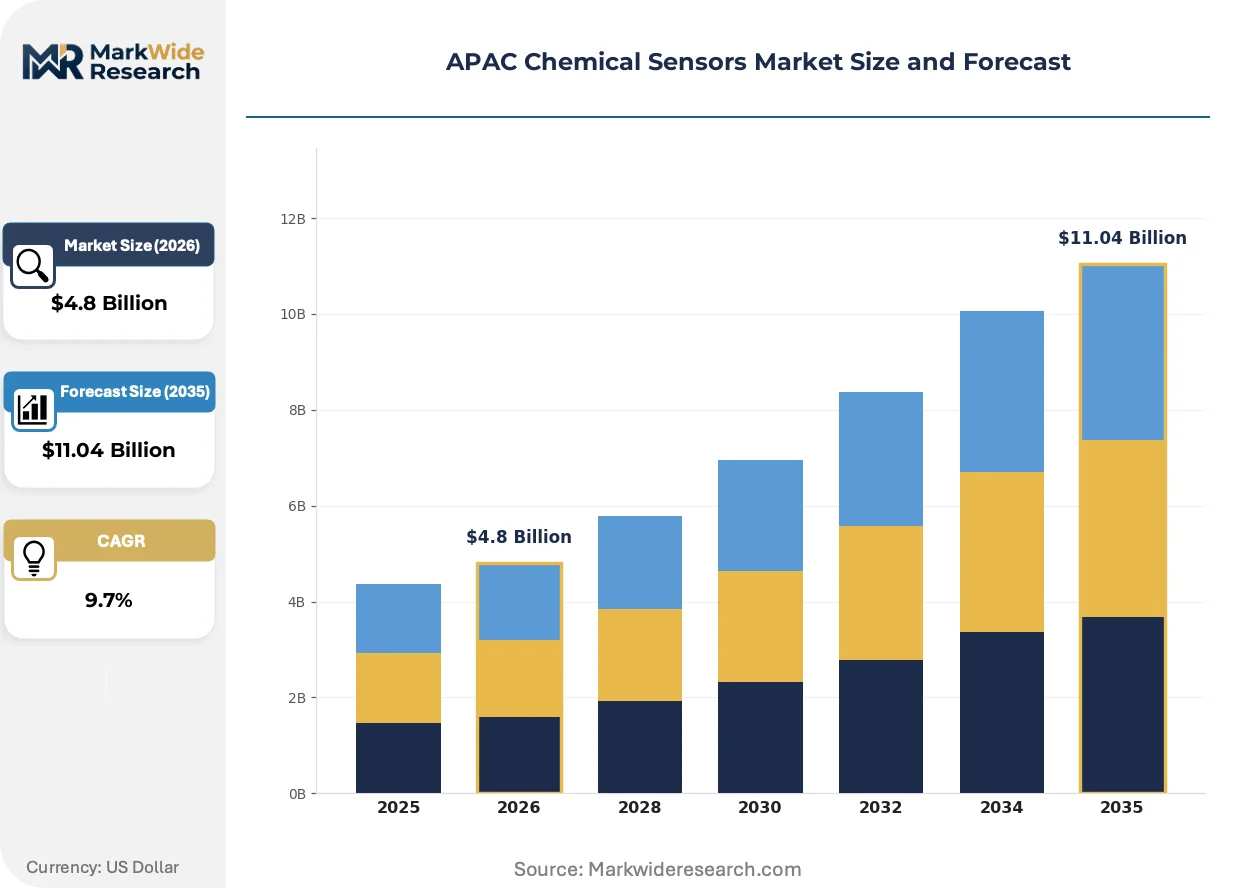
China's dual carbon mandates under MEE are compressing deployment timelines for emissions monitoring systems, forcing industrial buyers to accelerate sensor procurement cycles and integrate real-time measurement into process control architectures.
Growth Catalysts
- MEE emission standards:China's tightening monitoring requirements for heavy industry expand certified sensor system demand across petrochemical and steel complexes.
- Semiconductor cleanroom protocols:Optical fiber sensors gain traction in pharmaceutical and chip manufacturing facilities requiring electromagnetic immunity.
- Hydrogen infrastructure buildout:Japan's METI technology roadmaps channel subsidies toward high-selectivity, low-power devices for fuel cell and storage applications.
Market Restraints
- Precious metal input volatility:Electrochemical sensor manufacturing depends on platinum and palladium electrodes, exposing margins to commodity price swings.
- Single-source optical component supply:Specialized infrared emitters and photodetectors concentrate among Japanese and German component suppliers.
- Cross-border certification friction:Divergent hazardous environment standards between China's GB system and South Korea's KOSHA create product configuration complexity.
Strategic Opportunities
- Vietnam industrial corridor expansion:Electronics assembly and textile manufacturing clusters in Bac Ninh and Hai Phong present undeveloped demand for workplace chemical monitors.
- India water quality instrumentation:Municipal and industrial wastewater treatment plants drive thick film sensor volume as BIS standards tighten.
- AI-enabled predictive maintenance:Machine learning integration with distributed sensor networks creates service revenue streams beyond hardware sales.
Industry Challenges
- Calibration technician scarcity:Certified personnel for electrochemical sensor field servicing remain concentrated in Shanghai, Tokyo, and Seoul metro areas.
- Legacy SCADA integration complexity:Brownfield manufacturing facilities require protocol translation layers to connect modern optical arrays with established control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Chemical Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical Sensors, Optical Sensors, Gas Sensors, Thick Film Sensors Technology: Amperometric, Potentiometric, Conductometric, Optical Fiber End User: Environmental Monitoring, Industrial Manufacturing, Healthcare, Food & Beverage Application: Water Quality Testing, Air Quality Monitoring, Process Control, Safety Testing |
| Companies Covered | Honeywell International Inc., Siemens AG, Emerson Electric Co., Bosch Sensortec GmbH, Denso Corporation, ABB Ltd., Figaro Engineering Inc., Yokogawa Electric Corporation, Sensirion AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Chemical Sensors Market Strategic Shifts
Sensor architectures are converging with edge computing and wireless telemetry, collapsing the traditional separation between measurement hardware and data infrastructure while enabling predictive rather than reactive industrial safety systems.
Optical fiber sensing technology is integrating photonic crystal and interferometric detection methods to achieve parts-per-billion resolution for toxic gas identification. Semiconductor fabs in South Korea's Gyeonggi Province and pharmaceutical cleanrooms across China's Jiangsu Province are adopting these platforms at accelerated procurement cycles. This capability compression is integrating chemical measurement directly into wafer-handling robotics and isolator systems, eliminating discrete sampling stations.
METI's national sensor roadmap in Japan is mandating hydrogen leak detection specifications for fueling station networks and storage terminals. The framework requires sub-1000 ppm response thresholds with zero false-positive tolerance under vibration and temperature cycling. Equipment suppliers serving Tokyo Bay industrial zones and Osaka-Kobe chemical complexes are reconfiguring product lines to meet these certification requirements ahead of enforcement deadlines.
Refinery operators in Thailand and Singapore are unbundling sensor maintenance from original equipment supply contracts, creating independent service markets for calibration and replacement cycle management. Third-party technical service providers in Rayong and Jurong Island are capturing recurring revenue streams previously retained by hardware manufacturers. This disaggregation is most visible in continuous emissions monitoring systems where uptime guarantees now determine vendor selection more than initial capital cost.
APAC Chemical Sensors Market Segmentation
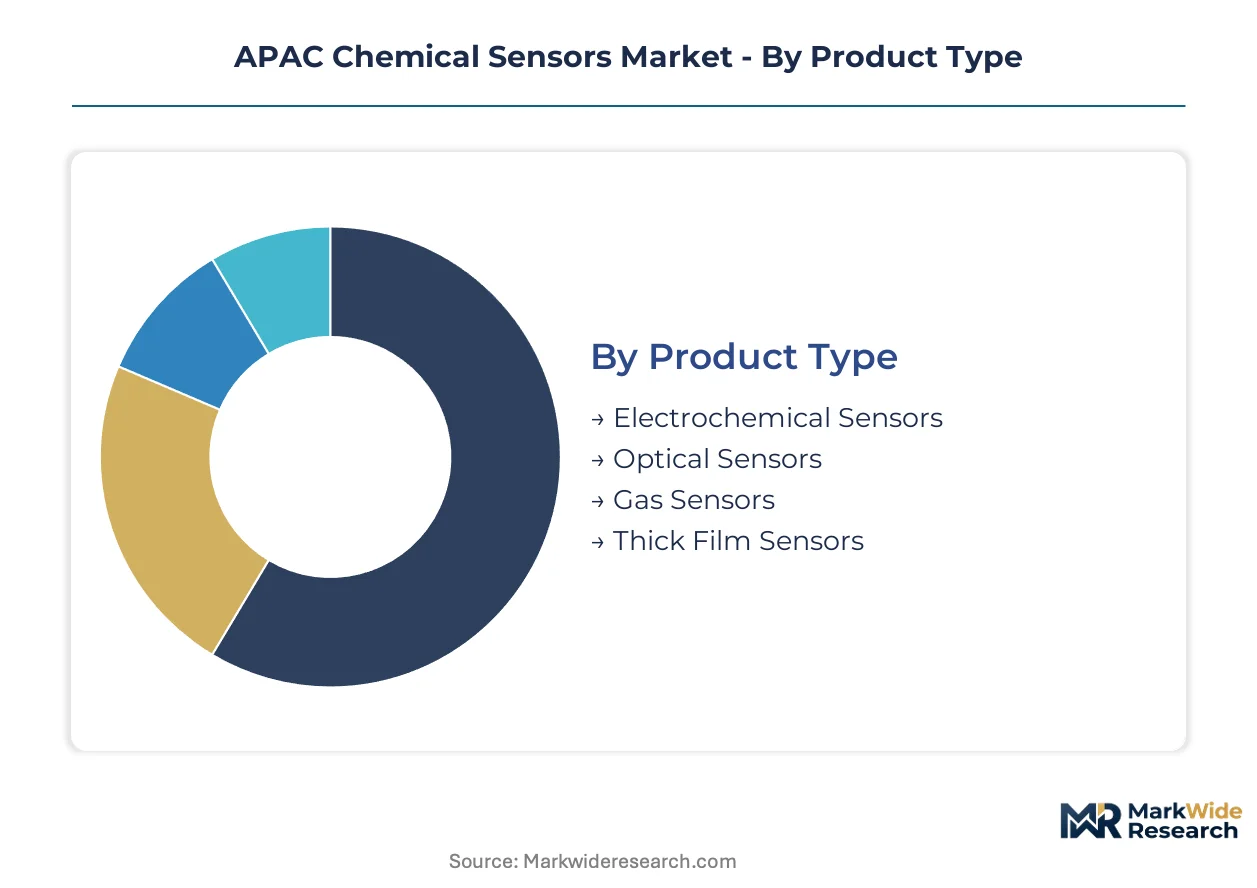
Segmentation in the APAC Chemical Sensors Market reveals distinct procurement patterns across technology maturity and regulatory exposure. Buyers in China's Yangtze River Delta industrial corridor and Japan's Keihin industrial zone configure sensor portfolios differently based on emission compliance deadlines versus process optimization priorities.
Product Type:
Procurement decisions pivot on detection threshold requirements versus total cost of ownership across the sensor lifecycle.
- Electrochemical Sensors:These devices employ platinum or palladium electrodes immersed in electrolyte solutions to generate current proportional to target gas concentration. Demand concentrates in China's petrochemical complexes along the Bohai Rim, where MEE mandates require continuous stack monitoring with parts-per-million resolution and proven field reliability under high-humidity conditions.
- Optical Sensors:Photonic detection systems leverage absorbance, fluorescence, or interferometric principles to achieve drift-free measurement without electrode degradation. Semiconductor fabs in South Korea's Gyeonggi Province and pharmaceutical cleanrooms in Japan's Kansai region specify these for electromagnetic immunity and sub-parts-per-billion detection of process contaminants.
- Gas Sensors:Solid-state and catalytic platforms target combustible and toxic gas detection in hazardous classified environments. Thailand's Rayong refinery operators and Singapore's Jurong Island chemical terminals specify these for KOSHA and workplace safety certifications.
- Thick Film Sensors:Screen-printed metal oxide layers on ceramic substrates enable cost-effective water quality and basic gas detection. India's municipal wastewater treatment plants under tightening BIS standards drive volume procurement for pH and dissolved oxygen monitoring.
Volume sits with electrochemical platforms; growth tilts toward optical fiber arrays.
Technology:
Signal transduction method determines integration complexity with existing distributed control architectures.
- Amperometric:Current measurement at fixed applied potential dominates dissolved oxygen and chlorine residual detection in water treatment. China's coastal desalination facilities and Japan's semiconductor ultrapure water systems specify these for rapid response kinetics.
- Potentiometric:Ion-selective electrode potential measurement enables pH and specific ion detection without reagent consumption. Vietnam's emerging electronics manufacturing clusters in Bac Ninh are adopting these for process bath control as FDI expands.
- Conductometric:Resistance change measurement targets humidity and reducing gas detection in HVAC and indoor air quality applications. South Korea's commercial building automation integrators embed these for MFDS workplace environment compliance.
- Optical Fiber:Evanescent wave and interferometric configurations deliver immunity to electrical noise and corrosion. METI's hydrogen infrastructure specifications are accelerating deployment at Tokyo Bay fueling stations and Osaka-Kobe storage terminals.
Amperometric systems anchor current installed base; optical fiber configurations are climbing the fastest.
End User:
Budget authority and replacement cycle timing vary sharply between regulatory-driven and efficiency-driven procurement.
- Environmental Monitoring:Continuous emissions monitoring systems and ambient air networks require certified calibration protocols and data telemetry integration. China's MEE enforcement in the Yangtze River Delta is compressing deployment timelines for heavy industry.
- Industrial Manufacturing:Process control and safety systems prioritize uptime guarantees and predictive maintenance integration. Japan's METI efficiency mandates are embedding sensors into broader automation roadmaps for steel and chemical complexes.
- Healthcare:Anesthesia gas monitoring and ventilator integration demand medical-grade certifications and biocompatibility. South Korea's MFDS governs clinical deployment standards for hospital systems in Seoul metro areas.
- Food & Beverage:Cold chain monitoring and fermentation process control require hygienic design and rapid sanitization compatibility. Australia's wine regions and Southeast Asian dairy processing plants specify these for export certification compliance.
Industrial manufacturing commands largest capital allocation; environmental monitoring is gaining share fastest.
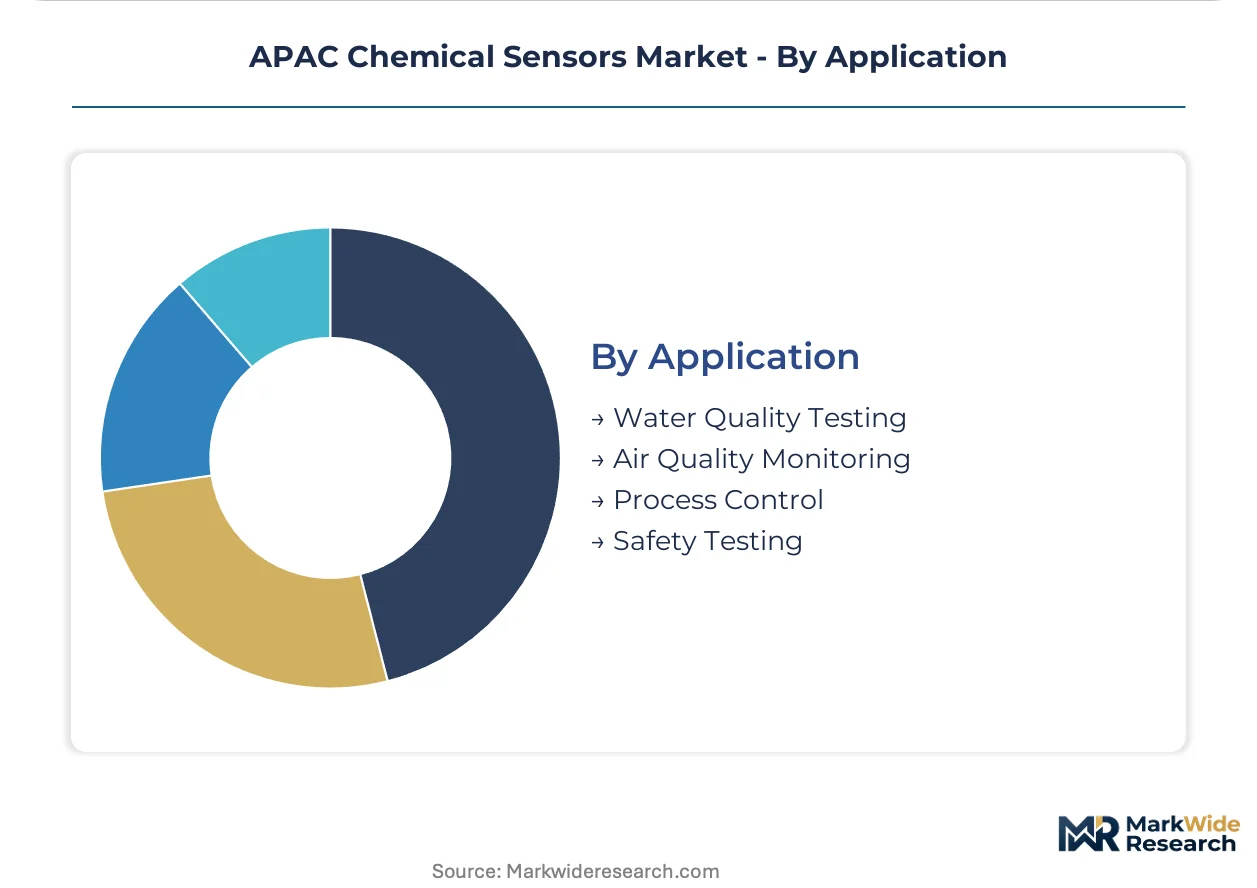
Application:
Use case specificity dictates sensor packaging, sampling methodology, and data interface requirements.
- Water Quality Testing:Multi-parameter probe assemblies target pH, dissolved oxygen, conductivity, and turbidity in municipal and industrial treatment. India's Ganges basin cleanup initiatives and Southeast Asian smart city programs are expanding procurement.
- Air Quality Monitoring:Ambient network stations and fence-line monitoring arrays measure criteria pollutants and hazardous air contaminants. China's urban air quality disclosure requirements are standardizing sensor specifications across provincial environmental bureaus.
- Process Control:In-line analyzers enable real-time chemical concentration feedback for reactor optimization and product quality assurance. Japan's chemical and pharmaceutical manufacturers specify these for METI productivity enhancement programs.
- Safety Testing:Personal monitors and area detectors protect workers from acute chemical exposure in confined spaces and leak scenarios. South Korea's KOSHA enforcement in shipbuilding and petrochemical maintenance drives replacement demand.
Process control captures premium pricing; air quality monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta economic zone concentrates the heaviest procurement activity, with bonded logistics parks and free-trade zones accelerating sensor imports for semiconductor and petrochemical complexes across Shanghai, Jiangsu, and Zhejiang provinces.
China
Petrochemical clusters along the Bohai Rim and Yangtze River Delta drive bulk orders for electrochemical sensor arrays. MEE emission monitoring mandates for heavy industry compress deployment timelines. Tianjin and Ningbo port zones host calibration service hubs serving steel and chemical complexes.
Japan
Hydrogen fueling infrastructure buildout in Tokyo Bay and Osaka-Kobe corridors demands high-selectivity leak detection systems. METI technology roadmaps channel subsidies toward low-power sensor platforms. Keihin industrial zone chemical manufacturers embed optical fiber arrays into process control architectures.
South Korea
Semiconductor fabs in Gyeonggi Province specify electromagnetic-immune optical sensors for cleanroom contamination monitoring. MFDS workplace exposure limits and KOSHA safety certifications drive replacement cycles for personal monitors. Busan-Ulsan petrochemical belt operators unbundle maintenance contracts from hardware supply.
India
Municipal wastewater treatment plants under tightening BIS standards procure thick film sensors for pH and dissolved oxygen monitoring. Ganges basin cleanup initiatives expand multi-parameter probe assemblies. Gujarat and Maharashtra industrial corridors attract sensor distributors serving textile and pharmaceutical manufacturers.
Vietnam
Electronics assembly clusters in Bac Ninh and Hai Phong present undeveloped demand for workplace chemical monitors as FDI expands. Textile manufacturing in Dong Nai Province requires emission compliance systems for export certification. Ho Chi Minh City logistics hubs emerge as regional distribution points for sensor calibration services.
APAC Chemical Sensors Market Competitive Environment
Top-tier vendors anchor refinery and semiconductor fab deployments, while mid-tier specialists compete on cost in water quality and air monitoring instrumentation. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with integrated automation platforms, pure-play sensor specialists with miniaturized module expertise, and regional system integrators with calibration service networks. Competitive moves concentrate on strategic partnerships for hydrogen infrastructure certification and geographic expansion into Vietnam and India industrial corridors.
Within the diversified industrial tier, Honeywell International Inc., Siemens AG, and Bosch Sensortec GmbH represent distinct positioning vectors. Honeywell exemplifies the large-scale refinery deployment archetype through its distributed sensing architecture. Siemens occupies a position emphasizing process-control integration. Bosch Sensortec sits within the miniaturization-specialist segment, extending reach beyond traditional industrial buyers into consumer and mobility applications. These three anchors illustrate how scale, integration depth, and form-factor specialization define competitive differentiation in the APAC procurement landscape.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Emerson Electric Co. |
| Bosch Sensortec GmbH |
| Denso Corporation |
| ABB Ltd. |
| Figaro Engineering Inc. |
| Yokogawa Electric Corporation |
| Sensirion AG |
| Others |
Value Chain & Pricing Dynamics
Optical fiber sensor manufacturing migration from discrete benchtop assemblies to wafer-scale photonic integration is collapsing unit economics while concentrating production capability among Japanese and German component houses. This dual compression simultaneously erodes electrochemical sensor margins through performance-tier substitution and locks in premium pricing for qualified optical arrays serving semiconductor fabs.
Pricing Analysis
Lead-time premiums command 15-25% markups for certified optical arrays delivered under 8-week windows, while spot inventory of electrochemical platforms trades at discounts to contract offtake. Three-tier pricing structure across premium, standard, and economy levels separates MEE-certified emissions systems from workplace safety monitors and basic water quality probes. Cost compression in thick film sensors is intensifying because Indian municipal procurement favors lowest-bid compliance over performance specifications. Price-sensitive buyers in Vietnam's emerging electronics clusters prioritize economy-tier personal monitors, whereas South Korean semiconductor fabs absorb premium optical fiber pricing for electromagnetic immunity guarantees.
Supply Chain Analysis
Platinum and palladium electrode supply rests on South African mining output and Russian refined metal flows, exposing electrochemical sensor margins to commodity volatility. Specialized infrared emitters and photodetectors draw from Japanese and German component suppliers, creating single-source vulnerability for optical array manufacturers. Distribution runs through Shanghai, Tokyo, and Singapore calibration hubs that anchor regional service networks for refinery and fab deployments. Tariff exposure concentrates at Chinese port zones where bonded logistics parks buffer import duties for Yangtze River Delta industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC chemical sensors market sits in a technology-transition phase where optical fiber platforms displace electrochemical arrays in premium applications. This substitution dynamic reconfigures competitive positioning and investment priorities across the value chain.
For Market Incumbents: Extend calibration service networks into Vietnam's Bac Ninh corridor and India's Gujarat industrial belt before local system integrators capture maintenance revenue. Deepen backward integration into platinum electrode supply through offtake agreements with South African refiners, insulating margins from spot market volatility. METI's hydrogen infrastructure specifications threaten electrochemical incumbents; accelerate optical fiber certification investments to defend position in Japan's fueling station deployments.
For New Entrants and Emerging Players: E-commerce channels serving small-to-mid water treatment operators in Southeast Asia offer low-friction entry without established distributor relationships. Target India's municipal wastewater segment where BIS compliance deadlines outpace incumbent service capacity. White-space exists in AI-enabled predictive maintenance subscriptions for distributed sensor networks, unbundling software revenue from hardware margins that incumbents protect.
For Investors and Strategic Acquirers: Re-rating potential sits with optical fiber specialists possessing METI hydrogen certification given Japan's infrastructure buildout timeline. Long-term viability favors platforms with demonstrated electromagnetic immunity and sub-parts-per-billion resolution. Acquisition targets should show calibration technician density in underserved corridors. Watch KOSHA enforcement intensity in South Korean shipbuilding as an inflection indicator for personal monitor replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Infrastructure Certification | METI specifications for Tokyo Bay fueling stations create qualified-supplier moats. |
| Calibration Service Network Expansion | Third-party technical providers in Rayong and Jurong Island capture recurring revenue streams. |
| Optical Fiber Manufacturing Scale-Up | Wafer-scale photonic integration reduces unit costs for Gyeonggi Province semiconductor fabs. |
| AI-Enabled Predictive Maintenance Platform | Machine learning integration with distributed networks creates service revenue beyond hardware. |
| Platinum Supply Security Agreement | Offtake contracts with South African refiners stabilize electrochemical sensor input costs. |
Study Parameters
Multi-period observation of MEE enforcement intensity, METI subsidy allocation patterns, and semiconductor fab capital expenditure cycles anchored the trend analysis, supplemented by interviews with plant managers at petrochemical complexes, procurement leads at downstream OEMs, calibration service technicians, and technical R&D directors. Secondary validation drew from customs and trade data, SEC 10-K filings of listed industrial conglomerates, MEE emission disclosure databases, and KOSHA workplace safety incident reports. Bottom-up sensor unit demand estimates triangulated against top-down industrial automation spending forecasts.
Segment-weighting across technology type, end-use industry, and regional regulatory cluster determined value allocation throughout the forecast period. Amperometric and optical fiber technology trajectories were modeled separately given their divergent substitution dynamics. CAGRs derived from elasticity-adjusted deployment schedules responsive to MEE mandate timelines and METI roadmap milestones. Hydrogen infrastructure buildout assumptions and semiconductor fab contamination control spending patterns served as industry-specific forecast inputs.
The model holds under stable platinum group metal supply and continued MEE enforcement intensity; deviation in trade flow disruptions or regulatory relaxation would shift electrochemical sensor demand trajectories. Forecasts reflect documented assumptions regarding technology substitution rates and certification reciprocity across GB, KOSHA, and METI frameworks. A small set of triggers warrants ongoing watch: palladium price spikes, optical component export restrictions, and Vietnam FDI acceleration in electronics assembly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Global Light Sensors Market