
 Global Nanophotonics Market | 2026-2036
Global Nanophotonics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanophotonics Market Outlook
East Asian foundry capacity is consolidating around compound semiconductor epitaxy for photonic integrated circuits. Samsung Electronics leverages its display panel fabrication infrastructure to anchor quantum dot production at scale. Intel Corporation competes in silicon photonics foundry services for datacom transceivers. Nichia Corporation dominates high-brightness LED chip architectures through sustained gallium nitride process refinement.
Nanophotonics governs light-matter interaction at sub-wavelength scales, typically below 100 nanometers, enabling manipulation of photons through engineered metallic nanostructures, semiconductor quantum dots, and periodic dielectric lattices. Its primary commercial purpose centers on replacing electronic signal processing with optical alternatives that reduce latency and thermal load in high-bandwidth systems. Photonic crystals and plasmonics occupy the most mature technology tiers with established manufacturing protocols, while quantum dots capture expanding margin pools in display and biomedical tagging applications. Telecommunications and imaging applications lead current volume deployment, though sensors for autonomous systems represent the fastest-expanding application segment.
The US FCC governs optical communication spectrum allocation, while the EU RoHS and REACH frameworks restrict hazardous substances in nanophotonic component manufacturing, directly shaping material selection and import compliance costs. Japan's METI coordinates national photonics roadmaps that funnel public R&D funding toward next-generation optical interconnect standards. Stakeholders must monitor divergence between US export controls on advanced lithography and EU subsidy programs for open photonics foundries, as this regulatory friction will determine which supply chains capture emerging defense and satellite communication contracts.
Market Dynamics
Optical interconnect demand in hyperscale data centers is compressing electronic signal processing timelines, forcing foundries to retool compound semiconductor capacity toward photonic integrated circuits. This demand surge from North American cloud infrastructure operators is restructuring procurement patterns across East Asian manufacturing clusters.
Growth Catalysts
- China's dual carbon goals:Tightened energy-efficiency mandates are accelerating LED and laser diode replacement cycles in industrial lighting and automotive headlamp systems.
- Hyperscale data center buildouts:North American cloud operators are expanding optical interconnect deployment to manage thermal loads in high-bandwidth computing environments.
- Photonic crystal maturation:Established manufacturing protocols for periodic dielectric lattices are lowering barrier-to-entry for telecom component suppliers.
Market Restraints
- Gallium nitride supply concentration:High-brightness LED chip production depends on limited epitaxial wafer sources concentrated in Japanese and Taiwanese foundries.
- EU REACH compliance costs:Hazardous substance restrictions in nanophotonic component manufacturing are elevating material qualification timelines and import documentation burdens.
- Electron-beam lithography bottlenecks:Sub-100 nanometer feature fabrication requires equipment with extended lead times and specialized operator training.
Strategic Opportunities
- Biomedical quantum dot tagging:Diagnostic imaging and therapeutic tracking applications are opening margin pools outside traditional telecom and display verticals.
- Japan's METI photonics roadmap:Public R&D funding directed toward next-generation optical interconnect standards is creating anchor demand for domestic foundry services.
- Autonomous sensor integration:LiDAR and machine vision systems for automotive and robotics applications are pulling plasmonic and metamaterial technologies into volume production.
Industry Challenges
- Compound semiconductor talent scarcity:Epitaxial growth and III-V process engineering expertise concentrates in aging workforces at Japanese and Korean national laboratories.
- Multi-physics simulation complexity:Photonic-thermal-mechanical co-design requirements are extending product development cycles beyond traditional electronic component timelines.
- Legacy fab reconfiguration costs:Converting CMOS lines to silicon photonics requires cleanroom modifications and metrology upgrades that strain mid-tier foundry balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanophotonics Market |
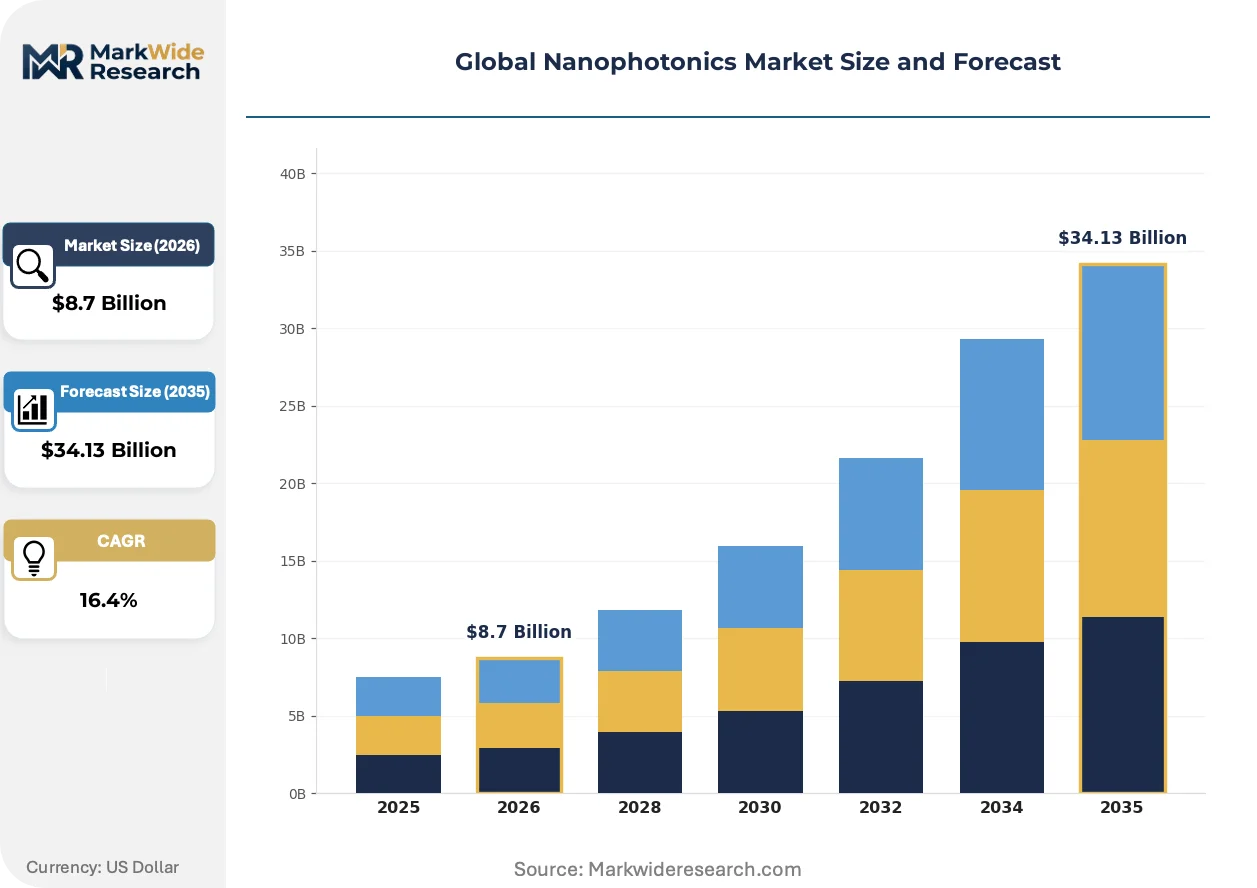
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Plasmonics, Quantum Dots, Photonic Crystals, Nano-Optomechanics Application: Displays, Sensors, Telecommunications, Imaging End User: Electronics, Healthcare, Aerospace, Defense Form Factor: Devices, Components, Systems, Modules |
| Companies Covered | Cree Inc., Samsung Electronics, OSRAM Opto Semiconductors GmbH, Lumentum Holdings Inc., Intel Corporation, IBM Corporation, Sharp Corporation, Nichia Corporation, LG Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanophotonics Market Strategic Shifts
Silicon photonics is migrating from telecom transceivers into sensing and computing substrates, while regulatory divergence between US export controls and EU subsidy programs is fragmenting supply chain alignment. These shifts are compressing technology transfer timelines and reshaping foundry customer relationships.
Co-packaged optics is decentralizing signal processing architecture in hyperscale data centers. This integration of photonic and electronic dies within single packages reduces interconnect power loss. Cloud operators in the United States are adopting co-packaged solutions for AI training clusters. The technology is decentralizing switching functions from centralized chassis to distributed rack-level units.
The EU F-Gas Regulation is phasing down fluorinated greenhouse gases used in plasma etching and chamber cleaning for photonic device fabrication. This restriction is forcing foundries to qualify alternative chemistries and retrofit abatement systems. German and Dutch equipment suppliers are accelerating dry-process substitution development to maintain EU customer access.
Hyperscale buyers are consolidating vendor relationships around vertically integrated photonics suppliers capable of delivering packaged sub-assemblies rather than discrete components. This specification shift is displacing merchant modulator and detector suppliers. The pattern is most visible in procurement contracts from North American cloud operators seeking single-source accountability for optical interconnect performance.
Global Nanophotonics Market Segmentation
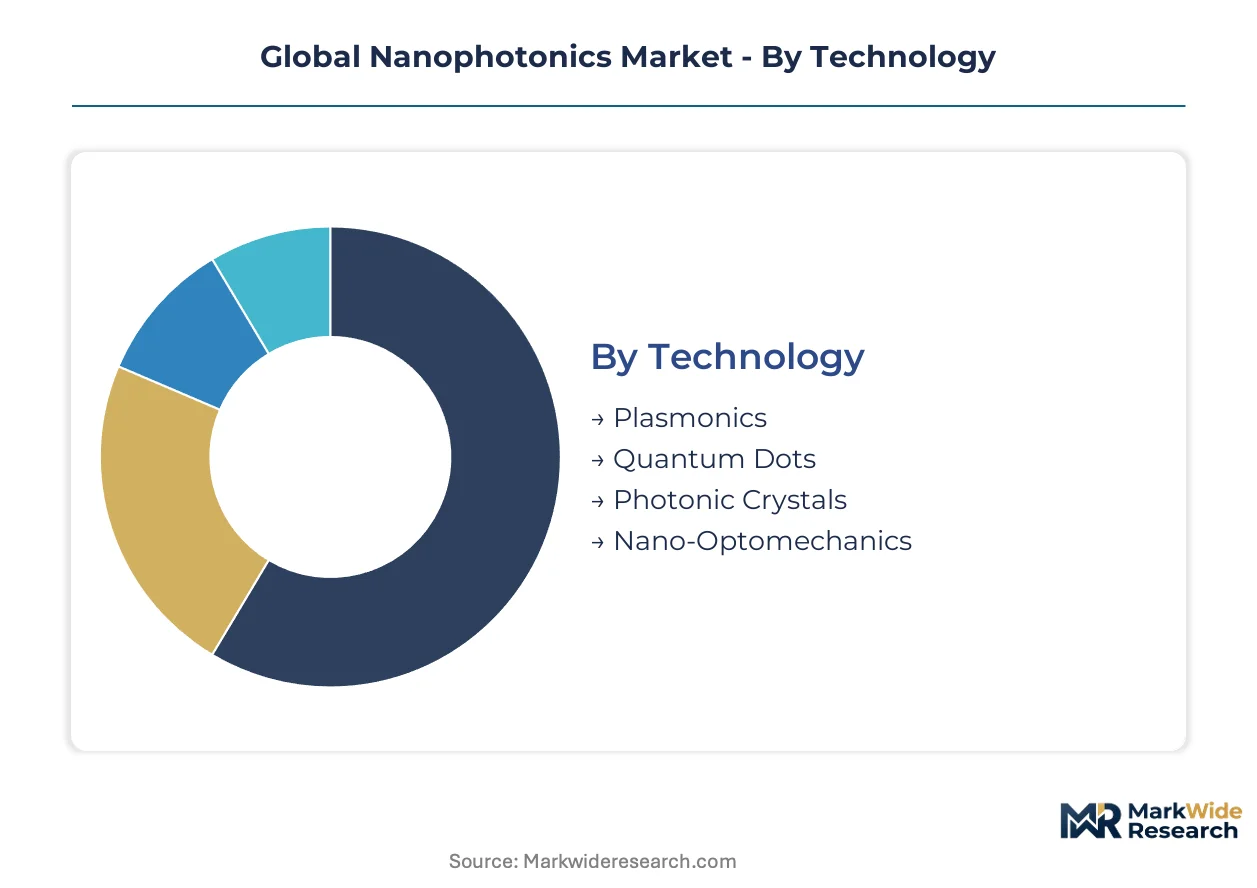
Segmentation in nanophotonics reveals how regulatory frameworks fragment procurement requirements across technology tiers. Certification burdens for EU REACH compliance, US FCC spectrum allocation, and Japan's METI roadmaps create distinct compliance cost structures that reshape competitive positioning in each segment.
Technology:
Certification requirements vary sharply by technology maturity. Photonic crystals face streamlined EU RoHS documentation, while quantum dots trigger extended ECHA substance registration timelines. Plasmonic devices for defense applications require US ITAR clearance, constraining supplier pools.
- Plasmonics:Engineered metallic nanostructures manipulate light through surface plasmon polaritons at sub-wavelength scales. Defense contractors in the United States drive procurement for infrared sensing and stealth coatings, constrained by ITAR export licensing delays. The technology commands premium pricing in aerospace applications where electromagnetic signature control is critical.
- Quantum Dots:Semiconductor nanocrystals with tunable emission spectra enable high-color-gamut displays and biomedical fluorescence tagging. Samsung Electronics anchors volume demand for QD-enhanced display panels, while diagnostic laboratories in Japan and Germany expand consumption for multiplexed assay systems. ECHA registration requirements for cadmium-free formulations extend supplier qualification cycles.
- Photonic Crystals:Periodic dielectric lattices control photon propagation through bandgap engineering. Telecom component suppliers leverage established foundry protocols for wavelength division multiplexing filters.
- Nano-Optomechanics:Integrated photonic and mechanical structures enable precision sensing and quantum information processing. Research institutions in Switzerland and Austria anchor early-stage demand.
Photonic crystals sit at the top of the volume ranking, with quantum dots climbing the fastest.
Application:
Cost tier differentiation separates premium defense and medical imaging from commoditized consumer display applications. Telecommunications infrastructure occupies the mid-tier with volume-scale procurement from state-backed operators.
- Telecommunications:Optical interconnects and wavelength-division multiplexing components replace electronic signal processing in high-bandwidth networks. Hyperscale data center operators in the United States compress procurement timelines for co-packaged optics, while China's MIIT mandates domestic sourcing quotas for 5G backhaul equipment. Thermal management requirements in AI training clusters accelerate technology refresh cycles.
- Sensors:LiDAR, biochemical detectors, and structural health monitors leverage plasmonic and photonic crystal architectures. Automotive OEMs in Germany and Japan specify autonomous vehicle perception systems, pulling metamaterial designs into volume production. EU F-Gas Regulation restrictions on plasma etching chemistries force foundry process requalification.
- Displays:Quantum dot enhancement films and micro-LED arrays enable high-dynamic-range visualization. Consumer electronics manufacturers in South Korea and Taiwan dominate panel integration.
- Imaging:Super-resolution microscopy and medical diagnostic systems exploit near-field optical effects. Academic medical centers in the United States and Switzerland anchor premium equipment procurement.
Telecommunications commands the largest revenue base, with sensors expanding most quickly.
End User:
Customer type determines specification stringency and contract duration. Defense programs lock in decade-long supply agreements, while electronics OEMs rotate vendors annually based on cost benchmarks.
- Electronics:Consumer device and computing equipment manufacturers integrate photonic components for signal processing and sensing. Apple and Meta anchor North American demand for AR/VR waveguide modules, while Chinese smartphone OEMs accelerate under-display sensor adoption. FCC equipment authorization timelines create 6-12 month launch delays for new photonic subsystems.
- Healthcare:Diagnostic imaging and therapeutic device manufacturers deploy quantum dots and plasmonic biosensors. FDA 510(k) clearance requirements for fluorescence-guided surgery systems extend development timelines beyond 24 months. Japanese pharmaceutical conglomerates fund quantum dot probe development for oncology applications.
- Aerospace:Satellite communication and aircraft systems specify radiation-hardened photonic components. European Space Agency programs funnel R&D contracts toward Dutch and German foundries.
- Defense:Military communication and electronic warfare systems demand ITAR-controlled supply chains. US Department of Defense programs restrict vendor pools to domestic and allied-nation sources.
Electronics generates the highest shipment volumes, with healthcare gaining share fastest.
Form Factor:
Supply concentration varies by integration depth. Discrete components fragment across merchant suppliers, while packaged modules consolidate around vertically integrated providers.
- Components:Discrete lasers, modulators, detectors, and waveguides ship as unintegrated die or packaged chips. Merchant suppliers in Taiwan and Japan dominate modulator and detector production for telecom applications. Intel's silicon photonics foundry services displace discrete component vendors in hyperscale data center procurement.
- Modules:Integrated sub-assemblies combining photonic and electronic functions enable plug-in deployment. North American cloud operators consolidate vendor relationships around module-level suppliers capable of performance guarantees.
- Devices:Standalone instruments for spectroscopy, microscopy, and sensing anchor academic and industrial R&D procurement.
- Systems:Complete equipment platforms incorporating photonic subsystems serve medical imaging and communication infrastructure end markets.
Components lead absolute volume, with modules capturing margin expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting nanophotonics foundry investments toward jurisdictions with streamlined substance registration protocols. Cost-of-compliance gaps between REACH-heavy European operations and East Asian regulatory environments are accelerating capacity migration.
United States
Hyperscale data center operators in Virginia and Oregon compress procurement timelines for co-packaged optical interconnects. The FCC governs spectrum allocation for photonic communication systems, creating 6-12 month equipment authorization delays. Intel Corporation anchors silicon photonics foundry services in the Pacific Northwest, displacing discrete component vendors in cloud infrastructure contracts.
China
MIIT mandates domestic sourcing quotas for 5G optical backhaul equipment, redirecting procurement toward state-backed foundries. Dual carbon goals and tightened energy-efficiency standards from MEE accelerate LED replacement cycles in industrial lighting. Manufacturing clusters in Shenzhen and Suzhou concentrate compound semiconductor epitaxy capacity for photonic integrated circuits.
Japan
METI coordinates national photonics roadmaps that funnel public R&D funding toward next-generation optical interconnect standards. PMDA regulatory pathways for fluorescence-guided surgery systems extend development timelines beyond 24 months. Nichia Corporation dominates high-brightness LED chip production through sustained gallium nitride process refinement in Anan.
Germany
Automotive OEMs in Stuttgart and Munich specify autonomous vehicle LiDAR systems, pulling metamaterial designs into volume production. The EU F-Gas Regulation phases down fluorinated greenhouse gases used in plasma etching, forcing foundry process requalification. OSRAM Opto Semiconductors anchors optoelectronic component supply for European industrial automation.
South Korea
Samsung Electronics leverages display panel fabrication infrastructure to anchor quantum dot production at scale for QD-enhanced televisions. MFDS regulatory frameworks govern biomedical fluorescence tagging applications, extending supplier qualification cycles. Foundry capacity in Suwon and Pyeongtaek concentrates on compound semiconductor epitaxy for photonic integrated circuits.
Global Nanophotonics Market Competitive Environment
East Asian producers anchor one tier; North American and European specialists hold differentiated positions in defense and biomedical applications. The vendor base separates between vertically integrated conglomerates with captive display or semiconductor operations and merchant component suppliers serving telecom infrastructure. Three archetypes dominate: diversified electronics conglomerates leveraging existing fab infrastructure, pure-play photonics specialists focused on wavelength-specific components, and silicon photonics foundries displacing discrete vendors. Competitive moves concentrate on backward integration into epitaxial wafer supply and strategic partnerships with hyperscale cloud operators.
Among diversified electronics conglomerates, Samsung Electronics and LG Display exemplify the archetype of leveraging display panel infrastructure for quantum dot scale production. Within the compound semiconductor specialist tier, Nichia Corporation occupies a position representing sustained gallium nitride process refinement for high-brightness applications. Intel Corporation sits within the silicon photonics foundry archetype, competing to displace discrete component suppliers in datacom transceiver procurement.
| Leading Market Players |
|---|
| Cree Inc. |
| Samsung Electronics |
| OSRAM Opto Semiconductors GmbH |
| Lumentum Holdings Inc. |
| Intel Corporation |
| IBM Corporation |
| Sharp Corporation |
| Nichia Corporation |
| LG Display |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride epitaxial wafer costs cascade through three distinct pricing tiers as compound semiconductor foundries in Japan and Taiwan convert substrate pricing power into module-level premiums. Raw material concentration at Nichia Corporation and select Taiwanese suppliers compresses margins for merchant LED chip vendors while vertically integrated display manufacturers capture downstream margin pools.
Pricing Analysis
Distributor markups on discrete photonic components range from 15% to 35% depending on certification tier, with ITAR-cleared plasmonic devices commanding the widest spreads. Three-tier pricing structure across defense-qualified, industrial-grade, and consumer-tier specifications reflects divergent qualification burdens. Cost compression in high-brightness LED chips is intensifying because Chinese domestic foundries are expanding gallium nitride capacity. Hyperscale data center operators exhibit the lowest price sensitivity due to thermal-load reduction mandates, while automotive Tier 1 suppliers negotiate aggressively on LiDAR detector volumes.
Supply Chain Analysis
Freight costs for electron-beam lithography equipment from German and Dutch suppliers add 8-12% to total installed cost for East Asian foundries, compressing capital deployment timelines. Manufacturing concentrates in Japan, Taiwan, and South Korea for compound semiconductor epitaxy, with China expanding domestic photonic integrated circuit capacity. Raw material flows draw from Australian gallium refiners, Japanese sapphire substrate producers, and German precursor chemical suppliers. Single-source vulnerability around MOCVD reactor maintenance creates operational risk during capacity ramps. Distribution runs through vertically integrated module suppliers rather than discrete component merchants for North American cloud infrastructure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hyperscale buyers are consolidating vendor relationships around packaged sub-assembly guarantees rather than discrete component specifications.
For Market Incumbents: Acquire compound semiconductor epitaxy capacity in Taiwan or Japan before gallium nitride wafer supply tightens further. Defend module-level pricing power by integrating photonic and electronic die packaging capabilities in-house, as Intel's silicon photonics foundry services threaten merchant modulator suppliers. Secure ITAR clearance pathways for plasmonic defense applications before regulatory backlogs extend. For New Entrants and Emerging Players: Launch via direct partnerships with German automotive OEMs specifying autonomous vehicle LiDAR systems, bypassing established telecom component channels. Target biomedical quantum dot tagging applications in Japan and Germany where ECHA and MFDS regulatory barriers deter commodity competitors. Penetrate through cadmium-free formulation development that accelerates supplier qualification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where compound semiconductor talent scarcity meets aging workforces at Japanese national laboratories. Long-term viability favors vertically integrated providers with captive display or cloud infrastructure customer relationships over merchant component specialists. Watch for inflection signals in EU F-Gas Regulation enforcement that would force dry-process substitution investments and reshape equipment supplier competitive positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Captive gallium nitride capacity insulates margin structures from Japanese and Taiwanese substrate pricing power. |
| Co-Packaged Optics Platform Development | Intel's foundry services demonstrate how photonic-electronic integration displaces discrete component vendors in hyperscale procurement. |
| Cadmium-Free Quantum Dot Formulation | ECHA registration compliance accelerates supplier qualification cycles for diagnostic imaging and display applications. |
| ITAR-Cleared Plasmonic Manufacturing | US Department of Defense programs restrict vendor pools, creating premium pricing tiers for qualified suppliers. |
| Dry-Process Etching Qualification | EU F-Gas Regulation phase-down forces foundry process requalification that German equipment suppliers are positioned to capture. |
Study Parameters
Direct dialogue with compound semiconductor process engineers, hyperscale data center procurement directors, photonic integrated circuit designers, and regulatory compliance officers at ECHA and METI grounded qualitative assessments. Secondary validation drew from FCC equipment authorization databases, EU REACH substance registration filings, SEC 10-K disclosures from listed photonics suppliers, and hyperscaler capital expenditure reports. Bottom-up demand modeling across technology tiers triangulated against top-down market sizing from trade flow analysis.
Segmented outputs across plasmonic, quantum dot, photonic crystal, and nano-optomechanical technology tiers combined with application splits in telecommunications, sensors, displays, and imaging. End-user differentiation among electronics OEMs, healthcare device manufacturers, aerospace contractors, and defense programs shaped volume allocation. CAGRs were derived from technology adoption curves weighted against regulatory compliance timeline impacts. Forecast inputs included electron-beam lithography equipment lead times, gallium nitride epitaxial wafer supply expansion schedules, and hyperscale data center thermal density specifications.
Several conditions sit outside the modeled scope, including unforeseen export control expansions on advanced lithography, abrupt shifts in Chinese domestic sourcing mandate enforcement, and breakthroughs in all-optical computing that would displace electronic-photonic hybrid architectures. Forecasts reflect assumptions about sustained hyperscale infrastructure investment and gradual EU F-Gas Regulation phase-down timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Wavelength Service Market
Optics
Stroboscope Market
Optics
Fiber Optic Cable Market
Optics
Optical Telephoto Lens Market
Optics
US Photonics Market
Optics
Digital Holographic Microscopy Market
Optics
Optical Telescope Market
Optics
Beam Expanders Market
Optics
Global Super Hi Vision Market
Optics
Fiber Optic Receiver Market
Optics
Asia Pacific Fiber Optics Market
Optics
Fiber Optic Development Tools Market
Optics
Fiber Optic Switch Market
Optics
MEMS Mirrors Market
Optics
Latin America Optical Imaging Market
Optics
Liquid Crystal on Silicon Market