
 Acoustic Respiration Sensors Market | 2026-2036
Acoustic Respiration Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Respiration Sensors Market Outlook
Modular sensor-to-platform bundling is shifting buyer choice across acute and ambulatory settings. ResMed leverages its sleep therapy ecosystem to anchor acoustic respiration modules within integrated care workflows. Philips Healthcare competes through hospital-grade manufacturing scale across North American and European installed bases. Medtronic differentiates via deep cardiac-respiratory convergence in its monitoring portfolio.
Acoustic respiration sensors detect airflow sounds, chest wall vibrations, or tracheal acoustics through piezoelectric or capacitive transduction, typically operating in bandwidths from 20 Hz to 2 kHz to isolate breath sounds from ambient noise; their primary purpose is continuous, non-contact respiratory rate and pattern monitoring in clinical and home environments. Wearable sensors lead unit volume due to expanding remote patient monitoring contracts, while in-hospital devices command the dominant margin pool through multi-parameter integration and software subscription attach rates. Smart algorithms represent the fastest-expanding technology layer as edge-AI processing enables real-time apnea detection without cloud dependency.
The FDA's breakthrough device program and the EU MDR's Class IIa surveillance requirements shape product development timelines and clinical evidence burdens for manufacturers seeking dual-market access. HIPAA data governance and GDPR health-data provisions constrain cloud-architecture choices, pushing vendors toward on-device processing. Stakeholders must weigh regulatory jurisdiction sequencing against the capital intensity of parallel FDA-EMA validation tracks.
Market Dynamics
Edge-AI processing is compressing cloud dependency and rewriting competitive positioning in acoustic respiration monitoring, as on-device inference slashes latency and HIPAA compliance costs for vendors serving US hospital networks.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated clearance track trims validation timelines for novel sensor platforms, enabling faster commercialization of apnea-detection algorithms in US acute care settings.
- German Hospital Procurement:Post-surgical respiratory surveillance mandates in German tertiary centers are pulling acoustic monitoring systems into step-down unit standard configurations.
- Piezoelectric Transduction Maturation:Advances in 20 Hz to 2 kHz bandwidth isolation are sharpening signal-to-noise ratios for chest wall vibration detection in home sleep monitoring.
Market Restraints
- EU MDR Class IIa Evidence Burden:The EU MDR's clinical surveillance requirements impose documentation costs that favor scaled manufacturers over mid-tier entrants seeking dual-market access.
- MEMS Foundry Concentration:Taiwan and South Korea dominate capacitive transducer fabrication, creating single-source vulnerability for acoustic sensor supply chains.
- Optical Plethysmography Substitution:Camera-based respiration tracking in consumer wellness devices is capturing price-sensitive remote monitoring segments.
Strategic Opportunities
- India Remote Patient Monitoring:CDSCO's streamlined Class B medical device registration is opening ambulatory acoustic sensor deployment for chronic obstructive pulmonary disease management in tier-2 cities.
- Cardiac-Respiratory Convergence:Integration of acoustic respiration modules with implantable cardiac monitors is creating premium tier positioning in integrated health networks.
- Subscription Software Attach:Real-time pattern-recognition algorithms delivered via SaaS models are expanding recurring revenue pools beyond hardware margins in North American hospital systems.
Industry Challenges
- Biomedical Signal Processing Talent Scarcity:The shortage of engineers trained in respiratory acoustics and edge-AI optimization is constraining R&D velocity for algorithm refinement.
- Legacy EMR Integration Complexity:Acoustic sensor data streams require custom HL7 FHIR mapping to penetrate Cerner and Epic dominated US hospital IT environments.
- Parallel FDA-EMA Validation Capital Intensity:Simultaneous breakthrough device and notified body conformity assessments demand duplicated clinical studies, stretching startup balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Respiration Sensors Market |
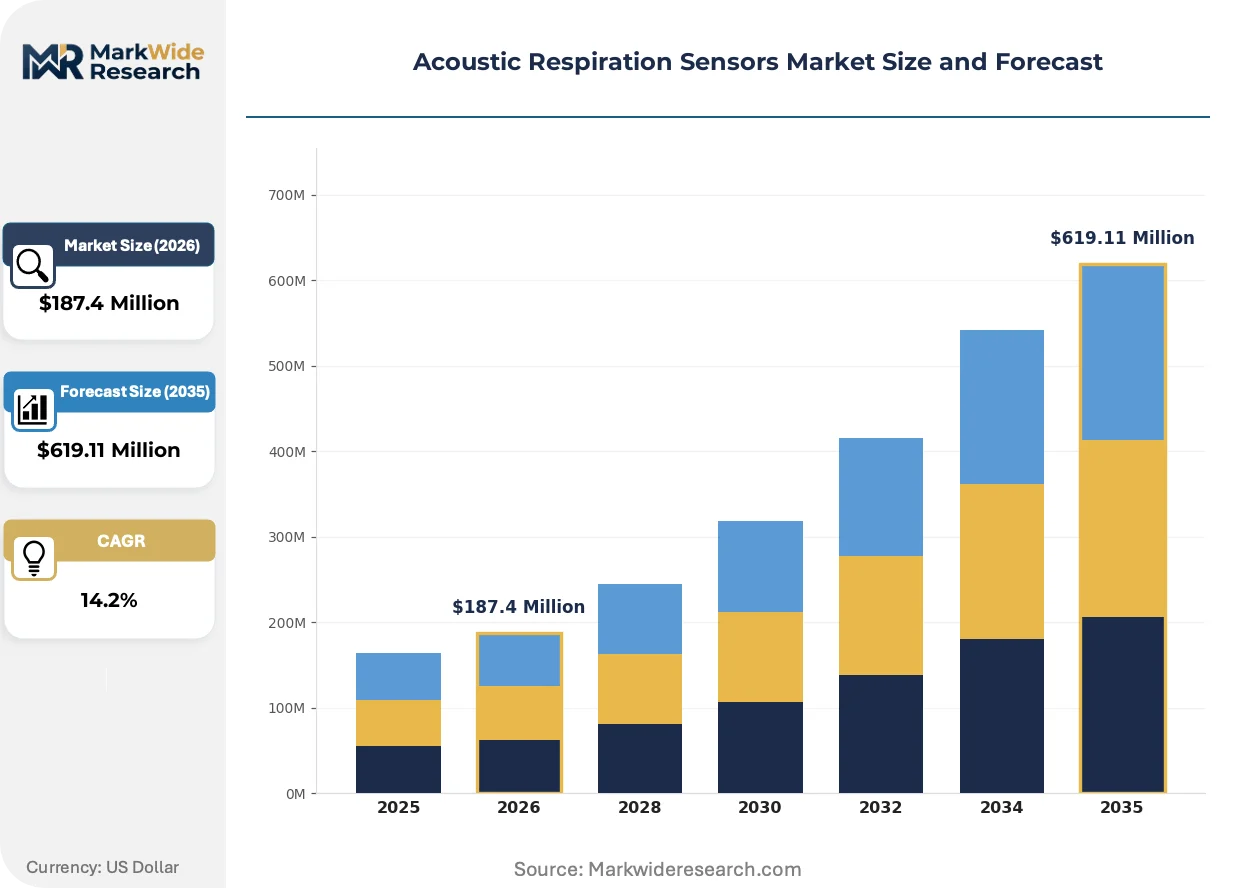
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Portable Monitors, In-Hospital Devices, Home Care Unit End User: Hospitals, Clinics, Home Care Providers, Research Institutions Technology: Acoustic Monitoring, Piezoelectric Sensors, Ultrasound-Based, Smart Algorithms Application: Sleep Apnea Diagnosis, Chronic Obstructive Pulmonary Disease, Vital Signs Monitoring, Patient Health Tracking |
| Companies Covered | ResMed, Abbott Laboratories, Philips Healthcare, GE Healthcare, Smiths Medical, Medtronic, Masimo, Drägerwerk, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Respiration Sensors Market Strategic Shifts
Algorithmic intelligence is migrating from cloud servers to sensor edges, while regulatory frameworks on both sides of the Atlantic accelerate or complicate market entry depending on vendor scale and evidence strategy.
Smart algorithms are expanding into real-time apnea detection without network dependency. US step-down units are piloting these modules to reduce alarm fatigue and latency. The shift is compressing cloud-architecture competitive advantages and favoring vendors with silicon-level optimization capabilities.
The EU AI Act's risk classification for medical device software is reshaping quality management system requirements for acoustic respiration platforms. Manufacturers must now document algorithmic transparency and post-market performance monitoring. German notified bodies are interpreting these provisions most stringently, slowing CE marking for novel sensor-to-AI pipelines.
Integrated health networks are consolidating vendor relationships around multi-parameter platform contracts. Standalone acoustic sensor vendors face exclusion from US hospital procurement shortlists unless bundled with pulse oximetry or capnography modules. The pattern is most visible in Kaiser Permanente and Veterans Health Administration purchasing frameworks.
Acoustic Respiration Sensors Market Segmentation
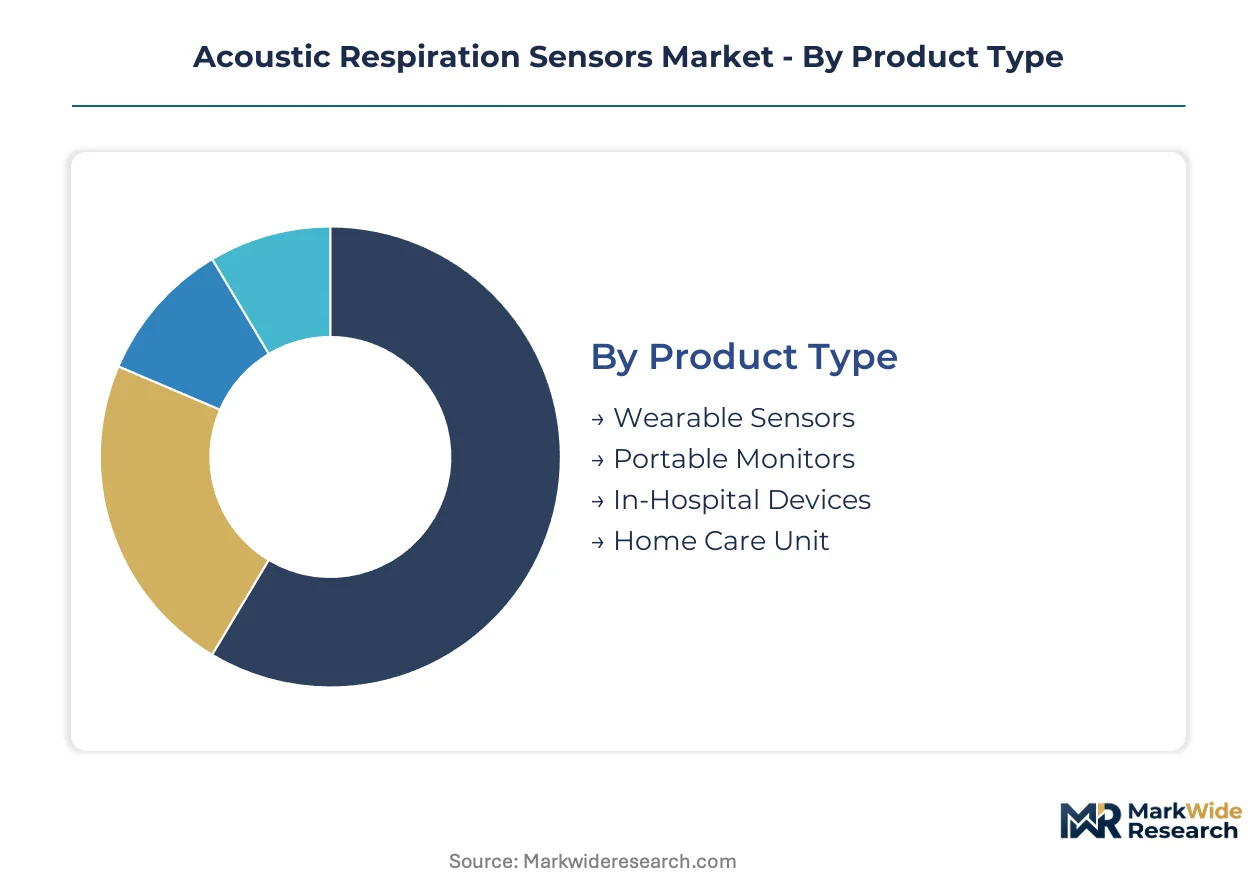
Acoustic respiration sensors fragment across four orthogonal dimensions that determine procurement pathways and margin structures. Product type dictates integration depth with clinical workflows, while technology selection governs cloud dependency and regulatory evidence burdens. Application focus shapes reimbursement eligibility and algorithm training requirements.
Product Type:
Wearable sensors and in-hospital devices sit at opposite poles of integration depth, with portable monitors and home care units occupying intermediate positions in the deployment spectrum.
- Wearable Sensors:Chest-worn or adhesive patches employing piezoelectric transduction for continuous ambulatory monitoring. Remote patient monitoring contracts with US integrated delivery networks concentrate procurement volume here, though battery life constraints limit multi-day adherence.
- In-Hospital Devices:Multi-parameter bedside units embedding acoustic modules alongside pulse oximetry and capnography. German tertiary centers expanding post-surgical surveillance drive replacement cycles, with software subscription attach rates commanding the dominant margin pool.
- Portable Monitors:Handheld or cart-based systems for inter-departmental transport. Clinics in India's tier-2 cities favor these for chronic obstructive pulmonary disease outreach programs under CDSCO Class B registration pathways.
- Home Care Unit:Standalone bedside consoles for domestic sleep apnea surveillance. Reimbursement variability across US state Medicaid programs constrains penetration relative to clinical-grade alternatives.
Wearable sensors lead volumes today; smart algorithm integration is gaining share fastest.
End User:
Procurement authority and evidence requirements diverge sharply between institutional purchasers with quality management systems and decentralized home care channels.
- Hospitals:Step-down units in US health networks mandate continuous respiration monitoring for opioid-sedated patients. Kaiser Permanente and Veterans Health Administration purchasing frameworks favor bundled multi-parameter contracts over standalone acoustic sensors.
- Clinics:Outpatient pulmonary function labs deploy portable acoustic systems for pre-operative assessments. German ambulatory care centers face EU MDR Class IIa surveillance documentation requirements that favor scaled suppliers.
- Home Care Providers:Durable medical equipment distributors serving sleep therapy markets. ResMed's ecosystem bundling anchors acoustic modules within integrated care workflows for this channel.
- Research Institutions:Academic medical centers conducting algorithm validation studies for FDA breakthrough device submissions. NIH-funded respiratory acoustics programs supply training data for edge-AI optimization.
Hospitals dominate revenue concentration; home care providers are expanding most quickly.
Technology:
Signal processing architecture determines cloud dependency, latency tolerance, and HIPAA compliance architecture for US deployment.
- Acoustic Monitoring:Broadband sound capture from 20 Hz to 2 kHz isolating breath sounds from ambient noise. Standard configurations in legacy hospital installations require custom HL7 FHIR mapping for Cerner and Epic EMR integration.
- Piezoelectric Sensors:Transduction of chest wall vibrations through ceramic or polymer elements. Advances in bandwidth isolation are sharpening signal-to-noise ratios for home sleep monitoring applications.
- Ultrasound-Based:Doppler detection of tracheal airflow without skin contact. Research-stage deployment in neonatal intensive care units avoids adhesive-related skin integrity complications.
- Smart Algorithms:Edge-AI processing enabling real-time apnea detection without network dependency. US step-down units pilot these modules to reduce alarm fatigue and cloud-architecture compliance costs.
Acoustic monitoring retains installed base dominance; smart algorithms represent the steepest expansion trajectory.
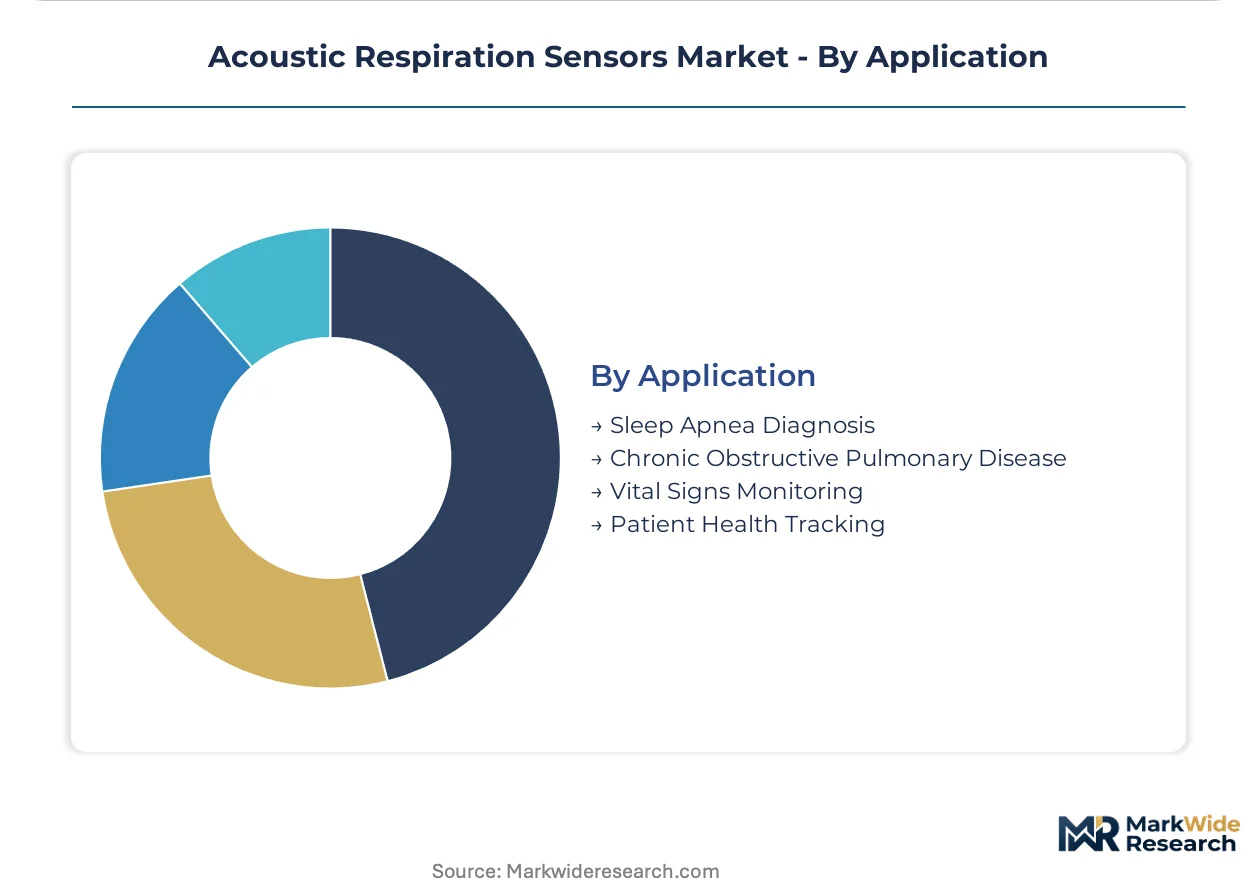
Application:
Clinical indication determines reimbursement coding, algorithm training data requirements, and competitive substitution risk from alternative monitoring modalities.
- Sleep Apnea Diagnosis:Home-based polysomnography alternatives using acoustic respiration pattern recognition. US Medicare coverage determinations for remote therapeutic monitoring are expanding eligible patient populations.
- Chronic Obstructive Pulmonary Disease:Continuous monitoring for exacerbation early warning. India's CDSCO streamlined registration is opening ambulatory deployment in tier-2 cities with high COPD prevalence.
- Vital Signs Monitoring:General ward respiratory rate surveillance alongside pulse oximetry. Optical plethysmography substitution in consumer wellness devices is capturing price-sensitive segments.
- Patient Health Tracking:Consumer-grade wellness applications with limited clinical validation. GDPR health-data provisions and HIPAA constraints push vendors toward on-device processing for this channel.
Vital signs monitoring anchors hospital procurement; sleep apnea diagnosis is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic respiration monitoring originated in German university hospitals during the 1990s, where researchers first validated tracheal sound analysis for post-operative surveillance. The technology diffused through North American integrated health networks and Asia-Pacific manufacturing clusters over subsequent decades.
United States
Kaiser Permanente and Veterans Health Administration procurement frameworks favor bundled multi-parameter contracts incorporating acoustic modules. FDA breakthrough device designation compresses validation timelines for novel sensor platforms. NIH-funded respiratory acoustics programs at Boston academic medical centers supply training data for edge-AI algorithm development.
Germany
Tertiary centers in Munich and Berlin mandate continuous post-surgical respiratory surveillance in step-down units. EU MDR Class IIa surveillance requirements impose documentation burdens that favor scaled manufacturers over mid-tier entrants. Baden-Württemberg's medical technology cluster hosts precision piezoelectric transducer fabrication for bandwidth-isolated chest wall vibration detection.
India
Tier-2 cities with high chronic obstructive pulmonary disease prevalence drive ambulatory acoustic sensor deployment. CDSCO streamlined Class B medical device registration reduces market entry barriers for portable monitoring systems. Karnataka's Bengaluru medical device corridor concentrates contract manufacturing for wearable respiratory patches serving domestic and export markets.
Japan
Super-aging demographics expand home sleep apnea diagnosis demand beyond clinical polysomnography capacity. PMDA's streamlined review pathway for software-as-a-medical-device accelerates algorithm-based product approvals. Osaka-Kobe industrial zone maintains precision ceramics supply chains for piezoelectric transducer elements in next-generation sensors.
South Korea
National health insurance coverage expansion for remote patient monitoring creates reimbursement tailwinds for wearable respiratory devices. MFDS regulatory harmonization with FDA breakthrough pathways enables parallel market entry strategies. Seoul Capital Area semiconductor foundries fabricate edge-AI processing chips enabling on-device apnea detection without cloud dependency.
Acoustic Respiration Sensors Market Competitive Environment
Premium-margin players sit above commodity-margin players across algorithmic sophistication and EMR integration depth. The vendor base stratifies into three tiers: diversified health technology conglomerates with hospital-grade manufacturing scale, sleep therapy ecosystem operators leveraging integrated care workflow bundling, and cardiac monitoring specialists pursuing respiratory convergence. Consolidation pressure intensifies as integrated health networks reduce approved vendor lists. Dominant competitive moves include strategic partnerships for HL7 FHIR interoperability and portfolio diversification into multi-parameter bedside platforms.
Within the diversified health technology tier, ResMed and Philips Healthcare exemplify contrasting ecosystem strategies. ResMed anchors acoustic modules within sleep therapy workflows through software subscription attach models. Philips Healthcare occupies a position shaped by hospital-grade manufacturing scale across North American and European installed bases. Medtronic represents the cardiac-respiratory convergence archetype, integrating acoustic respiration capabilities with implantable monitor portfolios to capture premium positioning in integrated health networks.
| Leading Market Players |
|---|
| ResMed |
| Abbott Laboratories |
| Philips Healthcare |
| GE Healthcare |
| Smiths Medical |
| Medtronic |
| Masimo |
| Drägerwerk |
| Honeywell International |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up sensor module specialists anchor supply discipline across Taiwan and South Korea foundries, translating concentrated wafer fabrication into predictable component pricing that constrains margin volatility for downstream acoustic respiration device assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs acoustic respiration sensor procurement, with FDA breakthrough designation and EU MDR Class IIa certification tiering price bands by clinical evidence burden. Premium tiers attach software subscription rates for edge-AI apnea detection, while economy segments face cost compression from optical plethysmography substitution in consumer wellness channels. Home care providers exhibit highest price sensitivity; integrated health networks purchasing multi-parameter bundles show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Kaiser Permanente and Veterans Health Administration procurement frameworks compel acoustic sensor vendors to qualify piezoelectric transducers from both Taiwan and South Korea MEMS foundries. Ceramic substrate supply draws from Japan's Osaka-Kobe industrial zone, while edge-AI processing chips source from Seoul Capital Area semiconductor fabs. Single-source vulnerability concentrates in Taiwan capacitive transducer fabrication. Distribution runs through durable medical equipment distributors and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acoustic respiration sensors rests on edge-AI processing cost-down curves and premium-tier algorithm attach rates displacing commodity hardware-only configurations.
For Market Incumbents: Lock in multi-parameter platform bundling with Kaiser Permanente and Veterans Health Administration purchasing frameworks before standalone sensor vendors achieve HL7 FHIR interoperability. Backward integration into piezoelectric transducer fabrication mitigates Taiwan foundry concentration risk. Priority certification investment targets EU MDR Class IIa surveillance documentation to exclude mid-tier entrants from German hospital procurement shortlists. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass incumbent GPO lock-in for portable acoustic monitors targeting India's tier-2 COPD management programs under CDSCO Class B registration. White-space concentrates in ambulatory sleep apnea diagnosis beyond ResMed's ecosystem bundling. Go-to-market anchors on SaaS algorithm pricing decoupled from hardware margins. For Investors and Strategic Acquirers: Valuations sit cheapest among edge-AI algorithm specialists lacking FDA breakthrough pathway progress but holding NIH-funded training data repositories. Five-to-ten-year viability favors cardiac-respiratory convergence plays with implantable monitor integration capabilities. Watch FDA breakthrough device designation velocity as inflection signal for premium-tier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated clearance compresses validation timelines for novel apnea-detection algorithms in US acute care. |
| EU MDR Class IIa Certification Pathway | Notified body conformity assessment filters mid-tier entrants from German tertiary center procurement. |
| Hospital System Partnership | Kaiser Permanente bundled multi-parameter contracts exclude standalone acoustic sensor vendors. |
| Edge-AI Software Companion Development | On-device inference slashes HIPAA compliance costs and cloud-architecture dependency for US networks. |
| Reimbursement Strategy | Medicare remote therapeutic monitoring coverage expansion enlarges eligible sleep apnea patient populations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sleep therapy clinic operators with secondary validation against FDA 510(k) filings, CDSCO registration databases, CMS Medicare coverage determinations, and EU MDR notified body guidance documents. Bottom-up sensor shipment modeling and top-down healthcare IT expenditure triangulation anchored market sizing.
Comparable-period anchoring tied projection assumptions to historical replacement cycles in German post-surgical surveillance installations and US step-down unit expansion patterns. Segmentation dimensions spanned product type integration depth, technology signal processing architecture, application clinical indication, and end-user procurement authority. CAGRs derived from algorithm adoption S-curves and edge-AI chip cost trajectories. Modeling incorporated NIH funding flows for respiratory acoustics research and MFDS-PMDA regulatory harmonization progress.
The model assumes a particular technology adoption path; alternative pathways for camera-based optical plethysmography would alter the outlook for acoustic sensor penetration in consumer wellness segments. Deviation in FDA breakthrough device designation velocity or EU AI Act risk classification stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Thermometer Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Lighting Control Sensors Market