
 AR and VR Lens Market | 2026-2036
AR and VR Lens Market Size, Share, and Industry Trends Forecast 2026-2036
AR and VR Lens Market Insights
Buyer concentration in the entertainment sector is rebalancing as enterprise procurement from healthcare providers and education institutions accelerates. Microsoft leverages its mixed-reality platform to anchor defense and industrial training contracts. Sony specializes in high-resolution OLED microdisplay integration for consumer VR headsets. Google competes through Android XR ecosystem partnerships that extend its software influence into lens-integrated hardware.
AR and VR lenses are precision optical components that manipulate light paths to create immersive virtual or augmented visual fields, typically incorporating aspheric or Fresnel surface profiles to minimize aberrations while maintaining compact form factors. These lenses serve the primary commercial purpose of translating microdisplay output into wide-field, distortion-corrected images positioned at comfortable viewing distances for extended wear. Fresnel lenses currently dominate volume production for consumer VR headsets due to their lightweight, thin-profile advantages over conventional spherical designs. Optical waveguides represent the fastest-growing technology segment as manufacturers pursue see-through AR formats that overlay digital content without obstructing ambient vision. Training simulations command premium pricing among applications, driven by defense and aviation sector procurement of certified immersive systems.
FDA clearance requirements for telemedicine AR devices shape product development timelines for healthcare-facing lens systems in the United States. EMA medical device regulations and CE marking obligations under the EU MDR govern market access for European clinical applications. China's NMPA and MIIT coordinate standards for near-eye display products, influencing both domestic manufacturers and export-bound suppliers. Stakeholders must monitor evolving ophthalmic safety standards and regional certification divergence to align R&D roadmaps with compliant commercialization pathways.
Market Dynamics
Optical waveguide manufacturing advances are compressing lens thickness and weight while expanding see-through AR formats, fundamentally restructuring competitive advantage around precision optics capabilities rather than display integration alone.
Growth Catalysts
- Surgical Training Demand:Healthcare providers in the United States are expanding procurement of immersive simulation systems for remote diagnostics and operative rehearsal, creating certified device demand that validates premium lens specifications.
- EMA Medical Device Regulations:CE marking obligations under the EU MDR are accelerating compliance investments by European clinical application developers, filtering out subscale suppliers and consolidating procurement toward qualified optics vendors.
- Fresnel Lens Volume Production:Lightweight thin-profile Fresnel designs dominate consumer VR headset manufacturing, with precision molding advances enabling cost-efficient scaling across mass-market hardware platforms.
Market Restraints
- Optical-Grade Polymer Volatility:Specialized cyclo-olefin polymer feedstock prices fluctuate with petrochemical input costs, compressing margins for injection-molded Fresnel lens producers serving price-sensitive consumer segments.
- Precision Optics Cluster Concentration:Manufacturing of high-index glass substrates and diffractive optical elements concentrates in Germany and Japan, exposing supply chains to single-source geopolitical and logistics risks.
- Waveguide Yield Limitations:Nanoimprint lithography for surface-relief gratings achieves sub-60% manufacturing yield at volume, constraining cost-down trajectories for AR waveguide modules targeting consumer price points.
Strategic Opportunities
- Defense Training Procurement:Aviation and military simulation contracts in the United States specify certified immersive systems with extended field-of-view requirements, opening premium pricing tiers for qualified lens suppliers.
- China NMPA Pathway Alignment:Near-eye display product standards coordinated by MIIT create compliance frameworks that domestic and export-bound suppliers can leverage for accelerated market access across Asia-Pacific healthcare applications.
- Pancake Optics Convergence:Folded optical path designs combining polarized beam splitters with quarter-wave plates enable sub-25mm form factors, creating differentiation vectors for next-generation VR headset platforms.
Industry Challenges
- Optical Design Talent Scarcity:Computational optics and freeform surface engineering expertise concentrates among legacy camera lens and semiconductor lithography veterans, forcing competitive recruitment from adjacent precision industries.
- FDA 510(k) Timeline Compression:Telemedicine AR devices face extended clearance cycles for ophthalmic safety validation, delaying revenue recognition for healthcare-facing lens system developers targeting clinical deployment.
- Interoperability Standard Fragmentation:Divergent display interface specifications between Qualcomm Snapdragon Spaces, Android XR, and proprietary headset architectures force redundant lens-to-display calibration investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR and VR Lens Market |
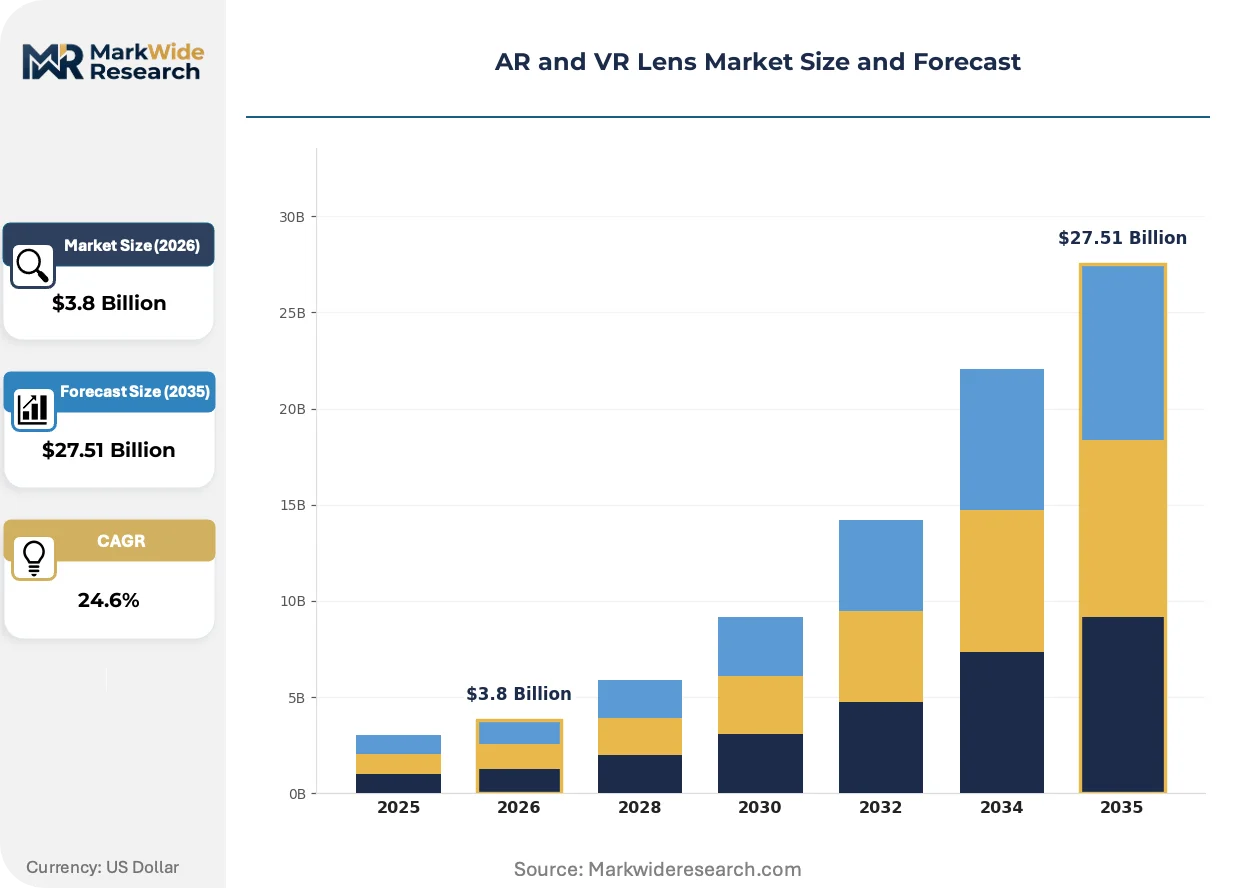
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresnel Lenses, Aspheric Lenses, Spherical Lenses, Cylindrical Lenses Technology: Optical Waveguides, Light Field Display, Holographic Optics, LCD Technology Application: Gaming, Training Simulations, Retail Experiences, Telemedicine End User: Education Institutions, Healthcare Providers, Retail Brands, Entertainment Companies |
| Companies Covered | Pico Interactive, HTC, Microsoft, Vuzix Corporation, Pimax, Sony, Google, Lenovo, DPVR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR and VR Lens Market Trends and Innovations
Waveguide architecture evolution and regulatory harmonization pressures are simultaneously enabling thinner AR form factors and reshaping which suppliers can participate in clinical and defense procurement channels.
Surface-relief grating waveguides fabricated through nanoimprint lithography are rewriting the cost-structure assumptions for consumer AR glasses. Display module integrators in China and Taiwan are adopting these designs at accelerated procurement cycles. The technology is compressing the minimum viable price point for see-through overlays from enterprise-only tiers toward mass-market accessibility.
EU MDR Article 10 technical documentation requirements are intensifying post-market surveillance obligations for near-eye medical devices. European clinical AR developers must maintain vigilance systems tracking optical radiation exposure and visual fatigue incidents. Surgical training system vendors are responding by embedding real-time luminance monitoring and automatic exposure limiting into lens-integrated firmware.
Aviation and heavy industry buyers are consolidating vendor relationships around turnkey immersive training platforms rather than discrete hardware procurement. Systems integrators are capturing margin previously allocated to component suppliers by bundling lens modules with scenario content and certification documentation. This pattern concentrates procurement authority in the United States and Germany where defense and industrial safety regulators mandate comprehensive training system validation.
AR and VR Lens Market Segmentation
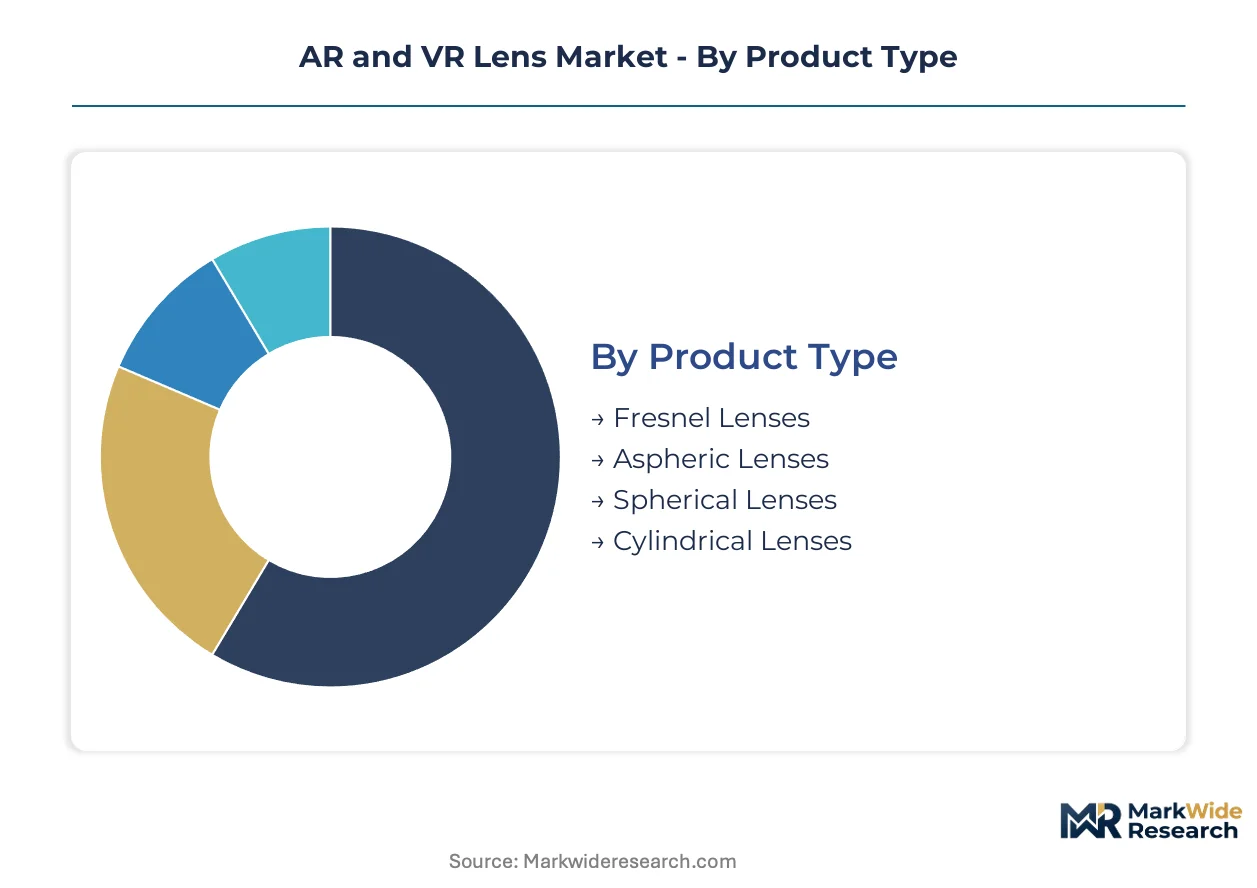
Lens specification choices directly determine headset form factor, optical performance, and manufacturing cost structure across AR and VR platforms. Segmentation reveals how component suppliers align technical capabilities with divergent upgrade cycles between consumer entertainment and enterprise certification requirements.
Product Type:
Replacement cycles for headset optics vary sharply by lens architecture, with thinner profiles commanding premium pricing during generational transitions.
- Fresnel Lenses:These concentric-ring surface profiles reduce material volume while maintaining focal power, enabling sub-10mm thickness in mass-market VR headsets. Demand concentrates among entertainment companies sourcing price-sensitive consumer hardware from Chinese manufacturing clusters, constrained by optical-grade polymer feedstock volatility.
- Aspheric Lenses:Complex curved surfaces correct spherical aberration without multiple elements, supporting higher-resolution microdisplay integration. Healthcare providers in Germany specify these for surgical training systems requiring edge-to-edge clarity, validating premium specifications through FDA and CE marking procurement channels.
- Spherical Lenses:Traditional curved surfaces dominate legacy VR architectures and budget headset tiers.
- Cylindrical Lenses:These correct astigmatism in waveguide coupling optics and specialized projection systems.
Volume placements concentrate in Fresnel designs; the faster expansion belongs to aspheric precision optics for enterprise certification.
Technology:
Technology selection governs whether lens systems enable opaque VR immersion or transparent AR overlay, determining addressable application scope.
- Optical Waveguides:These etched-glass or polymer substrates guide display light through total internal reflection toward the eye while preserving ambient visibility. Procurement from defense and aviation training contractors in the United States specifies extended field-of-view waveguide modules, with nanoimprint lithography yield limitations constraining cost reduction.
- Holographic Optics:Diffractive elements manipulate light through interference patterns, enabling ultra-thin form factors. Google leverages these in Android XR ecosystem partnerships targeting see-through consumer glasses, though manufacturing complexity limits scaling.
- Light Field Display:Multi-plane focal techniques reduce vergence-accommodation conflict in extended-use medical applications.
- LCD Technology:Direct-view liquid crystal panels with paired optics serve cost-constrained VR entry segments.
LCD-based systems retain volume dominance; waveguide architectures are climbing the fastest toward clinical and defense qualification.
Application:
Application segmentation tracks how immersion depth requirements translate into lens specification tiers and certification burdens.
- Training Simulations:Certified immersive systems for aviation and heavy industry mandate extended field-of-view optics with distortion calibration documentation. Procurement concentrates in the United States and Germany where defense regulators validate comprehensive training platforms, commanding premium pricing tiers unavailable to consumer segments.
- Telemedicine:Near-eye diagnostic displays require ophthalmic safety validation under FDA 510(k) and EU MDR frameworks. Sony integrates high-resolution OLED microdisplays with precision lenses for remote surgical visualization, facing extended clearance timelines that filter subscale suppliers.
- Gaming:Consumer entertainment drives Fresnel lens volume with price-sensitive specifications.
- Retail Experiences:Virtual try-on and spatial commerce applications prioritize lightweight waveguide compatibility.
Gaming generates the highest unit placements; telemedicine certification requirements are expanding most quickly as healthcare providers validate reimbursement pathways.
End User:
End user categories determine whether lens procurement emphasizes unit economics or compliance documentation.
- Healthcare Providers:Hospital systems and surgical training centers source certified immersive equipment with embedded real-time luminance monitoring. China's NMPA and MIIT standards coordination creates compliance frameworks that domestic and export-bound suppliers leverage for Asia-Pacific market access.
- Education Institutions:Universities and vocational programs procure mid-tier VR headsets for skills training, balancing immersion quality against budget constraints.
- Retail Brands:Marketing departments deploy AR try-on experiences requiring see-through waveguide compatibility.
- Entertainment Companies:Game publishers and streaming services drive Fresnel lens volume through mass-market headset partnerships.
Entertainment companies anchor current volume; healthcare providers are gaining share fastest as surgical simulation procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cyclo-olefin polymer feedstock availability in East Asia and precision glass substrate manufacturing in Central Europe anchor the AR and VR lens supply geography. Demand clusters concentrate where defense procurement, clinical certification frameworks, and consumer hardware ecosystems intersect.
United States
Defense training contracts and FAA-certified aviation simulation systems drive procurement of extended field-of-view waveguide modules. FDA 510(k) clearance requirements for telemedicine AR devices filter subscale suppliers from clinical applications. Boston and Seattle host mixed-reality development clusters where Microsoft anchors defense and industrial training platform integration.
Germany
Precision optics manufacturing for surgical training systems validates premium aspheric lens specifications through CE marking procurement channels. EU MDR Article 10 technical documentation requirements intensify post-market surveillance for near-eye medical devices. Jena and Munich concentrate diffractive optical element fabrication capabilities serving European clinical AR developers.
China
NMPA and MIIT coordinate near-eye display product standards that domestic manufacturers leverage for Asia-Pacific healthcare market access. Mass-market VR headset production concentrates in Shenzhen and Dongguan manufacturing clusters. Surface-relief grating waveguide adoption accelerates as display module integrators compress cost structures toward consumer price points.
Japan
High-index glass substrate and diffractive optical element manufacturing concentrates in legacy camera lens supply chains. METI standards coordination influences regional certification alignment for ophthalmic safety validation. Tokyo and Osaka precision optics veterans supply computational optics expertise to waveguide lithography process development.
South Korea
OLED microdisplay integration with precision lens systems supports high-resolution VR headset architectures for consumer entertainment. MFDS medical device regulations create parallel compliance pathways for clinical AR applications. Seoul and Suwon host display-lens integration facilities serving export-bound hardware platforms.
AR and VR Lens Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue waveguide miniaturization and clinical certification specializations. The vendor base stratifies across three tiers: integrated headset manufacturers capturing system-level margins, specialized lens fabricators supplying precision optics modules, and materials providers controlling cyclo-olefin polymer and high-index glass substrate feedstocks. Dominant competitive moves include strategic partnerships between display integrators and optical design houses, plus backward integration into nanoimprint lithography equipment to secure waveguide yield improvements.
Among integrated headset manufacturers, Microsoft, Sony, and Google exemplify divergent strategic archetypes. Microsoft occupies the enterprise-certification tier through mixed-reality platform anchoring of defense and industrial training contracts. Sony represents the high-resolution consumer entertainment vector via OLED microdisplay integration specialization. Google sits within the ecosystem-extension tier, leveraging Android XR partnerships to project software influence into lens-integrated hardware architectures.
| Leading Market Players |
|---|
| Pico Interactive |
| HTC |
| Microsoft |
| Vuzix Corporation |
| Pimax |
| Sony |
| Lenovo |
| DPVR |
| Others |
Pricing and Supply Chain Analysis
Cyclo-olefin polymer feedstock costs transmit directly through Fresnel lens manufacturing into consumer VR headset pricing tiers, with optical-grade resin volatility compressing margins for injection-molded producers serving price-sensitive entertainment buyers while waveguide lithography yield limitations sustain premium positioning for AR clinical applications.
Pricing Analysis
Certification documentation and extended warranty bundling separate defense procurement contracts from unbundled consumer hardware sales. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and field-of-view specification, with FDA 510(k) and CE marking obligations filtering subscale suppliers from clinical tiers. Cost compression in mass-market Fresnel production intensifies because of petrochemical input volatility. Entertainment companies exhibit highest price sensitivity; defense training contractors accept premium specifications with full service integration.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gates concentrate qualified lens supply among German precision optics clusters and Japanese diffractive element manufacturers. High-index glass substrates and nanoimprint lithography equipment draw from legacy camera lens and semiconductor supply chains concentrated in Germany, Japan, and Taiwan. Single-source vulnerability runs through precision molding tool fabrication for surface-relief gratings. Distribution runs through integrated headset manufacturers capturing system-level margins rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around waveguide yield capabilities and clinical certification investments, with nanoimprint lithography yield limitations and EU MDR compliance burdens forcing subscale Fresnel producers toward exit or acquisition.
For Market Incumbents: Anchor defense and industrial training platform relationships through turnkey immersive system bundling that captures margin from scenario content and certification documentation. Pursue backward integration into nanoimprint lithography equipment to secure waveguide yield improvements against emerging display integrators in China. Counter Sony's OLED microdisplay integration specialization with embedded real-time luminance monitoring firmware for EU MDR Article 10 compliance. For New Entrants and Emerging Players: FDA 510(k) clearance pathway compression in the United States opens a window for telemedicine AR lens developers targeting extended clearance timelines that filter established suppliers. Target mid-tier education institution procurement balancing immersion quality against budget constraints, where certification requirements remain lighter than healthcare applications. Pursue geographic expansion through NMPA alignment for Asia-Pacific healthcare market access rather than competing directly in saturated consumer VR entertainment channels. For Investors and Strategic Acquirers: Waveguide module procurement acceleration from defense aviation contractors is the leading indicator that premium optical capabilities are consolidating toward qualified vendors with extended field-of-view documentation. Position acquisition screening around precision optics fabricators with existing CE marking technical documentation and post-market surveillance systems for near-eye medical devices. Monitor EU MDR vigilance system implementation costs as the inflection signal distinguishing viable clinical AR suppliers from subscale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Yield Improvement Investment | Nanoimprint lithography process development at sub-60% yield compresses cost structures toward consumer AR price points. |
| Clinical Certification Pathway Alignment | FDA 510(k) and EU MDR CE marking investments filter competition and validate premium pricing in surgical training applications. |
| Defense Platform Integration Partnership | Turnkey immersive system bundling with aviation and military contractors captures margin from content and certification documentation. |
| Pancake Optics R&D Convergence | Folded optical path designs with polarized beam splitters enable sub-25mm form factors for next-generation VR headsets. |
| Optical Design Talent Acquisition | Computational optics recruitment from legacy camera lens and semiconductor lithography veterans addresses capability scarcity. |
Research Methodology
SEC 10-K filings, EMA medical device registration databases, and NMPA near-eye display standards formed the secondary backbone, supplemented by customs trade data tracking cyclo-olefin polymer and high-index glass substrate flows. Primary interviews with optical design engineers, defense procurement officers, hospital biomedical equipment committees, and nanoimprint lithography equipment specialists validated technical assumptions. Bottom-up lens unit shipment estimates by product type and top-down headset production forecasts triangulated market sizing across the analysis window.
Historical trendline analysis of Fresnel lens volume placements and waveguide module procurement cycles established baseline growth patterns. The forecast framework modeled technology adoption, application certification requirements, end-user procurement authority, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate synthesis incorporating optical waveguide manufacturing yield trajectories and healthcare reimbursement pathway validation timelines.
The model assumes a particular technology adoption path; alternative pathways for surface-relief grating waveguides achieving volume yield breakthrough would alter the outlook substantially. Forecasts reflect assumptions regarding defense training budget continuity and EU MDR implementation stringency. A model refresh is warranted upon material change in nanoimprint lithography yield rates or FDA telemedicine device clearance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Middle East and Africa Tunable Laser Market
Optics
Polymeric Optical Fiber Market
Optics
Beam Combining Optics Market
Optics
India Laser Market
Optics
Collimating Lens Market
Optics
Optical Wavelength Service Market
Optics
Fiber Optical Receivers Market
Optics
Advanced Optics Market
Optics
Fiber Optic Preform Market
Optics
Photonics Market
Optics
Optical Microscope Market
Optics
Beam Expanders Market
Optics
Optical Profilometer Market
Optics
Fiber Optic Amplifier Market
Optics
Optical Imaging Market
Optics
Optical Lens for Mobile Phone Market