
 Feed Binders Market | 2026-2036
Feed Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Binders Market Analysis
ISO 22000 certification for feed safety management is bifurcating the competitive landscape into qualified and non-qualified suppliers. Cargill Incorporated leverages its integrated supply chain from grain origination to binder formulation, sustaining cost advantages across multiple geographies. BASF SE anchors its position through synthetic polymer binders engineered for high-shear pelleting lines, while Borregaard AS specializes in lignin-based solutions derived from sustainable wood pulping operations.
Feed binders are adhesive compounds, typically comprising lignosulfonates, starches, clays, or synthetic polymers, that agglomerate feed ingredients into durable pellets withstand mechanical handling and water immersion without disintegration. Pellet durability indices above 95% reduce feed waste in automated delivery systems and improve conversion ratios in intensive livestock operations. Clay and lignin variants occupy mature volume positions in ruminant feed applications where cost sensitivity dominates procurement decisions, while guar gum commands premium positioning in aquaculture diets requiring high water stability. Powder and liquid forms are gaining traction among feed manufacturers retrofitting existing mixing equipment rather than investing in dedicated pelleting lines.
The FDA Center for Veterinary Medicine and the EU Feed Hygiene Regulation impose stringent contaminant limits and traceability requirements that elevate compliance costs for binder suppliers seeking market access. BIS certification requirements in India and evolving GB standards in China add further layering of national conformity assessment protocols. Stakeholders must monitor how tightening mycotoxin thresholds and sustainability disclosure mandates in the EU Green Deal reshape raw material sourcing strategies and product qualification timelines.
Market Dynamics
ISO 22000 certification requirements are bifurcating supplier qualification timelines, forcing feed manufacturers to consolidate binder procurement around audited supply chains while non-certified producers lose access to regulated end-use channels.
Growth Catalysts
- Aquaculture diet transition:Vietnamese and Indonesian shrimp farmers are abandoning mash feeds for pelleted formulations requiring specialized water-stable binders. This shift intensifies procurement of guar gum and modified starches.
- EU Feed Hygiene Regulation:Tighter mycotoxin thresholds and traceability mandates are accelerating replacement of unqualified binder sources with certified suppliers holding documented supply chain controls.
- High-shear pelleting lines:Synthetic polymer binders engineered for extrusion temperatures above 120°C are penetrating intensive poultry operations in Brazil and Thailand where throughput rates dominate equipment selection.
Market Restraints
- Guar seed price volatility:Indian monsoon variability and speculative commodity trading create input cost spikes that compress margins for aquaculture-focused binder formulators.
- Lignosulfonate supply concentration:Scandinavian wood pulping operations control 70% of technical lignin output, exposing ruminant feed producers to single-source geographic risk.
- Clay binder performance ceiling:Bentonite and sepiolite variants cannot achieve pellet durability indices above 92%, limiting penetration in automated delivery systems requiring 95%+ mechanical integrity.
Strategic Opportunities
- India BIS certification gap:Domestic feed compounders face 18-24 month qualification timelines for imported binders, creating first-mover advantage for local production facilities achieving in-country certification.
- EU Green Deal sustainability disclosure:Mandatory Scope 3 emissions reporting is elevating procurement preference for lignin-based binders with verified carbon-negative pulping credentials.
- Liquid binder retrofit channel:Powder-to-liquid conversion systems allow feed mills to bypass capital-intensive pelleting investments while achieving pellet quality through post-extrusion spraying.
Industry Challenges
- Feed safety auditor scarcity:Qualified ISO 22000 lead auditors with feed-specific expertise command premium rates, extending supplier certification cycles and delaying market access.
- Legacy mixing equipment incompatibility:Retrofitting 1980s-era horizontal mixers for liquid binder application requires mechanical redesigns that disrupt continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Binders Market |
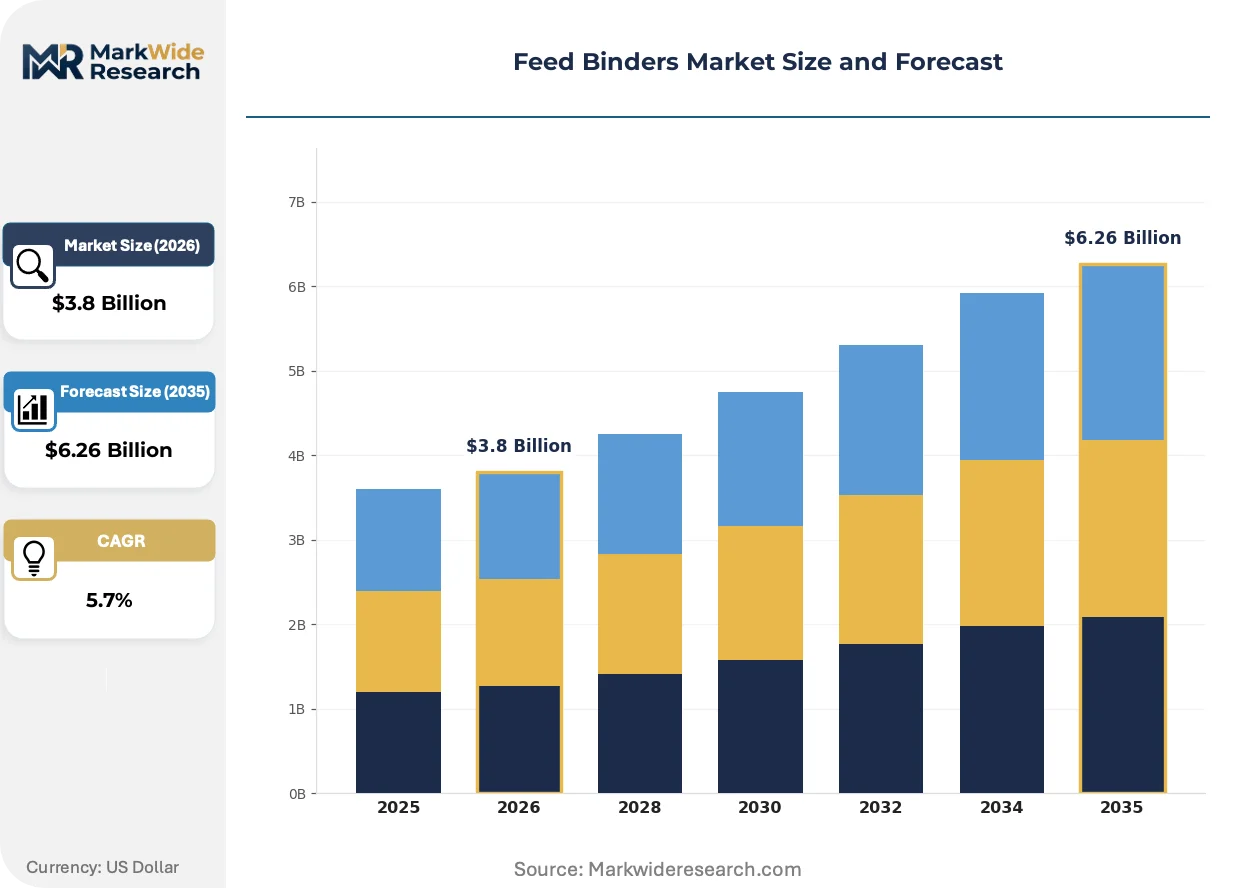
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Binder Type: Clay, Lignin, Starch, Guar Gum Application: Poultry Nutrition, Ruminant Feed, Aquaculture, Swine Nutrition Form: Granular, Powder, Liquid, Pellets End User: Feed Manufacturers, Livestock Producers, Pet Food Companies, Aquafarmers |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, DuPont, Darling Ingredients, Alltech, BASF SE, Borregaard AS, The Emsland Group, CP Kelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Binders Market Emerging Trajectories
Bio-based polymer engineering and precision feed manufacturing are converging to redefine binder performance specifications across species-specific formulations.
Enzymatically modified starches with enhanced amylopectin branching are displacing conventional corn and tapioca binders in salmonid diets. Norwegian and Chilean aquafeed producers are adopting these variants at commercial scale. The displacement is compressing commodity starch margins while rewarding suppliers with in-house enzymatic processing capabilities.
REACH authorization requirements for formaldehyde-based binder intermediates are forcing reformulation of urea-formaldehyde resins used in ruminant mineral blocks. German compounders face substance evaluation deadlines that eliminate legacy chemistries from approved ingredient lists. Lignosulfonate and protein-based alternatives are capturing reformulation volumes as ECHA compliance deadlines approach.
Integrated feed-binder procurement contracts are consolidating supplier relationships among Southeast Asian shrimp feed producers. Vietnamese and Indonesian compounders are abandoning spot-market purchasing for annual volume commitments with technical support provisions. This behavioral shift is most visible among vertically integrated aquaculture groups operating hatchery-to-harvest operations requiring feed security guarantees.
Feed Binders Market Segmentation
Feed binder procurement patterns diverge sharply across species requirements, regulatory exposure, and equipment compatibility. Manufacturers configure product portfolios around these fractures to defend margin positions against substitute materials.
Binder Type:
Clay and starch variants face the most acute substitution pressure from bio-based polymers in premium aquaculture formulations, while lignin and guar gum maintain defensive moats through performance specifications.
- Clay:Bentonite and sepiolite compositions deliver cost-efficient pellet cohesion for ruminant mineral blocks and broiler mashes. Brazilian and Indian compounders dominate procurement volumes where price sensitivity overrides durability thresholds below 92% pellet integrity indices.
- Lignin:Technical lignosulfonates derived from Scandinavian kraft pulping operations provide water-resistant binding for extruded aquafeeds and mineral supplements. EU Green Deal procurement preferences are elevating demand for carbon-negative pulping credentials in Dutch and German feed operations.
- Starch:Native and modified corn, tapioca, and wheat derivatives serve as the default binder in cost-optimized poultry and swine diets across Southeast Asian integrated operations.
- Guar Gum:Galactomannan polysaccharide extracted from Indian legume crops commands premium positioning in shrimp and salmonid feeds requiring extended water stability.
Clay anchors the volume base while guar gum gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity livestock formulations from precision aquaculture diets where binder specifications determine feed conversion economics.
- Poultry Nutrition:High-throughput broiler and layer operations in Thailand and Brazil prioritize synthetic polymer binders compatible with extrusion temperatures exceeding 120°C. Automated delivery systems mandate pellet durability above 95% to minimize waste in mechanized feeding lines.
- Aquaculture:Vietnamese shrimp farmers and Norwegian salmon producers require water-stable binders preventing pellet disintegration during extended immersion. Guar gum and modified starch variants dominate this specification-intensive segment.
- Ruminant Feed:Cattle and dairy operations in Argentina and New Zealand rely on clay and lignin binders for mineral block cohesion and total mixed ration pellet integrity.
- Swine Nutrition:Sow and grower-finisher diets in China and Spain employ starch-based binders balancing pellet hardness against palatability requirements for high-intensity production systems.
Poultry nutrition generates the largest absolute tonnage while aquaculture expands most quickly.
Form:
Equipment retrofit economics are reshaping form factor preferences among feed manufacturers avoiding capital-intensive pelleting investments.
- Powder:Standard dry-mix incorporation remains dominant in legacy horizontal mixer installations across Midwestern US and Eastern European compounders.
- Liquid:Post-extrusion spraying systems allow feed mills to achieve pellet quality without dedicated pelleting lines. Brazilian and Indonesian producers are retrofitting 1990s-era equipment with liquid application skids.
- Granular:Intermediate particle size reduces dust generation during pneumatic conveying in Vietnamese and Bangladeshi aquafeed plants.
- Pellets:Pre-agglomerated binder concentrates serve specialized mineral block manufacturers in Australian and South African ruminant feed operations.
Powder maintains installed base dominance while liquid climbs the fastest.
End User:
Customer type determines technical service intensity and contract structure, from spot purchasing by smallholders to integrated procurement by multinational aquaculture groups.
- Feed Manufacturers:Commercial compounders in Vietnam, Indonesia, and India consolidate annual volume commitments with technical support provisions. ISO 22000 certification requirements are disqualifying non-audited binder suppliers from qualified vendor lists.
- Aquafarmers:Vertically integrated shrimp and finfish operators from hatchery through harvest demand feed security guarantees and documented supply chain controls. Thai and Ecuadorian groups are shifting from spot-market purchasing to strategic partnerships.
- Livestock Producers:Cattle, swine, and poultry operations in Argentina and Poland purchase binders through distributor networks or cooperative procurement structures.
- Pet Food Companies:Premium dry kibble manufacturers in Italy and Germany specify palatability-enhancing binders with clean-label positioning for human-grade ingredient claims.
Feed manufacturers anchor procurement volumes while aquafarmers are consolidating supplier relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed binder procurement concentrates among aquafeed compounders in Southeast Asia, integrated poultry operations in Brazil, and ruminant feed manufacturers in the European Union. These buyer archetypes drive divergent specification requirements across geographies.
Vietnam
Mekong Delta shrimp farmers are accelerating pelleted feed adoption, intensifying demand for water-stable guar gum and modified starch binders. The Ministry of Agriculture and Rural Development enforces Decree 08/2022/ND-CP on feed safety management, requiring documented supply chain controls. Binh Duong Province hosts concentrated aquafeed manufacturing clusters where compounders are consolidating annual volume commitments with technical support provisions.
Brazil
Integrated broiler and layer operations in São Paulo and Paraná states prioritize synthetic polymer binders compatible with high-shear extrusion above 120°C. MAPA (Ministry of Agriculture, Livestock and Food Supply) regulates feed additive safety through Normative Instruction No. 15. The Sorocaba feed manufacturing corridor is retrofitting 1990s-era mixing equipment with liquid binder application skids to bypass capital-intensive pelleting investments.
Germany
Dutch and German compounders are elevating procurement preference for lignin-based binders with verified carbon-negative pulping credentials under EU Green Deal sustainability disclosure mandates. ECHA substance evaluation deadlines are eliminating formaldehyde-based binder intermediates from approved ingredient lists. Lower Saxony's ruminant feed manufacturing belt is capturing reformulation volumes as REACH authorization requirements force urea-formaldehyde resin substitution.
India
Domestic feed compounders face 18-24 month BIS certification timelines for imported binders, creating first-mover advantage for local production facilities achieving in-country qualification. Guar seed price volatility from Rajasthan and Gujarat growing regions compresses margins for aquaculture-focused formulators. The Haryana-Punjab dairy belt maintains heavy reliance on clay and lignin binders for total mixed ration pellet integrity where cost sensitivity dominates procurement decisions.
Indonesia
Javanese shrimp feed producers are abandoning spot-market purchasing for integrated procurement contracts with documented supply chain controls. The National Agency of Drug and Food Control regulates feed additive safety through BPOM standards. Surabaya's aquafeed manufacturing hub is expanding pellet binder procurement as farmed shrimp output climbs and farmers shift from mash to pelleted diets.
Feed Binders Market Vendor Landscape
Player mix skews toward diversified agribusiness conglomerates with captive grain origination capabilities, specialty chemical manufacturers with polymer engineering competencies, and regional compounders with localized certification advantages. Strategic archetypes include integrated supply chain operators sustaining cost advantages across multiple geographies, synthetic polymer specialists engineering for high-shear pelleting specifications, and lignin-based solution providers leveraging sustainable wood pulping credentials. Dominant competitive moves center on backward integration into raw material sourcing and geographic expansion through in-country certification achievement.
Among diversified agribusiness operators, Cargill Incorporated and Archer Daniels Midland Company exemplify integrated supply chain archetypes with grain origination-to-binder formulation capabilities. BASF SE and Borregaard AS occupy distinct specialization positions, with the former representing synthetic polymer engineering competencies and the latter anchoring lignin-based sustainable sourcing credentials. These four entities illustrate how competitive positioning fragments across cost-driven integration strategies versus performance-driven material science differentiation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| DuPont |
| Darling Ingredients |
| Alltech |
| BASF SE |
| Borregaard AS |
| The Emsland Group |
| CP Kelco |
| Others |
Supply Flow & Price Mechanics
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, forcing feed manufacturers to pay premiums for audited supply chains while non-certified producers face exclusion from regulated procurement channels. This bifurcation concentrates pricing power among qualified suppliers serving Vietnamese aquafeed compounders and German ruminant feed operations.
Pricing Analysis
Cost-plus contracts with guar seed indexation dominate procurement between Indian formulators and Southeast Asian aquafeed producers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified lignin binders from commodity clay variants. Cost compression in standard-tier starch binders is intensifying because enzymatic processing investments raise fixed-cost barriers. Smallholder livestock producers in Argentina exhibit highest price sensitivity, while vertically integrated Norwegian salmon groups accept premium positioning for water-stable formulations.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for Scandinavian lignosulfonate shipments to Indian compounders. Supply concentrates in Norway, India, and Brazil, with technical lignin drawing from Scandinavian kraft pulping, guar gum resting on Rajasthan agricultural output, and bentonite anchored in domestic mining operations. Single-source vulnerability pervades the lignosulfonate segment where 70% of output originates from geographically concentrated wood pulping. Distribution runs through integrated feed-binder procurement contracts with annual volume commitments rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feed binders market sits in early-cycle expansion as Vietnamese and Indonesian shrimp farmers accelerate pelleted feed adoption, creating sustained procurement growth for water-stable binder formulations.
For Market Incumbents: Compound certification advantages by achieving BIS qualification in India before import timelines tighten further. Defend margin positions through backward integration into guar seed origination in Rajasthan and Gujarat, countering commodity price volatility that threatens aquaculture-focused formulators. Prioritize liquid binder retrofit channels in Brazil and Indonesia where feed mills seek pellet quality without capital-intensive pelleting investments.
For New Entrants and Emerging Players: BIS certification fast-tracks create first-mover advantage for domestic Indian production facilities, exploiting 18-24 month qualification barriers facing imported binders. Target the liquid binder retrofit segment in Indonesian aquafeed plants where 1990s-era mixing equipment demands post-extrusion spraying solutions. Pursue partnerships with vertically integrated Thai shrimp groups shifting from spot purchasing to strategic supply guarantees.
For Investors and Strategic Acquirers: EU Green Deal sustainability disclosure mandates reshape the acquisition landscape toward lignin-based suppliers with verified carbon-negative pulping credentials. Long-term viability centers on feed safety auditor networks and ISO 22000 certification infrastructure serving regulated procurement channels. Watch for REACH authorization deadlines eliminating formaldehyde-based chemistries as the signal for reformulation-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Seed Origination | Captive supply from Rajasthan growing regions insulates margins against monsoon-driven price spikes. |
| ISO 22000 Certification Achievement | Audited supply chain status unlocks qualified vendor lists at Vietnamese aquafeed compounders. |
| Liquid Binder Application System Deployment | Post-extrusion spraying retrofits bypass capital barriers for Indonesian feed mill upgrades. |
| Carbon-Negative Pulping Credential Verification | Verified lignin sourcing satisfies EU Green Deal Scope 3 disclosure mandates for Dutch compounders. |
| In-Country Production Facility Establishment | Domestic Indian manufacturing circumvents BIS import timelines and captures first-mover certification advantage. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with feed manufacturing procurement directors, aquafeed compounder technical managers, and lignin supplier sustainability officers; and secondary validation through customs trade data, EU Feed Hygiene Regulation compliance filings, and BIS certification records. Bottom-up demand modeling triangulated against top-down supply capacity assessments across Norwegian pulping operations and Indian guar processing facilities.
Across the analysis window, forecasts incorporated binder type segmentation by performance tier, application segmentation by species-specific durability requirements, and form factor segmentation by equipment compatibility constraints. CAGRs derived from production capacity expansion timelines and adoption curves for pelleted aquafeed diets. Key inputs included Vietnamese shrimp farm pelleted feed conversion rates and Brazilian poultry operation extrusion temperature specifications.
Decision-makers should treat outputs as directional under sustained aquaculture diet transition and stable regulatory enforcement intensity; material deviation would warrant model refresh. Specific risk factors include Indian monsoon variability affecting guar seed supply and ECHA substance evaluation accelerating formaldehyde-based binder phase-outs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Agricultural Coatings Market