
 Gibberellins Market | 2026-2036
Gibberellins Market Size, Share, and Industry Trends Forecast 2026-2036
Gibberellins Market Analysis
Chinese agrochemical manufacturers is hardening capacity for gibberellic acid fermentation, tightening global supply availability. Syngenta AG leverages integrated seed-and-plant-health platforms to bundle gibberellin treatments with hybrid crop portfolios. BASF SE anchors European demand through precision-dosing formulation technologies that reduce application rates. Bayer AG competes on biologicals convergence, positioning gibberellins within integrated crop nutrition programs.
Gibberellins comprise a class of tetracyclic diterpenoid plant hormones, with GA3 (gibberellic acid) representing the most commercially produced variant through submerged fermentation of Fusarium fujikuroi. These compounds function as growth promoters that stimulate stem elongation, seed germination, and fruit setting across temperate and subtropical crops. Liquid formulations dominate commercial channels due to ease of tank-mixing with foliar nutrition programs, while powder and granular forms retain share in developing-market direct-sales networks. The seed germination application commands the largest volume pool, though fruit development applications generate superior per-hectare margins in premium horticulture segments.
The EPA regulates gibberellin tolerances under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU's EFSA enforces Maximum Residue Limits under Regulation 396/2005, shaping formulation standards and export compliance costs. China's Ministry of Agriculture and Rural Affairs oversees pesticide registration under NY/T standards, creating divergent approval timelines that fragment market access. India's Central Insecticides Board mandates BIS certification for imported active ingredients, adding procedural layers for foreign suppliers. Stakeholders must monitor regulatory divergence on biological-versus-synthetic classification, as this determination will reshape competitive positioning across major producing regions.
Market Dynamics
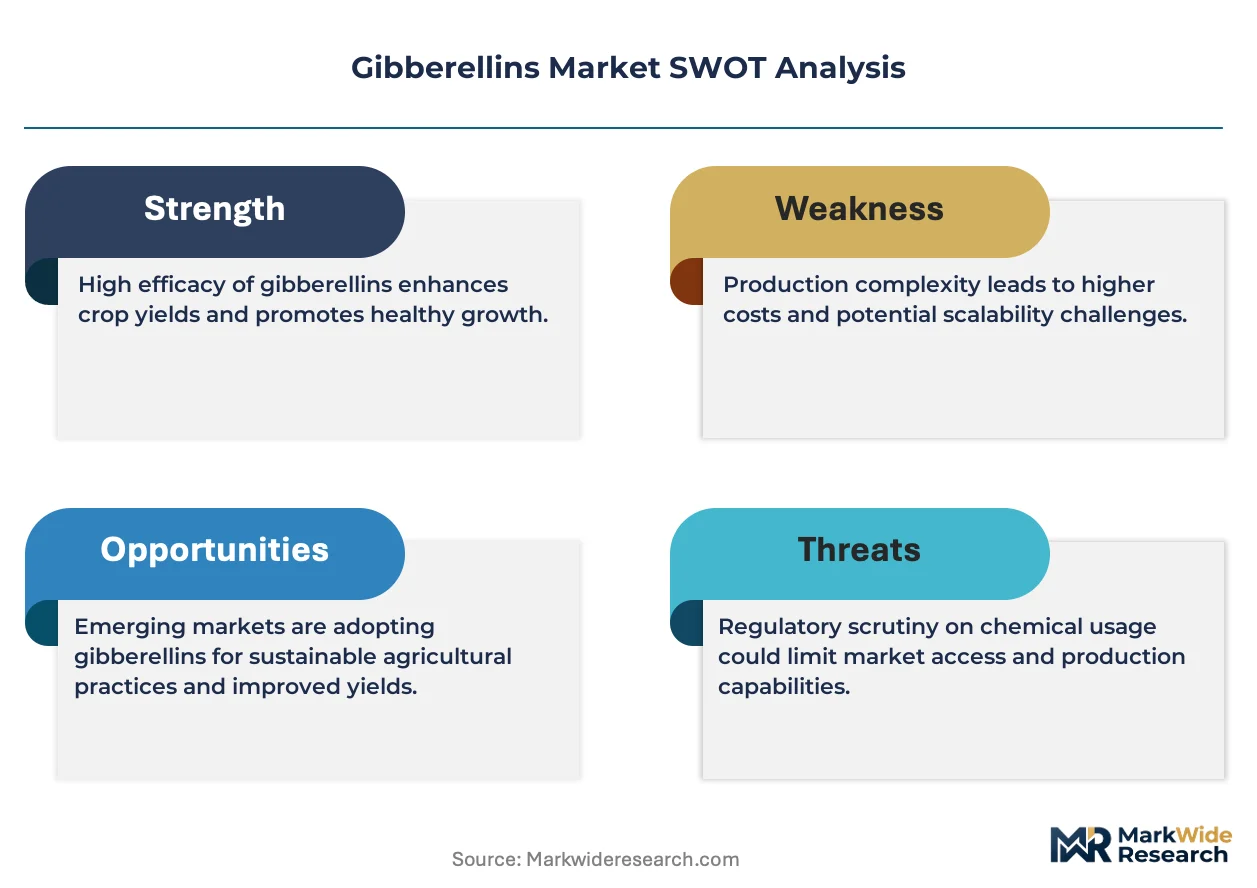
The EU's Sustainable Use of Pesticides Regulation is compressing residue limits and forcing reformulation investments across the entire supply chain. This regulatory pressure is reshaping competitive positioning by advantaging producers with precision-dosing capabilities and bio-based development pipelines.
Growth Catalysts
- Protected greenhouse expansion:China's Shandong province is scaling controlled-environment agriculture, concentrating gibberellin procurement volumes among large-scale vegetable producers.
- Precision fermentation advances:Submerged fermentation of Fusarium fujikuroi is yielding higher GA3 titers, reducing unit production costs for gibberellic acid manufacturers.
- Table grape premiumization:Specialty fruit growers in Spain and Chile are expanding gibberellin applications for berry sizing to capture export market premiums.
Market Restraints
- Raw material volatility:Carbohydrate feedstock prices for fungal fermentation fluctuate with global corn and molasses markets, compressing margin stability.
- Supply concentration:Chinese agrochemical manufacturers control a disproportionate share of gibberellic acid fermentation capacity, creating single-source vulnerability.
- Regulatory fragmentation:Divergent approval timelines between China's NY/T standards, India's BIS certification, and EPA tolerances fragment market access and extend registration costs.
Strategic Opportunities
- Biological convergence:Integration of gibberellins with microbial inoculants and biostimulants is opening integrated crop nutrition program channels.
- Bio-based formulation tailwinds:The EU Green Deal and national bioeconomy strategies are incentivizing fermentation-derived alternatives to synthetic plant growth regulators.
- Direct-to-grower platforms:E-commerce channels in developing markets are disintermediating traditional agrochemical distribution, enabling margin capture by formulators.
Industry Challenges
- Fermentation scale-up expertise:Qualified bioprocess engineers capable of optimizing Fusarium fujikuroi strain performance remain scarce relative to capacity expansion plans.
- Residue compliance complexity:Meeting simultaneous EFSA Maximum Residue Limits, EPA tolerances under FIFRA, and importing country standards requires multi-jurisdictional analytical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gibberellins Market |
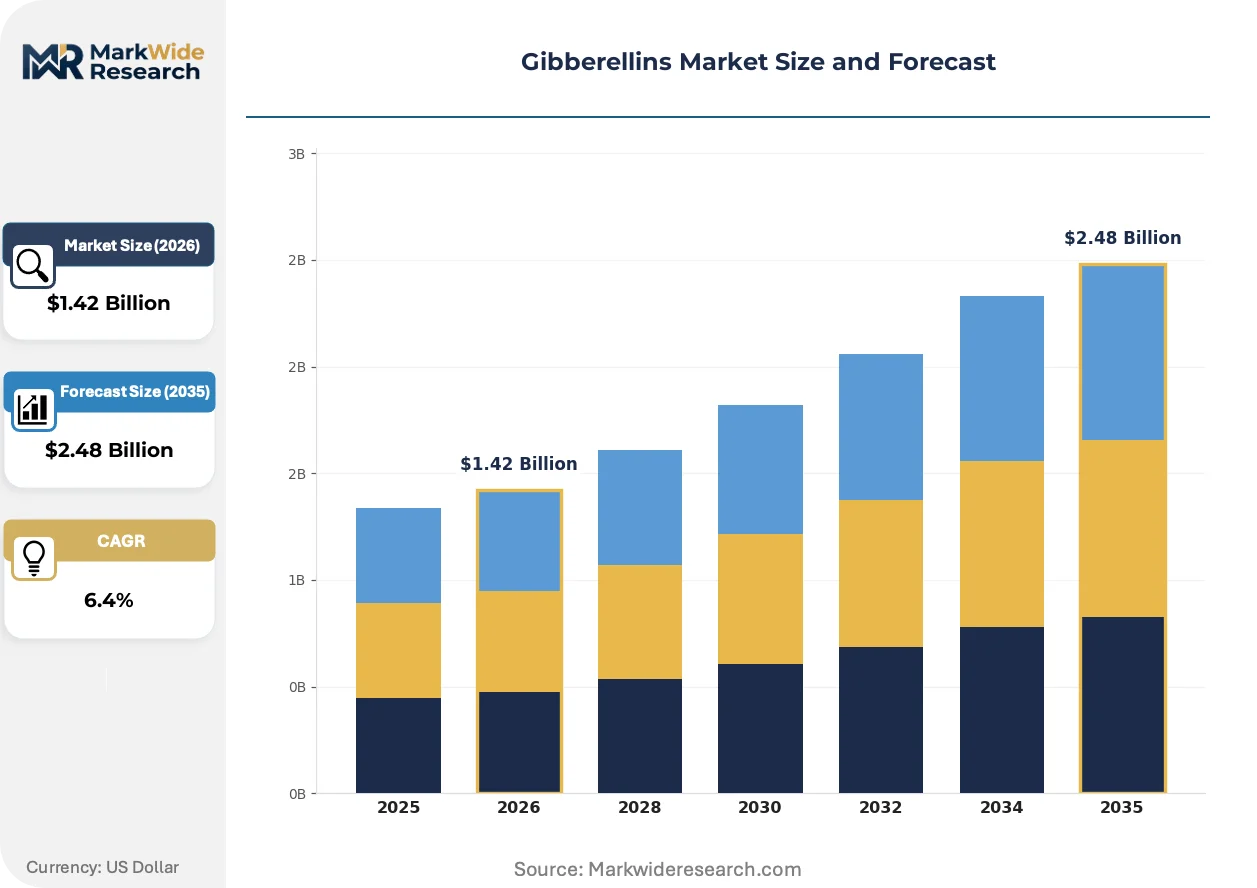
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GA3, GA4, GA7, GA8 Application: Seed Germination, Fruit Development, Flower Induction, Vegetative Growth End User: Agricultural Producers, Horticulturists, Research Institutions, Home Gardeners Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | Syngenta AG, BASF SE, Bayer AG, UPL Limited, Nufarm Limited, FMC Corporation, Valent BioSciences LLC, Fine Americas, Inc., Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gibberellins Market Emerging Trajectories
Three intersecting developments are restructuring how gibberellins are formulated, regulated, and procured. Technology convergence, policy stringency, and channel transformation are compressing legacy business models while opening new competitive terrain.
Precision-dosing formulation technology is electrifying application economics. Micro-encapsulation and controlled-release systems enable sub-gram-per-hectare gibberellin deployment. Premium horticulture segments in the Netherlands and California are adopting these systems fastest. The technology is electrifying margin structures by reducing active ingredient volumes per treated hectare while maintaining efficacy.
REACH authorization procedures and the EU's F-Gas Regulation are tightening environmental release standards for plant protection products. Formulators must now submit extended toxicity dossiers for metabolites and degradation products. Small and mid-sized suppliers without dedicated regulatory affairs teams are exiting the European market, concentrating share among integrated multinationals.
Consolidated procurement by greenhouse operator cooperatives is displacing individual grower purchasing. Large protected agriculture clusters in Shandong, Almeria, and Antalya are negotiating annual volume contracts directly with fermentation manufacturers. This pattern is most visible in China's vegetable seedling industry, where cooperative buying power has compressed distributor margins by half.
Gibberellins Market Segmentation
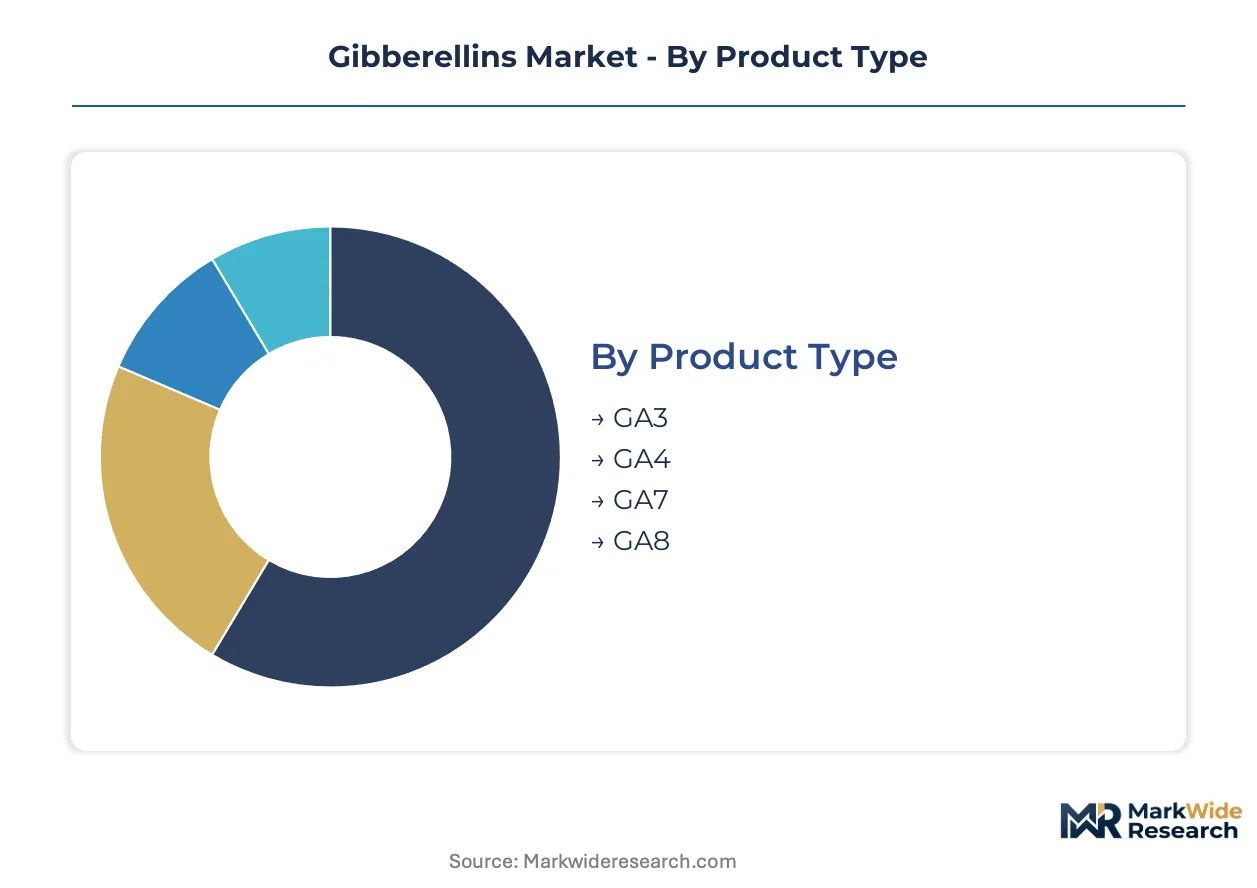
Gibberellin procurement patterns diverge sharply across product chemistries, crop applications, and user sophistication levels. Segmentation reveals where fermentation economics, formulation complexity, and regulatory compliance costs concentrate margin capture.
Product Type:
Capital intensity peaks with GA3 manufacturing, where submerged fermentation infrastructure demands the heaviest upfront bioprocessing investment.
- GA3:The dominant commercial variant produced through Fusarium fujikuroi fermentation. Chinese manufacturers in Shandong province control the bulk of installed fermentation capacity, though strain optimization investments are climbing.
- GA4:Higher-purity specification requiring additional chromatographic separation stages. Specialty apple and pear growers in Spain's Lleida region specify GA4 for flower induction protocols where residue limits under EFSA Regulation 396/2005 are tightest.
- GA7:Niche specification for research applications requiring precise hormonal ratios. Limited commercial fermentation runs restrict supply to contract manufacturing arrangements.
- GA8:Emerging fermentation target with lower titer yields than GA3. Academic partnerships in the Netherlands are advancing strain engineering to improve production economics.
Most installed capacity flows through GA3. Expansion is steepest in GA4 as premium horticulture segments demand higher-purity specifications.
Application:
Volume distribution tracks crop value chains, with margin concentration diverging from tonnage leadership.
- Seed Germination:The largest volume application across field crops and vegetable seedlings. China's protected greenhouse operators in Shandong province purchase GA3 in bulk for uniform seedling establishment, though per-hectare margins remain compressed by commodity pricing.
- Fruit Development:Berry sizing in table grapes commands premium pricing. Chilean exporters in the Atacama region apply precision-dosing protocols to capture export market differentials, generating the highest per-hectare margins in the entire gibberellin portfolio.
- Flower Induction:Citrus and pineapple growers deploy gibberellins to synchronize flowering for harvest scheduling. Brazilian citrus cooperatives are expanding application programs to manage year-round production cycles.
- Vegetative Growth:Stem elongation in ornamental production and greenhouse vegetables. Dutch ornamental propagators integrate gibberellins with climate control systems for height management.
Seed germination dominates tonnage. Fruit development is climbing fastest as export-oriented horticulture expands precision application programs.
End User:
Procurement sophistication determines formulation preference and channel access.
- Agricultural Producers:Large-scale field crop and vegetable operations purchasing through distributor networks. Cooperative buying in China's greenhouse clusters is consolidating procurement power and compressing distributor margins.
- Horticulturists:Premium fruit and ornamental specialists requiring technical support. California table grape growers and Dutch ornamental propagators specify micro-encapsulated formulations with application protocol guidance.
- Research Institutions:Universities and agricultural research stations sourcing analytical-grade materials. Limited volumes but high specification requirements sustain specialty suppliers.
- Home Gardeners:Retail-packaged tablet and powder formulations through garden center channels. E-commerce platforms in India and Brazil are disintermediating traditional retail distribution.
Agricultural producers absorb the largest volume share. Horticulturists are expanding fastest as protected agriculture and premium crop segments professionalize.
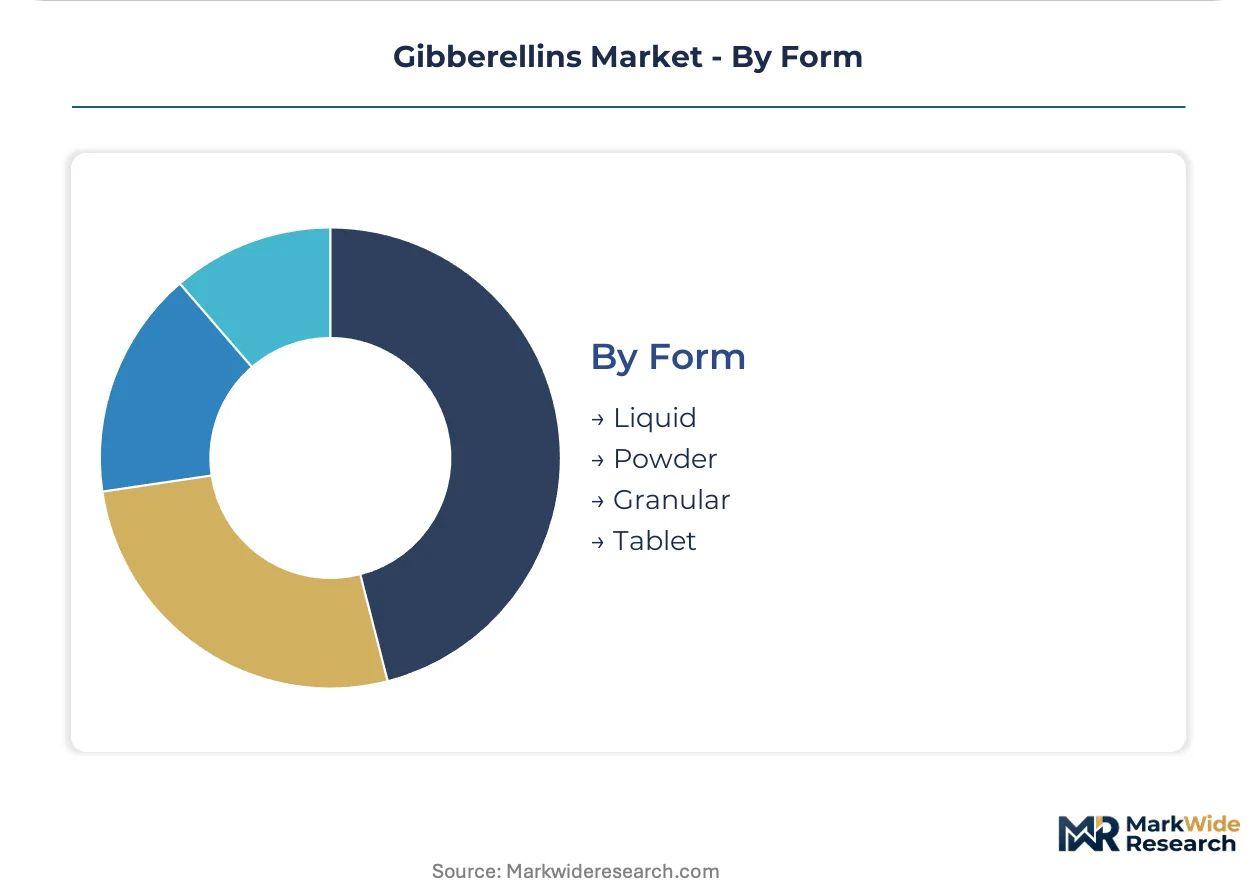
Form:
Formulation choice reflects application equipment, tank-mix compatibility, and user technical capacity.
- Liquid:Dominant commercial form enabling direct tank-mixing with foliar nutrition programs. Precision-dosing equipment in the Netherlands and California requires liquid compatibility for micro-encapsulated delivery systems.
- Powder:Retains share in developing-market direct-sales networks where water quality variability complicates liquid formulation stability. Indian horticulturists in Maharashtra and Karnataka states prefer powder for on-farm dilution control.
- Granular:Slow-release applications in soil incorporation protocols. Turf management and certain orchard systems specify granular for root-zone delivery.
- Tablet:Retail and home garden packaging format. Convenience positioning targets non-professional users with pre-measured dosing.
Liquid formulations command the largest production volume. Tablet formats are expanding most quickly through e-commerce channels targeting home gardening segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting gibberellin fermentation capacity toward jurisdictions with streamlined bioprocessing oversight. Chinese manufacturers exploit faster NY/T registration timelines to capture export orders blocked by EU REACH procedural delays.
China
Shandong province houses the dominant share of Fusarium fujikuroi fermentation infrastructure. The Ministry of Agriculture and Rural Affairs enforces NY/T pesticide standards that approve novel strains faster than Western equivalents. Qingdao and Weifang industrial clusters are expanding submerged fermentation tank farms to supply protected greenhouse operators across the province.
United States
California table grape growers deploy precision-dosing systems for berry sizing programs targeting export markets. The EPA regulates gibberellin tolerances under FIFRA, requiring residue testing protocols that add compliance overhead for imported active ingredients. Fresno County and the Central Valley concentrate domestic formulation packaging for specialty horticulture.
Spain
Lleida apple and pear specialists specify GA4 for flower induction under tight EFSA Maximum Residue Limits. The EU's Sustainable Use of Pesticides Regulation is compressing allowable residue thresholds and forcing reformulation investments. Almeria's greenhouse cooperatives are consolidating annual procurement contracts directly with fermentation suppliers.
Chile
Atacama region table grape exporters apply gibberellin protocols to capture premium pricing in North American and Asian markets. The country's national agricultural regulator enforces residue standards aligned with importing country requirements. Specialty fruit operations in Copiapó and Vallenar are scaling precision application programs for berry sizing.
India
Maharashtra and Karnataka horticulturists prefer powder formulations for on-farm dilution control in variable water quality conditions. The Central Insecticides Board mandates BIS certification for imported active ingredients, adding procedural layers for foreign suppliers. Nashik grape growers are expanding gibberellin use for export-quality fruit development.
Gibberellins Market Vendor Landscape
Chinese producers anchor the fermentation tier; European and Japanese specialists hold formulation and precision-dosing positions. The market structures around three tiers: integrated multinationals with seed-and-chemical platforms, mid-scale fermentation houses with cost advantages, and regional formulators serving protected agriculture clusters. Strategic moves concentrate on backward integration into strain optimization and geographic expansion through distributor acquisitions.
Within the integrated multinational tier, Syngenta AG and BASF SE exemplify platform bundling strategies that combine gibberellin treatments with hybrid crop portfolios and precision-dosing technologies. Bayer AG occupies a position emphasizing biologicals convergence, positioning fermentation-derived growth regulators within broader crop nutrition programs. These three anchors represent divergent responses to regulatory pressure: platform integration, formulation precision, and biological portfolio expansion.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer AG |
| UPL Limited |
| Nufarm Limited |
| FMC Corporation |
| Valent BioSciences LLC |
| Fine Americas, Inc. |
| Sumitomo Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Carbohydrate feedstock costs for Fusarium fujikuroi fermentation cascade through three pricing tiers downstream, with molasses and corn price volatility in Shandong province compressing margins at the bulk GA3 tier while precision-dosing formulations in California and the Netherlands command premium positioning.
Pricing Analysis
Distributor margins absorb the steepest compression in China's Shandong greenhouse supply chain, where cooperative buying power has halved intermediary spreads. Pricing stratifies across fermentation-grade bulk, chromatography-purified GA4, and micro-encapsulated precision formulations. Cost compression in bulk GA3 intensifies because Chinese manufacturers are expanding tank farm capacity faster than strain optimization yields improve. Agricultural producers in India's Maharashtra state exhibit highest price sensitivity, while Dutch ornamental propagators purchasing micro-encapsulated systems show least elasticity.
Supply Chain Analysis
Regional distribution centers in Qingdao and Weifang anchor hub-and-spoke patterns radiating toward protected agriculture clusters across Shandong province. Supply concentrates in China, with secondary fermentation nodes in India and formulation packaging in Spain and the United States. Raw material flows draw from global corn and molasses markets, with chromatographic resins for GA4 purification sourced from specialized chemical suppliers. Single-source vulnerability around Chinese fermentation capacity creates structural risk. Distribution runs through direct annual contracts between greenhouse cooperatives and fermentation manufacturers, displacing traditional agrochemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gibberellins market compounds steadily as protected greenhouse expansion in temperate zones sustains procurement volume growth across economic cycles.
For Market Incumbents: Anticipate regulatory divergence between EFSA Maximum Residue Limits and EPA tolerances under FIFRA by building multi-jurisdictional analytical capabilities. Backward integration into Fusarium fujikuroi strain optimization secures cost position against Chinese fermentation houses. Precision-dosing formulation investments defend margin compression from bulk GA3 commoditization. For New Entrants and Emerging Players: E-commerce platforms in India's home gardening segment offer the most penetrable white-space entry, with tablet-format retail packaging bypassing established distributor networks. Specialty GA4 supply for Spain's Lleida apple growers presents a second target, where EFSA residue stringency disadvantages bulk suppliers. Technical partnership with Dutch ornamental propagators provides credible formulation validation. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fermentation houses lack strain optimization capabilities to match Chinese cost structures. Five-to-ten year viability favors integrated platforms combining fermentation capacity with precision-dosing formulation expertise. Acquisition target archetype: European or Japanese formulators with established REACH dossiers and underutilized bioprocessing assets. Monitor EU Green Deal bioeconomy incentive disbursement velocity as inflection signal for fermentation-derived growth regulator demand.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Optimization Investment | Higher GA3 titers from Fusarium fujikuroi fermentation reduce unit production costs for Chinese manufacturers. |
| Precision-Dosing Formulation Development | Micro-encapsulation systems in the Netherlands enable sub-gram-per-hectare deployment with premium pricing. |
| Multi-Jurisdictional Registration Buildout | Parallel EPA, EFSA, and NY/T dossier preparation accelerates market access across major consuming regions. |
| Direct Cooperative Contracting | Annual volume agreements with Shandong greenhouse operators disintermediate distributor margin layers. |
| Bio-Based Formulation Transition | Fermentation-derived alternatives align with EU Green Deal incentives and tightening synthetic plant growth regulator scrutiny. |
Methodological Framework
Coverage spans China, the United States, Spain, Chile, and India, with primary inputs from each market combining interviews with fermentation plant managers, procurement leads at greenhouse cooperatives, agrochemical distribution channel partners, and technical R&D directors at formulation houses. Secondary validation draws from Chinese customs export data, EPA tolerance filings under FIFRA, EFSA Maximum Residue Limit registers, and SEC 10-K disclosures from listed agrochemical firms. Bottom-up volume modeling triangulates against top-down value estimates across the analysis window.
Granularity-level modeling disaggregates the projection horizon by product chemistry (GA3, GA4, GA7, GA8), application protocol (seed germination, fruit development, flower induction, vegetative growth), and user sophistication tier (agricultural producers, horticulturists, research institutions, home gardeners). CAGRs derive from segmented volume build-ups calibrated to greenhouse expansion trajectories and precision application adoption curves. Strain optimization yield improvements and regulatory approval timelines for novel formulations constitute key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Sustainable Use of Pesticides Regulation enforcement stringency and Chinese environmental policy shifts affecting fermentation capacity expansion. Outputs reflect documented assumptions around protected agriculture investment rates and residue limit harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
North America Feed Pigments Market