
 Middle East Feed Enzymes Market | 2026-2036
Middle East Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Enzymes Market Foresight
Project finance arrangements for greenfield feed mills are reconfiguring competitive entry in the Middle East feed enzymes space. Novozymes leverages its microbial strain library to anchor phytase supply contracts with Saudi poultry conglomerates. Adisseo competes through backward integration into methionine and enzyme premix production, sustaining margin control across the Gulf. BASF SE differentiates via granular formulation technology that withstands high-temperature pelleting common in regional feed manufacturing.
Feed enzymes are protein-based biocatalysts added to animal diets to degrade anti-nutritional factors, improve nutrient digestibility, and reduce environmental phosphorus and nitrogen excretion; phytase typically operates at pH 2.5-5.5 and temperatures up to 65°C during feed processing. Their primary commercial purpose is to unlock bound minerals and amino acids from plant-based feedstuffs, lowering formulation costs while meeting animal performance targets. Phytase dominates product type demand because phosphate release delivers the clearest cost-return calculus for poultry and swine nutritionists. Poultry leads application volume due to the region's massive broiler expansion, though aquaculture enzymes are gaining traction in Egypt's tilapia and shrimp intensive systems. Liquid formulations occupy the fastest-growing form segment as automated dosing systems penetrate modern feed mills in the UAE and Oman.
Saudi Arabia's SFDA enforces feed additive registration and maximum permitted enzyme activity levels, while the UAE's Ministry of Climate Change and Environment coordinates with GCC standardization bodies on imported feed safety protocols. These frameworks elevate compliance costs for new entrants but also create preferential access for suppliers with established regulatory dossiers. Stakeholders must monitor how Egypt's agricultural export ambitions reshape enzyme specification requirements for Nile Delta feed operations serving European-bound poultry.
Market Dynamics
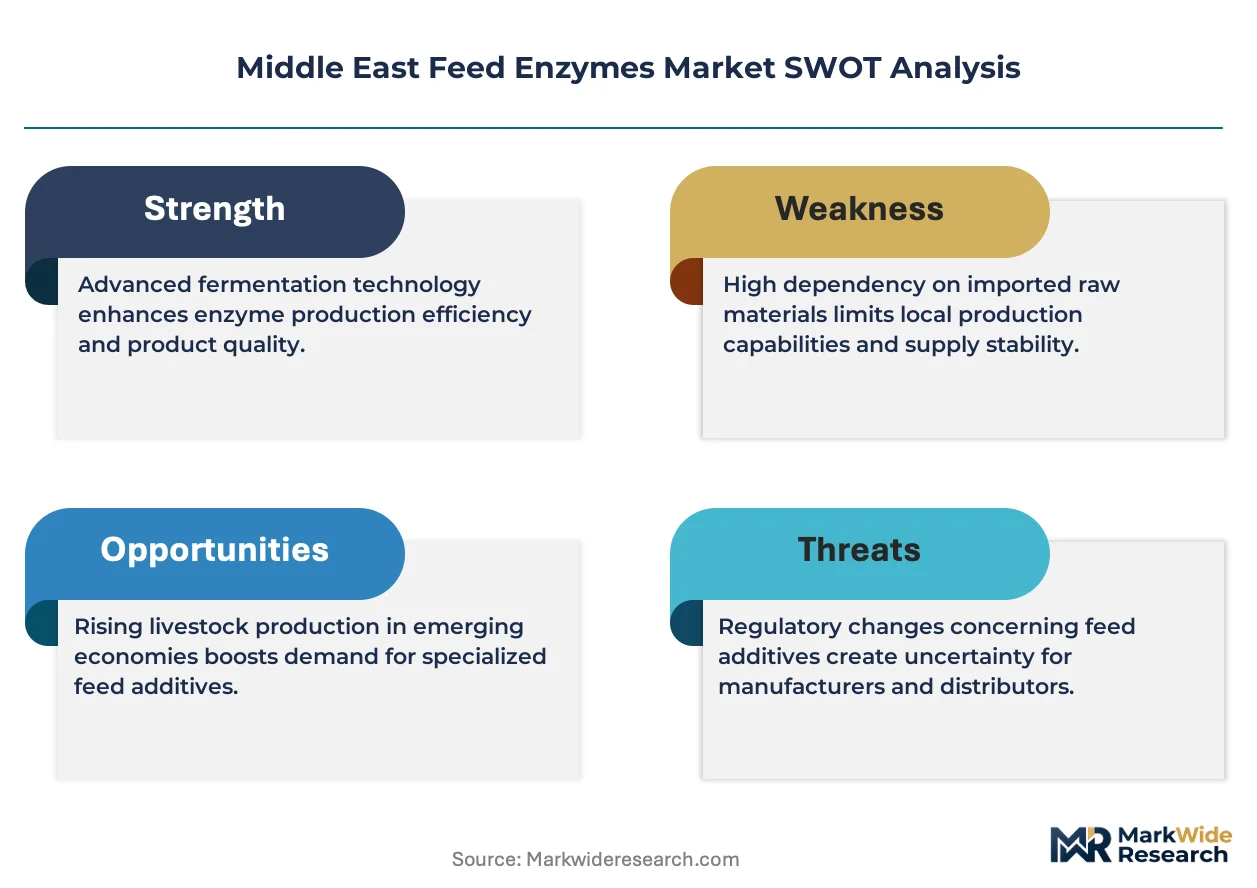
Saudi Arabia's SFDA registration tightening for feed additive imports is compressing supplier timelines while elevating quality dossier requirements, forcing enzyme manufacturers to reconfigure Gulf market entry strategies around regulatory pre-approval rather than post-arrival compliance.
Growth Catalysts
- Phytase cost-return clarity:Poultry nutritionists in Saudi vertically integrated broiler operations prioritize phosphate release metrics, embedding enzyme specifications directly into compound feed formulation software.
- SFDA additive registration:The Saudi Food and Drug Authority's mandatory pre-market enzyme activity verification creates a compliance moat that rewards dossier-ready suppliers with preferential contract access.
- Liquid dosing automation:UAE and Omani feed mills are retrofitting production lines with precision enzyme injection systems, displacing manual powder blending in facilities above 50,000 tonnes annual capacity.
Market Restraints
- Heat-stable formulation costs:Granular phytase variants capable of surviving 85°C pelleting temperatures carry 15-25% manufacturing premiums that compress margins for regional feed compounders.
- Import concentration risk:Over 70% of commercial enzyme supply routes through Jebel Ali and King Abdulaziz Port, creating single-point vulnerability during Red Sea shipping disruptions.
- Protease efficacy limits:Current commercial protease strains show inconsistent performance across sorghum-dominant rations common in Egyptian poultry operations, constraining application expansion.
Strategic Opportunities
- Egyptian aquaculture penetration:Intensive tilapia and shrimp operations in the Nile Delta remain underpenetrated by species-specific enzyme blends designed for high-plant protein aquafeeds.
- SFDA-GCC harmonization:Proposed mutual recognition protocols for enzyme registration between Saudi Arabia, UAE, and Kuwait would collapse multi-jurisdiction compliance costs for dossier holders.
- Enzyme-premix integration:Backward integration into methionine-enzyme co-formulation allows suppliers to bundle amino acid and digestibility solutions, capturing margin from separate additive categories.
Industry Challenges
- Regulatory dossier talent scarcity:Gulf feed enzyme suppliers face acute shortages of professionals fluent in SFDA technical documentation requirements and GCC standardization body protocols.
- Legacy pelleting equipment retrofit costs:Post-pelleting liquid enzyme application systems require capital outlays exceeding $400,000 per production line, slowing adoption outside greenfield mill construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Enzymes Market |
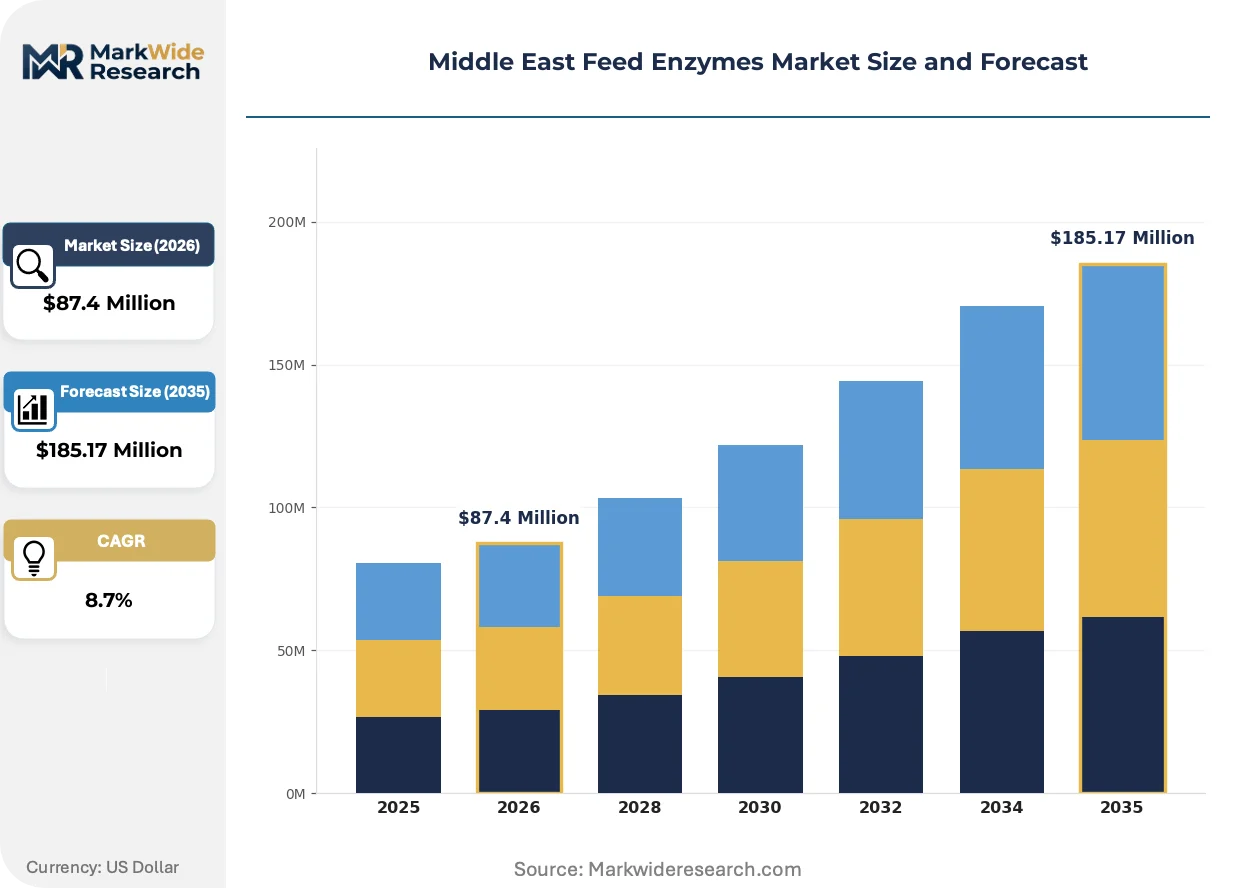
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Cellulase, Phytase, Protease Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Tablets Distribution Channel: Online, Distributors, Direct Sales, Retail |
| Companies Covered | Novozymes, Adisseo, BASF SE, Cargill Inc., Kemin Industries, DSM Nutritional Products AG, IFF (Danisco Animal Nutrition), Kerry Group Plc, Alltech, Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Enzymes Market Shifts & Advancements
Digital process control and automated dosing infrastructure are displacing manual enzyme handling across Gulf feed manufacturing, while regulatory data requirements and buyer procurement consolidation reshape competitive access patterns.
Precision liquid enzyme dosing technology is digitizing feed mill operations across the UAE and Oman. Automated injection systems measure phytase and carbohydrase activity in real-time during mash conditioning, eliminating batch-to-batch variation that plagued manual powder incorporation. Saudi poultry integrators with vertically controlled supply chains are mandating this equipment in supplier qualification audits, compressing contract windows for mills without installed dosing infrastructure.
SFDA's 2023 feed additive data integrity guidelines are tightening traceability requirements for imported enzymes. The regulation mandates blockchain-verified supply chain documentation and third-party laboratory confirmation of declared enzyme activity levels. European enzyme suppliers with established Gulf regulatory dossiers are accelerating registration renewal cycles to maintain preferential positioning before full enforcement deadlines.
Compound feed procurement in Saudi Arabia is consolidating around three-year enzyme supply agreements with performance-guarantee clauses. Poultry integrators are unbundling enzyme purchasing from broader premix contracts, creating direct supplier relationships that bypass traditional distributor markups. This disintermediation is most visible in the Central Region's large-scale broiler operations, where procurement teams now negotiate enzyme pricing separately from vitamin and mineral sourcing.
Middle East Feed Enzymes Market Segmentation
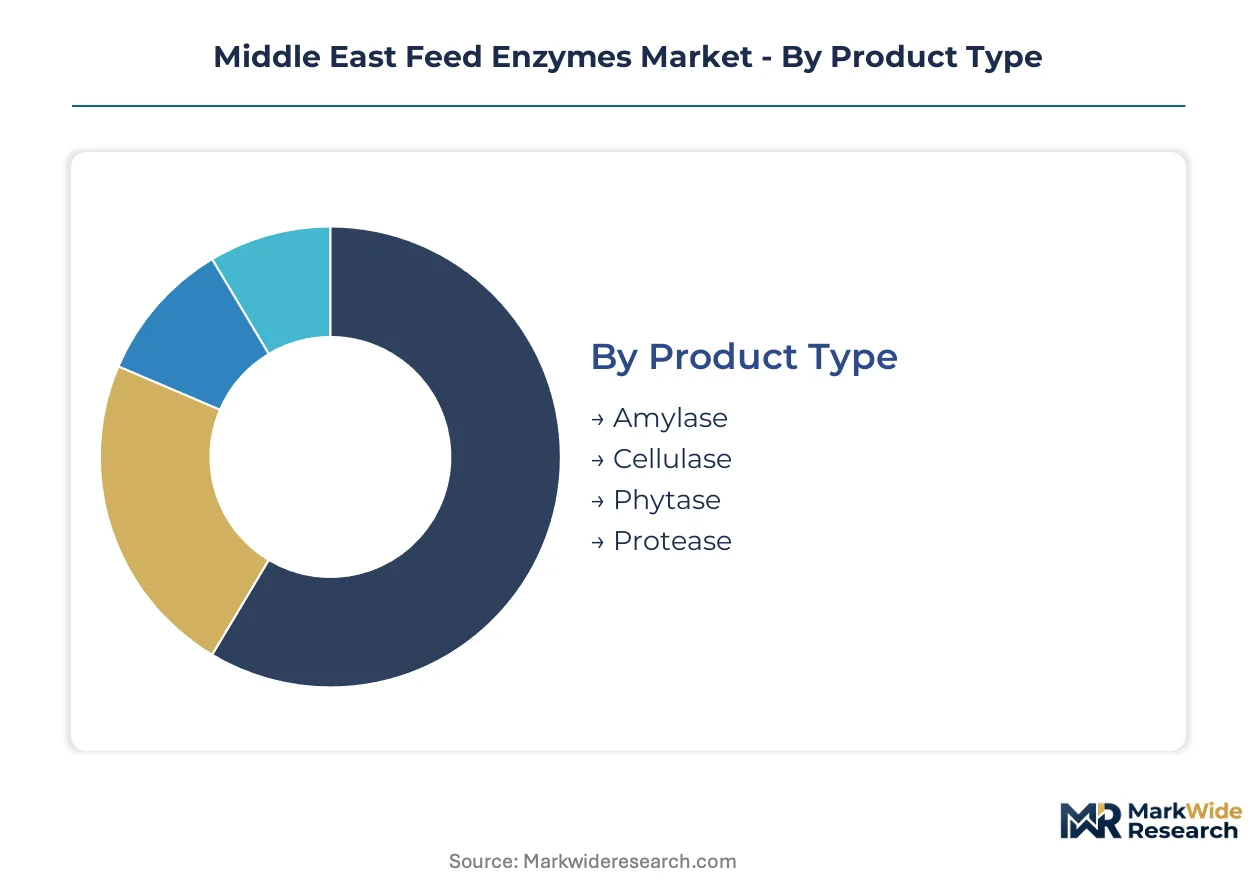
Enzyme selection in Middle East feed manufacturing follows distinct technical and commercial logics across product chemistry, target species, physical form, and procurement channels. Each segmentation dimension carries different margin profiles and regulatory exposure for suppliers serving Saudi, UAE, and Egyptian compound feed operations.
Product Type:
Enzyme selection spans hydrolytic functions from starch degradation through protein solubilization, with commercial prioritization driven by mineral release economics and heat tolerance requirements.
- Phytase:Catalytic proteins hydrolyze phytate-bound phosphorus in plant meals, releasing digestible phosphate and reducing dicalcium phosphate supplementation costs. Saudi vertically integrated broiler operations embed phytase specifications directly into formulation software, prioritizing heat-stable variants surviving 85°C pelleting. Established volume favors phytase; emerging adoption favors cellulase.
- Protease:Endo- and exopeptidases hydrolyze storage proteins in soybean and sorghum meals, improving amino acid digestibility coefficients. Egyptian poultry operations with sorghum-dominant rations show inconsistent performance response, constraining penetration outside Nile Delta soybean-based systems. Protease efficacy limits in regional feed matrices compress near-term expansion.
- Amylase:Alpha-amylase variants degrade starch polymers in wheat and corn-based rations common in UAE feed mills.
- Cellulase:Beta-glucanase and xylanase complexes target non-starch polysaccharides in barley and palm kernel meal prevalent in regional formulations.
Phytase commands formulation priority due to clearest cost-return quantification; cellulase gains traction as NSP-related gut health management intensifies.
Application:
Species-specific digestive physiology and production intensity determine enzyme ROI calculations across Middle East livestock sectors.
- Poultry:Broiler and layer operations dominate regional enzyme consumption, driven by Saudi Arabia's massive vertically integrated production complexes and UAE commercial hatchery expansion. High stocking densities and short production cycles amplify nutrient density optimization returns. Poultry anchors absolute volume; aquaculture climbs the fastest.
- Aquaculture:Intensive tilapia and shrimp systems in Egypt's Nile Delta and Saudi coastal zones increasingly deploy phytase and carbohydrase blends to manage high-plant protein aquafeed formulations. Species-specific enzyme cocktails for warm-water finfish remain underdeveloped relative to salmonid-optimized European products.
- Swine:Limited regional pork production constrains commercial relevance outside Lebanon and non-GCC markets.
- Ruminants:Dairy and feedlot operations in Saudi Arabia's Al-Kharj and UAE's Al Ain show nascent fibrolytic enzyme interest for total mixed rations.
Broiler sector procurement consolidation favors poultry-focused suppliers; aquaculture formulation complexity favors technical specialists.
Form:
Physical delivery systems determine manufacturing compatibility, dosing precision, and stability economics across Gulf feed mill infrastructure.
- Liquid:Aqueous enzyme concentrates enable automated injection during mash conditioning, eliminating batch variation inherent in manual powder blending. UAE and Omani mills above 50,000 tonnes annual capacity are retrofitting precision dosing systems, displacing dry forms in modern facilities. Liquid dosing automation accelerates penetration; granular heat stability defends legacy positions.
- Granular:Spray-dried and coated formulations withstand high-temperature pelleting common in regional feed manufacturing, carrying 15-25% manufacturing premiums that compress compounder margins. Saudi SFDA registration requirements favor established granular suppliers with verified thermal stability dossiers.
- Powder:Standard dry blends persist in smaller Egyptian and Yemeni mills lacking liquid handling infrastructure.
- Tablets:Compressed enzyme forms serve niche on-farm supplementation in remote pastoral systems with limited feed mill access.
Capital-intensive liquid infrastructure favors Gulf-based multinationals; powder and tablet forms retain relevance in fragmented North African markets.
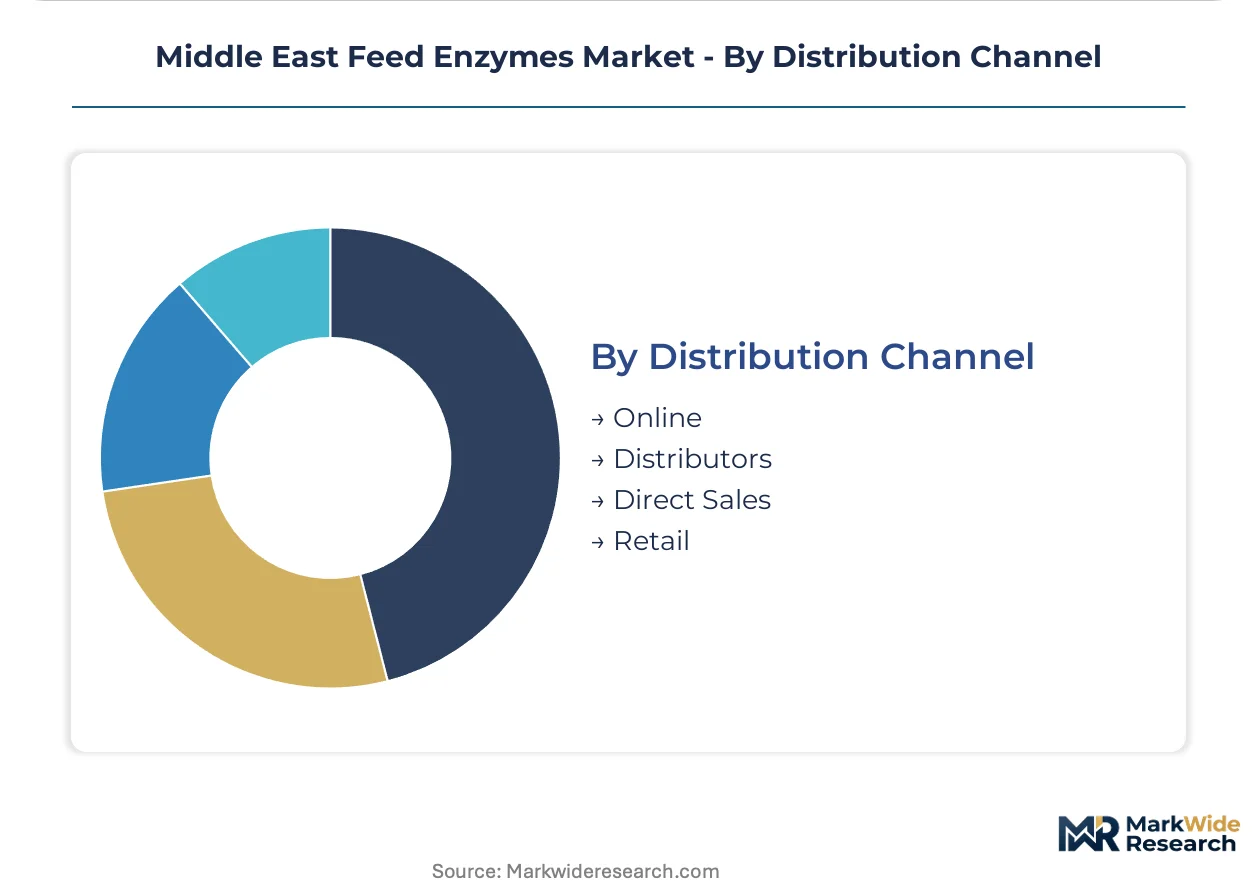
Distribution Channel:
Procurement pathway selection reflects customer scale, technical service requirements, and SFDA compliance complexity.
- Direct Sales:Enzyme manufacturers maintain dedicated technical teams serving Saudi poultry integrators with multi-year supply agreements and performance-guarantee clauses. Direct relationships bypass traditional distributor markups, compressing contract windows for intermediaries. Direct contracting concentrates in Central Region broiler operations; distributor networks defend peripheral market access.
- Distributors:Regional chemical and feed additive distributors aggregate smaller Egyptian and Jordanian compounders, bundling enzyme procurement with vitamin and mineral sourcing. Jebel Ali and King Abdulaziz Port concentration creates single-point vulnerability during Red Sea disruptions.
- Online:B2B procurement platforms gain traction among mid-sized UAE feed operations seeking price transparency.
- Retail:Veterinary and agricultural supply stores serve hobby farms and smallholder poultry operations with packaged enzyme supplements.
Procurement disintermediation favors direct supplier relationships at scale; distributor networks retain value in compliance-heavy import markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration tightening and GCC standardization initiatives are reconfiguring enzyme supply corridors across the Middle East, with Saudi Arabia and the UAE driving formulation specification upgrades while Egypt's aquaculture expansion opens adjacent demand pockets.
Saudi Arabia
Vertically integrated broiler operations in the Central Region anchor regional enzyme consumption, with Riyadh-based poultry conglomerates embedding phytase specifications directly into compound feed formulation software. SFDA mandates pre-market enzyme activity verification and blockchain-verified supply chain documentation, elevating compliance barriers for new entrants. The Al-Kharj dairy corridor shows nascent fibrolytic enzyme interest for total mixed rations.
United Arab Emirates
Commercial hatchery expansion in Dubai and Abu Dhabi sustains carbohydrase demand for high-energy broiler starter diets, while automated liquid dosing systems penetrate mills above 50,000 tonnes annual capacity. The Ministry of Climate Change and Environment coordinates with GCC standardization bodies on imported feed safety protocols, streamlining multi-jurisdiction compliance for established dossier holders. Jebel Ali's port concentration creates single-point supply vulnerability during Red Sea disruptions.
Egypt
Intensive tilapia and shrimp operations in the Nile Delta represent underpenetrated terrain for species-specific enzyme blends designed for high-plant protein aquafeeds. The country's agricultural export ambitions toward European markets are reshaping enzyme specification requirements for Delta feed operations. Alexandria and Damietta processing clusters drive procurement consolidation among mid-sized compounders seeking bundled vitamin-enzyme sourcing.
Kuwait
Proposed SFDA-GCC mutual recognition protocols for enzyme registration would collapse compliance costs for suppliers with Saudi dossiers, positioning Kuwait as a regulatory spillover beneficiary. The country's compact feed manufacturing base favors direct supplier relationships over distributor intermediation. Shuaiba's industrial zone concentrates warehousing capacity for regional enzyme redistribution.
Oman
Modernization of feed mill infrastructure in Sohar and Salalah is accelerating liquid enzyme adoption through precision injection retrofits, displacing manual powder blending in facilities serving the Sultanate's poultry sector. Port capacity expansion at Duqm is diversifying import routes away from Jebel Ali concentration. Government livestock self-sufficiency programs are expanding domestic broiler production, embedding enzyme specifications into national feed security planning.
Middle East Feed Enzymes Market Competitive Landscape
On the supply side, the industry is consolidating around multinational biocatalyst specialists with established GCC regulatory dossiers, with tiered competitive positioning separating thermal stability innovators from commodity phytase suppliers. Three archetypes dominate: microbial strain library holders leveraging proprietary discovery platforms, backward-integrated nutrition companies bundling enzymes with amino acid premixes, and formulation technology specialists differentiating via granular heat tolerance. Capacity expansion and strategic partnerships with Saudi poultry integrators represent the dominant competitive vectors.
Within the microbial platform tier, Novozymes anchors supply relationships through its strain collection capabilities, while Adisseo occupies a position linking methionine production with enzyme premix integration. BASF SE exemplifies the formulation technology archetype through granular heat-stability positioning. These three represent distinct competitive vectors: biological discovery, nutritional integration, and process engineering.
| Leading Market Players |
|---|
| Novozymes |
| Adisseo |
| BASF SE |
| Cargill Inc. |
| Kemin Industries |
| DSM Nutritional Products AG |
| IFF (Danisco Animal Nutrition) |
| Kerry Group Plc |
| Alltech, Inc. |
| Others |
Supply & Pricing Matrix
Jebel Ali's port concentration as the Gulf's primary enzyme import gateway amplifies pricing power for dossier-ready suppliers during Red Sea shipping disruptions. SFDA registration requirements compress supplier margins through compliance investment while rewarding established players with contract premiums.
Pricing Analysis
Certification level (SFDA-registered vs. non-registered) creates the primary spread between premium and standard enzyme tiers. The market operates on contract-based long-term offtake agreements with performance-guarantee clauses. Price differentiation rests on heat-stability verification and blockchain traceability documentation. Cost compression in granular phytase variants is intensifying because manufacturing premiums for 85°C pelleting tolerance compress compounder margins. Saudi vertically integrated broiler operations show least price sensitivity due to embedded formulation software specifications; Egyptian mid-sized compounders exhibit highest sensitivity.
Supply Chain Analysis
Upstream fermentation feedstocks draw from Danish, Dutch, and American microbial strain production hubs. Raw material dependencies center on corn steep liquor, yeast extracts, and pharmaceutical-grade salts for enzyme cultivation. Supply chain risk hinges on single-point vulnerability at Jebel Ali and King Abdulaziz Port during Red Sea corridor disruptions. Distribution runs through direct technical sales teams serving Saudi poultry integrators alongside regional chemical distributors aggregating smaller North African compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East feed enzymes market functions as a regulatory entrenchment story where SFDA dossier ownership creates defensible switching costs against new entrants. Network effects concentrate among suppliers with established Gulf poultry integrator relationships.
For Market Incumbents: Harden regulatory moats through accelerated SFDA registration renewal cycles before full blockchain documentation enforcement deadlines. Expand captive supply of methionine-enzyme co-formulation capacity in the Gulf to defend margin position against pure-play biocatalyst specialists. Prioritize liquid dosing automation partnerships with UAE and Omani mills above 50,000 tonnes capacity to lock in three-year supply agreements.
For New Entrants and Emerging Players: Pursue Egyptian aquaculture formulation partnerships as the most penetrable white-space target, where species-specific enzyme blends for Nile Delta tilapia remain underdeveloped. Target Saudi Al-Kharj dairy corridor fibrolytic enzyme demand as a secondary entry point with lighter regulatory burden than poultry. Lead with technical service capabilities and post-pelleting liquid application systems to bypass granular heat-stability manufacturing barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from European enzyme manufacturers with dormant GCC regulatory dossiers seeking liquidity from compliance renewal costs. Long-term viability favors suppliers with dual capabilities across microbial strain libraries and formulation technology. Watch for SFDA-GCC mutual recognition protocol announcements as the signal indicating collapsed multi-jurisdiction compliance costs and accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Dossier Acceleration | Blockchain-verified documentation secures preferential contract access with Riyadh-based poultry conglomerates. |
| Liquid Dosing Retrofit Partnerships | Precision injection system installations lock in multi-year supply agreements with UAE feed mills. |
| Backward Integration into Methionine | Captive amino acid production enables bundled pricing against separate additive category suppliers. |
| Egyptian Aquaculture Technical Launch | Species-specific blends for Nile Delta tilapia capture underpenetrated high-plant protein feed demand. |
| Granular Heat-Stability R&D Investment | 85°C pelleting tolerance defends market position in Saudi legacy feed manufacturing infrastructure. |
Research Methodology
Desk research of SFDA regulatory filings, GCC standardization body protocols, and poultry integrator annual reports preceded structured interviews with feed mill operations managers, poultry nutritionists, enzyme supplier technical directors, and port logistics coordinators. Secondary validation drew from customs trade data, compound feed production statistics, and veterinary pharmaceutical import records. Bottom-up enzyme volume estimates triangulated against top-down feed production forecasts across the analysis window.
Assumption sets held Saudi broiler expansion rates and SFDA enforcement timelines within observed patterns while varying Egyptian aquaculture penetration scenarios and Red Sea shipping disruption frequencies. Segmentation modeling spanned enzyme chemistry type, target species physiology, physical delivery form, and procurement channel structure. CAGRs derived from regression analysis against historical feed production correlations and enzyme inclusion rate trajectories. Industry-specific inputs incorporated phytase cost-return coefficients and liquid dosing automation adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian fermentation specialists or sudden SFDA-GCC harmonization would shift outcomes. Material shifts in Red Sea corridor stability or European enzyme supplier exit decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Feed Preservatives Market