
 North America Silage Additives Market | 2026-2036
North America Silage Additives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Silage Additives Market Analytics
Biological inoculant technology is narrowing the performance gap between chemical preservatives and microbial solutions across North American forage systems. Pioneer Hi-Bred International dominates seed-linked additive bundling through Corteva's distribution network. Kemin Industries leverages its Iowa manufacturing base to sustain rapid fulfillment for Midwest dairy cooperatives. Lallemand Animal Nutrition specializes in strain-specific Lactobacillus formulations that anchor premium positioning in temperature-variable climates.
Silage additives comprise chemical and biological agents applied to harvested forage to control fermentation, inhibit spoilage organisms, and preserve nutritional value for ruminant feed; typical formulations include organic acids such as propionic and formic acid at concentrations between 1-5 kg per ton of fresh forage, or bacterial inoculants delivering colony-forming units. Inoculants command expanding share as dairy operations prioritize aerobic stability and protein preservation over simple pH reduction. Dairy Feed applications generate the deepest margin pools due to volume concentration and formulation customization requirements. Enzyme-enhanced additives represent the fastest-growing product type as producers seek fiber digestibility improvements that translate to measurable milk yield gains.
The EPA regulates pesticide and antimicrobial claims on silage preservatives under FIFRA, while the FDA's Veterinary Feed Directive framework shapes how medicated or growth-promoting additives enter ruminant rations; state-level departments of agriculture in Wisconsin and California impose additional testing and labeling requirements that raise compliance costs for interstate suppliers. USDA conservation programs indirectly stimulate additive demand by subsidizing cover-crop-to-silage transitions that require preservation expertise. Stakeholders must monitor how FDA guidance on antibiotic alternatives redirects R&D budgets toward competitive biological solutions.
Market Dynamics
Biological inoculant formulations are displacing chemical preservatives across North American dairy operations as EPA scrutiny of antimicrobial residues intensifies and producers prioritize protein preservation over simple pH reduction. This technology transition is compressing margins for acid-based suppliers while rewarding strain-specific microbial developers.
Growth Catalysts
- USDA Conservation Programs:Subsidized cover-crop-to-silage transitions in the Midwest require specialized preservation expertise, driving additive bundling with agronomic services.
- FDA Veterinary Feed Directive:Restrictions on medicated feed additives redirect R&D investment toward competitive biological alternatives that bypass antimicrobial classification.
- Wisconsin and California dairy consolidation:Large-scale operations in these states generate volume procurement of customized additive blends with embedded technical support.
Market Restraints
- Propionic acid price volatility:Chemical preservative input costs fluctuate with petroleum derivatives, squeezing margin stability for traditional formulation suppliers.
- Midwest supplier concentration:Iowa and Minnesota manufacturing clusters create geographic dependency risk for rapid fulfillment to Great Plains cooperatives.
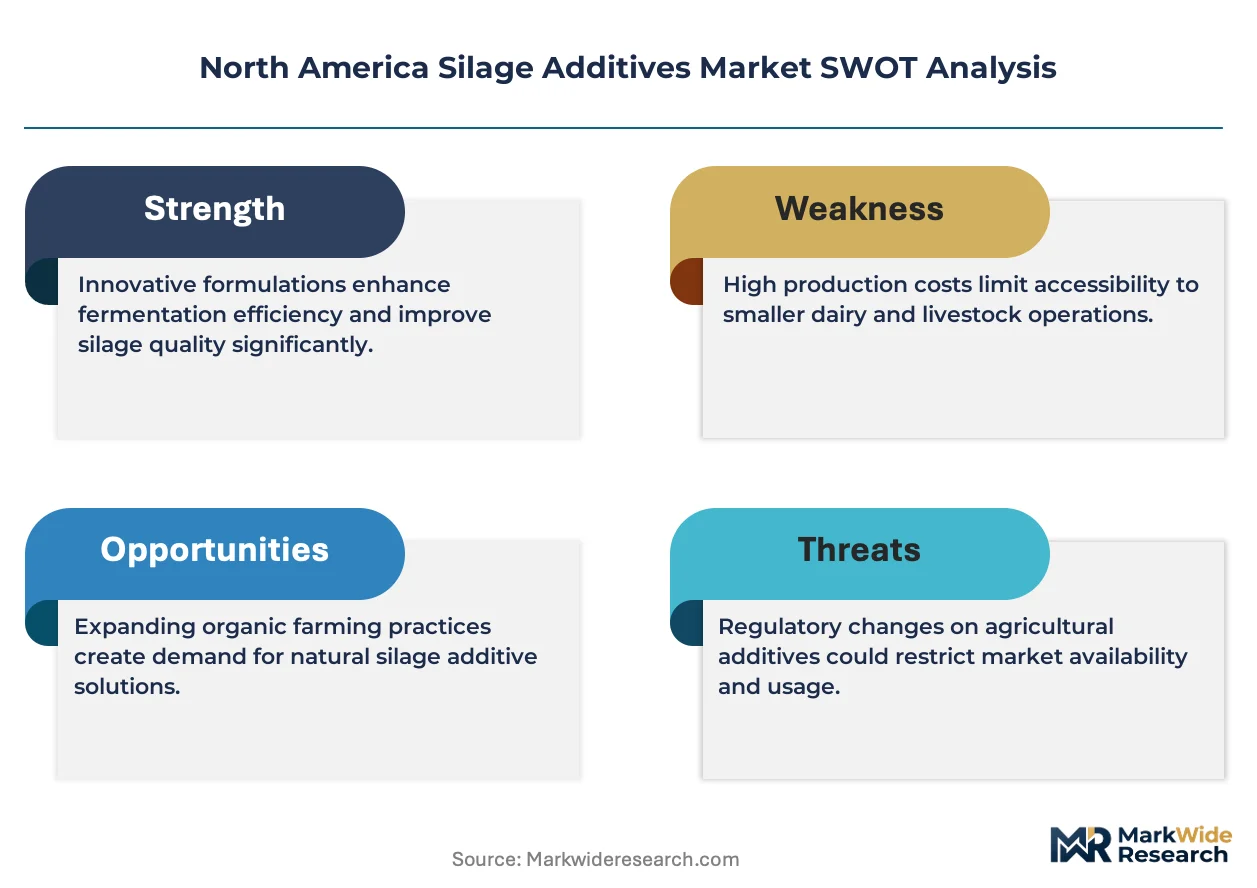
- Temperature variability performance gaps:Microbial inoculants show inconsistent efficacy across climate zones, limiting universal substitution for chemical alternatives.
Strategic Opportunities
- Canadian prairie expansion:Alberta and Saskatchewan dairy sectors remain underpenetrated for customized additive programs with embedded forage testing.
- Enzyme-bacteria convergence:Fiber-degrading enzyme cocktails paired with Lactobacillus strains unlock measurable milk yield gains that justify premium positioning.
- Direct-to-farm digital channels:E-commerce platforms bypass traditional cooperative distribution, enabling smaller Wisconsin producers to access technical formulations previously reserved for large operations.
Industry Challenges
- Strain-specific technical expertise:Dairy nutritionists lack training in microbial ecology, creating adoption friction for complex inoculant programs.
- Interstate labeling compliance:California and Wisconsin impose divergent testing requirements that fragment packaging and raise inventory costs for multi-state suppliers.
- Legacy fermentation monitoring integration:Wireless pH and temperature sensors require retrofitting existing bunker silos, delaying real-time additive adjustment adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Silage Additives Market |
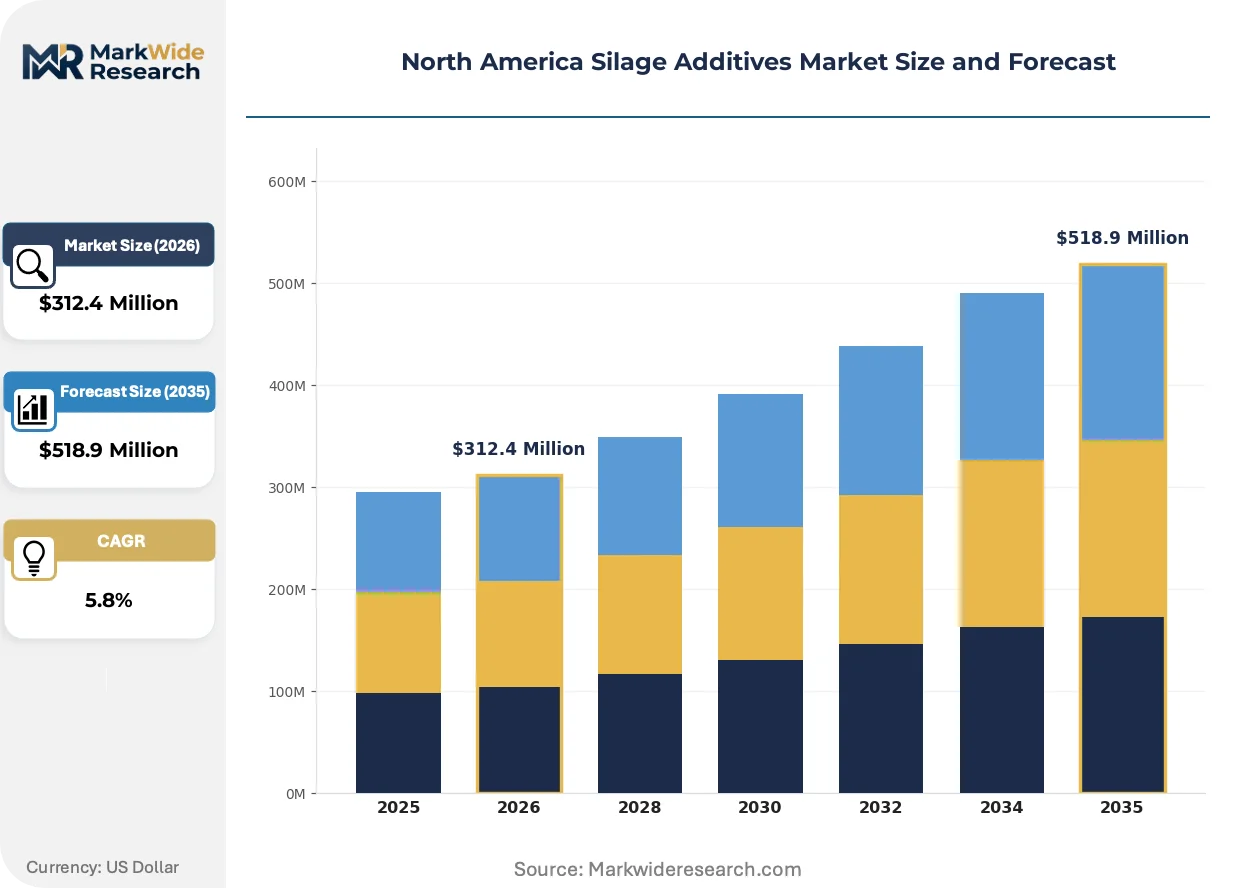
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Acids, Enzymes, Inoculants, Other Additives Application: Dairy Feed, Beef Feed, Specialty Crops, Others End User: Dairy Farms, Feedlots, Research Institutions, Commercial Farms Distribution Channel: Online, Agronomy Stores, Cooperatives, Wholesalers |
| Companies Covered | Cargill, Pioneer Hi-Bred International (Corteva Ag), Kemin Industries, BIOMIN Holding GmbH, American Farm Products, Lallemand Animal Nutrition, BASF SE, Eastman Chemical Company, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Silage Additives Market Evolving Landscape
Formulation science is converging with precision agriculture tools to enable real-time additive adjustment based on forage moisture and ambient conditions. This integration is compressing the feedback loop between harvest and preservation optimization.
Multi-strain inoculant technology is hybridizing traditional homofermentative and heterofermentative bacterial functions into single-application products. Large-scale California dairies are adopting these formulations at accelerated pace to secure aerobic stability without secondary chemical treatments. The technology is hybridizing what were previously separate product categories, forcing suppliers to consolidate R&D pipelines or exit premium positioning.
EPA's evolving FIFRA enforcement posture is reclassifying certain organic acid claims as pesticide registrations requiring expanded toxicology data. This regulatory friction is elevating compliance costs for propionic acid suppliers while creating competitive shelter for biological alternatives with different regulatory pathways. Midwest chemical preservative manufacturers are responding by reformulating at lower concentrations or pursuing biopesticide registrations.
Cooperative procurement consolidation is compressing supplier margins as dairy buying groups aggregate volume and demand technical service bundling. Traditional distribution through independent nutritionists is giving way to direct manufacturer relationships with large Wisconsin and California operations. This channel shift is most visible in the Great Lakes region where three major cooperatives now control additive specification for member farms.
North America Silage Additives Market Segmentation
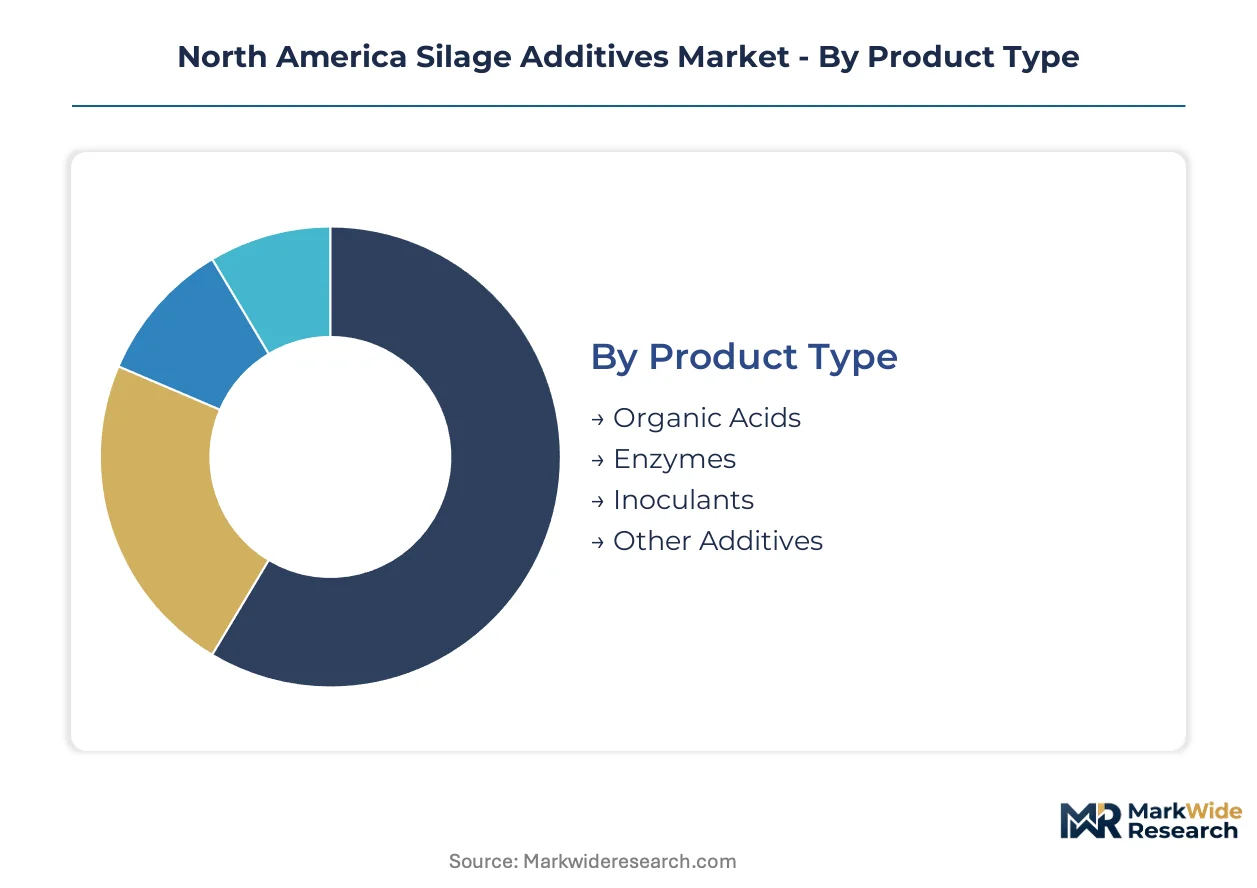
Silage additive purchasing patterns diverge sharply across product chemistry, livestock application, and procurement channel. Understanding these fault lines reveals where formulation premiums command pricing power versus where volume logistics dominate supplier selection.
Product Type:
Mature acid-based preservatives coexist with emerging microbial technologies across North American forage systems.
- Inoculants:Multi-strain bacterial formulations deliver Lactobacillus and Lactococcus species at colony-forming unit concentrations engineered for specific crop moisture profiles. Wisconsin and California dairies concentrate procurement here as EPA scrutiny of antimicrobial residues intensifies and protein preservation priorities displace simple pH reduction goals.
- Organic Acids:Propionic, formic, and acetic acid blends applied at 1-5 kg per ton of fresh forage provide rapid pH suppression and broad-spectrum spoilage inhibition. Price volatility in petroleum-derived inputs squeezes margin stability for Midwest chemical preservative suppliers serving traditional Great Plains cooperatives.
- Enzymes:Fiber-degrading cellulase and hemicellulase cocktails unlock digestibility improvements that translate to measurable milk yield gains in commercial dairy operations.
- Other Additives:Absorbents, nutrients, and preservative adjuncts address specialized moisture management challenges in high-humidity harvest windows.
Organic Acids retain volume leadership; Enzymes hold the steepest expansion curve as fiber digestibility premiums justify formulation costs.
Application:
End-use economics determine whether additive selection prioritizes fermentation control or nutritional enhancement.
- Dairy Feed:High-value lactating rations demand customized additive blends with embedded technical support and real-time forage testing. Large-scale operations in the Great Lakes and Central Valley generate the deepest margin pools through volume procurement of premium inoculant programs.
- Beef Feed:Backgrounding and finishing operations emphasize cost-efficient preservation with less formulation complexity than dairy counterparts. Feedlots across the Texas Panhandle and Nebraska Sandhills concentrate demand for acid-based products with rapid fulfillment requirements.
- Specialty Crops:Alfalfa, sorghum, and small-grain silages require crop-specific strain selection and moisture-adjusted application protocols.
- Others:Equine, small ruminant, and exotic livestock applications represent niche volume with specialized palatability and safety requirements.
Dairy Feed commands the highest formulation premiums; Specialty Crops are gaining share fastest as cover-crop-to-silage transitions diversify forage portfolios.
End User:
Scale and technical sophistication segment purchasing behavior across the customer base.
- Dairy Farms:Herd sizes above 500 head drive specification of customized additive programs with embedded nutritionist support and wireless fermentation monitoring. Wisconsin and California operations lead adoption of multi-strain inoculants with aerobic stability guarantees.
- Feedlots:Large commercial yards prioritize rapid delivery and bulk pricing over strain-specific technical differentiation.
- Commercial Farms:Diversified crop-livestock operations seek flexible additive portfolios spanning multiple forage types and livestock classes.
- Research Institutions:University extension and private trial facilities procure experimental formulations for strain validation and efficacy documentation.
Dairy Farms anchor revenue concentration; Commercial Farms are expanding procurement most quickly as mid-scale operations professionalize forage management.
Distribution Channel:
Channel structure determines supplier margin capture and technical service bundling intensity.
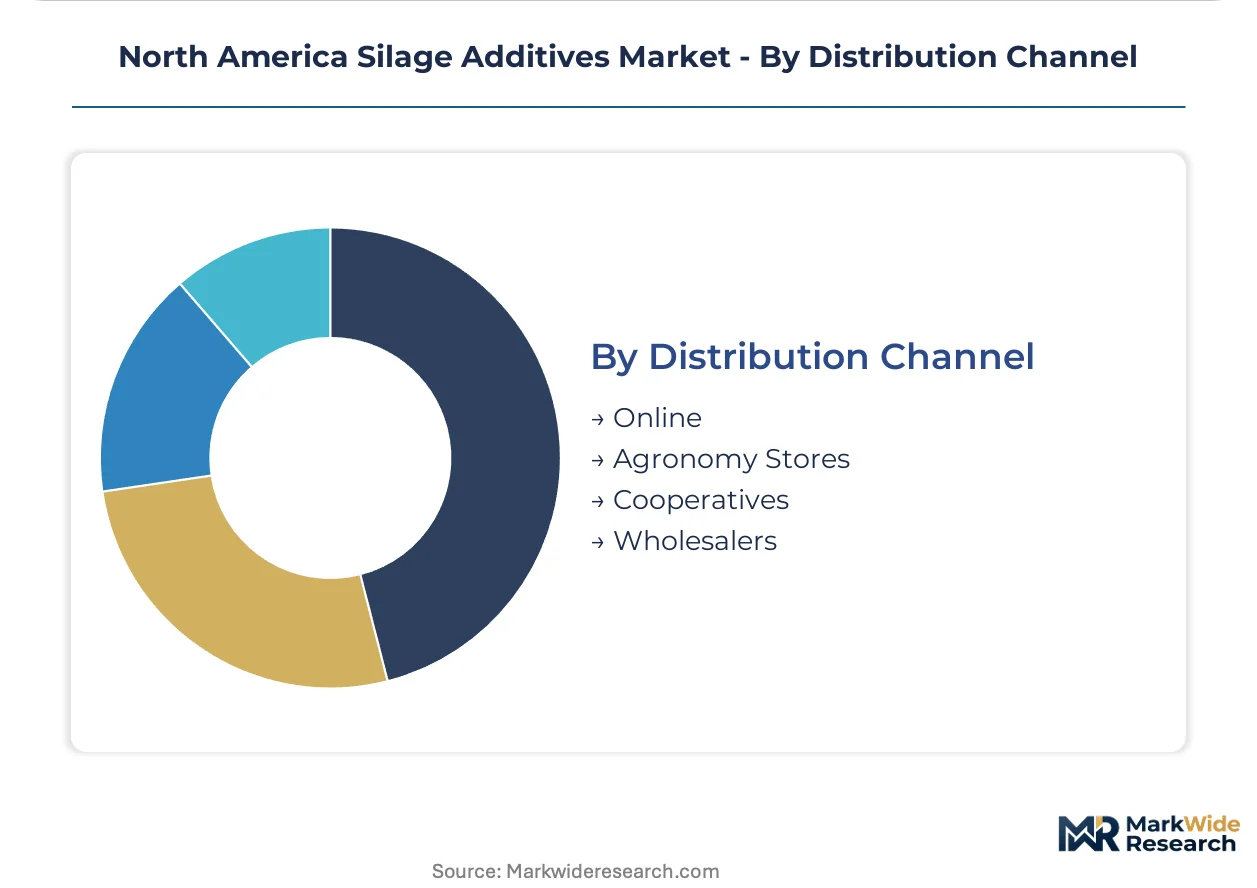
- Cooperatives:Dairy buying groups across the Great Lakes and Central Valley aggregate volume and demand embedded agronomic services, compressing standalone product margins.
- Agronomy Stores:Independent retailers serve smaller Wisconsin and Minnesota producers with localized inventory and seasonal credit terms.
- Wholesalers:Regional distributors manage logistics for multi-state suppliers navigating divergent California and Wisconsin labeling requirements.
- Online:Direct-to-farm digital platforms bypass traditional cooperative distribution, enabling smaller producers to access technical formulations previously reserved for large operations.
Cooperatives dominate volume throughput; Online channels are climbing fastest as procurement digitization penetrates mid-scale dairy operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports specialized inoculant formulations to dairy operations across the northern United States, establishing a cross-border trade corridor that channels Canadian biotech expertise into American forage systems.
United States
Wisconsin and California dairy consolidation drives concentrated additive procurement, with herds above 500 head specifying customized multi-strain programs. The EPA's FIFRA enforcement posture reclassifies certain organic acid claims as pesticide registrations, elevating compliance costs for traditional chemical suppliers. Iowa and Minnesota manufacturing clusters anchor rapid fulfillment networks serving Great Plains cooperatives with just-in-time delivery protocols.
Canada
Alberta and Saskatchewan dairy sectors remain underpenetrated for customized additive programs, creating expansion vectors for technical service bundling. Health Canada's PMRA regulates antimicrobial claims on silage preservatives under parallel frameworks to American EPA oversight. Prairie provinces concentrate demand for temperature-variable formulations that perform across continental climate extremes.
Mexico
Commercial feedlot expansion in Sonora and Chihuahua generates procurement of cost-efficient acid-based preservation systems. The country's national agricultural regulator imposes import documentation requirements that fragment cross-border distribution for multi-state American suppliers. Northern border states concentrate additive demand from integrated beef operations serving export markets.
North America Silage Additives Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agribusiness platforms and specialized microbial developers. Tiered competitive dynamics separate multinational chemical conglomerates from focused biotechnology specialists. Strategic archetypes include seed-linked additive bundlers, strain-specific microbial formulators, and regional chemical preservative manufacturers. Dominant competitive moves encompass cooperative procurement consolidation and direct-to-farm digital channel expansion.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland Company exemplify diversified input suppliers that span grain trading through value-added feed additives. Corteva's Pioneer Hi-Bred International anchors the seed-linked bundling archetype, leveraging distribution infrastructure to attach additive specifications to genetic material procurement. These entities occupy positions that reward scale economies and captive customer relationships across the agricultural value chain.
| Leading Market Players |
|---|
| Cargill |
| Pioneer Hi-Bred International (Corteva Ag) |
| Kemin Industries |
| BIOMIN Holding GmbH |
| American Farm Products |
| Lallemand Animal Nutrition |
| BASF SE |
| Eastman Chemical Company |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Iowa and Minnesota manufacturing clusters anchor North American silage additive production, concentrating formulation capacity near Midwest dairy demand centers and compressing logistics premiums for rapid fulfillment to Great Plains cooperatives.
Pricing Analysis
Current-generation multi-strain inoculants command substantial premiums over prior-generation single-strain formulations and commodity organic acid preservatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by strain complexity and embedded technical service intensity. Price differentiation centers on aerobic stability guarantees and protein preservation performance metrics. Pricing pressure stems from cooperative procurement consolidation as dairy buying groups aggregate volume and demand bundled agronomic support. Smaller Wisconsin producers exhibit highest price sensitivity, while California operations above 500 head show lowest sensitivity due to measurable milk yield gains justifying formulation premiums.
Supply Chain Analysis
USDA and EPA regulatory frameworks function as implicit export controls on antimicrobial preservative technologies, restricting cross-border flow of certain acid-based formulations and redirecting supply toward biological alternatives with cleaner regulatory pathways. Manufacturing concentrates in the United States, with Canadian prairie operations drawing from American Iowa and Minnesota hubs for specialized inoculant strains. Raw material dependencies include petroleum-derived propionic acid, Lactobacillus culture media, and fiber-degrading enzyme precursors. Supply chain risk centers on propionic acid price volatility tied to crude oil derivatives. Distribution runs through dairy cooperatives and direct-to-farm digital channels serving Wisconsin and California operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by dairy margin compression, with herd expansion and protein price recovery now stimulating additive procurement.
For Market Incumbents: Build switching-cost moats through embedded forage testing services and wireless fermentation monitoring integration that locks dairy operations into proprietary additive programs. Deepen strain-specific technical expertise to defend against generic microbial suppliers. Expand Iowa manufacturing capacity to secure rapid fulfillment advantages for Great Plains cooperative contracts. For New Entrants and Emerging Players: Pursue underpenetrated Alberta and Saskatchewan dairy sectors with temperature-variable formulation portfolios and bundled agronomic support previously unavailable in Canadian prairie markets. Target mid-scale Wisconsin operations through direct-to-farm digital channels that bypass entrenched cooperative distribution. Anchor go-to-market strategy on enzyme-bacteria convergence products demonstrating measurable milk yield improvements in commercial trials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among strain-specific microbial developers with embedded technical service contracts and multi-year cooperative supply agreements. Long-term viability favors platforms with EPA-compliant biological pathways that avoid antimicrobial classification risks. Acquisition targets should demonstrate proven aerobic stability performance across climate zones. Watch FDA guidance on antibiotic alternatives as the critical inflection signal redirecting R&D budgets toward biological solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme-Bacteria Convergence R&D | Fiber-degrading cocktails paired with Lactobacillus strains unlock milk yield premiums justifying formulation costs. |
| Direct-to-Farm Digital Channel Expansion | E-commerce platforms bypass cooperative gatekeepers and capture margin from mid-scale Wisconsin dairy operations. |
| Canadian Prairie Market Entry | Alberta and Saskatchewan dairy sectors lack customized additive programs with embedded forage testing services. |
| Wireless Fermentation Monitoring Integration | Real-time pH and temperature sensors enable dynamic additive adjustment and lock in customer switching costs. |
| PMRA Biopesticide Registration Pathway | Health Canada compliance opens cross-border supply corridors for EPA-scrutinized antimicrobial alternatives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy nutritionists, cooperative procurement managers, and microbial formulation scientists; and secondary validation through USDA conservation program documentation, EPA FIFRA registration databases, and FDA Veterinary Feed Directive guidance. Primary fieldwork captured procurement behavior across Wisconsin and California operations. Secondary sources included state agriculture department labeling requirements, trade flow data, and industry association forage preservation reports. Bottom-up volume estimates triangulated against top-down market sizing.
Forecast inputs considered product chemistry transitions, dairy herd consolidation trajectories, and regulatory pathway evolution across the analysis window. Segmentation modeling spanned formulation type, livestock application, operation scale tier, and distribution channel structure. CAGRs derived from trend extrapolation of biological inoculant adoption curves and cooperative procurement consolidation patterns. Industry-specific inputs included EPA enforcement posture shifts and cover-crop-to-silage transition subsidies.
Sensitivities concentrate around EPA FIFRA reclassification of organic acid claims, dairy margin volatility affecting additive purchasing cycles, and temperature variability impacts on microbial efficacy. Forecasts reflect documented assumptions regarding biological displacement rates and cooperative channel evolution. Material shifts in FDA antibiotic alternative guidance or propionic acid input costs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Fungicides Market