
 North America Feed Minerals Market | 2026-2036
North America Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Minerals Market Analytics
Subscription-based mineral monitoring programs is realigning how feed minerals are sold, shifting transactions from bulk commodity orders to recurring service bundles that include formulation adjustments and herd-specific analytics. Cargill Inc. leverages its extensive distribution network to dominate direct-to-feedlot channels across the Great Plains. BASF SE anchors its position through R&D intensity in chelated trace mineral technologies. Nutreco N.V. specializes in precision nutrition software that integrates with on-farm mineral dispensers.
Feed minerals are inorganic compounds including calcium, phosphorus, magnesium, sodium, potassium, sulfur, and trace elements such as zinc, copper, manganese, iron, selenium, and iodine, typically incorporated at 0.1% to 3% of total ration dry matter to support metabolic function, bone development, and enzymatic activity in livestock. Macrominerals sustain the largest volume base due to their essential role in dairy and beef cattle rations across North America. Trace minerals represent the fastest-expanding margin pool as chelated and hydroxy forms command premium positioning over inorganic sulfates and oxides. The liquid form segment is gaining traction in automated feed delivery systems, particularly within integrated poultry operations in the southeastern United States.
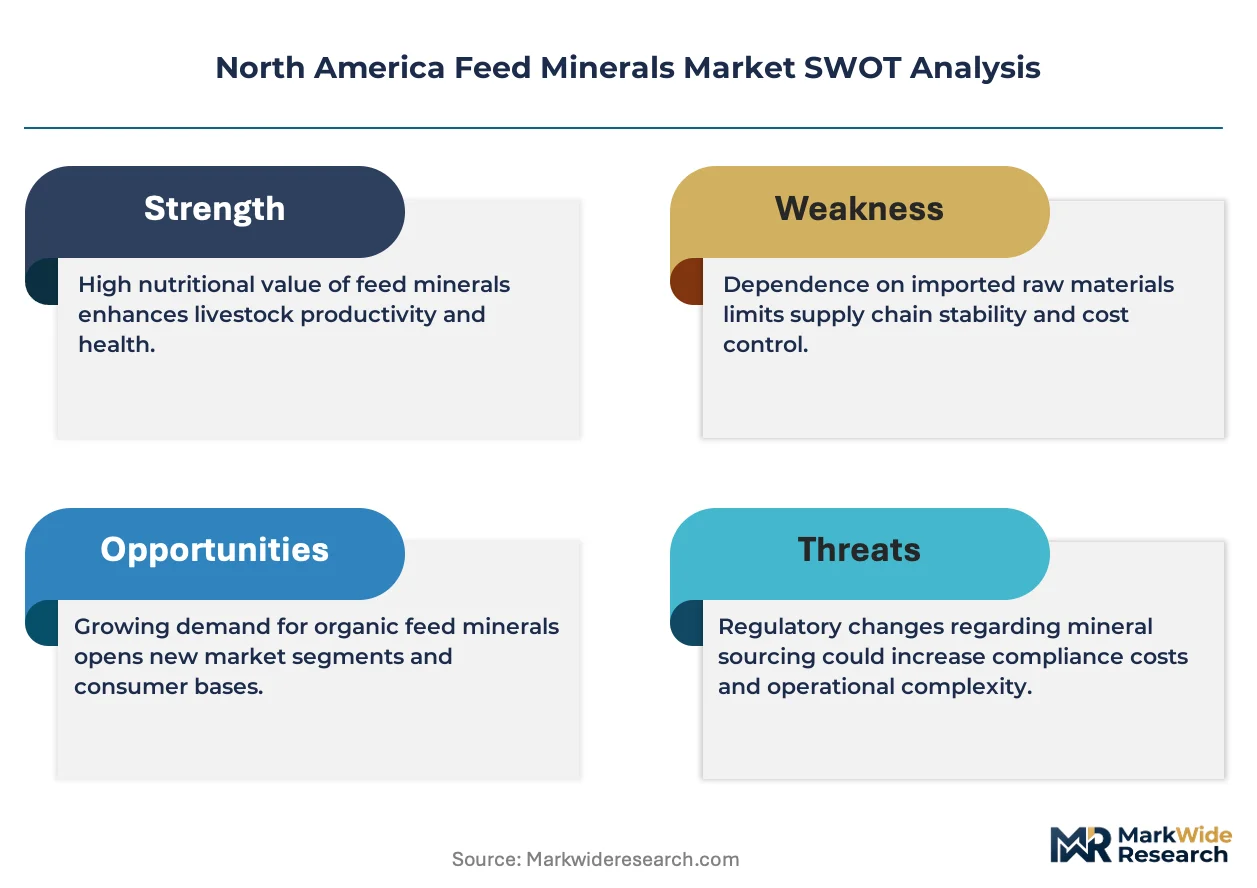
The FDA's Veterinary Feed Directive and the CFIA's Feed Program jointly govern mineral additive approvals, residue limits, and medicated feed distinctions across the United States and Canada, creating a dual-compliance burden for suppliers operating cross-border. State-level implementation of the FDA's updated antimicrobial guidance in California and New York further constrains mineral premix formulations that previously incorporated growth-promotion claims. Stakeholders must monitor evolving EPA nutrient management requirements for concentrated animal feeding operations, as phosphorus and zinc discharge limits increasingly influence mineral formulation decisions and create compliance-driven demand for low-excretion mineral sources.
Market Dynamics
The FDA's updated Veterinary Feed Directive has compressed prescribing autonomy for trace minerals, forcing feedlots and dairy operations into veterinarian-mediated procurement workflows that add cost layers while reducing formulation flexibility across commercial livestock operations.
Growth Catalysts
- Precision Nutrition Software:Integration of real-time mineral dispensers with herd analytics platforms allows dairy operations in Wisconsin to adjust supplementation protocols based on individual cow metabolic profiles.
- Texas Panhandle Feedlot Corridor:Concentrated cattle finishing operations drive bulk mineral procurement at scale, creating demand density that supports dedicated distribution infrastructure and technical service investments.
- CFIA Feed Program Alignment:Harmonized cross-border approval pathways between the United States and Canada reduce regulatory duplication costs for suppliers serving integrated North American livestock supply chains.
Market Restraints
- Phosphorus Input Volatility:Fluctuating phosphate rock prices and concentrated Moroccan export supply create margin pressure for macromineral premix manufacturers dependent on consistent phosphorus sourcing.
- EPA Nutrient Management Constraints:Discharge limits for zinc and phosphorus from concentrated animal feeding operations in the Chesapeake Bay watershed force reformulation away from standard sulfate sources toward lower-bioavailability alternatives.
- Substitution by Organic Trace Minerals:Hydroxy and chelated mineral forms command premium positioning that squeezes inorganic sulfate producers into commodity pricing tiers with compressed margins.
Strategic Opportunities
- Underpenetrated Canadian Prairie Dairy:Saskatchewan and Alberta dairy expansions lack mature mineral monitoring infrastructure, creating first-mover advantage for subscription-based formulation services.
- California Antimicrobial Guidance Tailwind:State-level restrictions on growth-promotion claims redirect mineral premix R&D toward immune-modulation and metabolic efficiency positioning.
- Liquid Mineral Automation Convergence:Integration of liquid mineral delivery systems with robotic feed pushers and automated mixing equipment opens precision dosing channels in southeastern US poultry integrations.
Industry Challenges
- Ruminant Nutritionist Talent Scarcity:Feedlot and dairy operations struggle to recruit professionals capable of balancing FDA compliance requirements with NRC mineral requirement optimization across varying forage bases.
- Dual-Compliance Certification Burden:Suppliers must maintain parallel FDA Veterinary Feed Directive and CFIA Feed Program documentation systems, extending product registration timelines and technical staff allocation.
- Legacy Feed Mill Integration Friction:Automated mineral dispensing systems require retrofitting of existing batching infrastructure, creating implementation delays and capital allocation conflicts at mid-sized operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Minerals Market |
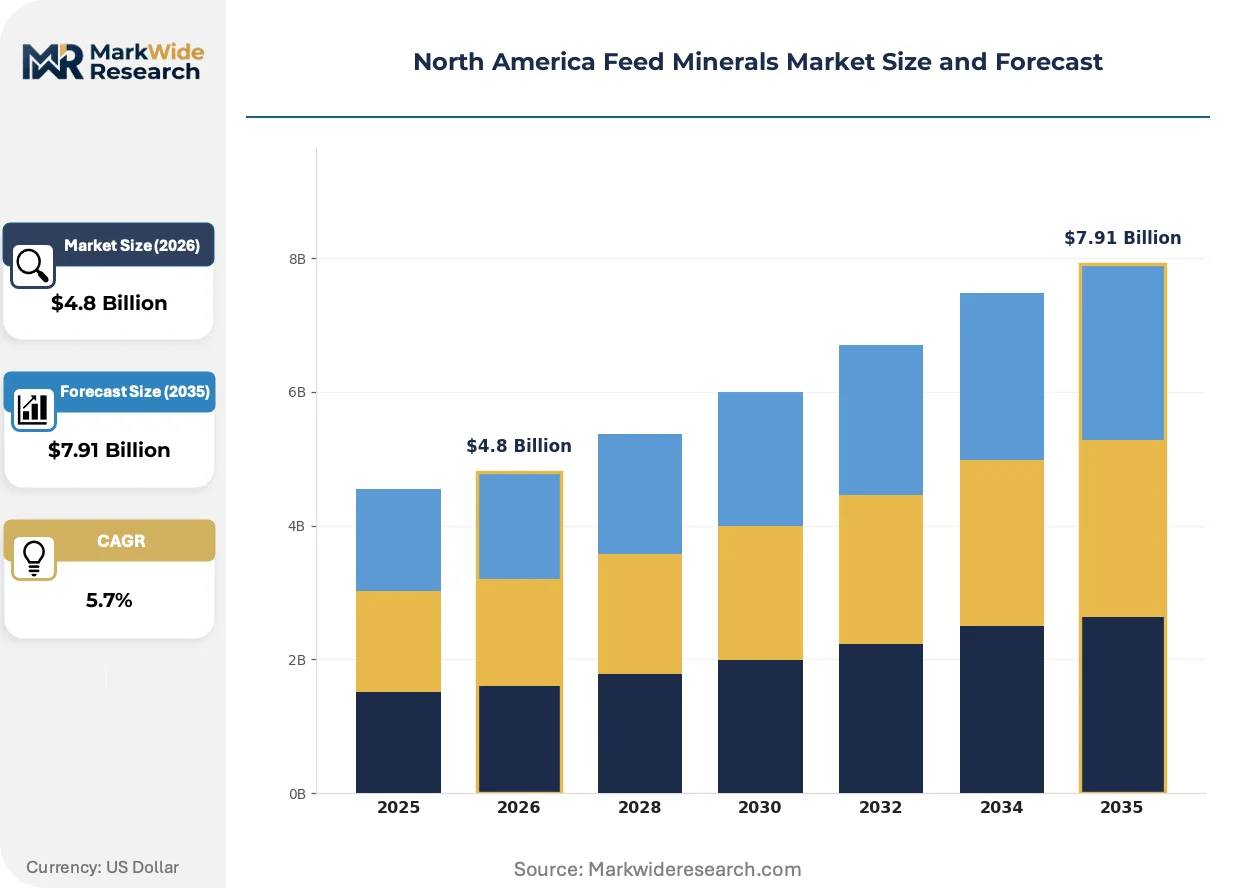
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premixes, Trace Minerals, Macrominerals, Vitamins Form: Granular, Powder, Liquid, Pellet Livestock Type: Cattle, Poultry, Swine, Aquaculture Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, Land O'Lakes Inc., Phibro Animal Health Corporation, Nutreco N.V., BASF SE, Kemin Industries, Novus International Inc., Alltech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Minerals Market Evolving Landscape
Chelated and hydroxy trace mineral technologies are compressing the performance gap between inorganic sulfates and organic forms, while liquid delivery systems and real-time monitoring platforms restructure how mineral nutrition is procured and administered across species.
Hydroxy trace minerals are electrifying competitive positioning in the premix sector by delivering intermediate bioavailability at cost structures below proteinates and amino acid chelates. Large-scale beef feedlots in the Texas-Oklahoma corridor have accelerated adoption of hydroxy copper and zinc forms to maintain liver enzyme function while managing EPA discharge exposure. The technology is electrifying margin structures by creating a three-tier mineral hierarchy that segments customers by performance requirements rather than species alone.
California's implementation of Senate Bill 27 antimicrobial use restrictions has forced mineral premix suppliers to eliminate growth-promotion language from product literature and reformulate around immune competence claims. The FDA's parallel enforcement of veterinary oversight for medically important minerals has tightened the link between mineral supplementation and veterinary-client-patient relationships. Dairy operations in the Central Valley face the steepest compliance adjustment costs due to their reliance on historical self-directed mineral programs.
Subscription-based mineral monitoring is displacing spot-market commodity procurement among upper Midwest dairy cooperatives. Real-time formulation adjustments based on milk urea nitrogen and somatic cell count data now bundle with physical mineral supply in multi-year service agreements. Wisconsin and Minnesota operations with 500+ cow herds show the fastest transition velocity, driven by lender requirements for documented nutritional management protocols.
North America Feed Minerals Market Segmentation
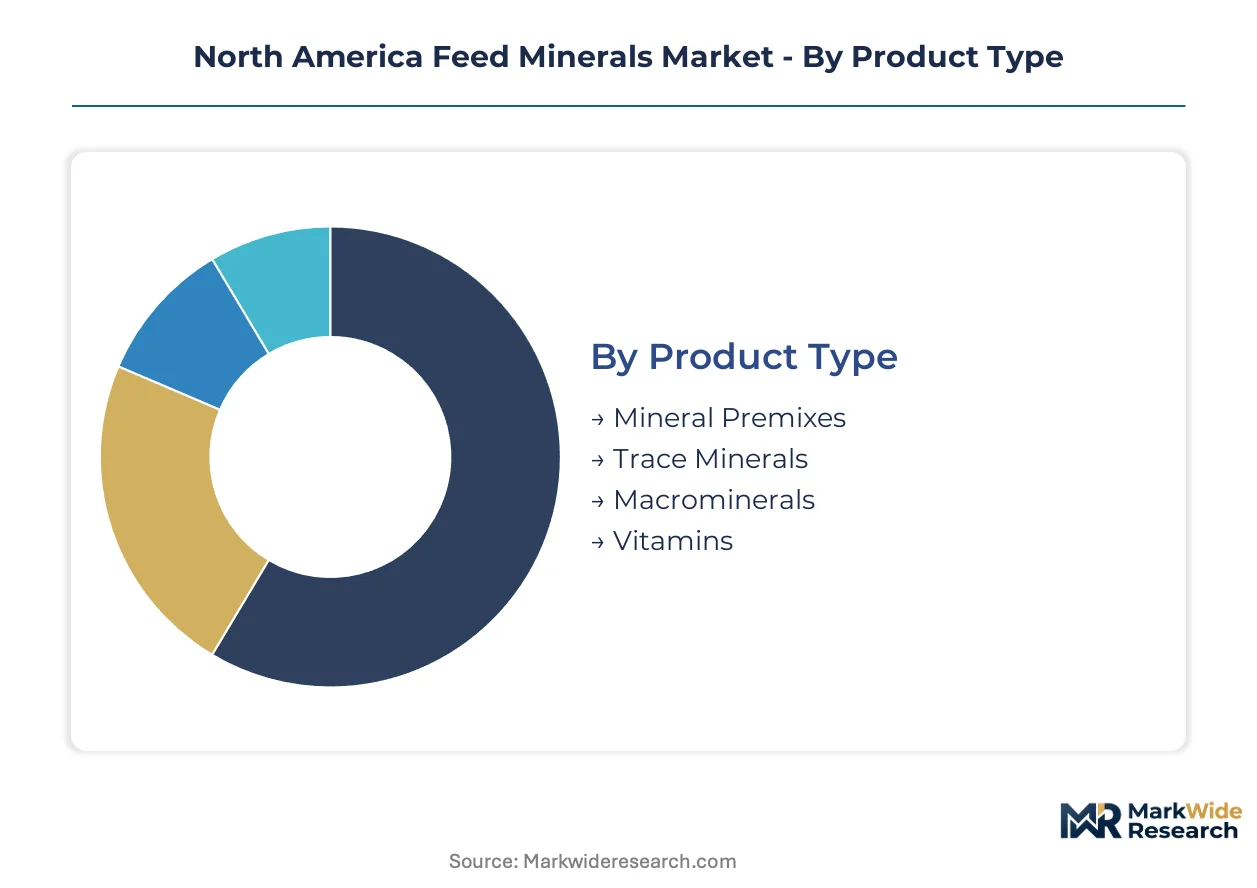
Feed mineral suppliers structure portfolios around four intersecting dimensions that determine formulation priorities, delivery logistics, and customer engagement models. Understanding how these segments interact clarifies why certain suppliers dominate specific channels while others capture premium positioning in specialized applications.
Product Type:
Upgrade cycles from basic commodity minerals to precision-formulated premixes are shortening as dairy and feedlot operations adopt subscription-based monitoring services that bundle analytics with physical supply.
- Mineral Premixes:Blended formulations combining macro and trace minerals with carriers at specified inclusion rates, typically 0.5% to 3% of total ration. Demand concentrates in Wisconsin and Minnesota dairy cooperatives where 500+ cow herds require documented nutritional protocols for lender compliance.
- Trace Minerals:Chelated, hydroxy, and inorganic forms of zinc, copper, manganese, iron, selenium, and iodine delivered at parts-per-million inclusion levels. Texas Panhandle feedlots drive bulk procurement of hydroxy copper and zinc forms to manage EPA discharge exposure while maintaining liver enzyme function in finishing cattle.
- Macrominerals:Calcium, phosphorus, magnesium, sodium, potassium, and sulfur compounds sustaining the largest volume base across North American cattle rations. Phosphate rock price volatility from concentrated Moroccan supply creates persistent margin pressure for premix manufacturers.
- Vitamins:Fat-soluble and water-soluble organic compounds co-formulated with mineral matrices for complete nutritional coverage. Poultry integrators in the southeastern United States specify vitamin-mineral complexes for automated delivery systems.
Volume placements concentrate in Macrominerals; the faster expansion belongs to Trace Minerals.
Form:
Cost tier differentiation separates commodity dry forms from precision liquid systems, with automation-ready formats commanding 40-60% price premiums over standard powders.
- Granular:Free-flowing mineral particles with uniform size distribution for mechanical handling and reduced segregation during transport. Beef feedlots in the Texas-Oklahoma corridor specify granular forms for high-volume pneumatic delivery systems.
- Powder:Fine-ground mineral particles offering maximum surface area for rapid dissolution and uniform mixing in total mixed rations. Mid-sized dairy operations continue specifying powders for compatibility with legacy batching infrastructure.
- Liquid:Suspended or dissolved mineral solutions enabling precision dosing through automated pumps and in-line injection systems. Southeastern US poultry operations are retrofitting robotic feed pushers with liquid mineral integration for real-time formulation adjustments.
- Pellet:Compressed mineral matrices with binding agents for controlled release and reduced dust generation during handling. Swine operations in the Midwest specify pelleted trace minerals to minimize waste in automated feeding systems.
Granular forms dominate current procurement volumes; liquid delivery is climbing the fastest as automation investments accelerate.
Livestock Type:
Application-specific requirements create divergent mineral specifications, with ruminant operations prioritizing bioavailability for metabolic efficiency while monogastric species emphasize feed conversion optimization.
- Cattle:Dairy and beef operations requiring calcium-phosphorus balance for bone development, milk synthesis, and reproductive performance. Upper Midwest dairy expansions in Saskatchewan and Alberta lack mature mineral monitoring infrastructure, creating first-mover opportunity for subscription services.
- Poultry:Broiler and layer operations demanding precise trace mineral levels for immune competence and eggshell quality. California's Senate Bill 27 antimicrobial restrictions have forced reformulation toward immune-modulation claims rather than growth-promotion positioning.
- Swine:Nursery and finishing operations requiring zinc and copper at pharmacological levels for gut health, now constrained by FDA veterinary oversight requirements. Midwest integrators face retrofit costs for automated mineral dispensing in existing facilities.
- Aquaculture:Finfish and shellfish operations with mineral requirements for osmoregulation and skeletal development in intensive production systems. Canadian coastal operations align with CFIA Feed Program specifications for cross-border supply chain integration.
Cattle applications anchor volume demand; poultry specifications are expanding most quickly as southeastern integrators automate.
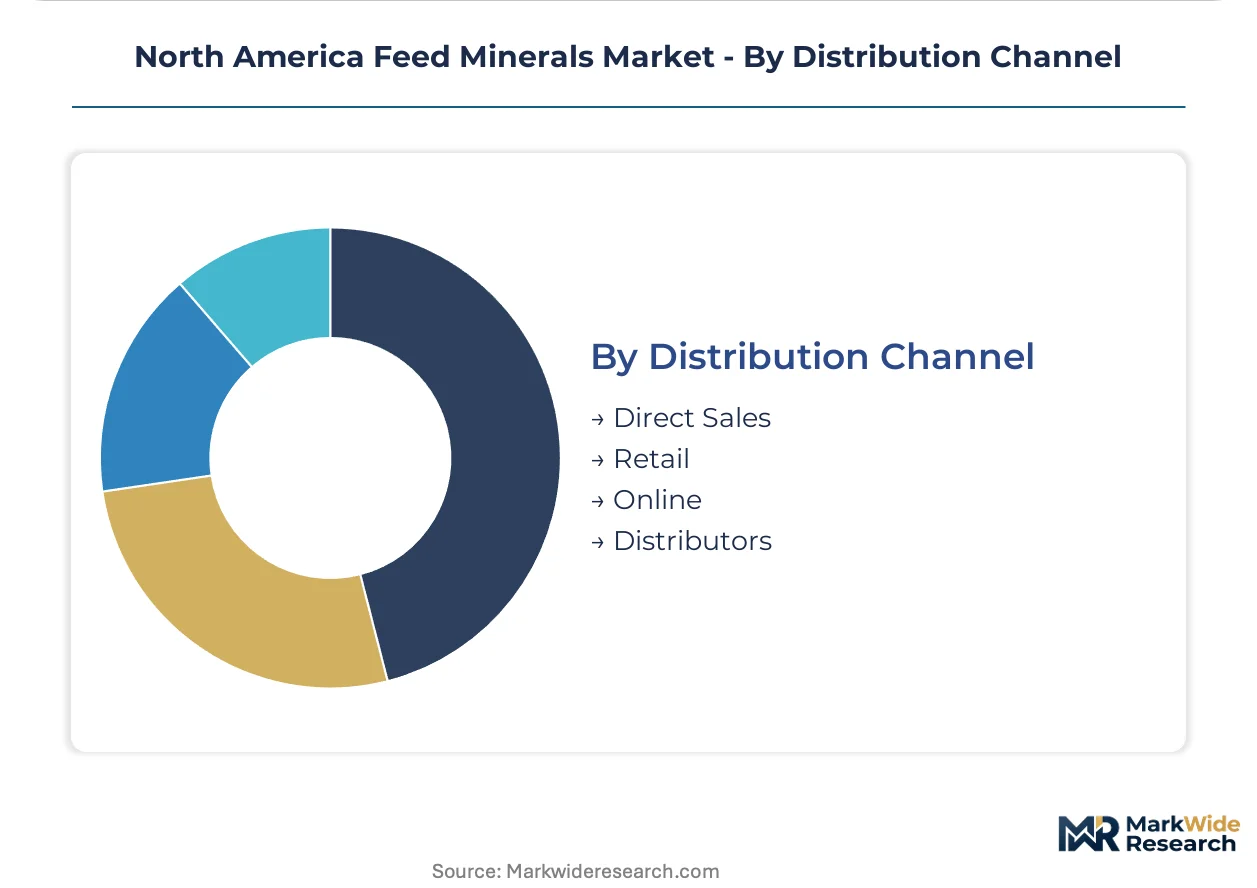
Distribution Channel:
Customer type segmentation separates price-sensitive commodity buyers from service-oriented precision nutrition adopters, with channel selection correlating directly to herd size and technical staff availability.
- Direct Sales:Manufacturer-to-feedlot relationships with embedded technical service and formulation support. Cargill leverages its Great Plains distribution network to lock in direct-to-feedlot contracts across the Texas Panhandle corridor.
- Retail:Farm supply stores and cooperatives serving smaller operations with bagged premixes and basic mineral supplements. Upper Midwest dairy cooperatives are transitioning retail customers toward bundled monitoring subscriptions.
- Online:E-commerce platforms enabling price comparison and bulk ordering for mid-sized operations with established nutritional programs. Regulatory complexity around FDA Veterinary Feed Directive compliance limits online growth for medicated mineral formulations.
- Distributors:Independent and captive distribution networks managing inventory, credit terms, and last-mile delivery across fragmented geography. Dual-compliance burden for FDA and CFIA documentation extends distributor onboarding timelines for cross-border suppliers.
Direct sales capture the largest volume commitments; distributor relationships are gaining share fastest as suppliers seek geographic coverage without capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral production concentrates in the Great Plains processing corridor while consumption clusters in dairy-dense Upper Midwest and feedlot-heavy Southern Plains regions. Canada supplies phosphate and trace mineral processing capacity that flows southward into integrated US livestock supply chains. Mexico's northern border states increasingly source premix formulations from Texas-based distributors serving cross-border cattle operations.
United States
The Texas Panhandle feedlot corridor drives bulk mineral procurement at scale, with concentrated cattle finishing operations creating demand density for dedicated distribution infrastructure. The FDA's Veterinary Feed Directive reshapes how trace minerals are prescribed across commercial livestock operations. Wisconsin and Minnesota dairy cooperatives with 500+ cow herds show fastest transition velocity toward subscription-based mineral monitoring programs.
Canada
Saskatchewan and Alberta dairy expansions lack mature mineral monitoring infrastructure, creating first-mover advantage for precision nutrition services. The CFIA Feed Program governs mineral additive approvals and residue limits, creating dual-compliance burden with FDA requirements for cross-border suppliers. Prairie Provinces processing capacity serves integrated North American supply chains with phosphate and macromineral production.
Mexico
Northern border states source mineral premix formulations through Texas-based distributors serving integrated cattle operations. The country's national feed regulator aligns with North American trade harmonization protocols for cross-border mineral commerce. Nuevo León and Chihuahua livestock clusters drive procurement of automated mineral dispensing systems for feedlot efficiency.
North America Feed Minerals Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across tiered market positions. The vendor base clusters around three strategic archetypes: diversified agribusiness conglomerates with captive distribution networks, pure-play premix manufacturers with precision nutrition software capabilities, and regional blenders serving fragmented dairy and feedlot geographies. Consolidation pressures intensify as subscription-based service models require capital investment in analytics platforms and technical field staff.
Within the diversified agribusiness tier, Cargill Inc. and Archer Daniels Midland Company anchor positions through extensive grain-handling infrastructure that captures downstream mineral blending economics. BASF SE and Nutreco N.V. occupy the technology-intensive segment, with the former representing European-based chemical conglomerates and the latter exemplifying Dutch-originated animal nutrition specialists. These named entities illustrate how competitive positioning separates volume-driven commodity suppliers from premium-positioned precision nutrition providers.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| Land O'Lakes Inc. |
| Phibro Animal Health Corporation |
| Nutreco N.V. |
| BASF SE |
| Kemin Industries |
| Novus International Inc. |
| Alltech Inc. |
| Others |
Value Network & Pricing Analysis
Phosphate rock from Moroccan export supply flows through macromineral premix manufacturing into three-tier pricing structures across Great Plains feedlot procurement, with concentrated upstream sourcing creating margin volatility that compresses commodity sulfate producers while premium hydroxy and chelated forms capture service-bundled value.
Pricing Analysis
Margin tightening in inorganic sulfate tiers reflects phosphate rock price volatility and substitution pressure from hydroxy trace minerals. Three-tier pricing structure across premium chelated, mid-grade hydroxy, and economy sulfate levels segments buyers by performance requirements rather than species alone. Pricing pressure intensifies in commodity macrominerals as Moroccan supply concentration and EPA discharge constraints force reformulation investments. Feedlot operations in the Texas Panhandle corridor show lowest price sensitivity due to veterinary-mediated procurement workflows, while mid-sized dairy operations in legacy batching infrastructure face highest cost-down pressure.
Supply Chain Analysis
Freight cost differentials between Moroccan phosphate rock import terminals and Great Plains processing plants shape regional premix manufacturing economics. Supply concentrates in the United States, Canada, and Morocco for phosphate and macromineral processing, with trace mineral refining anchored in domestic chemical manufacturing corridors. Raw material dependencies center on phosphate rock, copper sulfate, and zinc oxide feedstocks. Single-source vulnerability to Moroccan export policy shifts creates supply chain risk. Distribution runs through captive networks of diversified agribusiness conglomerates and independent distributors managing last-mile delivery across fragmented dairy geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Veterinary Feed Directive erects a compliance moat that favors incumbents with established veterinarian-client-patient relationship infrastructure and parallel CFIA documentation systems.
For Market Incumbents: Anticipate margin compression in commodity sulfate tiers by accelerating backward integration into hydroxy trace mineral production and locking in multi-year service contracts with 500+ cow dairy cooperatives. Substitution by precision nutrition software bundled with physical supply threatens spot-market premix volumes. Channel control through embedded technical field staff represents the critical defensive lever against asset-light formulation specialists. For New Entrants and Emerging Players: Distributor partnerships with established CFIA-FDA dual-compliance documentation capabilities offer the fastest path to Saskatchewan and Alberta dairy expansions lacking mature mineral monitoring infrastructure. Underpenetrated Canadian Prairie dairy represents the most accessible white-space target. Subscription-based formulation services with real-time herd analytics provide the differentiated go-to-market angle against commodity premix incumbents. For Investors and Strategic Acquirers: Acceleration of liquid mineral automation adoption in southeastern US poultry integrators is the leading indicator that precision dosing equipment manufacturers will command acquisition premiums. Long-term viability centers on service-model transitions rather than transactional commodity supply. Acquisition targets should profile as precision nutrition software platforms with existing mineral dispenser integrations. Stakeholders should monitor EPA nutrient management rulemaking in the Chesapeake Bay watershed as the signal for low-excretion mineral source demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydroxy Mineral Production | Captures margin pool between inorganic sulfates and premium chelates for Texas Panhandle feedlots. |
| Subscription Service Model Transition | Locks in Wisconsin and Minnesota dairy cooperatives with lender-compliant documented nutritional protocols. |
| CFIA-FDA Dual-Compliance Certification Investment | Extends product registration timelines but creates barrier-to-entry moat against regional blenders. |
| Liquid Mineral Automation Platform Integration | Aligns with robotic feed pusher retrofit cycles in southeastern US poultry operations. |
| Precision Nutrition Software Acquisition | Consolidates analytics capabilities with physical mineral supply for bundled service positioning. |
Research Methodology
Independent corroboration across feedlot nutrition directors, dairy cooperative procurement managers, and premix manufacturer technical sales leads underwrites the qualitative findings. Secondary validation draws from FDA Veterinary Feed Directive guidance documents, CFIA Feed Program specifications, EPA nutrient management enforcement records, and American Feed Industry Association regulatory filings. Bottom-up volume estimates from state-level cattle inventory data and top-down mineral inclusion rate assumptions triangulate market sizing.
Comparable-period anchoring to historical dairy herd expansion cycles and feedlot placement patterns establishes baseline demand assumptions across the projection horizon. Segmentation modeling incorporates product type, mineral form, livestock species, and distribution channel dimensions with regulatory compliance tier overlays. CAGRs derive from mineral inclusion rate trend analysis, herd size distribution shifts, and automation adoption curves. Forecast inputs center on veterinary oversight expansion timelines and EPA discharge limit enforcement intensity.
Caveats apply where FDA antimicrobial guidance expansion or CFIA feed additive reclassification could materially shift the outlook. Forecasts reflect assumptions around phosphate rock supply continuity and precision nutrition software penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Gibberellins Market