
 Vietnam Aquafeed Market | 2026-2036
Vietnam Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Aquafeed Market Intelligence
Mekong Delta feed mill capacity is decoupling from smallholder farm fragmentation as industrial aquaculture scales. Charoen Pokphand Group leverages its integrated hatchery-to-harvest model across An Giang and Dong Thap provinces. De Heus sustains a dense technical sales network that anchors its position among medium-scale pangasius growers. Cargill competes through species-specific formulation services delivered directly to floating cage operations in coastal Khanh Hoa.
Aquafeed denotes nutritionally complete compounded diets for farmed aquatic species, typically containing 25-45% crude protein from fish meal, soybean meal, and rendered animal byproducts, manufactured via extrusion or pelleting to achieve water stability for 2-4 hours in pond environments. Pellet and extruded formats dominate volume as Mekong Delta farmers prioritize feed conversion efficiency in intensive pangasius ponds. Crumbles and specialized marine formulations command margin premiums in shrimp hatcheries and premium seabass cage culture along the south-central coast.
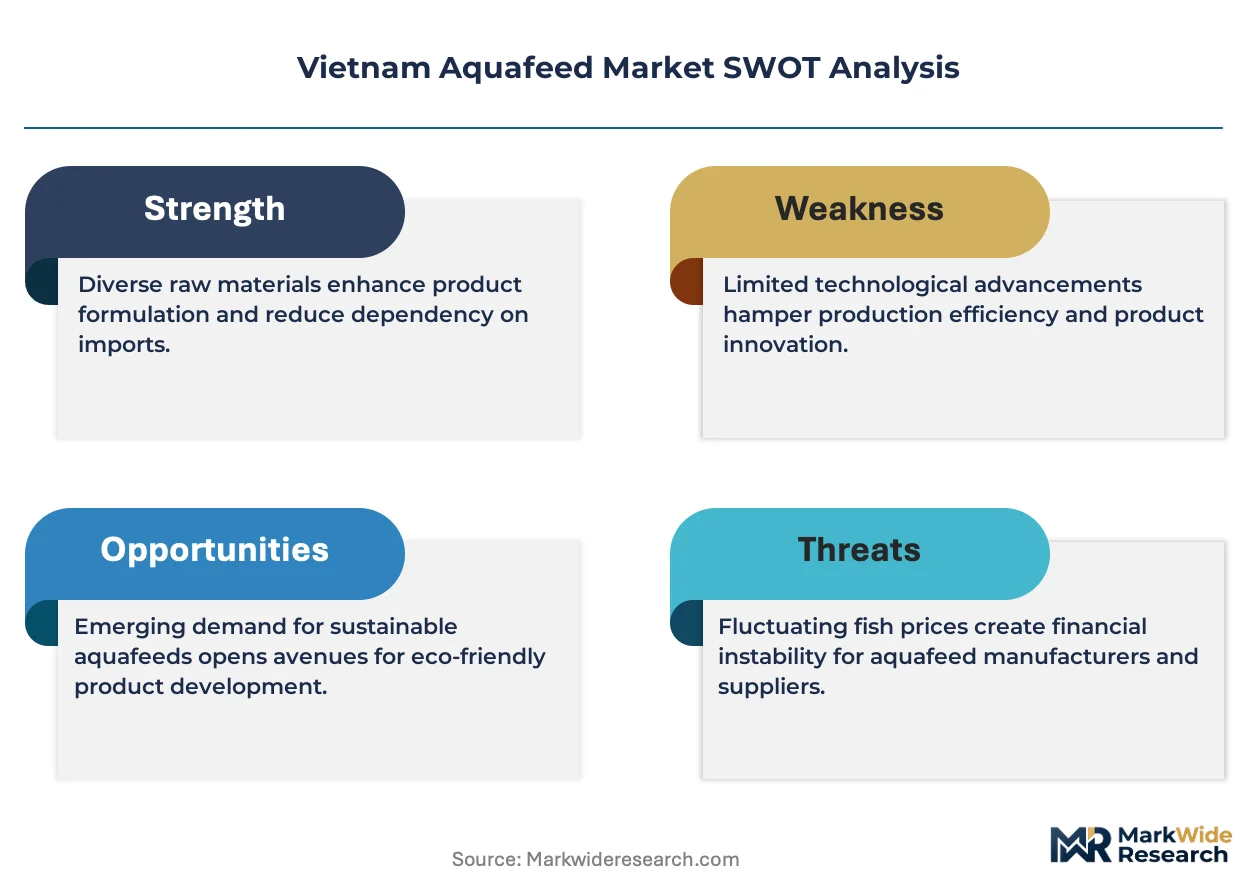
Vietnam's Ministry of Agriculture and Rural Development enforces antibiotic residue limits under Circular 24, while the country's national standards body administers feed safety protocols aligned with regional trade requirements. These frameworks compel mills to reformulate with alternative proteins and documented traceability systems. Stakeholders must monitor enforcement intensity in export-oriented supply chains as EU and US sanitary standards cascade backward into domestic formulation mandates.
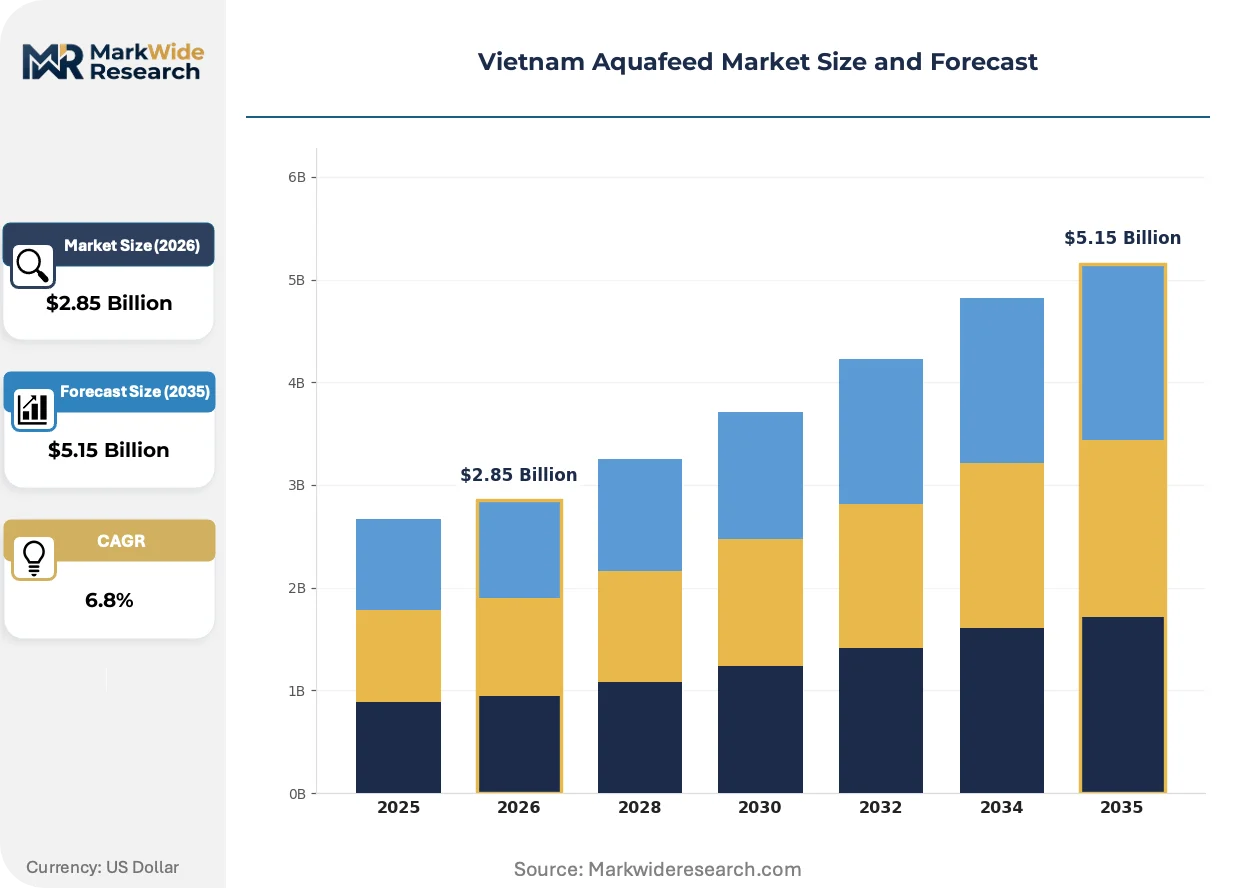
Market Dynamics
Circular 24 antibiotic residue limits from Vietnam's Ministry of Agriculture and Rural Development are forcing feed mills to reformulate protein sources and rebuild traceability systems across pangasius and shrimp supply chains.
Growth Catalysts
- Export-oriented sanitary mandates:EU and US import standards cascade backward into domestic formulation requirements, compelling mills to upgrade processing protocols for antibiotic-free certification.
- Intensive pond conversion:Mekong Delta smallholders are consolidating into industrial-scale operations that demand formulated feeds with optimized feed conversion ratios.
- Fish meal substitution:Novel single-cell protein and insect meal technologies are achieving cost parity in shrimp hatchery applications, reducing import dependency.
Market Restraints
- Soybean meal price volatility:Vietnam imports over 90% of its soybean crushing requirements, exposing formulated feed margins to global oilseed futures swings.
- Mekong Delta supply concentration:An Giang and Dong Thap provinces host disproportionate mill capacity, creating flood-risk exposure and logistics bottlenecks during monsoon seasons.
- Traceability infrastructure gaps:Smallholder farm fragmentation limits batch-level documentation compliance with Circular 24's chain-of-custody requirements.
Strategic Opportunities
- Central coastal shrimp expansion:Khanh Hoa and Phu Yen provinces offer underdeveloped pond acreage for premium marine formulations targeting export processing chains.
- Recirculating aquaculture system feed:Closed-loop shrimp and seabass operations in industrial zones require specialized low-waste extruded diets with enhanced water stability.
- Digital procurement platforms:Feed cooperatives in Can Tho and Vinh Long are piloting app-based bulk ordering systems that compress distributor margins and improve price transparency.
Industry Challenges
- Aquaculture nutritionist scarcity:Vietnamese universities produce insufficient feed formulation specialists capable of balancing amino acid profiles across multiple species.
- Extruder equipment lead times:European and Chinese machinery suppliers face 8-12 month delivery backlogs for high-capacity twin-screw extruders required by scaling mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Aquafeed Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Powder, Extruded, Crumbles Ingredient: Fish Meal, Soybean Meal, Corn Gluten Meal, Wheat Germ End User: Aquaculture Farms, Fish Hatcheries, Feed Mills, Research Institutions Application: Freshwater Fish, Marine Fish, Crustaceans, Others |
| Companies Covered | Nutreco, BASF SE, Charoen Pokphand Group, De Heus, Alltech, Archer Daniels Midland, Biomin GmbH, Aller Aqua, Cargill, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Aquafeed Market Strategic Shifts & Innovations
Protein source diversification and precision feeding technologies are compressing traditional formulation margins while opening specialized segments for functional additives and species-specific nutrition services.
Single-cell protein derived from methane-oxidizing bacteria is decentralizing fish meal procurement patterns among Mekong Delta pangasius integrators. Large-scale growers in An Giang province are trialing bacterial meal at 15-20% inclusion rates in grower diets. This biotechnology is compressing exposure to Peruvian anchovy catch volatility and enabling backward integration into on-site fermentation capacity.
Circular 24 enforcement by Vietnam's Ministry of Agriculture and Rural Development is mandating veterinary prescription systems for antibiotic use in aquaculture. Feed mills must now document every therapeutic additive batch through blockchain-anchored traceability platforms. Shrimp hatcheries in Bac Lieu and Ca Mau provinces face the steepest compliance costs, driving consolidation toward vertically integrated operations with captive laboratory testing.
Direct mill-to-farm contracting is displacing traditional distributor networks in intensive pangasius zones. Large pond operators in Dong Thap province now negotiate annual volume agreements with formulation specialists who embed technical service teams on-site. This channel shift is most visible among export-certified farms supplying EU retail chains, where feed documentation requirements exceed generic distributor capabilities.
Vietnam Aquafeed Market Segmentation
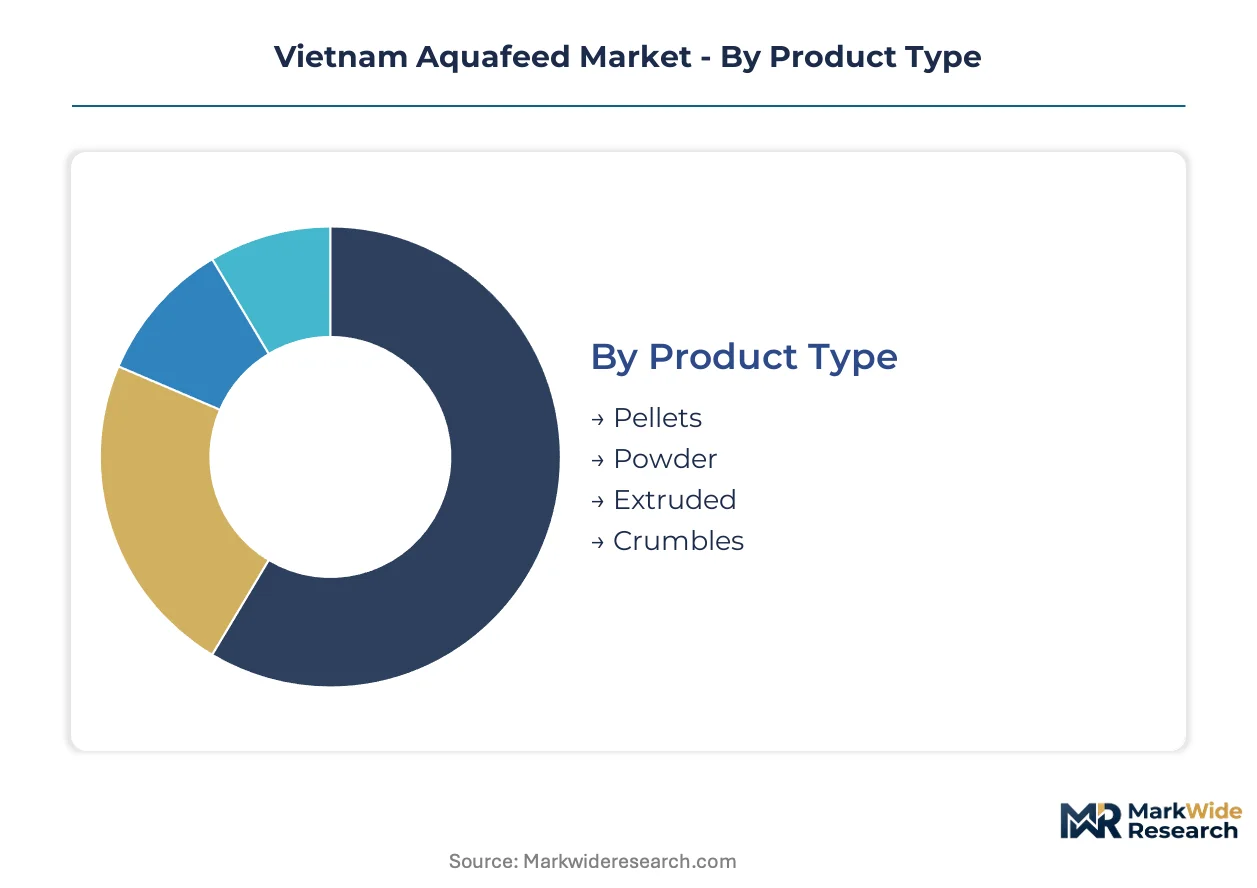
Vietnam's aquafeed segmentation reflects the country's dual focus on export-grade pangasius and shrimp production. Product formats and ingredient sourcing strategies diverge sharply between Mekong Delta freshwater operations and south-central coastal marine farming.
Product Type:
Supply concentration tilts toward extrusion capacity as industrial-scale farms displace smallholder mixing practices across An Giang and Dong Thap provinces.
- Pellets:Compressed cylindrical feeds with 2-8mm diameters dominate pangasius grower ponds across the Mekong Delta. An Giang province accounts for the heaviest offtake as consolidation into 10-hectare-plus operations accelerates demand for standardized sinking pellets with documented feed conversion ratios.
- Extruded:High-temperature processed feeds achieve superior water stability and lipid encapsulation for intensive shrimp ponds in Bac Lieu and Ca Mau. Khanh Hoa's emerging seabass cage sector is absorbing new extrusion lines as coastal farmers convert from trash fish to formulated diets.
- Crumbles:Fragmented extrudate serves larval and post-larval stages in shrimp hatcheries requiring precise particle sizing.
- Powder:Unprocessed meal blends persist among residual smallholder operations in Vinh Long and Can Tho provinces lacking access to pelleting equipment.
Pellets absorb the bulk of installed capacity; extruded formats are expanding most quickly as shrimp and marine fish intensification accelerates.
Ingredient:
Cost tier stratification separates premium marine formulations from commodity freshwater diets as protein source substitution reshapes procurement patterns.
- Fish Meal:Peruvian anchovy-derived protein concentrate commands premium pricing in shrimp broodstock and early-stage feeds. Import dependency creates margin volatility for Mekong Delta mills serving export-certified supply chains.
- Soybean Meal:Solvent-extracted protein at 44-48% crude protein dominates pangasius grower formulations. Vietnamese crush capacity constraints force reliance on Argentine and Brazilian imports, exposing formulations to currency and freight fluctuations.
- Corn Gluten Meal:Yellow pigment-rich byproduct from wet milling serves niche applications in ornamental fish and premium marine species requiring carotenoid enhancement.
- Wheat Germ:Vitamin E and essential fatty acid source finds limited use in high-value koi and aquarium fish feeds produced by specialty mills in Ho Chi Minh City industrial zones.
Soybean meal absorbs the bulk of installed capacity; fish meal substitution is climbing the fastest as single-cell protein technologies achieve scale.
End User:
Customer type fragmentation is concentrating toward vertically integrated aquaculture farms as independent feed mills face Circular 24 traceability compliance burdens.
- Aquaculture Farms:Industrial-scale pond and cage operators in Dong Thap and Khanh Hoa negotiate direct mill contracts embedding technical service teams. These farms now represent the primary volume channel as distributor networks contract.
- Fish Hatcheries:Post-larval and fry production facilities in Bac Lieu province demand micronized crumbles with documented probiotic inclusion and zero antibiotic residues.
- Feed Mills:Independent toll manufacturers in Can Tho province serve residual smallholder cooperatives lacking extrusion capability but facing margin compression from integrated competitors.
- Research Institutions:Can Tho University and Nha Trang University aquaculture departments pilot experimental formulations with novel protein sources, representing minimal commercial volume but technology transfer significance.
Aquaculture farms absorb the bulk of installed capacity; fish hatcheries are gaining share fastest as shrimp larval production consolidates toward biosecure facilities.
Application:
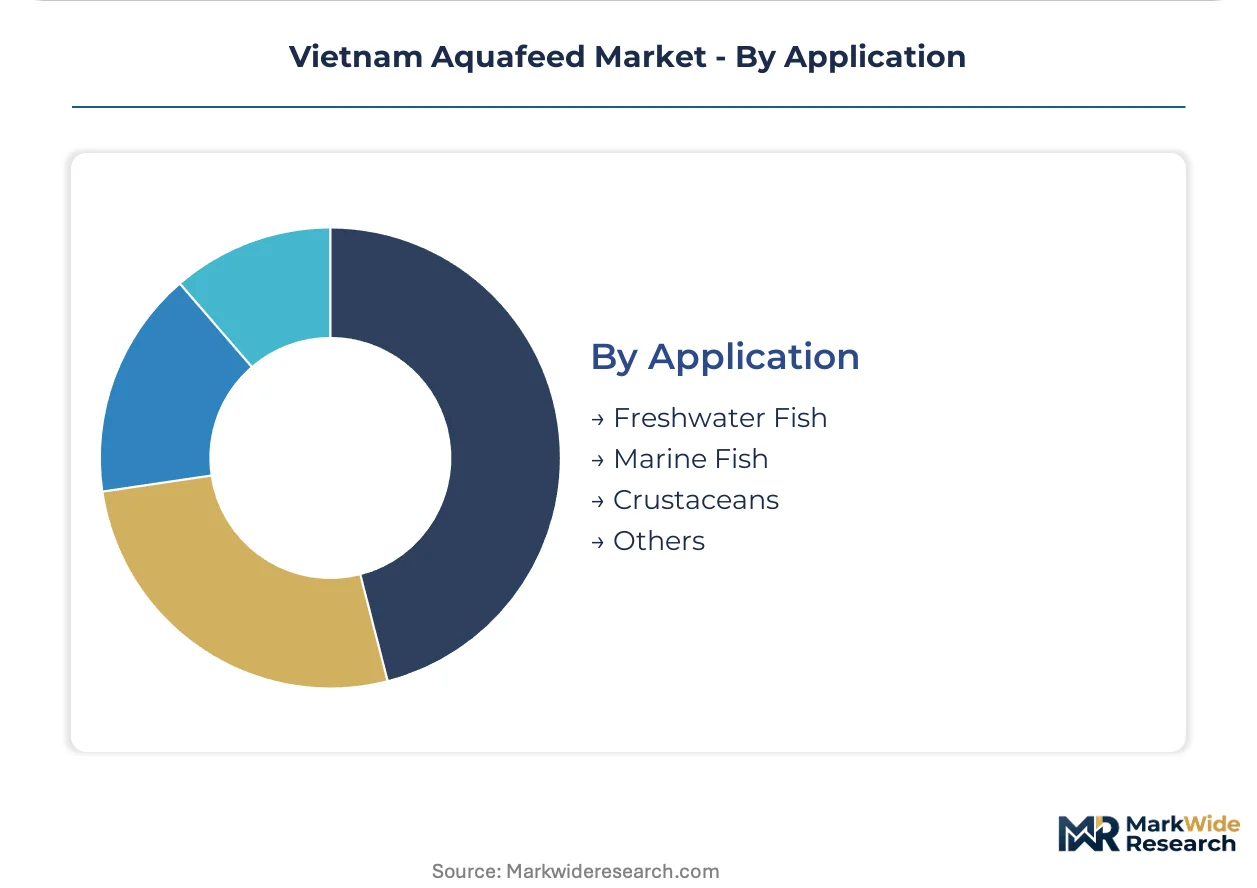
Geography drives application segmentation as freshwater pangasius concentration in the Mekong Delta diverges from marine shrimp expansion along the central coast.
- Freshwater Fish:Pangasius dominates tonnage, with striped catfish feeds formulated for 28-32% protein in grower stages across An Giang and Dong Thap provinces. Circular 24 antibiotic restrictions have forced reformulation toward acidifier and probiotic additives.
- Crustaceans:Whiteleg shrimp and black tiger shrimp feeds require 35-42% protein with cholesterol and phospholipid supplementation. Bac Lieu and Ca Mau provinces concentrate demand as intensive pond systems replace extensive mangrove-based production.
- Marine Fish:Seabass, grouper, and cobia cage culture in Khanh Hoa and Phu Yen provinces drives demand for high-lipid floating feeds with superior water stability.
- Others:Ornamental fish and frog farming in Mekong Delta periphery zones represent fragmented, low-volume demand served by specialty regional mills.
Freshwater fish absorbs the bulk of installed capacity; crustaceans are expanding most quickly as export-oriented shrimp farming intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean crushing capacity in the Mekong Delta anchors Vietnamese aquafeed production geography. Provincial feed mill clusters concentrate where pangasius pond density peaks and coastal shrimp hatcheries proliferate.
An Giang Province
Industrial pangasius pond consolidation drives extruded feed demand across 10-hectare-plus operations. Circular 24 antibiotic residue enforcement compels mills to document batch-level traceability through blockchain-anchored platforms. Long Xuyen industrial zones host Charoen Pokphand Group's integrated hatchery-to-harvest facilities.
Dong Thap Province
Direct mill-to-farm contracting displaces traditional distributor networks among export-certified farms. The Ministry of Agriculture and Rural Development mandates veterinary prescription systems for therapeutic additives. Cao Lanh district concentrates De Heus technical sales teams embedded with medium-scale growers.
Bac Lieu Province
Intensive whiteleg shrimp pond systems replace extensive mangrove-based production across coastal districts. Circular 24 compliance costs drive consolidation toward vertically integrated operations with captive laboratory testing. Ganh Hao industrial clusters absorb premium marine formulations with cholesterol and phospholipid supplementation.
Khanh Hoa Province
Seabass and grouper cage culture expansion creates demand for high-lipid floating feeds with superior water stability. Nha Trang Bay aquaculture zones convert from trash fish to formulated diets as marine species intensification accelerates. Cargill deploys species-specific formulation services directly to floating cage operations.
Ca Mau Province
Black tiger shrimp hatcheries demand micronized crumbles with documented probiotic inclusion and zero antibiotic residues. Provincial biosecure facilities consolidate larval production as smallholder fragmentation limits batch-level documentation compliance. Nam Can district hosts emerging recirculating aquaculture system pilots requiring specialized low-waste extruded diets.
Vietnam Aquafeed Market Key Industry Players
Global majors compete with regional champions across formulation expertise and technical service density. The vendor base separates into integrated agribusiness conglomerates, specialized aquaculture nutrition houses, and toll manufacturers serving residual cooperatives. Three archetypes dominate: hatchery-to-harvest integrators, species-specific formulation specialists, and commodity-scale feed compounders. Competitive moves concentrate on backward integration into protein sourcing and direct mill-to-farm channel displacement of distributor networks.
Within the integrated agribusiness tier, Charoen Pokphand Group exemplifies the hatchery-to-harvest model across Mekong Delta provinces. De Heus occupies a position among medium-scale pangasius growers through dense technical sales networks. Cargill anchors the species-specific service archetype with direct formulation delivery to coastal cage operations. These three companies represent distinct competitive vectors: vertical control, technical intimacy, and marine specialization.
| Leading Market Players |
|---|
| Nutreco |
| BASF SE |
| Charoen Pokphand Group |
| De Heus |
| Alltech |
| Archer Daniels Midland |
| Biomin GmbH |
| Aller Aqua |
| Cargill |
| Others |
Cost & Logistics Intelligence
Circular 24 antibiotic residue mandates from Vietnam's Ministry of Agriculture and Rural Development are forcing feed mills to absorb reformulation costs and rebuild documentation systems, compressing margins across commodity pangasius formulations while opening premium pricing for certified traceable supply chains.
Pricing Analysis
Technical service bundling separates De Heus and Cargill offerings from unbundled commodity suppliers serving price-sensitive smallholders. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with EU-export-certified farms paying substantial premiums for blockchain-anchored batch documentation. Cost compression in economy-tier pangasius feeds is intensifying because single-cell protein substitution has not yet achieved full cost parity with Peruvian fish meal. Independent cooperatives in Vinh Long exhibit the highest price sensitivity, while vertically integrated operators in Dong Thap prioritize feed conversion ratio guarantees over per-kilogram pricing.
Supply Chain Analysis
Direct mill-to-farm contracting handles industrial-scale buyer demand across An Giang and Dong Thap, displacing traditional distributor networks. Raw material sourcing draws from Argentina and Brazil for soybean meal, Peru for anchovy-derived fish meal, and domestic fermentation facilities for emerging single-cell protein. Supply chain risk centers on Mekong Delta flood exposure concentrated in An Giang and Dong Thap provinces, where monsoon disruptions create logistics bottlenecks during peak demand windows. Distribution runs through embedded technical sales teams for large operators, with residual cooperatives served by toll manufacturers in Can Tho.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as Circular 24 traceability burdens force sub-scale mills and unconsolidated smallholders toward exit or acquisition by integrated operators with captive laboratory testing capacity.
For Market Incumbents: Acquire fermentation assets and on-site single-cell protein capacity to reduce Peruvian fish meal dependency. Charoen Pokphand Group's integrated hatchery-to-harvest model demonstrates how backward integration into protein sourcing defends formulation margins against import volatility. Prioritize direct mill-to-farm contracting in Dong Thap to lock in export-certified volume before distributor networks fully collapse. For New Entrants and Emerging Players: Medium-scale pangasius growers in Vinh Long and Can Tho lacking technical service support represent the most penetrable buyer archetype. These operators face Circular 24 compliance gaps but resist premium pricing from established players. A mobile technical service team model with app-based procurement platforms offers a viable go-to-market angle, compressing legacy distributor margins while delivering traceability documentation. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated aquaculture operations with captive feed mills given accelerating consolidation pressure from antibiotic residue enforcement. Long-term viability favors targets with biosecure hatchery assets and established EU export certification. Monitor Circular 24 enforcement intensity in Bac Lieu shrimp hatcheries as the inflection indicator for compliance cost trajectories and consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Sourcing | On-site fermentation capacity reduces exposure to Peruvian anchovy catch volatility and currency fluctuations. |
| Blockchain-Anchored Traceability Platform | Circular 24 compliance requires batch-level documentation systems that smaller mills cannot independently deploy. |
| Direct Mill-to-Farm Contracting | Embedded technical service teams in Dong Thap displace distributor networks among export-certified operations. |
| Recirculating Aquaculture System Feed Development | Specialized low-waste extruded diets address emerging demand from industrial zone pilots in Nam Can district. |
| Digital Procurement Platform Launch | App-based bulk ordering systems in Can Tho and Vinh Long compress distributor margins and improve price transparency. |
Research Approach
Document review covered Vietnamese regulatory filings, EU import standard documentation, and Peruvian anchovy catch reports, complemented by interviews with feed mill operations managers, pangasius farm technical directors, shrimp hatchery biologists, and Ministry of Agriculture enforcement officers. Secondary validation drew from customs trade data, Circular 24 implementation guidance, and provincial agricultural statistics. Bottom-up volume estimates from individual mill capacity and top-down demand calculations from pond acreage expansion were triangulated to produce convergent market sizing.
Segment-level projections across product type, ingredient composition, end user category, and application geography were generated through the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical feed offtake against pond intensification rates and export volume growth. Key inputs included soybean meal import price trajectories, Circular 24 enforcement intensity assumptions, and single-cell protein cost parity timelines.
Revisions become necessary when antibiotic residue enforcement intensity exceeds baseline assumptions, when flood disruption frequency in the Mekong Delta accelerates beyond historical patterns, or when single-cell protein technologies achieve faster cost reduction than modeled. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Perch Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
North America Shrimp Feed Market