
 South America Feed Minerals Market | 2026-2036
South America Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Minerals Market Analytics
Modular premix configurations is broadening buyer choice across the South America Feed Minerals Market. Cargill Inc leverages its integrated supply chain to dominate bulk mineral distribution in Brazil. BASF SE anchors its position through specialized chelated mineral R&D. Nutreco NV differentiates via tailored trace element programs for large poultry integrators.
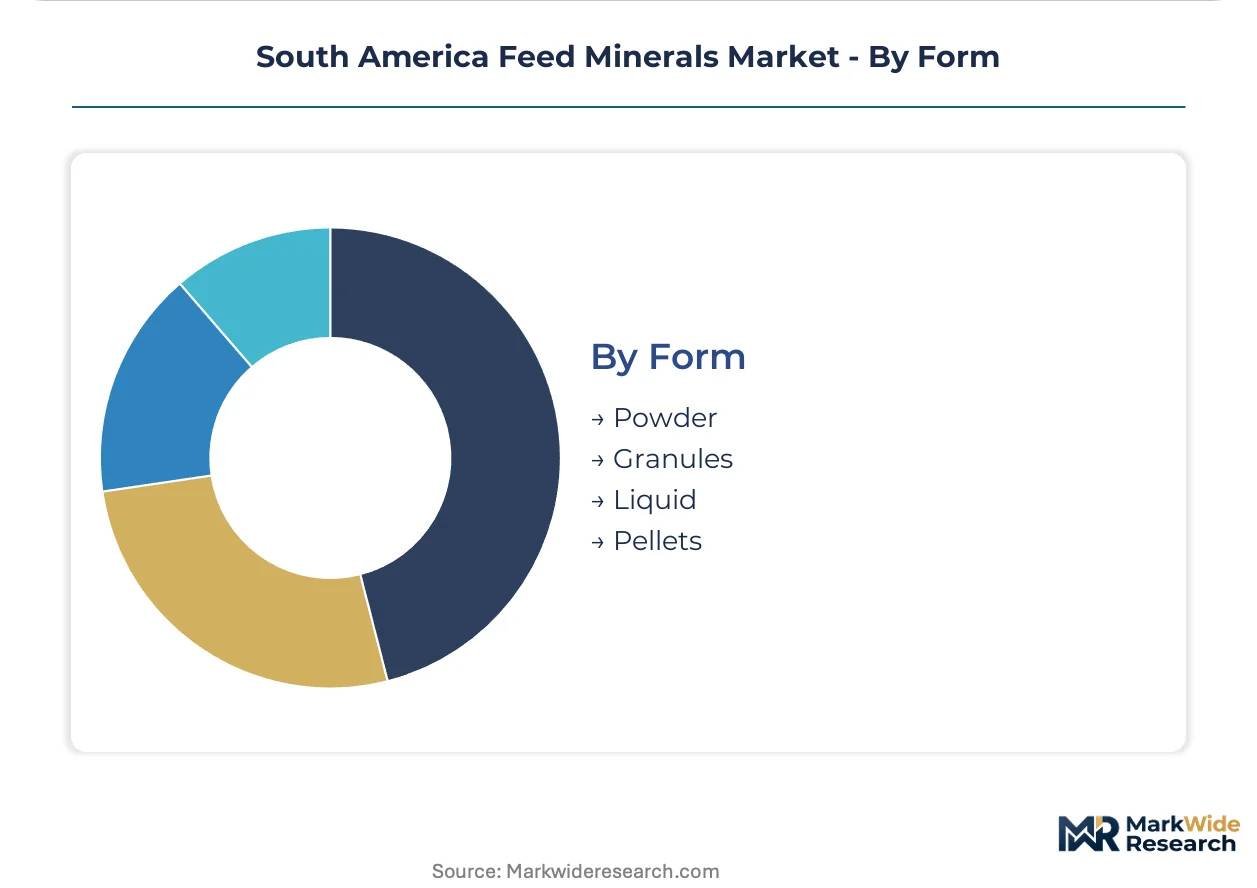
Feed minerals comprise inorganic and organic compounds including macro-minerals, trace elements, and chelated forms, typically formulated at inclusion rates between 0.01% and 1% of total feed weight to optimize metabolic function and prevent deficiency disorders in livestock. The primary commercial purpose centers on converting feed energy into productive output while maintaining herd health economics. Mineral Supplements capture the largest revenue pool due to established ruminant demand, while Chelated Minerals represent the fastest-expanding category as Brazilian producers pursue bioavailability premiums. Powder formulations maintain volume leadership, though Liquid forms gain share in automated dosing systems across industrial feed mills.
ANVISA in Brazil and SENASA in Argentina enforce residue limits and feed additive registrations that directly determine which mineral sources gain market access. Brazil's MAPA mandates on feed traceability and Argentina's evolving SENASA protocols on mineral maximum levels shape product portfolios and import substitution patterns. Stakeholders must monitor how pending regulatory harmonization across Mercosur feed standards will reshape cross-border mineral trade and local manufacturing requirements.
Market Dynamics
Brazil's MAPA traceability mandates for feed additives are forcing mineral premix suppliers to reconfigure formulation architectures and documentation systems across the entire supply chain. This regulatory pressure concentrates competitive advantage among suppliers with integrated quality assurance infrastructure.
Growth Catalysts
- Precision livestock farming:Brazilian poultry integrators deploy sensor-driven mineral dosing systems that optimize feed conversion ratios in real-time. This technology pull accelerates demand for bioavailable chelated forms.
- ANVISA residue limit harmonization:Brazil's pharmaceutical regulator tightens enforcement on mineral maximum levels in animal products, compelling feed mills to upgrade premix specifications.
- Southern soybean-livestock belt concentration:Feed production clusters in Paraná, Santa Catarina, and Rio Grande do Sul create dense demand nodes that reward localized mineral blending capacity.
Market Restraints
- Sulfate and oxide raw material volatility:Copper, zinc, and manganese sulfate prices fluctuate with Chinese smelter output and shipping rates through the Panama Canal.
- Import dependency for organic mineral ligands:Glycinates and proteinates rely on specialized amino acid precursors concentrated in European and Asian manufacturing bases.
- SENASA registration timelines in Argentina:The national agri-food safety service maintains multi-year approval queues for novel mineral sources that delay product launches.
Strategic Opportunities
- Uruguayan beef export premium channel:Grass-fed certification programs for EU and US markets create demand for selenium and cobalt supplementation in pasture-based systems.
- Chilean salmon aquaculture mineralization:Marine feed producers seek specialized trace element programs to address osmoregulation and immune function in intensive net-pen operations.
- Mercosur regulatory convergence:Pending harmonization of feed additive standards across Brazil, Argentina, Paraguay, and Uruguay will enable single-registration product portfolios.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities produce insufficient graduates with dual competency in animal nutrition and analytical chemistry to staff quality control laboratories.
- Legacy ERP integration with traceability platforms:Mid-sized feed mills struggle to connect MAPA-mandated digital documentation systems to existing inventory management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Minerals Market |
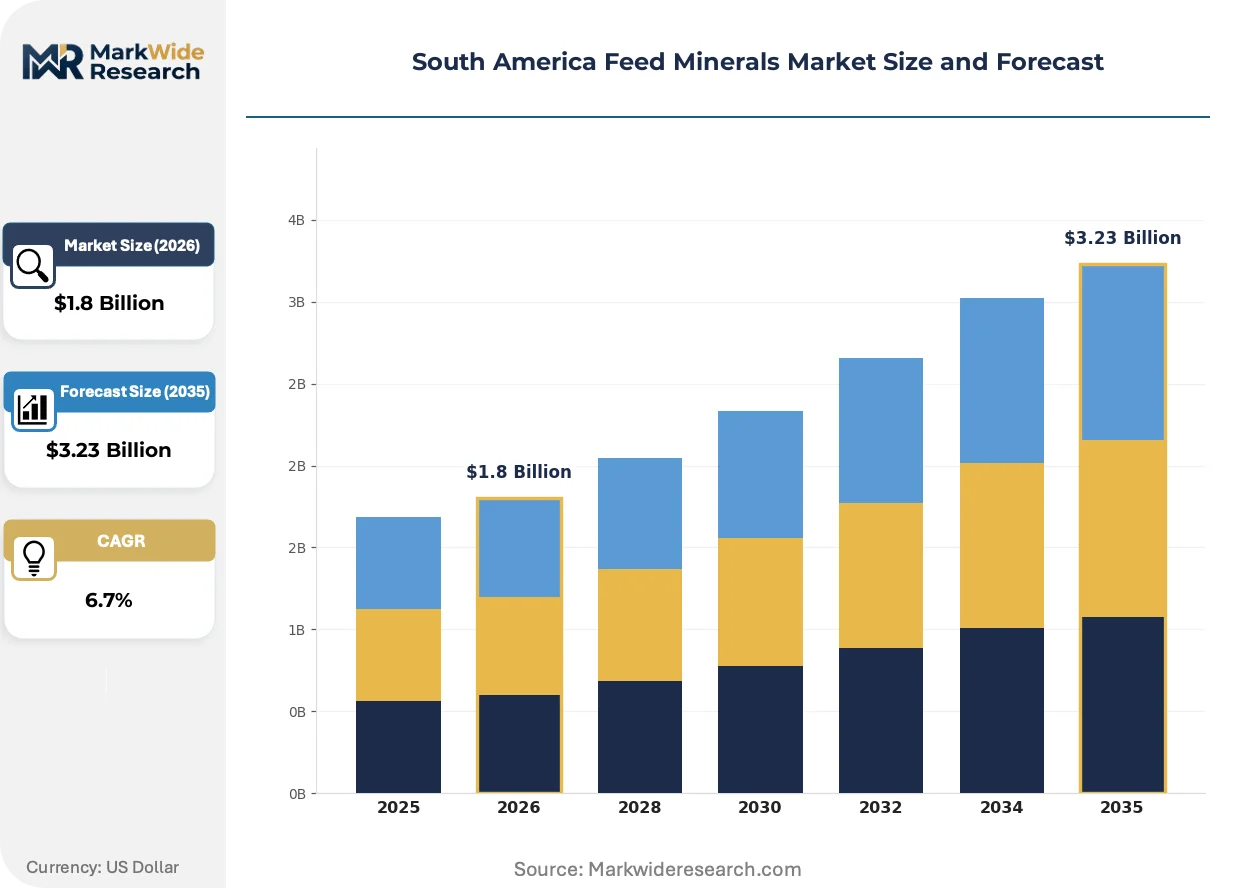
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Supplements, Trace Elements, Vitamins, Chelated Minerals Application: Ruminants, Poultry, Swine, Aquaculture End User: Farms, Feed Manufacturers, Distributors, Animal Breeders Form: Powder, Granules, Liquid, Pellets |
| Companies Covered | Cargill Inc, BASF SE, Nutreco NV, ADM, Kemin Industries, DSM Animal Nutrition, Zinpro Corporation, Novus International Inc, Pancosma SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Minerals Market Evolving Landscape
Mineral bioavailability engineering is displacing commodity-grade sourcing as the primary competitive axis in South American feed formulation. Suppliers now compete on metabolic efficiency metrics rather than elemental concentration alone.
Chelated glycinate and methionine-complexed minerals are unifying the previously separate categories of nutrition and pharmaceutical-grade supplementation. Large Brazilian poultry integrators adopt these forms at inclusion rates below traditional inorganic sources. This unification compresses the premium gap between standard and performance-grade mineral portfolios.
ANVISA's 2023 updated guidance on feed additive residue monitoring extends testing protocols to imported premix shipments. Argentine and Uruguayan mills serving export markets must now document mineral provenance through certified laboratory chains. The poultry segment bears the heaviest compliance burden due to short production cycles and rapid tissue residue accumulation risks.
Direct mill procurement of mineral premixes is consolidating previously fragmented distributor networks. Brazilian cooperatives and independent feed manufacturers now source trace element programs through technical service agreements with multinational suppliers, bypassing traditional regional distributors. This channel compression concentrates most visible in Santa Catarina's integrated pork production corridor.
South America Feed Minerals Market Segmentation
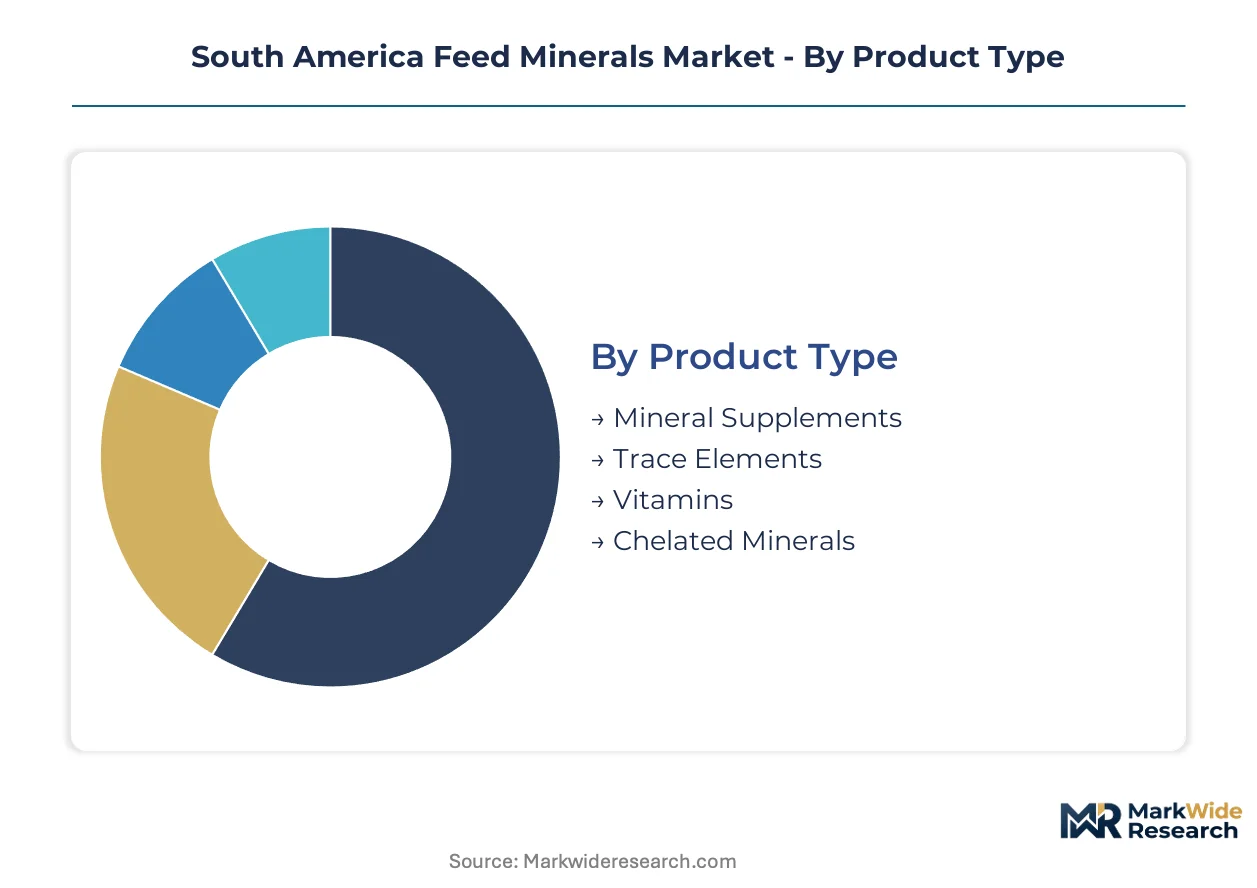
Feed mineral purchasing in South America follows distinct decision hierarchies across livestock species, formulation chemistry, and supply chain position. Buyers optimize for bioavailability thresholds, regulatory compliance burdens, and integration with automated dosing infrastructure.
Product Type:
Formulation chemistry determines price positioning and metabolic efficiency claims in Brazilian and Argentine procurement decisions.
- Mineral Supplements:Macro-mineral blends containing calcium, phosphorus, and magnesium dominate commercial ruminant rations across Brazil's southern states. Dairy cooperatives in Paraná specify these formulations for lactation support and skeletal maintenance in high-yielding Holstein herds.
- Chelated Minerals:Organic complexes with glycine or methionine ligands deliver superior absorption rates in poultry metabolism. Brazilian integrators in Santa Catarina deploy these forms to reduce environmental mineral excretion while maintaining feed conversion ratios under ANVISA residue monitoring protocols.
- Trace Elements:Selenium, cobalt, and iodine formulations target specific deficiency correction in pasture-based Uruguayan beef systems.
- Vitamins:Fat-soluble and water-soluble vitamin premixes complement mineral programs in swine starter feeds.
Volume sits with Mineral Supplements; growth tilts toward Chelated Minerals.
Application:
Species-specific metabolic demands create diverging mineral specification requirements across livestock categories.
- Poultry:Broiler and layer operations require precision trace element dosing to optimize feed conversion and eggshell quality. Brazilian integrators in Rio Grande do Sul source chelated zinc and manganese to support rapid growth phases while complying with MAPA traceability documentation mandates.
- Ruminants:Beef and dairy cattle depend on macro-mineral supplementation to balance high-grain finishing diets and pasture deficiencies. Argentine feedlots in Buenos Aires province specify calcium-phosphorus ratios to prevent metabolic disorders in Angus crossbreeds.
- Swine:Growing-finishing pigs require copper and zinc programs for growth promotion within SENASA residue limits.
- Aquaculture:Chilean salmon producers seek specialized selenium and iodine formulations for immune function in marine net-pen environments.
Revenue concentrates in Poultry; steepest expansion trajectory runs through Aquaculture.
End User:
Supply chain position determines technical service requirements and procurement scale economies.
- Feed Manufacturers:Industrial mills in Brazil's southern soybean-livestock belt purchase bulk mineral premixes for custom formulation. These buyers demand integrated quality assurance systems that interface directly with MAPA-mandated traceability platforms.
- Farms:Large integrated operations in Mato Grosso do Sul source direct from multinational suppliers, bypassing traditional distribution channels.
- Distributors:Regional wholesalers serve fragmented smallholder markets in Paraguay and Uruguay with standardized mineral packages.
- Animal Breeders:Genetic nucleus farms specify premium chelated programs for breeding stock performance.
Procurement scale favors Feed Manufacturers; margin expansion concentrates with Farms.
Form:
Physical presentation dictates handling infrastructure and dosing precision capabilities.
- Powder:Fine-ground mineral blends remain the default for manual mixing operations and smaller feed mills across Argentina's interior provinces. These formulations require dust control systems and present homogeneity challenges in low-inclusion applications.
- Liquid:Suspended mineral solutions integrate with automated dosing systems in Brazilian industrial feed mills. Poultry integrators in Santa Catarina specify liquid chelated programs for real-time feed conversion optimization through sensor-driven inclusion rate adjustments.
- Granules:Agglomerated forms reduce dust and improve flowability in mechanical handling systems.
- Pellets:Compressed mineral blocks serve pasture-based Uruguayan beef operations for free-choice supplementation.
Shipment volumes cluster in Powder; technology migration favors Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes the majority of feed minerals produced across South America, yet Argentina and Chile generate significant export-oriented demand that shapes regional trade flows. Production clusters concentrate in Brazil's southern states where soybean processing and livestock integration create dense supply nodes.
Brazil
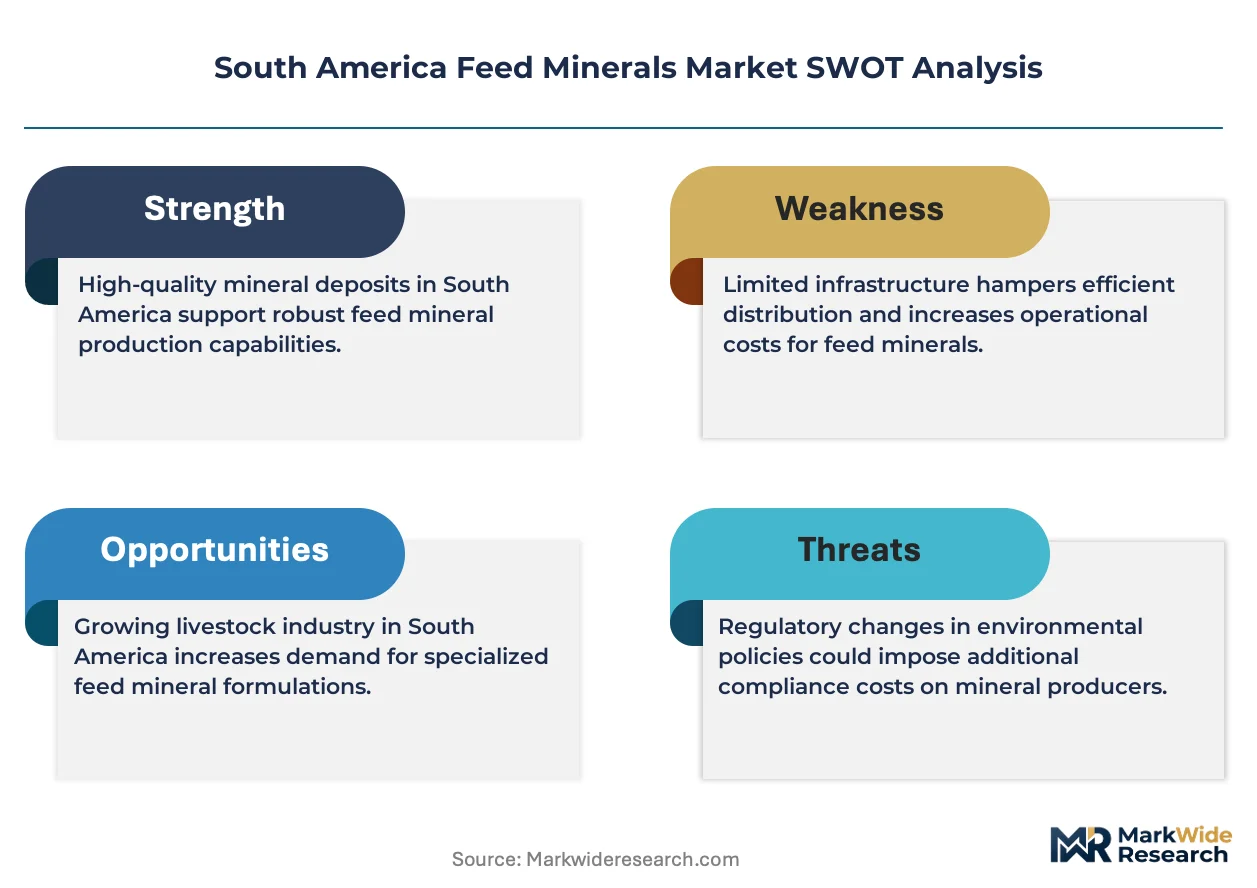
Poultry integrators in Santa Catarina and Rio Grande do Sul deploy precision mineral dosing systems for real-time feed conversion optimization. ANVISA residue limit harmonization compels feed mills to upgrade premix specifications and documentation systems. The Paraná-Santa Catarina corridor hosts the densest concentration of industrial mineral blending capacity serving dairy cooperatives and pork production networks.
Argentina
Beef feedlots in Buenos Aires province specify calcium-phosphorus ratios to prevent metabolic disorders in high-grain finishing diets. SENASA maintains multi-year approval queues for novel mineral sources that delay product launches for international suppliers. The Pampas grassland region generates concentrated demand for pasture supplementation programs targeting export-certified herds.
Chile
Salmon aquaculture operations in the Los Lagos and Aysén regions seek specialized selenium and iodine formulations for immune function in intensive net-pen environments. The country's national pharmaceutical regulator enforces strict residue monitoring on marine feed additives. Puerto Montt anchors the southern salmon feed production cluster where mineral premixes integrate with automated marine feed mills.
Uruguay
Grass-fed beef certification programs for EU and US markets create demand for selenium and cobalt supplementation in pasture-based systems. The national agri-food safety service aligns mineral maximum levels with Mercosur harmonization protocols. Northern livestock departments concentrate free-choice mineral block distribution for extensive grazing operations.
Paraguay
Expanding soybean-livestock integration in the Eastern Region generates demand for bulk mineral premixes among emerging feed manufacturers. The central bank's trade financing programs support import substitution for previously sourced Argentine mineral blends. Ciudad del Este serves as a distribution node for cross-border mineral trade serving Brazilian border states.
South America Feed Minerals Market Competitive Landscape
The competitive structure tilts toward integrated multinational suppliers with captive quality assurance infrastructure. Brazilian and Argentine markets reward players with direct technical service relationships to large poultry integrators and dairy cooperatives. Three archetypes dominate: diversified agribusiness conglomerates with mineral distribution networks, specialized chelated mineral developers, and regional premix blenders serving fragmented farm segments. Capacity expansion and backward integration into raw mineral sourcing represent the dominant competitive moves reshaping supply security.
Within the diversified agribusiness tier, Cargill Inc and ADM exemplify players leveraging integrated supply chains to dominate bulk mineral distribution across Brazil's southern soybean-livestock belt. BASF SE and DSM Animal Nutrition occupy positions among specialized chelated mineral developers, anchoring premium product portfolios through bioavailability-focused formulation capabilities. Nutreco NV represents the technical service archetype, embedding tailored trace element programs directly within large poultry integrator operations.
| Leading Market Players |
|---|
| Cargill Inc |
| BASF SE |
| Nutreco NV |
| ADM |
| Kemin Industries |
| DSM Animal Nutrition |
| Zinpro Corporation |
| Novus International Inc |
| Pancosma SA |
| Others |
Value Network & Pricing Analysis
Chelated mineral premiums over inorganic sulfates bifurcate procurement decisions across Brazilian feed mills, with bioavailability-grade formulations commanding technical service bundling while commodity oxides flow through bulk distributor networks. This tier divergence concentrates margin capture among suppliers with captive ligand production, forcing mid-tier blenders into price-competitive sulfate sourcing.
Pricing Analysis
Cost-down pressure on standard mineral sulfates accelerates because Brazilian poultry integrators consolidate procurement through direct mill agreements, compressing distributor markups. Three-tier pricing structure across premium chelates, standard sulfates, and economy oxides stratifies by ANVISA certification grade and MAPA traceability documentation depth. Price differentiation hinges on glycinate ligand sourcing and automated dosing compatibility. Smallholder cooperatives in Paraguay exhibit highest price sensitivity; large Santa Catarina integrators prioritize feed conversion metrics over unit cost.
Supply Chain Analysis
Copper and zinc sulfate supply rests on Chinese smelter output concentrated in Jiangxi and Yunnan provinces, with glycinate and methionine ligand production anchored in European and Asian amino acid manufacturing bases. Raw material dependencies span manganese ore from Gabon, selenium from Canada, and specialized proteinates from Western European chemical producers. Single-source vulnerability concentrates in organic mineral ligand streams subject to shipping rate volatility through the Panama Canal. Distribution runs through Brazilian cooperative networks and direct technical service agreements with multinational premix suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into glycinate ligand production and captive quality assurance infrastructure represents the dominant competitive race across South American feed minerals, with MAPA traceability mandates rewarding players who control documentation systems from raw material to finished premix.
For Market Incumbents: Cement supply security through backward integration into amino acid ligand manufacturing or long-term offtake agreements with European specialty chemical producers. Defend against emerging regional blenders by embedding MAPA-compliant digital traceability platforms directly within customer ERP systems. Prioritize certification investment in ANVISA residue testing protocols to maintain access to export-oriented poultry integrators. For New Entrants and Emerging Players: Enter via white-space targeting of Uruguayan grass-fed beef certification programs and Chilean salmon aquaculture mineralization, where specialized selenium and iodine formulations face limited domestic competition. Paraguay's emerging soybean-livestock belt offers the most penetrable geography, with feed manufacturers seeking import-substituted mineral blends. Pursue technical service partnerships with regional distributors possessing established SENASA registration capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale chelated mineral developers possessing proprietary glycinate complexing technology given ANVISA's tightening residue enforcement. Long-term viability favors players with dual-competency formulation chemists and integrated quality assurance infrastructure spanning Brazil and Argentina. Watch SENASA registration queue clearance rates as the inflection signal for Argentine market access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ligand Production | Captive glycinate sourcing insulates margins from European amino acid price volatility and shipping disruptions. |
| MAPA Traceability Platform Deployment | Digital documentation systems lock in Brazilian poultry integrators through compliance-embedded procurement contracts. |
| Regional Blending Capacity Expansion | Localized production in Paraná and Santa Catarina reduces logistics costs to dense soybean-livestock belt customers. |
| SENASA Registration Acceleration | Novel mineral source approvals in Argentina unlock access to Buenos Aires province feedlot demand. |
| Technical Service Agreement Scaling | Direct mill relationships bypass distributor networks and capture margin from precision dosing system integration. |
Research Methodology
Trade databases, ANVISA registration filings, and MAPA traceability protocol documentation formed the secondary backbone, cross-referenced with primary interviews involving feed mill procurement directors, poultry integrator nutritionists, and Argentine SENASA regulatory affairs specialists. Bottom-up volume modeling triangulated against top-down macro-mineral consumption estimates derived from livestock population data and feed conversion ratio benchmarks across the analysis window.
Historical mineral premix pricing trajectories and chelated mineral adoption curves informed the projection framework, with segmentation across formulation chemistry, livestock species application, and supply chain position modeled throughout the forecast period. CAGRs were derived from regression analysis of feed production growth, regulatory enforcement intensity, and bioavailability premium compression trends. Key inputs included ANVISA residue limit revision schedules and Mercosur harmonization protocol advancement indicators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese sulfate export restriction scenarios or Panama Canal logistics disruptions. Projections reflect assumptions on MAPA digital traceability implementation timelines and SENASA registration queue processing rates. ANVISA enforcement intensity, Chinese smelter output volatility, and Mercosur regulatory convergence advancement warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market