
 Agricultural Coatings Market | 2026-2036
Agricultural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Coatings Market Analysis
Specialty distributor networks for agricultural inputs is tilting toward consolidated procurement platforms serving major farming cooperatives. BASF SE leverages its integrated seed-and-chemistry pipeline to control coating formulation supply from polymer synthesis through field delivery. Bayer AG anchors its position through deep R&D intensity in biodegradable film coatings. Corteva Agriscience competes by specializing in trait-stacked seed coatings that align with proprietary genetics.
Agricultural coatings are functional barrier layers applied to seeds, fertilizers, or agrochemical granules, typically comprising polymer binders, colorants, and active ingredients at thicknesses of 5–50 microns to control release, improve adhesion, or protect against environmental stress. Their primary purpose is to enhance input efficiency and reduce off-target application losses in commercial crop production. Pesticide coatings dominate current volume flows, while herbicide coatings capture expanding margin pools as no-till farming expands. Specialty stores still handle the bulk of farmer-facing transactions, though distributor consolidation is shifting procurement power toward larger agricultural companies.
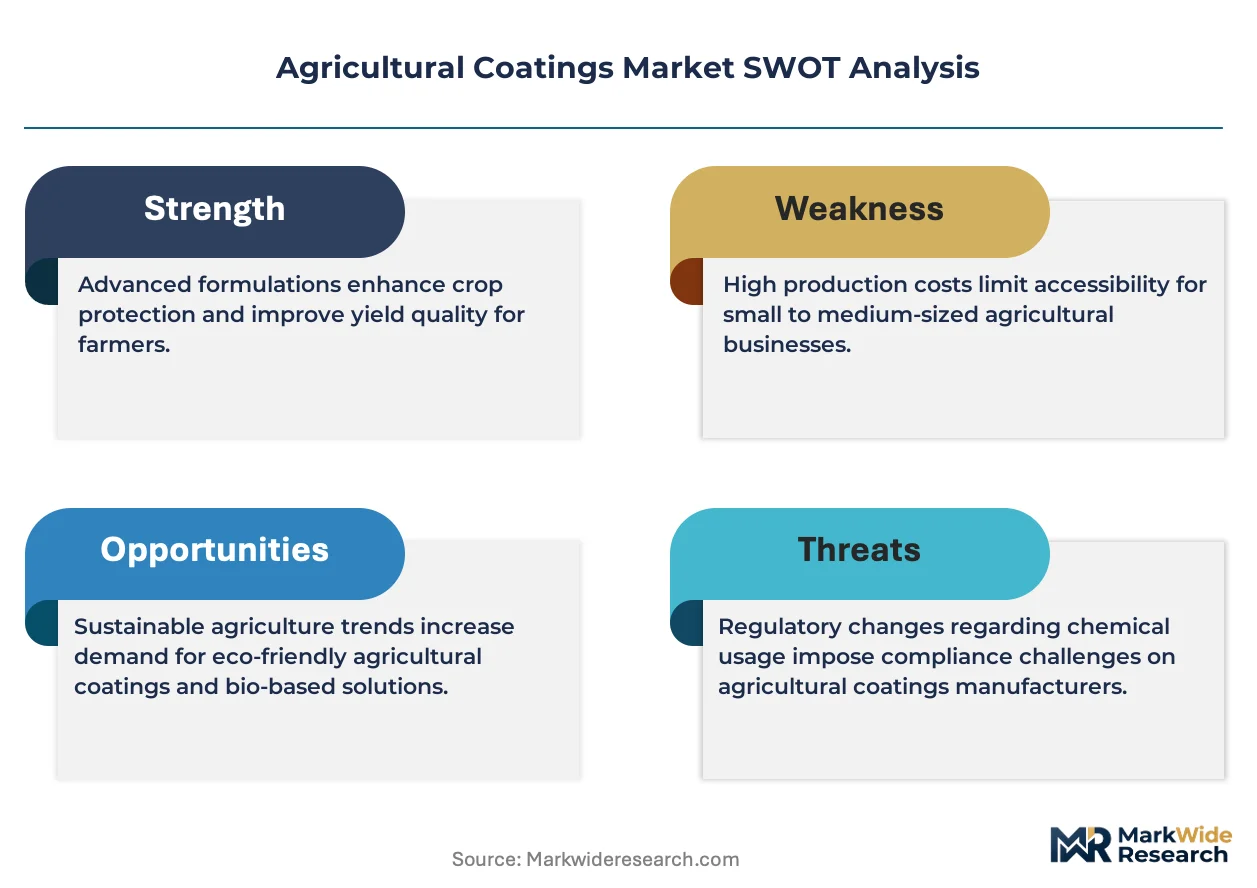
EPA registration requirements under FIFRA govern active ingredient incorporation into seed coatings in the United States, while REACH compliance in Europe restricts certain polymer chemistries used in coating matrices. Brazil's national agricultural regulator enforces residue thresholds that shape which coating technologies gain market access in its soybean and corn sectors. Stakeholders must monitor how diverging regulatory stringency across these jurisdictions influences formulation R&D priorities and regional manufacturing placement decisions.
Market Dynamics
Seed treatment consolidation among Brazilian soybean cooperatives is compressing formulation margins while elevating technical service requirements for coating suppliers.
Growth Catalysts
- No-till farming expansion:Reduced soil disturbance protocols in Argentina and Paraguay accelerate herbicide-coated seed demand as primary weed control vectors.
- REACH polymer restrictions:ECHA's phased limitations on conventional binder chemistries force European formulators toward bio-based alternatives, creating premium positioning opportunities.
- Climate stress adaptation:Drought-resistant film coatings gain traction in Australia's wheat belt where moisture retention determines yield stability.
Market Restraints
- Petrochemical input volatility:Polyurethane and acrylic binder costs fluctuate with crude oil indices, squeezing coating margin structures.
- Active ingredient concentration:EPA's FIFRA registration thresholds for neonicotinoid seed treatments limit formulation flexibility in US corn and soybean applications.
- Equipment compatibility gaps:Legacy seed treaters at smaller Brazilian farms cannot handle next-generation multi-layer coating viscosities.
Strategic Opportunities
- India's untapped rice sector:Coated seed penetration remains below 15% in eastern growing states, presenting volume expansion potential.
- Drone-compatible micro-granule coatings:Fertilizer coating formulations optimized for aerial application unlock precision agriculture workflows.
- EU Green Deal bio-input mandates:National subsidy frameworks for biodegradable coatings accelerate adoption in France and Germany.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in controlled-release polymer design concentrates at a handful of research institutions.
- Multi-jurisdiction registration timelines:Parallel EPA and ANVISA approval processes extend commercialization cycles for novel active-coating combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Coatings Market |
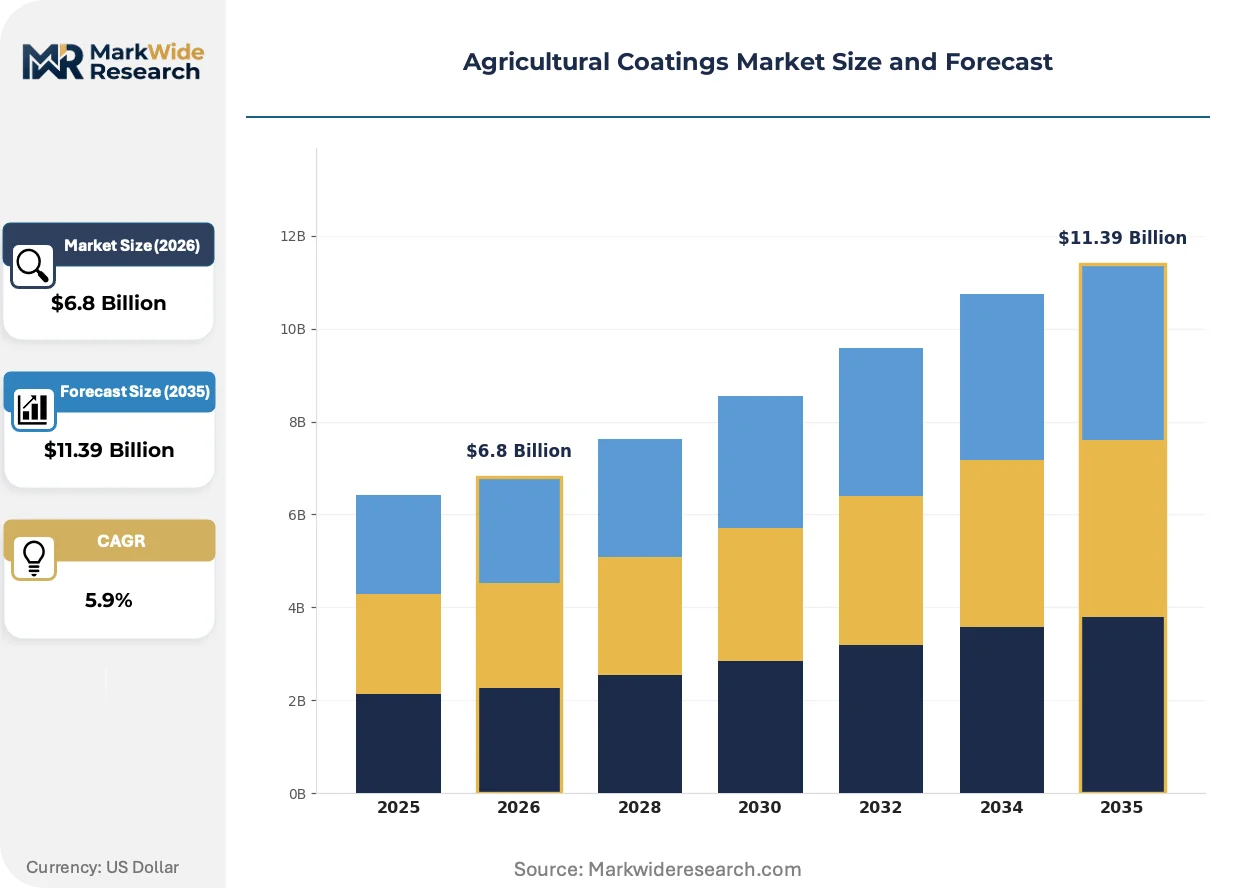
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Herbicides, Fungicides, Insecticides Application: Parks, Gardens, Farms, Horticulture Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors End User: Farmers, Agricultural Companies, Distribution Centers, Retailers |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta AG, Clariant AG, Croda International, Evonik Industries, FMC Corporation, Nippon Paint Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Coatings Market Emerging Trajectories
Coating functionality is migrating from passive protection toward active agronomic intervention, with formulation chemistry and application precision advancing in parallel.
Biodegradable film coatings derived from chitosan and lignin matrices are collapsing the historical trade-off between environmental persistence and field durability. Large-scale Brazilian soybean operations are adopting these materials at accelerating rates. The technology is collapsing regulatory compliance costs while opening premium pricing tiers previously reserved for conventional synthetic binders.
EPA's evolving pollinator risk assessment protocols for seed treatment dust drift are tightening label restrictions on neonicotinoid-coated corn and soybean seeds. Formulators must now demonstrate reduced abrasion potential and enhanced seed flowability to maintain registration eligibility. US Midwest distributors are restructuring inventory mixes toward lower-toxicity alternatives ahead of anticipated 2025-2026 label revisions.
Cooperative procurement platforms are consolidating farmer purchasing power across Brazil's Mato Grosso and Goiás states. Traditional independent distributors lose volume to vertically integrated buying groups that demand technical service bundling. This concentration is most visible in soybean seed coating contracts where cooperatives negotiate multi-year supply agreements with embedded agronomic advisory services.
Agricultural Coatings Market Segmentation
Segmentation in agricultural coatings reveals how formulation chemistry, application setting, and procurement channel each impose distinct technical and commercial requirements on suppliers. Understanding these divides clarifies where R&D investment concentrates versus where margin compression threatens.
Product Type:
Pesticide coatings turn over fastest in commercial corn and soybean operations where seasonal re-treatment cycles drive annual volume. Herbicide coatings move slower but command longer contract horizons as no-till systems lock farmers into multi-year weed management protocols. Fungicide and insecticide coatings occupy intermediate positions, with insecticide demand accelerating where pollinator risk assessments tighten.
- Pesticides:Polymer-bound active ingredient matrices applied at 10–30 microns thickness for controlled release of neonicotinoids or pyrethroids. Demand clusters in US Midwest corn operations where EPA dust drift regulations now mandate enhanced flowability specifications.
- Herbicides:Acrylic and polyurethane film systems engineered for abrasion resistance during mechanical planting. Brazilian Mato Grosso soybean cooperatives are expanding procurement of glyphosate-compatible coatings as no-till acreage deepens.
- Fungicides:Chitosan-lignin biodegradable matrices targeting soil-borne pathogens in humid growing regions.
- Insecticides:Micro-encapsulated formulations optimized for seed flowability under evolving pollinator protection protocols.
Pesticide coatings dominate installed base. Herbicide coatings are where expansion concentrates.
Application:
Cost tier separation is pronounced across application settings, with farm-scale operations absorbing premium multi-layer formulations while parks and gardens trade down to basic colorant-plus-binder systems.
- Farms:Precision-applied functional barriers at 15–50 microns integrating active ingredients, polymers, and flow agents for mechanized planting equipment. Australia's wheat belt is adopting drought-resistant film variants where moisture retention determines yield stability.
- Horticulture:Specialized coatings for greenhouse transplant stock requiring root-zone compatibility and controlled nutrient release. Netherlands glasshouse operations are specifying bio-based binders under EU Green Deal procurement mandates.
- Parks:Standardized colorant systems for turf grass and ornamental seed with minimal active ingredient loading.
- Gardens:Consumer-packaged coating kits emphasizing visual identification and basic fungal protection for home vegetable growers.
Farm applications capture the steepest expansion trajectory. Horticulture commands premium pricing tiers.
Distribution Channel:
Volume flow concentrates through distributor networks serving major cooperatives, while online retail captures emerging share in smaller-scale and specialty crop segments.
- Distributors:Vertically integrated procurement platforms consolidating seed-and-coating bundles for Brazilian soybean cooperatives and US Midwest farming operations. Technical service bundling now determines contract awards.
- Specialty Stores:Independent agricultural input retailers handling farmer-facing transactions with localized agronomic advisory. Share is compressing as cooperative buying groups centralize procurement.
- Online Retail:Direct-to-farmer platforms gaining traction in specialty vegetable seed and small-acreage operations.
- Supermarkets:Limited garden-center shelf space for consumer-oriented coating products.
Distributors dominate transaction value. Online retail is climbing the fastest.
End User:
Customer type determines service intensity, with agricultural companies demanding integrated formulation-to-field support while individual farmers prioritize price and equipment compatibility.
- Agricultural Companies:Large-scale operators and cooperatives specifying custom coating formulations aligned with proprietary seed genetics and precision planting systems. Brazil's expanding soybean belt is deepening penetration of trait-stacked coating bundles.
- Farmers:Individual producers selecting standard coating grades based on equipment compatibility and per-acre cost thresholds. Legacy seed treater limitations at smaller Brazilian farms constrain uptake of next-generation viscosities.
- Distribution Centers:Logistics hubs managing bulk coating application and inventory for regional supply networks.
- Retailers:Point-of-sale channels for packaged consumer and small-scale professional products.
Agricultural companies drive formulation innovation. Farmers represent volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazil's soybean belt while European formulators absorb compliance cost premiums under REACH polymer restrictions. This asymmetry reshapes regional manufacturing placement decisions as suppliers chase margin preservation.
United States
EPA's FIFRA registration thresholds for neonicotinoid seed treatments constrain formulation flexibility in corn and soybean applications. Dust drift protocols under evolving pollinator risk assessments tighten label restrictions ahead of anticipated 2025-2026 revisions. Iowa and Illinois distributors restructure inventory mixes toward lower-toxicity alternatives.
Brazil
ANVISA enforces residue thresholds that shape coating technology market access in soybean and corn sectors. Mato Grosso and Goiás cooperatives consolidate procurement power through vertically integrated buying groups demanding technical service bundling. Multi-year supply agreements with embedded agronomic advisory services now dominate contract structures.
Germany
ECHA's phased limitations on conventional binder chemistries force formulators toward bio-based alternatives under REACH compliance. EU Green Deal procurement mandates accelerate biodegradable coating adoption in glasshouse operations. Bavarian polymer research clusters concentrate controlled-release formulation expertise.
China
Dual carbon goals and GB standards on agricultural input sustainability reshape coating chemistry R&D priorities. Yangtze River Delta manufacturing bases scale chitosan-lignin biodegradable matrix production. Domestic seed treatment penetration deepens in wheat and rice growing regions.
Australia
Drought-resistant film coatings gain traction in the wheat belt where moisture retention determines yield stability. TGA-aligned agricultural chemical regulations govern active ingredient incorporation. Queensland and New South Wales broadacre operations adopt precision-applied functional barriers for climate stress adaptation.
Agricultural Coatings Market Vendor Landscape
Integrated chemistry-seed conglomerates and specialized coating formulators split the market along vertical integration fault lines. Three archetypes dominate: polymer synthesis-to-field pipeline controllers, trait-stacked genetics aligners, and biodegradable film specialists. Capacity expansion in Brazilian soybean belt proximity and technology licensing for bio-based binder alternatives represent the dominant competitive vectors.
Among German chemical conglomerates, BASF SE and Bayer AG exemplify integrated pipeline control from polymer synthesis through field delivery. BASF SE anchors the polymer-to-coating vertical integration archetype, while Bayer AG occupies the biodegradable film R&D intensity position. Corteva Agriscience represents the trait-stacked seed coating specialization archetype aligned with proprietary genetics. These three companies sit within distinct strategic tiers that shape formulation supply dynamics across major agricultural regions.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Syngenta AG |
| Clariant AG |
| Croda International |
| Evonik Industries |
| FMC Corporation |
| Nippon Paint Holdings |
| Others |
Supply Flow & Price Mechanics
Petrochemical input volatility determines both the premium spread between bio-based and synthetic coating formulations and the geographic clustering of polymer manufacturing capacity. Crude oil index fluctuations compress margin structures for polyurethane and acrylic binder suppliers while accelerating backward integration decisions among major formulators.
Pricing Analysis
The customization-premium spread separates configured-to-order trait-stacked coating bundles from standard pesticide-grade formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EPA FIFRA and ANVISA registration tiers. Cost compression in standard-grade synthetic binders is intensifying because Brazilian cooperative procurement platforms centralize volume negotiations. Individual farmers in India's eastern rice states exhibit highest price sensitivity, while agricultural companies in Brazil's Mato Grosso belt absorb premium multi-layer formulations.
Supply Chain Analysis
Contract-manufacturing concentration for polymer synthesis rests with integrated chemical conglomerates operating in Germany, China, and the United States. Raw material dependencies center on crude oil derivatives for conventional binders and agricultural waste streams for chitosan-lignin bio-based alternatives. Single-source vulnerability concentrates in Yangtze River Delta manufacturing bases for biodegradable matrix production. Distribution runs through vertically integrated procurement platforms serving Brazilian cooperatives and US Midwest farming operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative procurement platforms across Brazil's soybean belt, compressing formulation margins and elevating technical service requirements for coating suppliers.
For Market Incumbents: Harden formulation-to-field service bundles against margin compression from Brazilian cooperative buying groups. Deepen captive supply of bio-based polymer precursors to offset REACH compliance cost premiums in European markets. Lock in multi-year supply agreements with embedded agronomic advisory before 2025-2026 EPA label revisions accelerate inventory restructuring. For New Entrants and Emerging Players: India's eastern rice-growing states present the most penetrable geography for volume expansion, with coated seed penetration below 15%. Drone-compatible micro-granule fertilizer coatings for aerial application represent the fastest-climbing white-space segment. Partner with precision agriculture equipment distributors to bypass legacy seed treater compatibility gaps at smaller Brazilian farms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biodegradable film specialists with ANVISA-registered chitosan-lignin platforms. Long-term viability over a 5-10 year window hinges on regulatory alignment with EU Green Deal procurement mandates and EPA pollinator risk protocols. Watch for inflection signals in Brazilian cooperative technical service bundling requirements and ECHA polymer restriction phase-out timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | BASF SE's captive supply of polyurethane precursors insulates margin structures from crude oil volatility. |
| Bio-Based Binder Certification Investment | Bayer AG's biodegradable film R&D aligns with ECHA REACH restrictions and EU Green Deal subsidies. |
| Trait-Stacked Coating Bundle Development | Corteva Agriscience's proprietary genetics alignment captures premium pricing in Brazilian soybean cooperatives. |
| Cooperative Technical Service Partnership | Multi-year agreements with Mato Grosso buying groups lock in volume against independent distributor compression. |
| Drone-Compatible Formulation Launch | Micro-granule coatings optimized for aerial application unlock precision agriculture workflows in Australian wheat belt. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with coating formulation chemists, agricultural cooperative procurement managers, seed treatment equipment distributors, and regulatory affairs specialists; and secondary validation through EPA FIFRA registration databases, ANVISA residue threshold filings, ECHA REACH restriction notices, and customs trade data on polymer binder imports. Bottom-up triangulation across product type, application setting, and procurement channel converged with top-down macroeconomic drivers.
Forecast inputs considered seed treatment penetration rates across Brazil's expanding soybean belt, no-till farming adoption curves in Argentina and Paraguay, and REACH polymer restriction phase-out timelines over the projection horizon. Segmentation dimensions modeled include coating chemistry tier, active ingredient class, equipment compatibility grade, and regional regulatory cluster. CAGRs were derived from volume-weighted growth rates across these dimensions, incorporating drought-resistant film adoption in Australia's wheat belt and drone-compatible formulation uptake.
Practitioners should monitor EPA pollinator risk assessment protocol revisions, ANVISA residue threshold adjustments, and ECHA bio-based binder approval timelines for early signals of forecast deviation. Quarterly review of Brazilian cooperative procurement platform consolidation rates and crude oil derivative price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Agricultural Insect Pheromones Market