
 North America Specialty Animal Feed Additives Market | 2026-2036
North America Specialty Animal Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Specialty Animal Feed Additives Market Analysis
A shift from single-source vitamin premix contracts toward multi-source amino acid and enzyme procurement is repositioning how feed manufacturers manage input risk. Cargill, Incorporated leverages its captive grain origination network to secure cost-advantaged substrate flows for in-house fermentation of lysine and threonine. BASF SE anchors its position through backward integration into methionine precursors, sustaining margin capture across the value chain. Evonik Industries AG competes on manufacturing scale, operating one of the world's largest dedicated methionine complexes serving North American poultry integrators.
Specialty animal feed additives comprise biologically active compounds, microbial cultures, and chemically synthesized nutrients formulated at inclusion rates typically below one percent of total ration mass to enhance animal performance, health, or nutrient utilization efficiency. Production relies on submerged fermentation, chemical synthesis, or extraction processes followed by spray-drying, granulation, or microencapsulation to ensure thermostability during pelleting and gastric survival for live probiotics. Amino acids dominate value pools due to their irreplaceable role in least-cost diet formulation, while probiotics represent the fastest-expanding category as FDA restrictions on medically important antibiotics in livestock feed accelerate microbial alternative adoption. Enzymes occupy a mature but steadily growing position, with phytase and non-starch polysaccharide enzymes now standard in poultry and swine diets across the region.
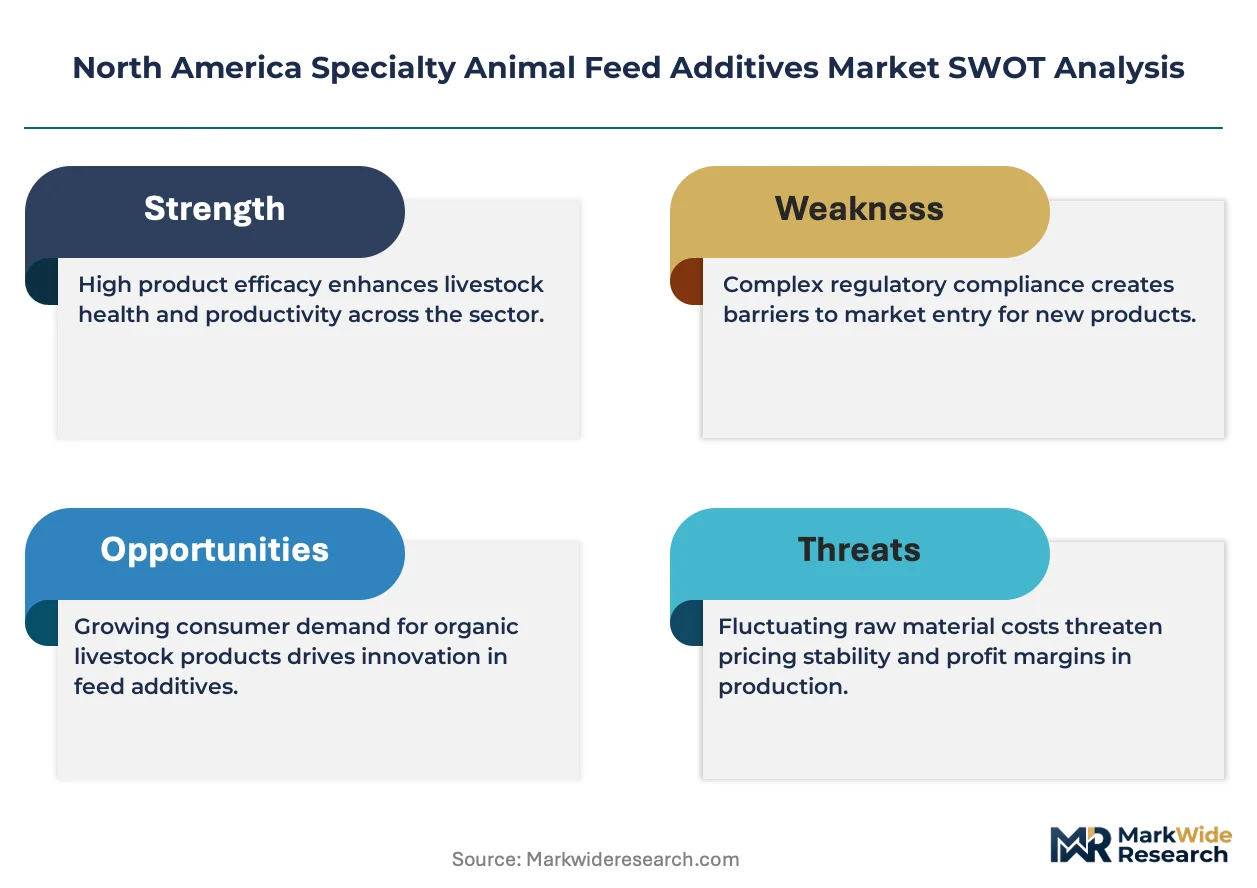
The FDA's Veterinary Feed Directive and ongoing enforcement of antibiotic stewardship protocols shape product registration pathways and label claims for growth-promotion additives. EPA oversight of fermentation facility emissions and state-level nutrient management regulations in Iowa, North Carolina, and California further constrain manufacturing siting and effluent handling. USDA Organic standards and third-party non-GMO verification programs create parallel premium channels that reward additive suppliers with segregated supply chains. Stakeholders must monitor pending state ballot initiatives on livestock housing standards, as these could cascade into revised feed formulation specifications and traceability requirements across integrated supply chains.
Market Dynamics
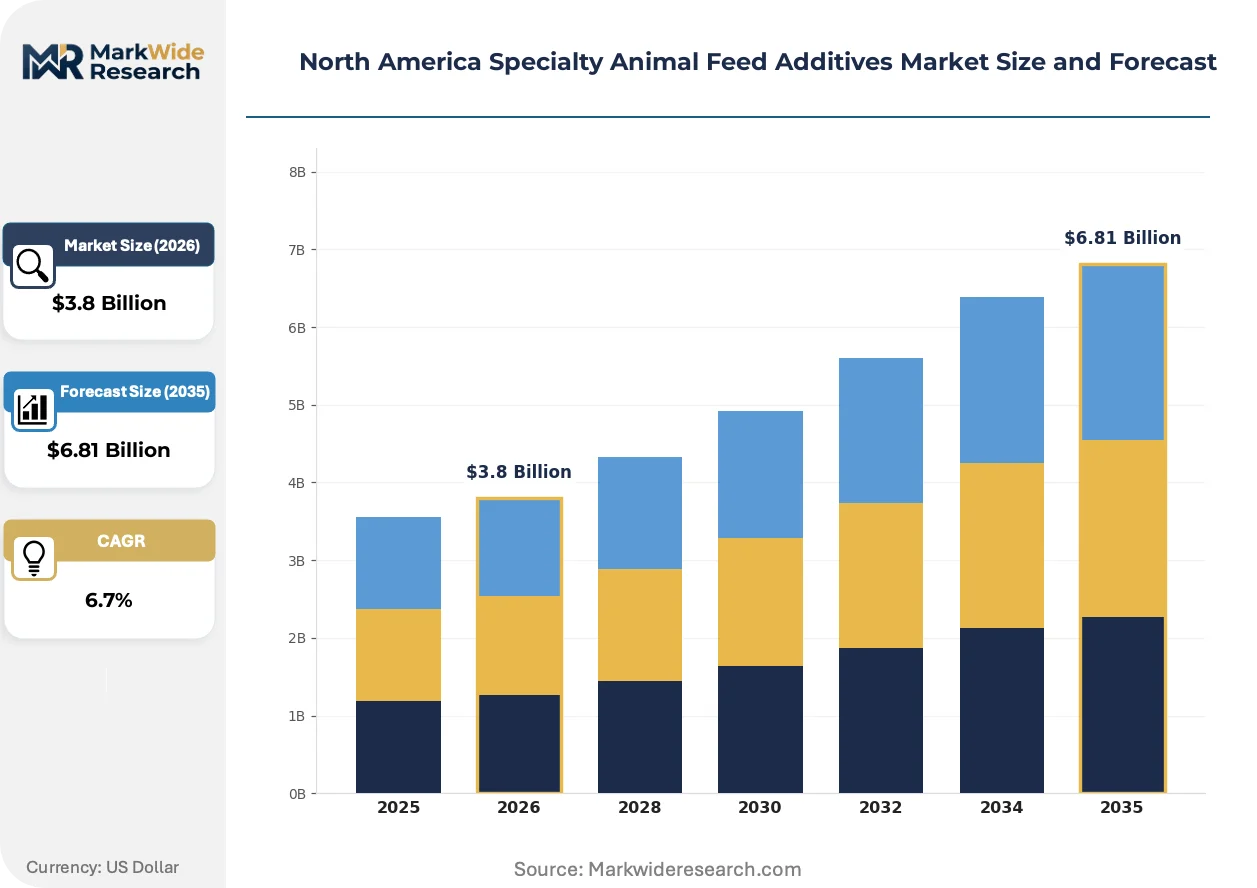
The FDA's Veterinary Feed Directive and state-level nutrient management protocols are compressing the antibiotic growth promoter window while simultaneously expanding the addressable market for microbial and enzymatic alternatives. This regulatory pivot is restructuring procurement patterns across integrated livestock operations.
Growth Catalysts
- Antibiotic stewardship mandates:The FDA's phased restrictions on medically important antibiotics in livestock feed are redirecting capital toward probiotic and prebiotic formulation development. Feedlots in Nebraska and Kansas now specify non-medicated alternatives in bulk tender documents.
- Rumen efficiency engineering:Dairy operations across Wisconsin and New York are deploying enzyme-enhanced total mixed rations to capture marginal milk yield gains. Phytase and fibrolytic enzyme inclusion rates are climbing in response to volatile soybean meal pricing.
- Midwest feedlot corridor concentration:The geographic clustering of large-scale cattle finishing operations from Iowa through Kansas generates procurement scale sufficient to justify dedicated additive manufacturing capacity. Bulk logistics advantages reinforce regional supply relationships.
Market Restraints
- Fermentation feedstock volatility:Corn steep liquor and molasses price swings directly compress margins for amino acid and organic acid producers. Cargill's captive grain origination network insulates it from spot market exposure that strains smaller competitors.
- EPA emissions compliance:Fermentation facility siting in Iowa and North Carolina faces escalating air quality permitting requirements. Capital expenditure thresholds for scrubber and anaerobic digester installations deter greenfield capacity additions.
- Live probiotic thermostability limits:Pelleting temperatures above 85°C degrade viable microbial counts, constraining formulation flexibility for high-energy poultry diets. Microencapsulation adds cost layers that erode price competitiveness against chemical alternatives.
Strategic Opportunities
- USDA Organic certification channel:Third-party non-GMO verification and organic livestock standards create premium pricing tiers for segregated supply chains. Additive suppliers with dual-certified production lines capture 15-30% price premiums over conventional equivalents.
- Precision fermentation platforms:Cell-culture-derived proteins and bioactive peptides are converging with traditional submerged fermentation to expand the functional ingredient portfolio. Early movers are securing offtake agreements with vertically integrated poultry integrators.
- California livestock housing ballot pathways:Pending state-level initiatives on confined animal feeding operations could cascade into revised feed formulation specifications. Suppliers with traceability infrastructure and welfare-aligned product positioning gain first-mover advantage in compliance-driven procurement.
Industry Challenges
- Microbiome formulation expertise scarcity:Strain selection, stability testing, and field validation for multi-species probiotic blends require specialized skill sets concentrated among academic and government research institutions. Recruitment competition with human biotech sectors elevates compensation costs.
- Legacy ERP integration friction:Feed manufacturers' existing formulation software often lacks modules for dynamic enzyme matrix values and real-time probiotic viability tracking. System upgrades demand capital allocation that competes with core production investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Specialty Animal Feed Additives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Amino Acids, Enzymes, Antioxidants Application: Poultry, Swine, Ruminants, Aquaculture End User: Farmers, Feed Manufacturers, Veterinary Clinics, Distributors Distribution Channel: Online Retail, Wholesale, Direct Sales, Others |
| Companies Covered | Cargill, Incorporated, BASF SE, Evonik Industries AG, Adisseo, Kemin Industries, ADM, International Flavors & Fragrances Inc., DSM Nutritional Products AG, Novonesis Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Specialty Animal Feed Additives Market Emerging Trajectories
Biotechnology-enabled feed additives are displacing commodity nutritional inputs through enhanced nutrient matrix values and documented performance claims. Three convergent developments are restructuring competitive positioning across the value chain.
Microencapsulated live probiotics is overtaking traditional freeze-dried preparations in North American poultry and swine applications. Major integrators in the Southeastern United States now specify enteric-coated formulations with demonstrated gastric survival rates above 70%. This technology is enabling direct-fed microbial products to command price positions historically reserved for antibiotic growth promoters.
The EPA's evolving enforcement of Clean Air Act provisions for fermentation facility volatile organic compound emissions is compressing operating margins for amino acid manufacturers. Facilities in Iowa and North Carolina face retrofit timelines that accelerate capital replacement cycles. Smaller producers without captive energy recovery systems are consolidating or exiting as compliance costs mount.
Direct contracting between livestock operations and additive suppliers is fragmenting the traditional distributor channel in the Midwest feedlot corridor. Large-scale operators in Nebraska and Kansas now negotiate volume-based pricing and technical service packages directly with manufacturers. This disintermediation is visible most acutely among cattle finishing operations exceeding 50,000 head capacity, where procurement teams employ dedicated feed ingredient specialists.
North America Specialty Animal Feed Additives Market Segmentation
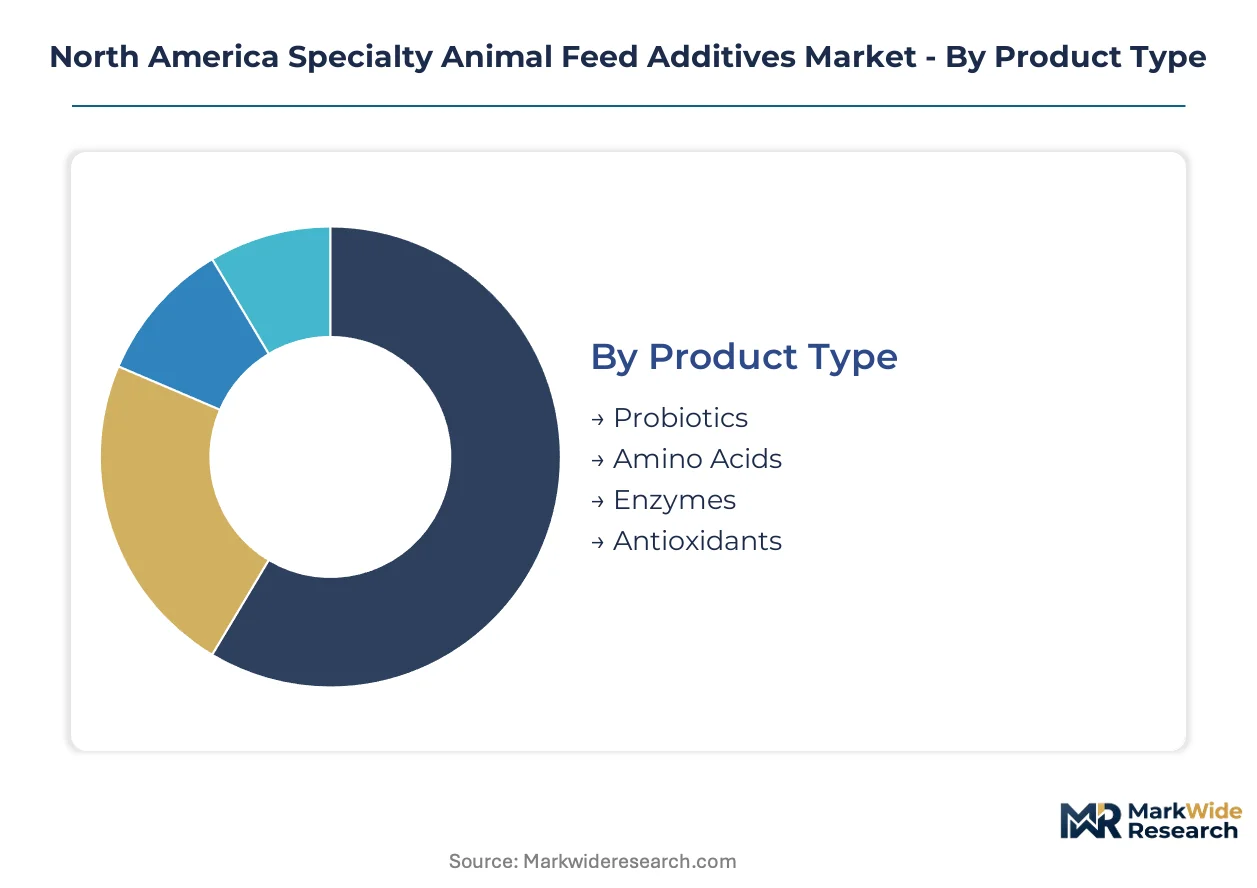
Specialty animal feed additives segment along four intersecting dimensions that determine procurement patterns and margin structures. Product chemistry dictates manufacturing capital intensity, while application species governs formulation specifications and regulatory pathways.
Product Type:
Supply concentration in amino acid fermentation facilities across the Midwest and Gulf Coast shapes competitive dynamics within this category.
- Probiotics:Live microbial cultures of Bacillus, Lactobacillus, and Enterococcus strains formulated for gastric survival and colonization efficacy. Demand clusters in Southeastern US poultry integrators responding to FDA antibiotic restrictions, with microencapsulation investments climbing to protect viability through pelleting thermal stress.
- Amino Acids:Crystalline lysine, methionine, threonine, and tryptophan produced via submerged fermentation of carbohydrate substrates. Bulk procurement from Nebraska-through-Kansas feedlot corridors dominates volume, with least-cost ration formulation driving specification in dairy and beef finishing operations.
- Enzymes:Phytase, xylanase, and cellulase preparations targeting anti-nutrient degradation and fiber digestion.
- Antioxidants:Synthetic ethoxyquin, BHT, and natural tocopherol blends preserving feed lipid stability.
Amino acids absorb the bulk of installed capacity; probiotics is expanding most quickly.
Application:
Species-specific digestive physiology and regulatory exposure create divergent formulation requirements across livestock categories.
- Poultry:High-density broiler and layer operations in Georgia, Arkansas, and Alabama drive phytase and probiotic inclusion. Enzyme matrix values now standard in integrator feed specifications, with direct-fed microbials displacing legacy antibiotic growth promoters in starter and grower rations.
- Ruminants:Dairy herds across Wisconsin and New York plus feedlot operations in Nebraska, Iowa, and Kansas constitute the demand core. Rumen-protected amino acids and fibrolytic enzymes capture marginal milk yield and feed conversion gains in volatile commodity margin environments.
- Swine:Wean-to-finish operations in Iowa, North Carolina, and Minnesota deploy phytase and NSP enzymes to reduce soybean meal dependency.
- Aquaculture:Channel catfish in Mississippi Delta and salmonid operations in Pacific Northwest specify specialized probiotic and immunostimulant formulations.
Poultry commands the largest additive volume; aquaculture is gaining share fastest.
End User:
Procurement sophistication varies sharply across customer types, fragmenting sales channel economics.
- Farmers:Owner-operators of mid-scale dairy and cow-calf operations purchasing through cooperatives and local feed dealers. Price sensitivity dominates, with generic amino acid and mineral premixes preferred over branded specialty additives.
- Feed Manufacturers:Integrated compounders and independent mills formulating complete feeds and supplements for downstream livestock operations. Technical service relationships and volume pricing agreements lock in supplier loyalty across multi-year contracts.
- Veterinary Clinics:Production animal practices prescribing therapeutic nutritional interventions for metabolic disorders and transition period management.
- Distributors:Regional ingredient brokers and national wholesale networks managing inventory and logistics for dispersed customer bases.
Feed manufacturers consolidate procurement volume; veterinary clinics are expanding their nutritional service portfolios most aggressively.
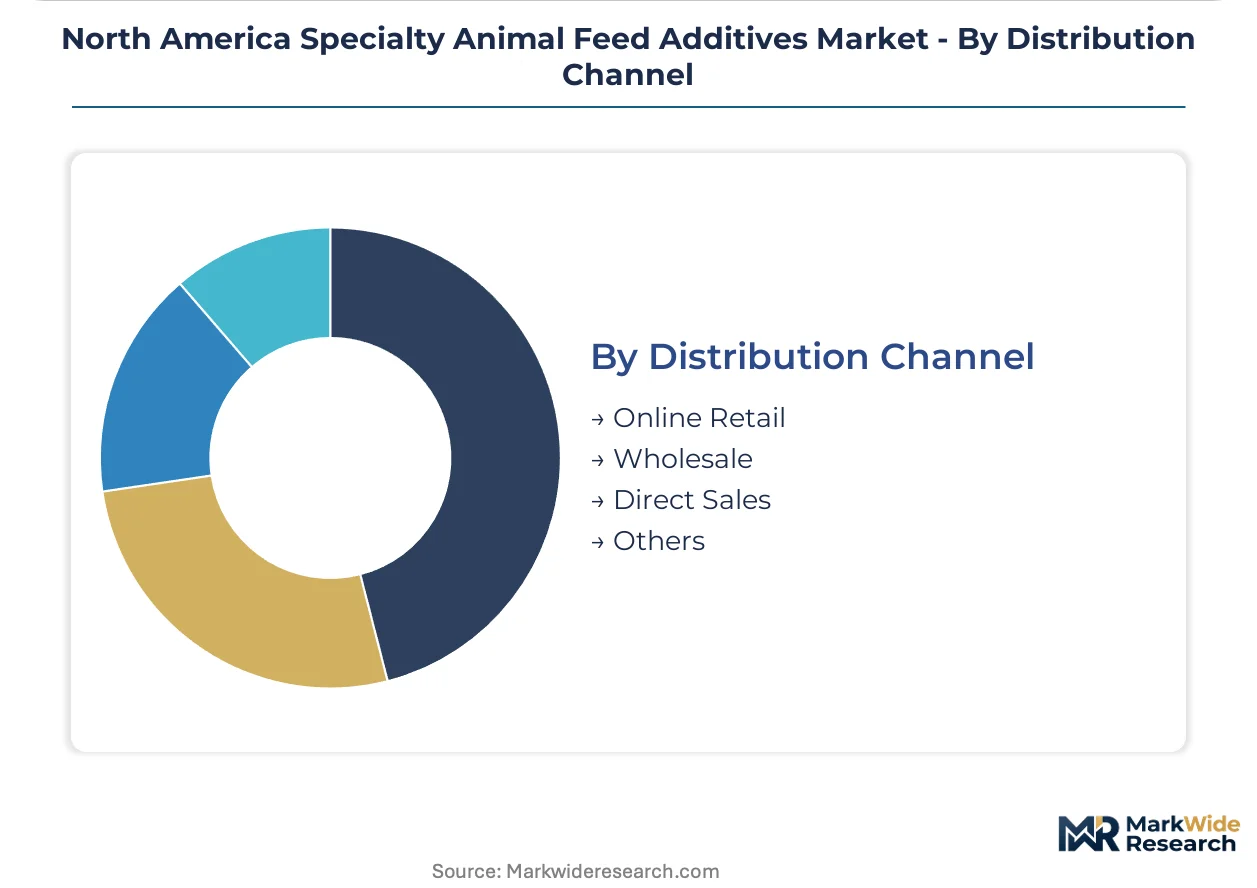
Distribution Channel:
Channel structure reflects shipment scale, technical service intensity, and customer geographic dispersion.
- Wholesale:Bulk rail and truck shipments of amino acids and enzymes to captive feed mills and independent compounders. Midwest grain elevator networks and river terminal infrastructure enable cost-efficient aggregation of multi-ingredient orders.
- Direct Sales:Manufacturer-to-producer relationships bypassing distributor markups in the cattle feedlot corridor. Technical field teams deliver on-site ration formulation support and real-time troubleshooting for operations exceeding 50,000 head capacity.
- Online Retail:E-commerce platforms serving hobby farmers, equine operations, and small-scale livestock producers with packaged probiotic and supplement products.
- Others:Cooperative buying groups, integrator captive supply arrangements, and auction-based spot procurement for distressed inventory.
Wholesale channels handle the majority of tonnage; direct sales are climbing the fastest as large operators consolidate procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn belt states from Nebraska through Iowa into Kansas concentrate amino acid fermentation capacity and drive procurement scale for bulk feed additive consumption.
United States
Dairy operations across Wisconsin and New York deploy rumen-protected enzymes to capture marginal milk yield gains in volatile commodity margin environments. The FDA's Veterinary Feed Directive and phased antibiotic restrictions redirect capital toward probiotic formulation development. Feedlot corridors in Nebraska, Iowa, and Kansas generate procurement scale sufficient to justify dedicated manufacturing capacity with bulk logistics advantages reinforcing regional supply relationships.
Canada
Prairie livestock operations in Alberta and Saskatchewan expand enzyme inclusion in beef finishing rations to improve feed conversion efficiency amid volatile grain pricing. Health Canada's PMRA oversees feed additive registration pathways parallel to FDA frameworks. Ontario's integrated poultry sector drives phytase demand through least-cost formulation protocols in high-density broiler operations near London and Stratford.
Mexico
Poultry integrators in Jalisco and Nuevo León accelerate probiotic adoption as export-oriented operations align with US antibiotic stewardship standards. The country's national agricultural regulator enforces feed safety protocols converging with North American trading bloc requirements. Bajío region feed mills concentrate procurement volume for amino acid and enzyme sourcing through cross-border supply relationships with US manufacturers.
Midwest Feedlot Corridor
Cattle finishing operations exceeding 50,000 head capacity in Nebraska and Kansas negotiate direct manufacturer contracts bypassing traditional distributor markups. State-level nutrient management regulations in Iowa constrain fermentation facility siting and effluent handling requirements. Omaha and Wichita serve as logistics nodes for rail and truck shipments of bulk amino acids to captive feed mills across the central plains.
Southeastern Poultry Belt
Broiler and layer operations in Georgia, Arkansas, and Alabama specify microencapsulated probiotics with demonstrated gastric survival rates above 70 percent. EPA emissions compliance for fermentation facilities faces escalating air quality permitting timelines. Atlanta and Little Rock anchor technical service networks delivering on-site ration formulation support to major integrators.
North America Specialty Animal Feed Additives Market Vendor Landscape
Backward integration into substrate supply and precursor chemicals dominates the current landscape as manufacturers defend margin positions against fermentation feedstock volatility. The vendor base stratifies across three tiers: diversified agricultural conglomerates with captive grain networks, specialized chemical producers with dedicated amino acid complexes, and biotechnology-focused innovators with precision fermentation platforms. Two competitive moves define current positioning: upstream control over raw material flows and direct contracting relationships with large-scale livestock operations that disintermediate traditional distribution channels.
Among diversified agricultural conglomerates, Cargill, Incorporated exemplifies the integrated archetype through its captive grain origination network securing cost-advantaged substrate flows. BASF SE anchors the chemical-specialist tier with backward integration into methionine precursors sustaining margin capture across the value chain. Evonik Industries AG occupies the scale-driven position with manufacturing capacity serving North American poultry integrators through dedicated amino acid complexes.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Evonik Industries AG |
| Adisseo |
| Kemin Industries |
| ADM |
| International Flavors & Fragrances Inc. |
| DSM Nutritional Products AG |
| Novonesis Group |
| Others |
Supply Flow & Price Mechanics
Microencapsulation technology adoption in live probiotic formulations is simultaneously elevating production cost structures and concentrating manufacturing capacity among suppliers with dedicated spray-drying and enteric-coating capabilities. This process shift tightens price competition in conventional freeze-dried segments while enabling premium positioning for thermostable alternatives that survive pelleting thermal stress above 85°C.
Pricing Analysis
Technical service bundling separates contract structures in the North American feed additives market, with large cattle feedlot operators in Nebraska and Kansas negotiating inclusive ration formulation support while smaller dairy cooperatives purchase unbundled commodity amino acids. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with USDA Organic and non-GMO verified products commanding 15-30% premiums over conventional equivalents. Cost compression in standard-grade lysine and methionine is intensifying because Cargill's captive grain origination network insulates it from spot market exposure that strains smaller competitors. Price sensitivity concentrates most acutely among mid-scale dairy owner-operators purchasing through local feed dealers, while integrated poultry integrators in Georgia and Arkansas prioritize gastric survival performance metrics over unit cost.
Supply Chain Analysis
Domestic-content requirements in California livestock housing ballot initiatives are reshaping sourcing specifications toward traceable supply chains with segregated production lines. Manufacturing gravity centers on Iowa, North Carolina, and Illinois, where fermentation facilities cluster near corn steep liquor and molasses feedstock sources. Raw material flows draw from Midwest grain elevator networks, Gulf Coast petrochemical precursors, and Southeast Asian vitamin intermediate suppliers. Single-source vulnerability concentrates in methionine precursor chemicals, where BASF's backward integration creates dependency risk for non-integrated competitors. Distribution runs through captive feed mills in the Midwest feedlot corridor, direct manufacturer relationships for operations exceeding 50,000 head capacity, and regional wholesale networks serving dispersed smaller producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Veterinary Feed Directive has erected a cost-of-compliance moat that rewards incumbent additive suppliers with established registration pathways and field validation datasets, while straining capital-constrained entrants lacking multi-year probiotic stability testing infrastructure.
For Market Incumbents: Acquire precision fermentation platform capabilities to expand beyond traditional submerged fermentation into cell-culture-derived bioactive peptides. Consolidate strain library assets through targeted biotechnology acquisitions, as microbiome formulation expertise scarcity elevates recruitment competition with human biotech sectors. Defensive positioning requires deepening captive substrate supply relationships and securing direct contracting lock-in with cattle finishing operations exceeding 50,000 head capacity before channel disintermediation accelerates.
For New Entrants and Emerging Players: Capture USDA Organic certification channel white space where segregated supply chains command 15-30% price premiums and incumbent capacity conversion lags demand growth. Target aquaculture probiotic formulations in the Mississippi Delta and Pacific Northwest, the fastest-expanding application segment with less entrenched supplier relationships than poultry or ruminant markets. Go-to-market execution should leverage precision fermentation technical differentiation to secure offtake agreements with vertically integrated poultry integrators seeking welfare-aligned positioning.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified agricultural conglomerates seeking biotechnology capabilities and by chemical specialists pursuing backward integration into fermentation infrastructure. Long-term viability favors suppliers with dual-certified production lines and traceability infrastructure aligned with pending California livestock housing compliance requirements. The signal to watch is state ballot initiative progression on confined animal feeding operations, which could cascade into revised feed formulation specifications and accelerate procurement consolidation among compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Investment | Cell-culture-derived proteins expand functional ingredient portfolios beyond traditional submerged fermentation constraints. |
| USDA Organic Certification Acquisition | Segregated supply chain infrastructure captures 15-30% price premiums in premium livestock channels. |
| Direct Feedlot Contracting Expansion | Manufacturer-to-producer relationships bypass distributor markups in the Nebraska-Kansas cattle finishing corridor. |
| Microencapsulation Capacity Buildout | Thermostable probiotic formulations survive pelleting temperatures above 85°C, displacing freeze-dried alternatives. |
| Fermentation Feedstock Integration | Captive grain origination networks insulate amino acid producers from corn steep liquor and molasses price volatility. |
Methodological Framework
USDA regulatory filings, EPA Clean Air Act enforcement records, and FDA Veterinary Feed Directive guidance documents formed the secondary backbone of this analysis. Primary fieldwork involved structured interviews with feed mill procurement directors, livestock nutritionists at integrated poultry operations, fermentation facility technical managers, and veterinary practitioners specializing in production animal metabolic disorders. This stakeholder input was cross-referenced with SEC 10-K disclosures from diversified agricultural conglomerates, state-level nutrient management permit databases, and third-party organic certification registry data. Bottom-up volume estimates from species-specific inclusion rate modeling were triangulated against top-down value projections derived from amino acid fermentation capacity utilization assessments.
Bottom-up modeling anchored the analytical lens, constructing additive consumption estimates from individual livestock operation scale data, species-specific diet formulation standards, and regional feed production statistics. Segmentation dimensions included product chemistry class, application species, end-user procurement sophistication tier, and distribution channel structure. CAGRs were derived from trend extrapolation of regulatory-driven substitution patterns, particularly antibiotic-to-probiotic displacement rates and enzyme matrix value adoption curves. Industry-specific forecast inputs incorporated volatile organic compound emissions compliance timelines for Iowa and North Carolina fermentation facilities, plus pending California ballot initiative probability assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement intensity shifts, state livestock housing regulatory ballot outcomes, and precision fermentation technology cost reduction trajectories. These assumptions reflect documented regulatory trajectories and technology adoption patterns rather than speculative scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
South America Feed Antibiotics Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Neem Pesticides Market