
 Asia-Pacific Feed Antibiotics Market | 2026-2036
Asia-Pacific Feed Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Antibiotics Market Outlook
Veterinary pharmacology expertise is redrawing competitive boundaries across the Asia-Pacific feed antibiotics sector. Merck Animal Health leverages its diagnostic-to-treatment pipeline to anchor integrated livestock health programs. Boehringer Ingelheim International GmbH sustains manufacturing scale across multiple Asian production hubs. Zoetis differentiates through species-specific formulation capabilities that address regional pathogen profiles.
Feed antibiotics comprise antimicrobial compounds administered through animal rations to prevent bacterial infections and promote growth performance in food-producing species. These formulations typically achieve therapeutic concentrations at inclusion rates measured in grams per ton of finished feed, with bioavailability varying by compound class and target species gastrointestinal physiology. Tetracyclines occupy the largest volume position due to broad-spectrum efficacy and established resistance management protocols in swine and poultry operations. Macrolides represent the fastest-expanding product category, driven by respiratory disease pressure in intensive beef cattle feedlots across Australia and New Zealand. Premix formulations capture disproportionate margin pools through value-added mineral and vitamin co-formulation services.
China's MEE enforces discharge limits on antibiotic manufacturing effluent, elevating compliance costs for domestic producers. India's CDSCO mandates veterinary prescription requirements for medicated feeds, reshaping distribution through licensed veterinarian channels. Australia's TGA residue monitoring program shapes export-oriented producer procurement decisions. Stakeholders must weigh regulatory trajectory against pathogen resistance patterns when allocating R&D resources across compound classes and species portfolios.
Market Dynamics
China's GB standards on veterinary drug residues are forcing reformulation across the entire Asia-Pacific feed antibiotics supply chain, compelling manufacturers to abandon legacy compounds and rebuild premix portfolios around compliant actives.
Growth Catalysts
- Intensive broiler operations:Southeast Asia's vertically integrated poultry houses are expanding preventive antibiotic protocols to manage necrotic enteritis and coccidiosis pressure in high-density housing systems.
- India's CDSCO prescription mandate:Licensed veterinarian channels are professionalizing medicated feed distribution, creating structured demand for documented therapeutic use in commercial dairy corridors.
- Macrolide respiratory applications:Australian and New Zealand beef feedlots are adopting tilmicosin and tulathromycin premixes to control Mannheimia haemolytica outbreaks in backgrounding and finishing phases.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for tetracyclines and penicillins clusters in eastern Chinese provinces, exposing formulators to MEE effluent enforcement disruptions.
- Residue testing infrastructure gaps:Vietnam, Indonesia, and Philippines lack accredited laboratory networks capable of validating withdrawal compliance for export-bound livestock products.
- Phytogenic substitution pressure:Oregano oil, thymol, and cinnamaldehyde blends are capturing growth promotion share in European-export-oriented Australian operations.
Strategic Opportunities
- Myanmar and Cambodia commercialization:Nascent intensive livestock sectors in these frontier markets lack established veterinary distribution, creating first-mover channel construction potential.
- Species-specific premix services:Formulators can capture margin expansion by co-developing mineral-vitamin-antibiotic matrices tailored to regional pathogen profiles in layer and breeder operations.
- Japan's positive list system alignment:Export-oriented Thai and Malaysian producers are seeking MHLW-compliant residue management protocols to access premium beef and pork import quotas.
Industry Challenges
- Veterinary pharmacology talent scarcity:Formulation chemists with dual expertise in antimicrobial resistance management and feed manufacturing process engineering command premium compensation across the region.
- Withdrawal period compliance validation:Producers struggle to synchronize antibiotic cessation with slaughter schedules when integrating backward into live operations from processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Antibiotics Market |
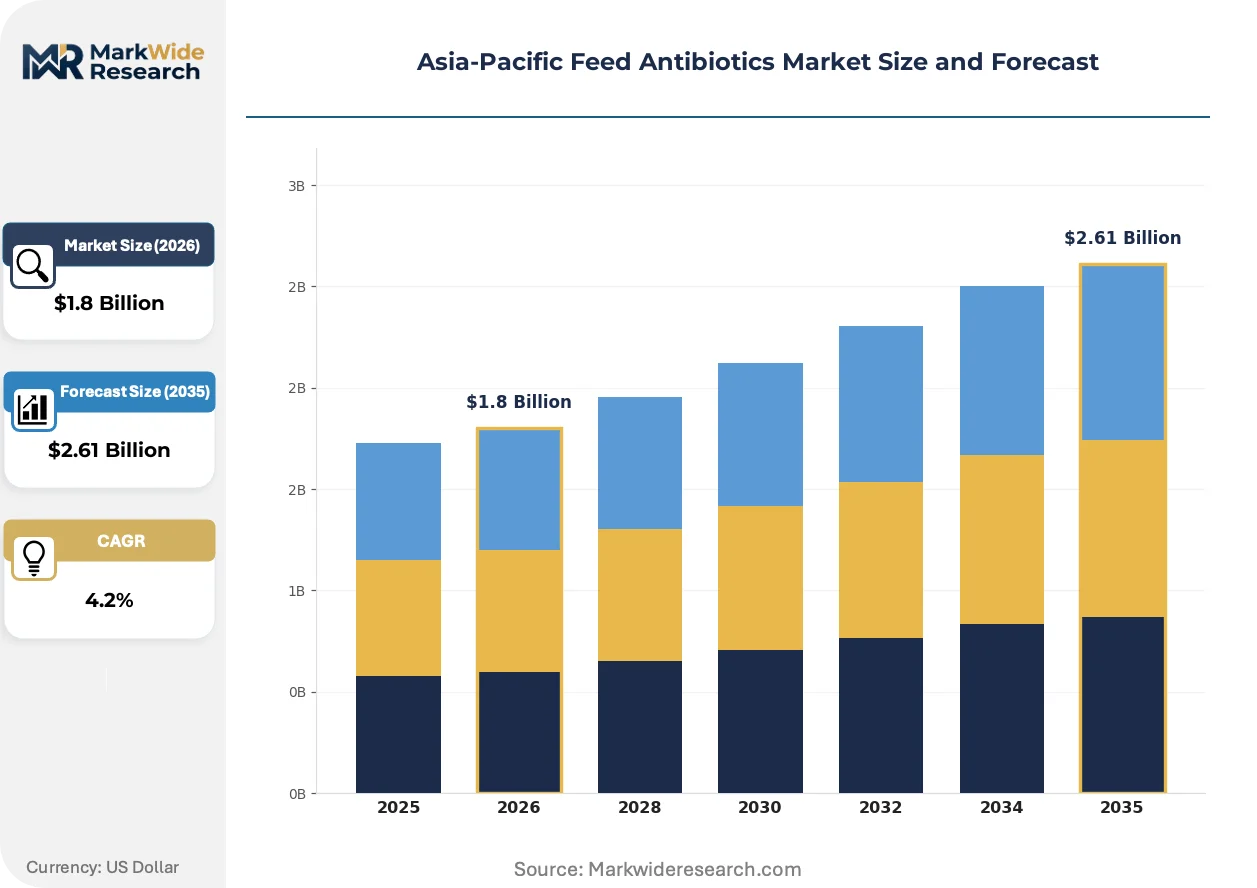
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetracyclines, Macrolides, Penicillins, Sulfonamides End User: Poultry, Swine, Ruminants, Aquaculture Formulation Type: Powder, Liquid, Premix, Granules Distribution Channel: Online, Retail, Distributors, Veterinarians |
| Companies Covered | Merck Animal Health, Boehringer Ingelheim International GmbH, Zoetis, Bayer AG, Elanco Animal Health, Virbac Animal Health, Zydus Cadila Healthcare, Adisseo, Cargill, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Antibiotics Market Strategic Shifts
Microencapsulation and targeted-release technologies are redrawing formulation economics in the Asia-Pacific feed antibiotics sector, enabling precision delivery that reduces inclusion rates while maintaining therapeutic efficacy.
Encapsulated tetracycline and macrolide formulations are bifurcating the premix market between commodity bulk actives and value-added controlled-release products. Australian feedlot operators and Indian dairy cooperatives are adopting these technologies at accelerating rates to optimize bioavailability and reduce environmental loading. This technology shift is compressing margins on unformulated bulk antibiotics while expanding the addressable premium for integrated health service providers.
China's MEE enforcement of antibiotic manufacturing effluent discharge limits is restructuring production geography across the region. Domestic Chinese producers are absorbing capital costs for wastewater treatment upgrades or relocating to industrial parks with centralized remediation infrastructure. Southeast Asian formulators dependent on Chinese API supply are diversifying sourcing toward Indian and South Korean manufacturers to mitigate regulatory interruption risk.
Integrated livestock health contracting is displacing transactional premix purchasing in Australia's export-oriented beef sector. Large feedlot operators are consolidating procurement through diagnostic-linked therapeutic protocols that bundle laboratory testing, veterinarian oversight, and formulated feed delivery. This service integration is most advanced in Queensland and New South Wales cattle feeding regions supplying Japanese and Korean import markets.
Asia-Pacific Feed Antibiotics Market Segmentation
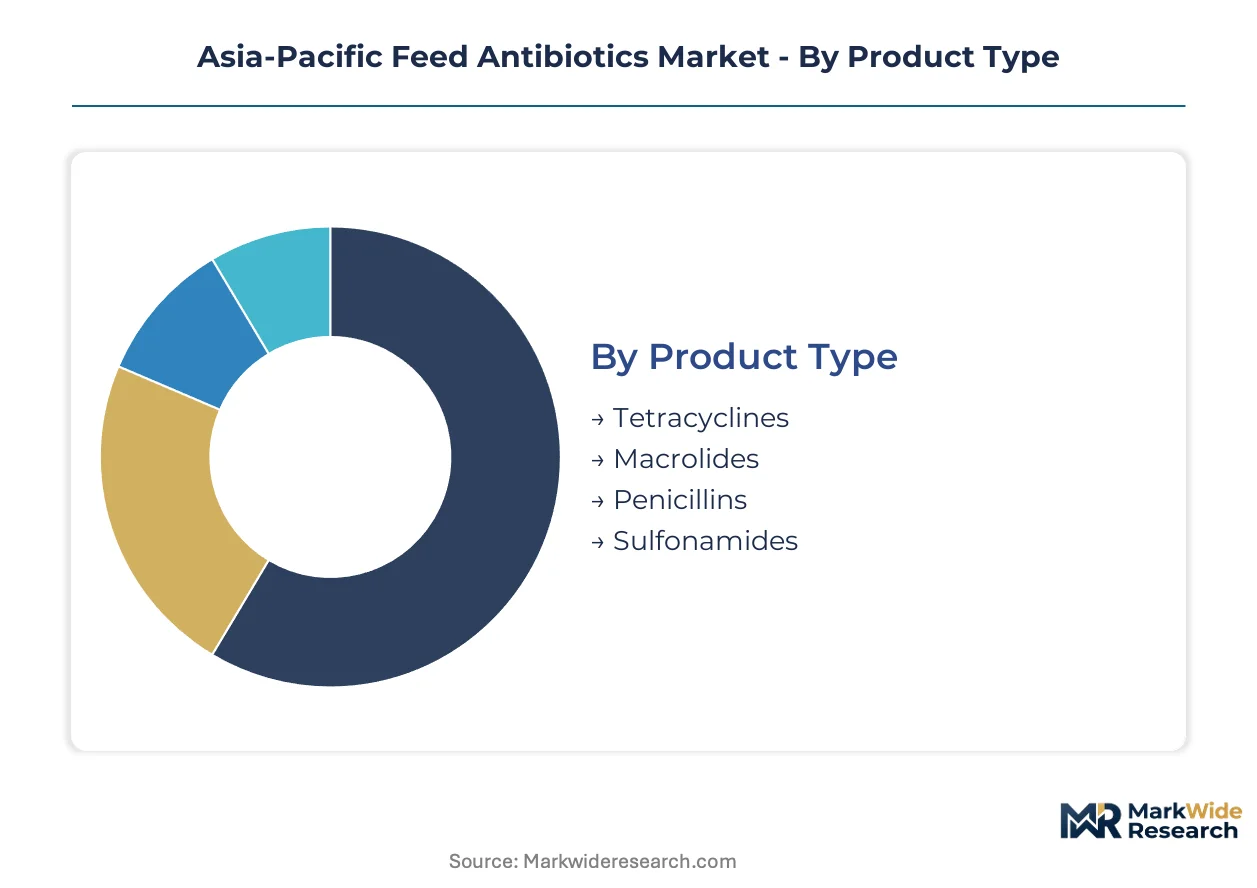
Antibiotic compound classes face divergent regulatory fates across the Asia-Pacific region, with residue limits and prescription mandates fragmenting demand patterns by molecular structure. Species-specific gastrointestinal physiology and export market compliance requirements further stratify formulation preferences across national boundaries.
Product Type:
China's GB standards on veterinary drug residues and India's CDSCO prescription mandates are bifurcating demand between legacy broad-spectrum compounds and reformulation-compliant alternatives.
- Tetracyclines:Chlortetracycline and oxytetracycline formulations achieve therapeutic concentrations at inclusion rates of 10-50 grams per ton in finished feed. Southeast Asian broiler operations concentrate demand for these compounds to manage necrotic enteritis in high-density housing systems, though China's tightening residue limits are forcing portfolio rebalancing toward compliant actives.
- Macrolides:Tilmicosin and tulathromycin premixes target Mannheimia haemolytica respiratory infections in Australian and New Zealand beef feedlots. Australian export-oriented producers are adopting these formulations at accelerating rates to meet Japan's MHLW positive list system requirements for premium beef import quotas.
- Penicillins:Procaine penicillin G premixes serve therapeutic niches in Indian dairy mastitis prevention protocols under CDSCO-mandated veterinary prescription channels.
- Sulfonamides:Sulfamethazine and sulfadiazine combinations retain residual demand in Vietnamese and Indonesian swine operations lacking accredited residue testing infrastructure for export compliance.
Tetracyclines handle the majority of throughput; macrolides are the fastest mover on share.
End User:
Species physiology and housing density determine bioavailability requirements and therapeutic concentration targets across formulation portfolios.
- Poultry:Broiler operations across Thailand, Vietnam, and Indonesia drive preventive antibiotic consumption for coccidiosis and necrotic enteritis management in climate-controlled vertical housing systems.
- Swine:Post-weaning diarrhea protocols in Chinese and Vietnamese sow-to-finish operations concentrate demand for water-soluble antibiotic delivery systems.
- Ruminants:Australian and New Zealand feedlot backgrounding phases adopt macrolide premixes for respiratory disease control during high-stress receiving periods.
- Aquaculture:Shrimp farming operations across Vietnam and Indonesia face regulatory pressure from China's MEE effluent enforcement affecting API supply chains for aquatic medicated feeds.
Poultry dominates volume absorption; ruminant applications are climbing the fastest as Australian feedlots professionalize procurement.
Formulation Type:
Manufacturing process economics and species feeding systems determine physical form selection across the value chain.
- Powder:Bulk active pharmaceutical ingredients in crystalline form serve compound feed manufacturers with in-house premix blending capabilities, particularly in India's commercial dairy corridors.
- Liquid:Water-soluble concentrates enable post-weaning medication via drinking water systems in Vietnamese and Indonesian swine nurseries.
- Premix:Mineral-vitamin-antibiotic co-formulations capture premium margins through value-added technical services tailored to regional pathogen profiles.
- Granules:Microencapsulated and targeted-release technologies optimize bioavailability in Australian feedlot operations while reducing environmental loading.
Premix formulations command the highest margin pool; granules are expanding most quickly on technology adoption.
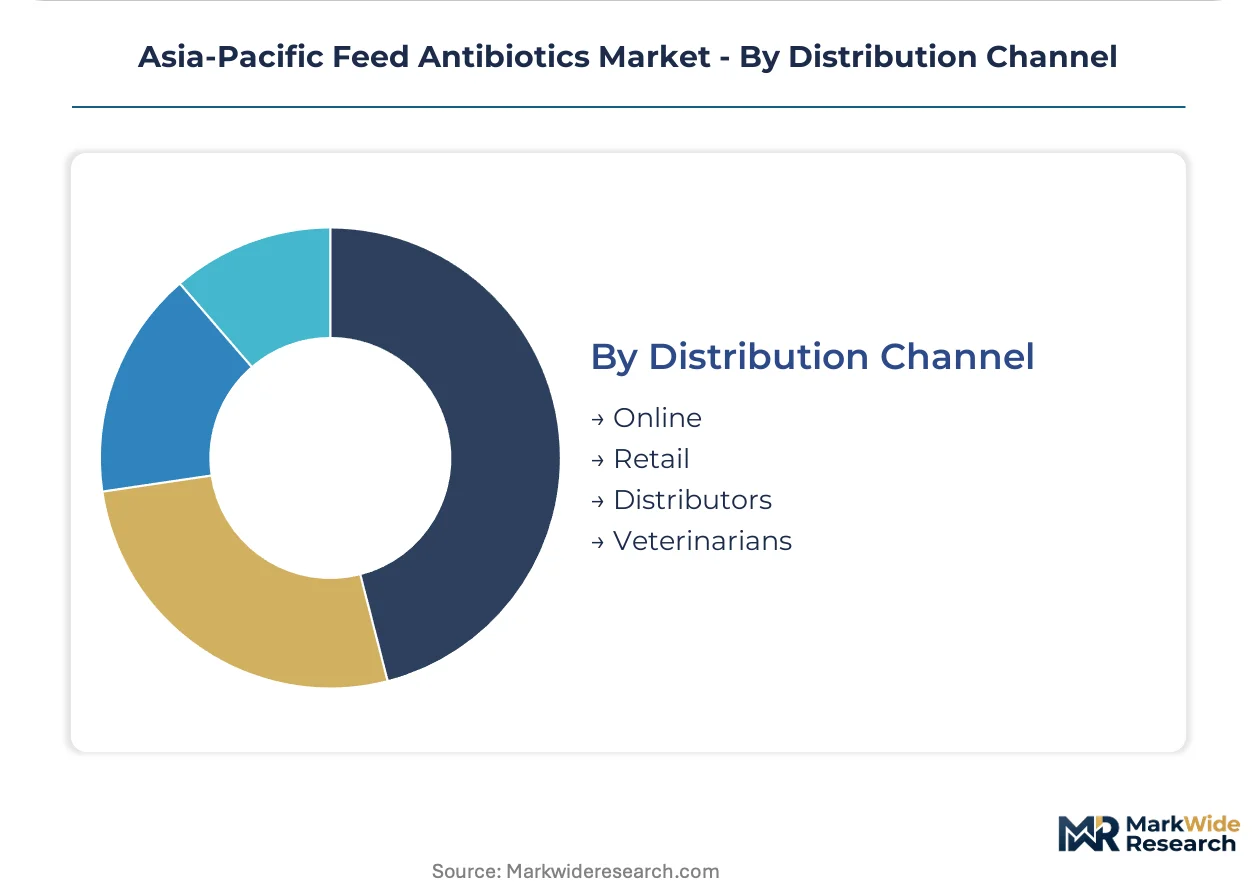
Distribution Channel:
Regulatory prescription mandates and producer scale stratify channel access across national veterinary frameworks.
- Online:E-commerce platforms serve smallholder producers in Myanmar and Cambodia frontier markets lacking established veterinary distribution infrastructure.
- Retail:Agricultural supply stores retain relevance for over-the-counter tetracycline sales in jurisdictions without prescription mandates.
- Distributors:Regional wholesalers manage inventory and technical support for integrated poultry and swine operations across Southeast Asia.
- Veterinarians:India's CDSCO prescription mandate is consolidating medicated feed distribution through licensed practitioner channels, professionalizing therapeutic documentation.
Distributor networks handle the majority of volume; veterinarian channels are gaining share fastest on regulatory prescription expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors regulatory enforcement across the Asia-Pacific feed antibiotics landscape, with GB standards on veterinary drug residues forcing supply chain recalibration throughout the region.
China
Intensive swine and poultry operations in Sichuan and Shandong provinces drive bulk tetracycline consumption for necrotic enteritis management. The Ministry of Ecology and Environment enforces antibiotic manufacturing effluent discharge limits, elevating compliance costs for domestic API producers. Yangtze River Delta formulators are relocating to industrial parks with centralized wastewater remediation infrastructure.
India
Commercial dairy corridors in Maharashtra and Gujarat concentrate demand for penicillin-based mastitis prevention protocols. The CDSCO mandates veterinary prescription requirements for all medicated feeds, professionalizing distribution through licensed practitioner channels. Haryana's integrated dairy cooperatives are consolidating procurement around documented therapeutic use systems.
Australia
Queensland and New South Wales feedlots adopt macrolide premixes for Mannheimia haemolytica respiratory control during high-stress receiving periods. The TGA residue monitoring program shapes export-oriented procurement decisions for Japanese and Korean premium beef quotas. Integrated livestock health contracting is displacing transactional premix purchasing across the sector.
Vietnam
Vertically integrated broiler houses in the Mekong Delta expand preventive antibiotic protocols for coccidiosis management in climate-controlled housing systems. The national veterinary regulator lacks accredited laboratory networks capable of validating withdrawal compliance for export-bound products. Domestic formulators remain dependent on Chinese API supply subject to MEE enforcement disruptions.
Thailand
Export-oriented swine operations in the Central Plains seek MHLW-compliant residue management protocols to access Japanese premium pork import quotas. The Department of Livestock Development tightens import certification for premix actives. Chonburi province's integrated poultry processors are backward integrating into feed manufacturing to control antibiotic inclusion documentation.
Asia-Pacific Feed Antibiotics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational animal health conglomerates commanding diagnostic-to-treatment pipelines while regional formulators compete on mineral-vitamin-antibiotic co-development services. The upper tier consolidates procurement relationships through bundled laboratory testing and veterinarian oversight programs. Three archetypes define competitive positioning: integrated health service providers, species-specific formulation specialists, and API-dependent regional blenders. Dominant competitive moves include geographic expansion into frontier markets lacking veterinary distribution infrastructure and technology licensing for microencapsulation capabilities.
Among integrated health service providers, Merck Animal Health and Boehringer Ingelheim International GmbH exemplify the diagnostic-linked therapeutic protocol model, while Zoetis occupies a position within the species-specific formulation specialist tier. These three companies represent contrasting geographic origins and corporate structures: Merck Animal Health operates as a US-based animal health division, Boehringer Ingelheim International GmbH anchors German pharmaceutical manufacturing heritage, and Zoetis functions as a standalone animal health corporation. Each exemplifies a distinct strategic archetype without claiming specific market share positions or recent transactional activity.
| Leading Market Players |
|---|
| Merck Animal Health |
| Boehringer Ingelheim International GmbH |
| Zoetis |
| Bayer AG |
| Elanco Animal Health |
| Virbac Animal Health |
| Zydus Cadila Healthcare |
| Adisseo |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Phytogenic substitution in Australian beef feedlots is redrawing procurement economics, simultaneously compressing commodity antibiotic price floors while elevating premium tiers for encapsulated formulations with documented residue compliance. China's MEE effluent enforcement adds geographic cost dispersion, fragmenting API sourcing across Indian and South Korean alternatives.
Pricing Analysis
Australian and Indian feedlot operators face a 15-25% price spread between bulk tetracycline actives and microencapsulated macrolide formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and veterinary oversight bundling. Cost compression in commodity bulk actives is intensifying because Chinese API producers absorb MEE-mandated wastewater treatment capital. Smallholder poultry operations in Vietnam and Indonesia exhibit highest price sensitivity; Japanese export-oriented Australian feedlots show least.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient production for tetracyclines and penicillins consumed across Asia-Pacific formulators. Eastern Chinese provinces feed from concentrated chemical manufacturing clusters now subject to MEE discharge limits. Single-source vulnerability concentrates in Yangtze River Delta API producers facing relocation or upgrade costs. Distribution runs through regional wholesalers managing inventory and technical support for integrated Southeast Asian poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific feed antibiotics penetration remains early-cycle, with Myanmar and Cambodia intensive livestock sectors just beginning preventive protocol adoption. India's CDSCO prescription mandate accelerates professionalization of medicated feed distribution channels.
For Market Incumbents: Secure backward integration into diagnostic-linked therapeutic protocols to anchor procurement relationships against phytogenic substitution pressure. Expand mineral-vitamin-antibiotic co-development services for layer and breeder operations to defend margin position. Lock in MHLW-compliant residue management certification for Thai and Malaysian export-oriented producers.
For New Entrants and Emerging Players: Lead with species-specific microencapsulation capabilities targeting Australian feedlot respiratory disease protocols. Myanmar and Cambodia veterinary distribution infrastructure gaps represent most penetrable white-space. Construct e-commerce platforms serving smallholder producers in frontier markets lacking established channels.
For Investors and Strategic Acquirers: China's GB standards reshapes the acquisition landscape toward reformulation-compliant premix specialists with established MEE-adapted supply chains. Five-to-ten year viability favors integrated health service providers bundling laboratory testing with formulated feed delivery. Monitor Japan's MHLW positive list system expansion as signal for premium tier demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Australian feedlots adopt precision delivery systems to optimize tilmicosin bioavailability and reduce environmental loading. |
| Veterinary Distribution Channel Construction | Myanmar and Cambodia frontier markets lack established infrastructure, creating first-mover consolidation opportunities. |
| MHLW Compliance Certification Investment | Thai and Malaysian export-oriented producers seek residue management protocols for premium beef and pork quotas. |
| API Supply Diversification | Southeast Asian formulators reduce Chinese concentration risk through Indian and South Korean sourcing alternatives. |
| Integrated Livestock Health Contracting | Queensland feedlots displace transactional premix purchasing through diagnostic-linked therapeutic protocol bundles. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across veterinary pharmaceutical manufacturing, commercial livestock production, and regulatory compliance domains. Primary interviews captured formulation chemists, feedlot procurement managers, and CDSCO regulatory affairs specialists. Secondary validation drew from MEE discharge filings, TGA residue monitoring reports, Indian customs trade data, and Japanese MHLW positive list amendments. Bottom-up volume modeling triangulated against top-down value estimates across compound class and species segments.
Across the analysis window, projections incorporate tetracycline and macrolide adoption trajectories, prescription mandate enforcement timelines, and export market compliance tiering. Segmentation dimensions span antibiotic compound class, target species physiology, formulation technology, and distribution channel regulatory status. CAGRs derive from fitted growth curves calibrated to livestock inventory expansion, intensive housing system penetration, and residue limit tightening schedules. Feed conversion efficiency metrics and veterinary oversight cost curves inform price elasticity assumptions.
Forecasts assume regulatory continuity in China's MEE enforcement, India's CDSCO prescription mandate, and Japan's MHLW positive list system; material policy shifts would require re-modeling. Antimicrobial resistance surveillance outcomes, phytogenic efficacy validation, and frontier market infrastructure buildout pace constitute primary revision triggers. Recalibration cycles align with material shifts in GB standards implementation, CDSCO inspection intensity, and Australian feedlot procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Feed Antioxidants Market