
 Turf and Ornamental Inputs Market | 2026-2036
Turf and Ornamental Inputs Market Size, Share, and Industry Trends Forecast 2026-2036
Turf and Ornamental Inputs Market Analytics
A shift from single-source chemical procurement to multi-source biological and synthetic portfolios is broadening supplier relationships across the Turf and Ornamental Inputs Market. BASF SE anchors its position through advanced formulation R&D for golf course and sports field applications. Syngenta AG competes via integrated seed-to-solution platforms that extend into ornamental pest management. Nufarm Limited specializes in off-patent active ingredient supply, leveraging manufacturing scale to control cost-sensitive segments.
Turf and Ornamental Inputs comprise chemically and biologically active products applied to non-crop vegetation, including nitrogen-phosphorus-potassium formulations with micronutrient packages and systemic fungicides with specified application rates per thousand square feet. Their primary purpose is to sustain aesthetic quality, playability, and plant health across managed landscapes where visual uniformity and surface performance carry commercial value. Fertilizers dominate product-type revenue due to recurring seasonal application cycles across golf courses and sports fields. Herbicides capture expanding share as glyphosate-resistant weed populations alter maintenance protocols. Online platforms represent the fastest-growing distribution channel, though wholesale distributors still occupy the margin pool through technical service bundling.
EPA registration requirements under FIFRA govern pesticide composition and label claims for turf applications in the United States. State-level departments of agriculture in Florida, California, and Texas enforce additional notification and buffer-zone rules that shape local product availability. ECHA's REACH framework and the EU Green Deal's Farm to Fork pesticide reduction targets constrain formulation chemistry for European suppliers. Stakeholders must monitor evolving biologicals registration pathways and state-level neonicotinoid restrictions to anticipate portfolio rebalancing requirements.
Market Dynamics
Precision nutrient programs are compressing application frequencies across golf course maintenance protocols, forcing input suppliers to reformulate for extended-release performance rather than volume-driven repeat sales.
Growth Catalysts
- EPA FIFRA Registration Pathways:Streamlined biological pesticide approvals are accelerating novel active ingredient commercialization for turfgrass disease management.
- Sun Belt Climate Concentration:Year-round growing seasons in Florida, Texas, and California sustain continuous fertilizer and fungicide consumption cycles.
- Soil Microbiome Analytics:On-site biological testing is enabling customized microbial inoculant prescriptions for ornamental nursery operations.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers control upstream synthesis of glyphosate and dicamba intermediates, exposing formulators to trade policy volatility.
- Neonicotinoid Restrictions:State-level bans in New York and Connecticut are eliminating systemic insecticide options for ornamental pest control.
- Phosphorus Runoff Liability:Chesapeake Bay and Great Lakes watershed regulations impose buffer-zone setbacks that reduce treatable acreage per property.
Strategic Opportunities
- Biostimulant Registration Acceleration:USDA BioPreferred program incentives are opening federal procurement channels for amino acid and seaweed extract formulations.
- Direct-to-Superintendent Platforms:E-commerce channels are bypassing traditional distribution markups for municipal golf course maintenance departments.
- Sports Turf Convergence:Hybrid bermudagrass overseeding protocols for professional stadiums are creating demand for specialized colorant and growth regulator combinations.
Industry Challenges
- Calibration Expertise Scarcity:Spreaders and sprayers with variable-rate technology require certified operators that most municipal parks departments cannot retain.
- Legacy Inventory Obsolescence:State label amendments for chlorpyrifos and diazinon are forcing distributors to absorb write-downs on stocked product.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turf and Ornamental Inputs Market |
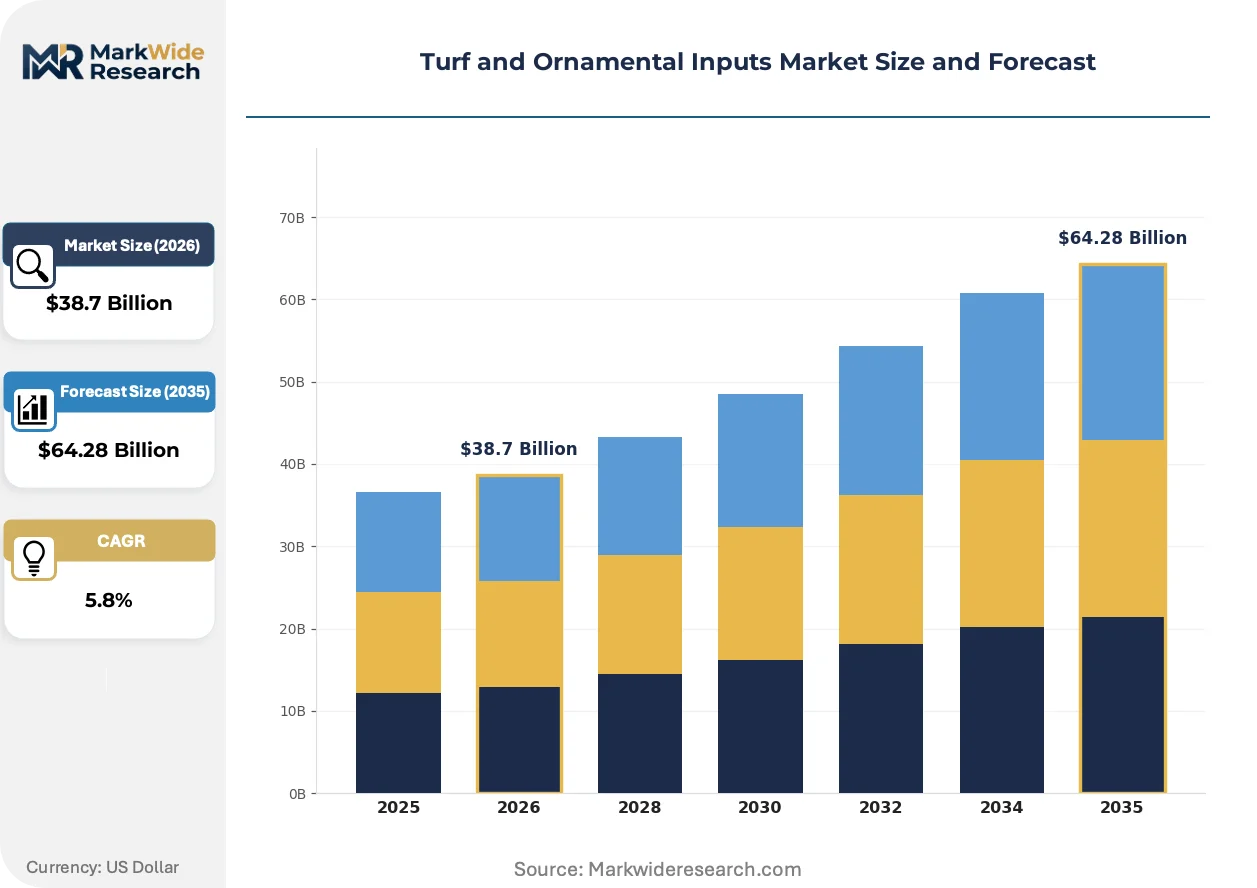
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Pesticides, Herbicides, Soil Amendments Application: Home Gardens, Golf Courses, Sports Fields, Landscaping End User: Gardeners, Golf Course Managers, Landscape Contractors, Parks Departments Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Agricultural Cooperatives |
| Companies Covered | FMC Corporation, Adama Agricultural Solutions, BASF SE, Corteva Agriscience, American Vanguard Corporation, Bayer CropScience AG, Nufarm Limited, SiteOne Landscape Supply Inc, Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turf and Ornamental Inputs Market Evolving Landscape
Electrification of application equipment is reshaping product formulation requirements, as battery-powered precision sprayers demand lower-viscosity tank mixes and reduced-volume carriers.
Controlled-release nitrogen polymer coatings are electrifying fertilizer performance benchmarks across championship golf courses. Superintendents at facilities like Augusta National and Pebble Beach are adopting 8-12 week longevity formulations to reduce labor costs. This chemistry is compressing seasonal application counts from six passes to three, threatening volume-dependent distributor revenue models.
REACH authorization requirements under ECHA are constraining copper-based fungicide availability for European ornamental producers. The framework's substitution mandate is accelerating triazole and SDHI chemistry transitions in Dutch bulb operations. German nursery associations are petitioning for extended transition timelines to avoid crop loss during the 2025 growing season.
Integrated pest management certification is becoming a mandatory procurement filter for municipal and institutional buyers. Landscape maintenance contracts in California school districts and Texas HOA portfolios now require documented biological control rotation protocols. This specification shift is elevating suppliers with technical service capabilities over commodity chemical vendors in competitive bidding processes.
Turf and Ornamental Inputs Market Segmentation
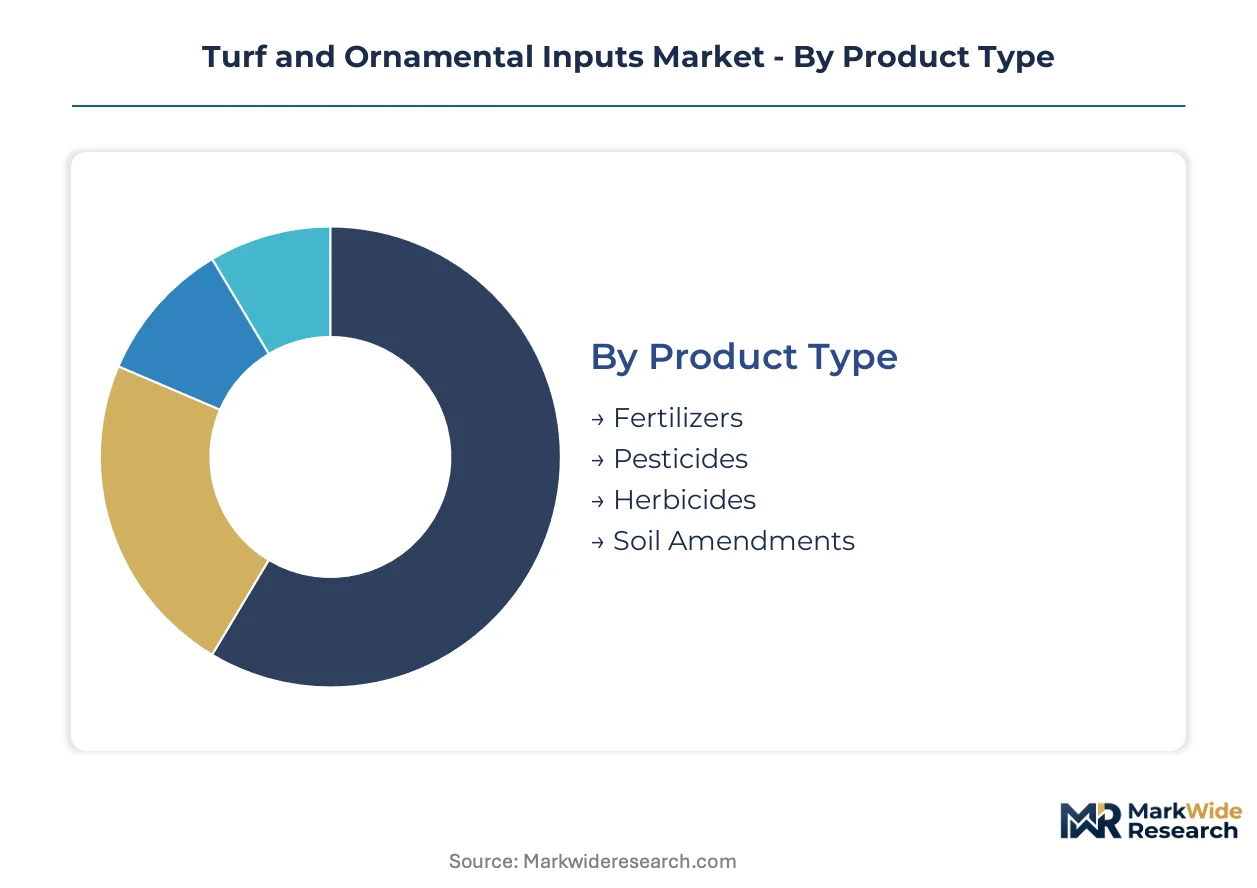
Turf and ornamental inputs serve distinct performance requirements across managed landscapes, from precision nutrient delivery on championship golf courses to cost-effective maintenance protocols for municipal parks. Segmentation reveals how formulation chemistry, application equipment, and procurement channels align with specific end-use value thresholds.
Product Type:
Formulation chemistry and release mechanism specifications define competitive positioning within each product category, with polymer coating technologies and biological active ingredients reshaping performance benchmarks.
- Fertilizers:Nitrogen-phosphorus-potassium formulations with micronutrient packages dominate recurring revenue through seasonal application cycles. Controlled-release polymer coatings extending longevity to 8-12 weeks are compressing application frequencies across Sun Belt golf courses, threatening volume-dependent distributor models.
- Pesticides:Systemic fungicides with specified application rates per thousand square feet sustain plant health where visual uniformity carries commercial value. EPA streamlined biological pesticide approvals are accelerating novel active ingredient commercialization for turfgrass disease management.
- Herbicides:Glyphosate-resistant weed populations are altering maintenance protocols and expanding category share. Chinese manufacturers control upstream synthesis of glyphosate and dicamba intermediates, exposing formulators to trade policy volatility.
- Soil Amendments:Customized microbial inoculant prescriptions enabled by on-site biological testing are gaining traction in ornamental nursery operations.
Mature deployment sits with Fertilizers. Newer deployment is concentrated in Soil Amendments.
Application:
Surface performance requirements and aesthetic standards vary sharply across end-use settings, with professional sports venues and residential landscapes operating on fundamentally different input specifications and procurement timelines.
- Golf Courses:Precision nutrient programs demand extended-release performance rather than volume-driven repeat sales. Superintendents at facilities like Augusta National and Pebble Beach are adopting 8-12 week longevity formulations to reduce labor costs.
- Sports Fields:Hybrid bermudagrass overseeding protocols for professional stadiums are creating demand for specialized colorant and growth regulator combinations. Battery-powered precision sprayers are reshaping product formulation requirements for lower-viscosity tank mixes.
- Landscaping:Integrated pest management certification is becoming a mandatory procurement filter for municipal and institutional buyers in California school districts and Texas HOA portfolios.
- Home Gardens:E-commerce channels are bypassing traditional distribution markups for residential consumers seeking convenience and price transparency.
Procurement sophistication peaks with Golf Courses. Volume expansion is climbing the fastest in Sports Fields.
End User:
Technical expertise availability and budget authority shape input selection, with certified operators commanding premium formulations and municipal purchasers prioritizing compliance documentation.
- Golf Course Managers:Spreaders and sprayers with variable-rate technology require certified operators that most municipal parks departments cannot retain, creating capability scarcity.
- Landscape Contractors:Technical service bundling through wholesale distributors occupies the margin pool for commercial maintenance operations.
- Parks Departments:Direct-to-superintendent platforms are emerging for municipal golf course maintenance departments seeking to bypass traditional markups.
- Gardeners:Online platforms represent the fastest-growing access channel for residential end users.
Technical complexity concentrates with Golf Course Managers. Procurement autonomy is expanding most quickly among Landscape Contractors.
Distribution Channel:
Channel economics reflect service intensity requirements, with high-touch technical support commanding margin premiums and digital platforms capturing price-sensitive transactional volume.
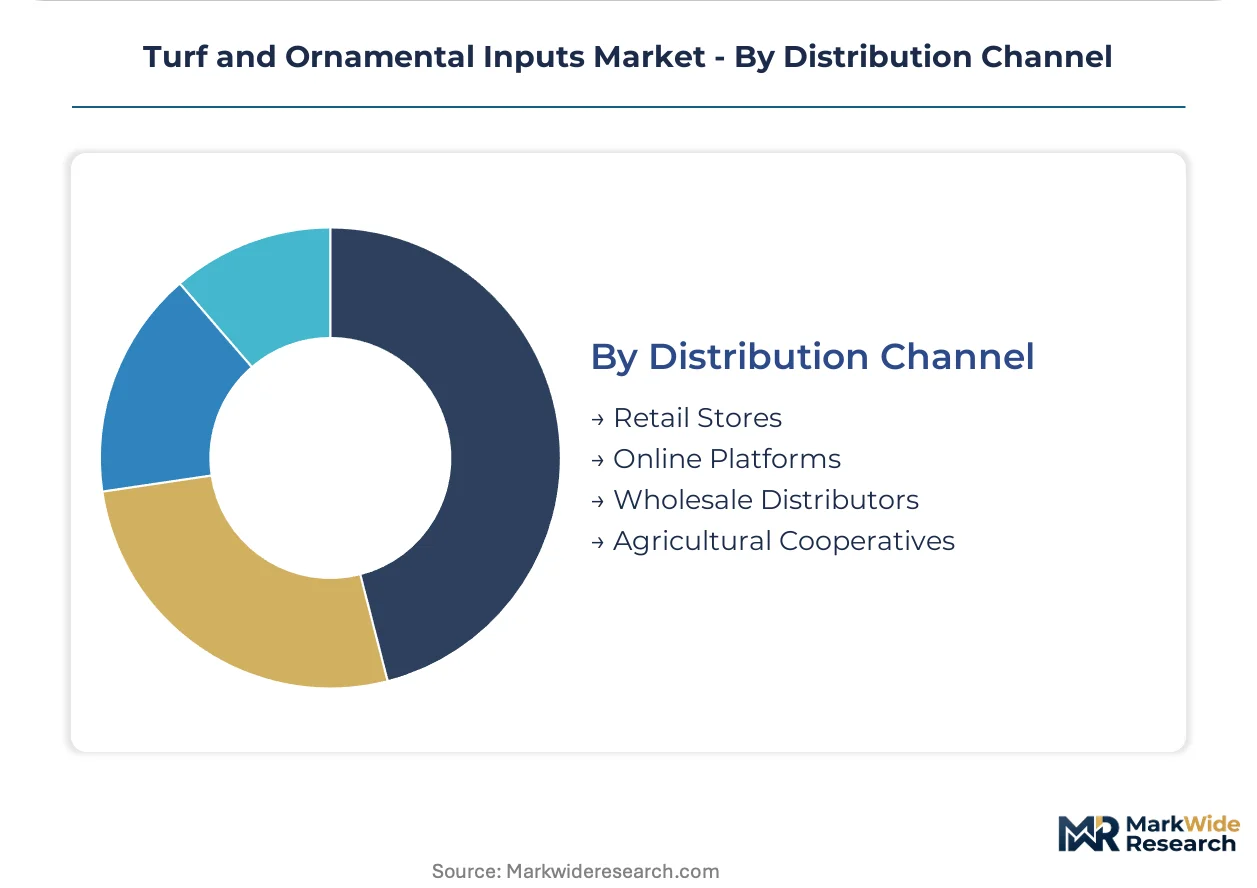
- Wholesale Distributors:Technical service bundling maintains margin pool dominance through certified agronomist support and inventory financing for seasonal demand spikes.
- Online Platforms:E-commerce expansion is compressing traditional distributor markups for municipal and residential buyers. This channel is gaining share fastest.
- Retail Stores:Immediate product availability and localized agronomic advice sustain relevance for emergency pest and disease interventions.
- Agricultural Cooperatives:Volume aggregation and group purchasing power serve cost-sensitive landscape maintenance operations in rural and semi-urban markets.
Service integration peaks with Wholesale Distributors. Digital migration is accelerating most rapidly through Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for turf and ornamental inputs concentrates in the United States, where year-round maintenance cycles across Sun Belt states sustain continuous consumption. European regulatory constraints are reshaping supplier portfolios, while Asia-Pacific growth emerges from golf course development and urban landscaping expansion.
United States
Precision nutrient programs across Florida, Texas, and California golf courses drive sustained fertilizer and fungicide consumption. EPA FIFRA registration pathways govern pesticide composition, while state agriculture departments enforce additional buffer-zone rules. The Sun Belt corridor from Orlando to San Diego anchors volume, with superintendents at Augusta National and Pebble Beach adopting extended-release formulations.
Germany
Dutch bulb operations and ornamental nurseries generate concentrated demand for disease management chemistry. ECHA REACH authorization requirements constrain copper-based fungicide availability, accelerating triazole and SDHI transitions. German nursery associations in Lower Saxony petition for extended transition timelines to avoid crop loss during peak growing seasons.
China
Upstream synthesis of glyphosate and dicamba intermediates concentrates manufacturing capacity, exposing global formulators to trade policy volatility. The Ministry of Ecology and Environment enforces dual carbon goals that tighten chemical production standards. Shandong and Jiangsu provinces host the bulk of active ingredient production, with domestic golf course development expanding downstream demand.
Australia
Sports field maintenance and municipal park programs sustain steady herbicide and fertilizer consumption across temperate coastal zones. The Therapeutic Goods Administration and state environmental protection agencies regulate runoff and application protocols. Sydney and Melbourne metropolitan councils drive procurement sophistication, with hybrid bermudagrass management creating specialized input demand.
United Kingdom
Heritage golf courses and estate landscaping sustain premium product demand despite compressed maintenance budgets. HSE pesticide registration and EU-legacy REACH compliance shape product availability for ornamental producers. The Southeast England corridor from Surrey to Kent concentrates championship course density, where precision application equipment adoption outpaces national averages.
Turf and Ornamental Inputs Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers rebalance biological and synthetic offerings. The vendor base clusters around three strategic tiers: integrated agricultural conglomerates with seed-to-solution platforms, specialized turf formulators with regional service networks, and generic manufacturers leveraging off-patent chemistry scale. Competitive intensity centers on formulation R&D partnerships and direct-to-superintendent digital channels that bypass traditional distribution markups.
Within the integrated agrochemical tier, BASF SE and Syngenta AG exemplify divergent positioning archetypes. BASF anchors premium formulation development for golf course and sports field applications, while Syngenta extends integrated pest management platforms into ornamental disease control. Nufarm Limited occupies the manufacturing-scale tier, supplying cost-sensitive segments through off-patent active ingredient volumes. SiteOne Landscape Supply represents the distribution-consolidation archetype, bundling technical service with inventory financing for seasonal demand spikes.
| Leading Market Players |
|---|
| FMC Corporation |
| Adama Agricultural Solutions |
| BASF SE |
| Corteva Agriscience |
| American Vanguard Corporation |
| Bayer CropScience AG |
| Nufarm Limited |
| SiteOne Landscape Supply Inc |
| Syngenta AG |
| Others |
Value Network & Pricing Analysis
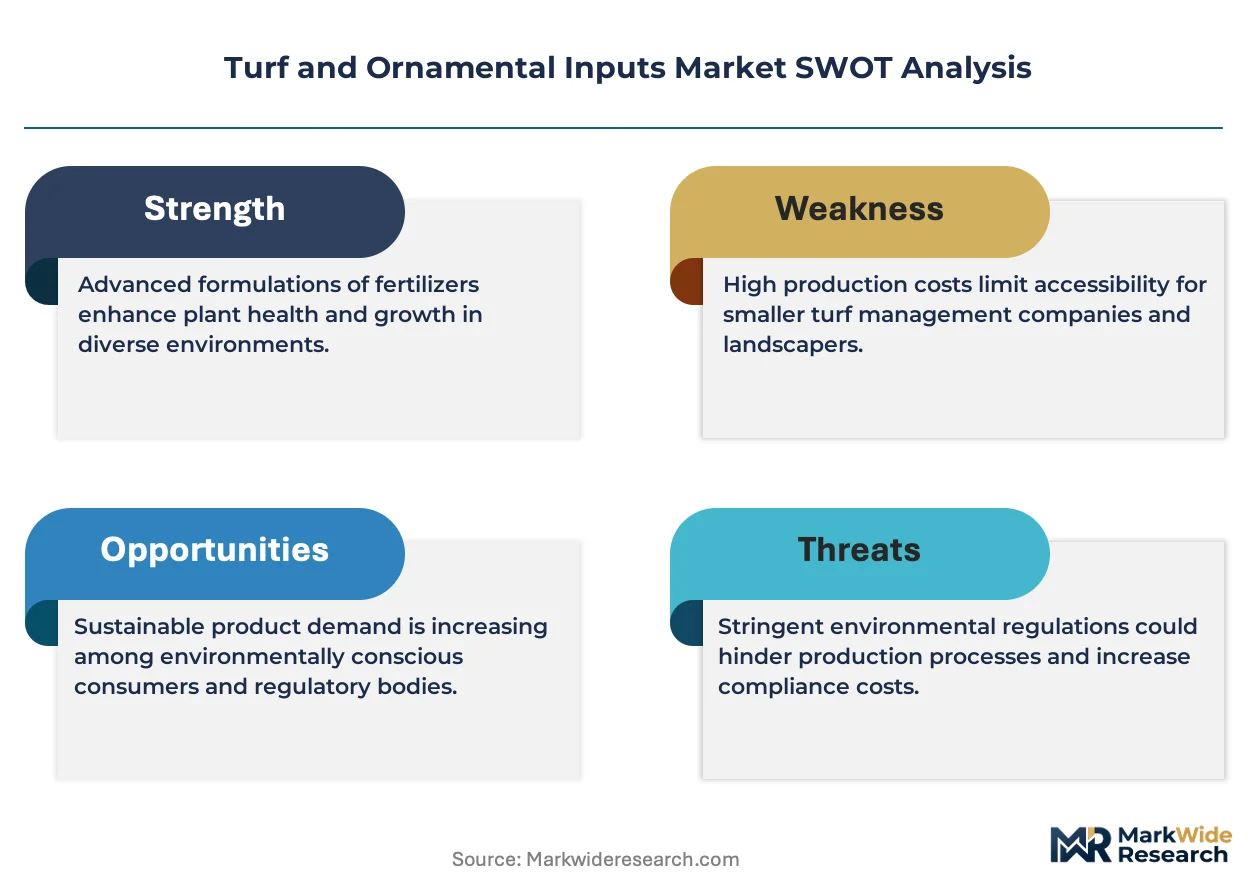
Private-equity-rolled-up distributors like SiteOne Landscape Supply anchor pricing discipline through inventory financing leverage, compressing margins for smaller wholesalers unable to match seasonal credit terms while simultaneously locking in superintendent loyalty via certified agronomist bundling.
Pricing Analysis
Volume-driven distributor revenue from six-pass seasonal fertilizer programs is yielding to margin-protected three-pass extended-release formulations. Three-tier pricing structure across premium polymer-coated, standard granular, and economy bulk-blend levels separates championship golf courses from municipal parks and residential gardeners. Cost compression in the economy tier is intensifying because Chinese glyphosate intermediate producers are passing through tariff exposure. Municipal parks departments exhibit highest price sensitivity due to fixed budget cycles, while Augusta National-tier facilities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Returns of obsolete chlorpyrifos and diazinon stocks are forcing distributors to absorb write-downs, creating reverse-logistics costs that reshape procurement timing and inventory depth decisions. Active ingredient synthesis concentrates in China, India, and Germany, with Shandong province hosting glyphosate intermediate production and Gujarat housing generic formulation facilities. Formulation chemistry draws from petroleum-derived polymer feedstocks, phosphate rock concentrates, and biological fermentation substrates. Single-source vulnerability sits with Chinese dicamba intermediate supply, exposing Nufarm and Adama to trade policy volatility. Distribution runs through wholesale agronomist networks for technical service, though direct-to-superintendent e-commerce channels are capturing price-transparent municipal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race: manufacturers are pursuing captive supply of controlled-release polymer coatings to escape specialty chemical supplier pricing power and secure formulation differentiation.
For Market Incumbents: Lock in extended-release polymer supply agreements with specialty chemical producers before capacity tightens, while simultaneously acquiring regional biological testing laboratories to capture soil microbiome analytics revenue streams threatened by independent agritech entrants. BASF and Syngenta must defend against SiteOne's consolidation momentum by embedding certified superintendents within distributor technical teams. For New Entrants and Emerging Players: Begin with municipal parks departments in Sun Belt states where calibration expertise scarcity creates service gaps that variable-rate spreader-as-a-service models can fill. The most penetrable white space sits in direct-to-superintendent platforms for Florida and Texas golf courses seeking to bypass wholesale markups. A biological inoculant subscription paired with on-site testing hardware offers recurring revenue without legacy inventory burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor off-patent formulators with manufacturing scale in India and established EPA registration portfolios, as REACH compliance costs and neonicotinoid label amendments force European and Northeast US specialty players into restructuring. Long-term viability over the coming decade hinges on biologicals registration acceleration under USDA BioPreferred pathways. The signal to watch is state-level phosphorus runoff litigation settlement timelines, which will compress treatable acreage and favor precision application technology providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Coatings | Captive supply of controlled-release nitrogen chemistry secures margin protection against specialty chemical price volatility. |
| Biologicals Registration Acceleration | USDA BioPreferred program incentives open federal procurement channels for amino acid and seaweed extract formulations. |
| Direct-to-Superintendent Platform Launch | E-commerce bypass of wholesale markups captures price-sensitive municipal golf course maintenance departments in Sun Belt states. |
| Soil Microbiome Testing Laboratory Acquisition | On-site biological analytics enable customized microbial inoculant prescriptions for ornamental nursery operations. |
| Variable-Rate Application Equipment Partnership | Battery-powered precision sprayer integration demands lower-viscosity tank mixes and reduces-volume carriers from formulation partners. |
Research Methodology
Multi-period observation of EPA registration approval timelines, state-level neonicotinoid restriction enactments, and golf course superintendent procurement surveys anchored the trend analysis, supplemented by interviews with formulation R&D directors, wholesale distributor agronomists, municipal parks procurement officers, and biological testing laboratory operators. Secondary validation drew from EPA FIFRA registration databases, state agriculture department enforcement records, USDA BioPreferred program disclosures, and SEC filings of publicly traded input suppliers. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against end-use expenditure patterns ensured consistency.
Segment-weighting across fertilizers, pesticides, herbicides, and soil amendments incorporated application-frequency compression effects from extended-release formulations and biological substitution rates. Modeled dimensions included product chemistry, release mechanism specifications, end-use setting sophistication, and distribution channel service intensity. CAGRs were derived from recursive substitution modeling of synthetic-to-biological transitions and precision application equipment penetration curves. Industry-specific forecast inputs encompassed EPA streamlined biological pesticide approval velocity and Sun Belt climate concentration effects on year-round consumption cycles.
Underlying measurement precision varies by segment; fertilizer volume estimates carry tighter precision than nascent soil amendment categories where biological testing adoption remains uneven. Forecasts reflect assumptions around regulatory pathway stability and trade policy continuity for Chinese intermediate supply. Practitioners should monitor state-level phosphorus runoff litigation filings and EPA neonicotinoid registration review timelines for early signals of portfolio rebalancing requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market