
 Crop Spraying Drone Market | 2026-2036
Crop Spraying Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Spraying Drone Market Insights
Pay-per-acre spraying contracts and equipment-leasing cooperatives is fragmenting capital requirements across smallholder networks. DJI leverages its manufacturing scale to dominate multirotor hardware in East Asian markets. XAG Co., Ltd anchors its position through AI-assisted targeting systems that reduce chemical overuse. Yamaha Motor Co., Ltd sustains premium positioning with industrial-grade reliability in Japanese rice-farming cooperatives.
Crop spraying drones are unmanned aerial vehicles equipped with precision pump systems, spray nozzles, and tank capacities typically ranging from ten to thirty liters, designed to distribute agrochemicals with GPS-guided accuracy over irregular terrain. Multirotor configurations lead current deployment due to vertical takeoff capability and low-altitude maneuverability around obstacles, while fixed-wing drones capture expanding share in broad-acre cereal operations where flight endurance outweighs flexibility. Agricultural service providers represent the fastest-growing end-user category as farm operators outsource capital-intensive fleet ownership to specialized spraying businesses.
FAA Part 107 rules and EASA drone-specific regulations shape product certification requirements and pilot training standards across North American and European markets, while China's CAAC low-altitude economy policies accelerate domestic manufacturing scale. ESG-linked chemical-reduction mandates and emerging ISO standards for aerial application precision will determine which platform architectures achieve preferred-supplier status with institutional buyers. Stakeholders must monitor regulatory divergence between permissive commercial zones and restrictive flight corridors as this fragmentation determines viable go-to-market pathways.
Market Dynamics
Fleet ownership concentration among agricultural service providers is compressing equipment procurement cycles and forcing manufacturers toward pay-per-use hardware economics rather than outright sales.
Growth Catalysts
- FAA Part 107 waivers:Expanded commercial flight corridors in the US are unlocking large-scale soybean and corn operations for aerial application services.
- AI-assisted targeting systems:Computer vision-enabled nozzle control reduces chemical overuse rates and satisfies tightening ESG-linked chemical-reduction mandates.
- East Asian manufacturing scale:Shenzhen and Guangzhou production clusters are driving unit cost compression for multirotor platforms.
Market Restraints
- Li-ion battery supply concentration:Cathode material processing dependency on Chinese refiners creates input cost volatility and geopolitical exposure.
- EASA open-category payload limits:European operators face structural barriers to tank capacity expansion above 25 kilograms.
- Ground-based precision spraying:Autonomous tractor-mounted systems threaten drone penetration in flat, broad-acre cereal geographies.
Strategic Opportunities
- Indian smallholder cooperatives:Equipment-leasing pools fragment capital requirements across fragmented landholdings below 5 hectares.
- ISO 21384-3 compliance:Emerging aerial application precision standards create preferred-supplier accreditation pathways for institutional buyers.
- Hyperspectral-LiDAR convergence:Early-stage pest detection integration enables preventive spraying contracts ahead of visible crop damage.
Industry Challenges
- Part 107 remote pilot certification:FAA training throughput constraints create operational scaling bottlenecks for spraying service providers.
- Legacy farm management software:Integration friction with established yield-mapping platforms delays fleet deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Spraying Drone Market |
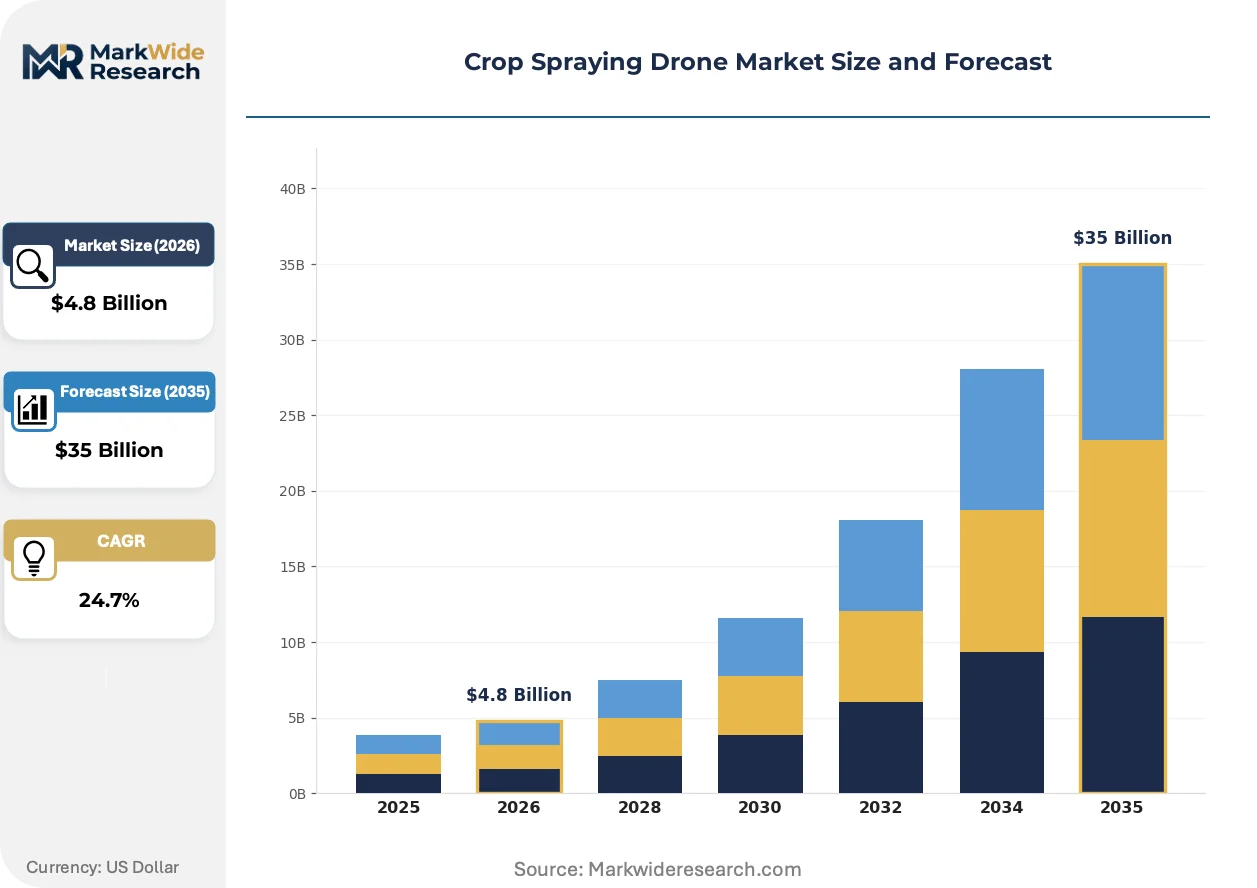
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor Drones, Fixed-Wing Drones, Hybrid Drones, Agricultural Robots Application: Pesticide Application, Fertilizer Spraying, Seed Sowing, Crop Monitoring End User: Farmers, Agricultural Service Providers, Government Agencies, Research Institutions Technology: GPS Navigation, AI-Assisted Targeting, Automated Flight Planning, Remote Sensing |
| Companies Covered | DJI, XAG Co., Ltd, Yamaha Motor Co., Ltd, AeroVironment, Inc., Parrot SA, PrecisionHawk, AgEagle Aerial Systems, Autel Robotics, 3D Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Spraying Drone Market Trends and Innovations
Platform architecture decisions are pivoting around endurance-versus-maneuverability tradeoffs as operators segment their fleets by crop type and terrain complexity.
Electrostatic spray charging is migrating from experimental vineyard trials to mainstream row-crop deployment. California almond cooperatives are adopting the technology at pilot-scale. Droplet adhesion improvements are compressing chemical volume requirements per hectare and reshaping tank capacity specifications.
China's CAAC low-altitude economy policies are accelerating domestic airspace classification reforms. Unmanned traffic management corridor designation is enabling beyond-visual-line-of-sight operations in Heilongjiang rice belts. Domestic manufacturers are responding with extended-range fixed-wing platforms optimized for these corridors.
Service contracts now unbundle hardware ownership from application labor. Brazilian soybean operators are purchasing spraying outcomes by treated acre rather than leasing equipment. This procurement evolution concentrates fleet purchasing power among specialized aerial application businesses and marginalizes individual farm ownership.
Crop Spraying Drone Market Segmentation
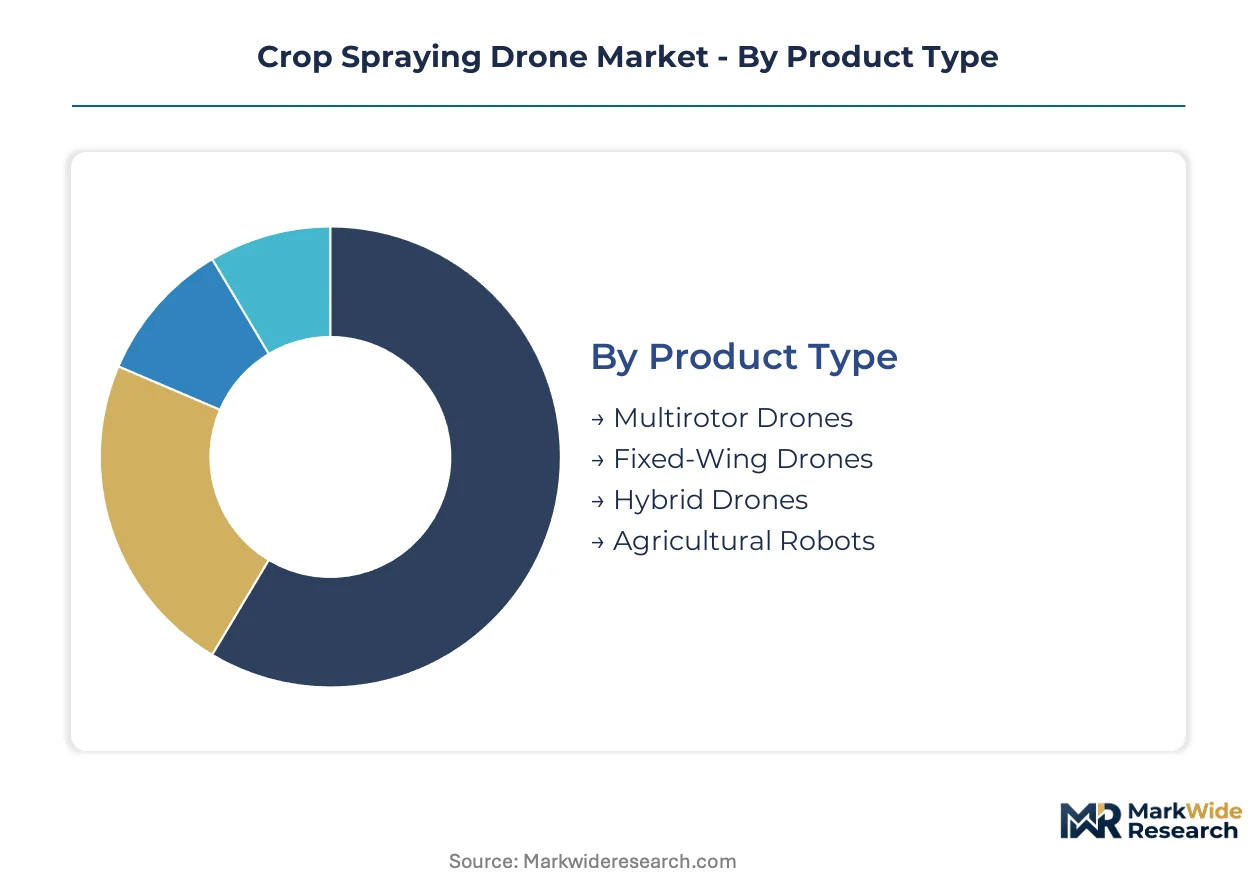
Crop spraying drone procurement patterns diverge sharply by operational tempo and capital intensity. Fleet operators prioritize platform architectures that match crop cycles and terrain constraints, while service providers segment investments by contract duration and acreage commitments.
Product Type:
Multirotor configurations turn over fastest due to battery degradation and nozzle wear in high-frequency spraying cycles, while fixed-wing platforms operate on slower replacement schedules tied to airframe certification intervals.
- Multirotor Drones:Vertical takeoff capability and low-altitude maneuverability around obstacles define this architecture. Demand concentrates in Brazilian soybean operations and Chinese rice belts where irregular terrain limits ground-based alternatives. DJI's manufacturing scale in Shenzhen compresses procurement lead times for agricultural service providers.
- Fixed-Wing Drones:Extended flight endurance and higher payload efficiency suit broad-acre cereal operations. Adoption is climbing in Heilongjiang province where CAAC unmanned traffic management corridors enable beyond-visual-line-of-sight missions across flat topography.
- Hybrid Drones:Combines vertical takeoff with fixed-wing cruise efficiency for mixed-terrain deployments.
- Agricultural Robots:Ground-based autonomous platforms compete for spraying contracts in orchard and vineyard settings.
Multirotor platforms anchor the volume base while fixed-wing configurations gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity chemical application from premium precision services requiring sensor integration and prescription mapping.
- Pesticide Application:The dominant revenue category, requiring calibrated droplet sizing and electrostatic charging for canopy penetration. Brazilian soybean operators and Indian cotton cooperatives drive contract volume through pay-per-acre outsourcing models.
- Fertilizer Spraying:Variable-rate application based on NDVI mapping commands premium pricing. Uptake is expanding in US corn operations where USDA precision agriculture incentives offset equipment costs.
- Seed Sowing:Drone-based rice seeding in Japanese farming cooperatives reduces labor dependency during narrow planting windows.
- Crop Monitoring:Hyperspectral and multispectral imaging enables early pest detection ahead of visible damage thresholds.
Pesticide application commands the installed base while fertilizer spraying climbs fastest on precision agriculture adoption curves.
End User:
Customer type determines ownership models, with capital concentration shifting from individual farms to specialized service businesses.
- Agricultural Service Providers:Fleet-based businesses capture economies of scale through multi-client route optimization. Indian equipment-leasing cooperatives fragment capital requirements across smallholder networks below five hectares.
- Farmers:Direct ownership persists in large-scale operations with in-house maintenance capabilities and FAA Part 107 certified pilots.
- Government Agencies:Mosquito control and public health spraying contracts in Brazil and Southeast Asia sustain dedicated procurement channels.
- Research Institutions:Field trial validation and protocol development for emerging chemistries and biological agents.
Agricultural service providers anchor fleet purchasing volume while government agency contracts expand on vector control mandates.
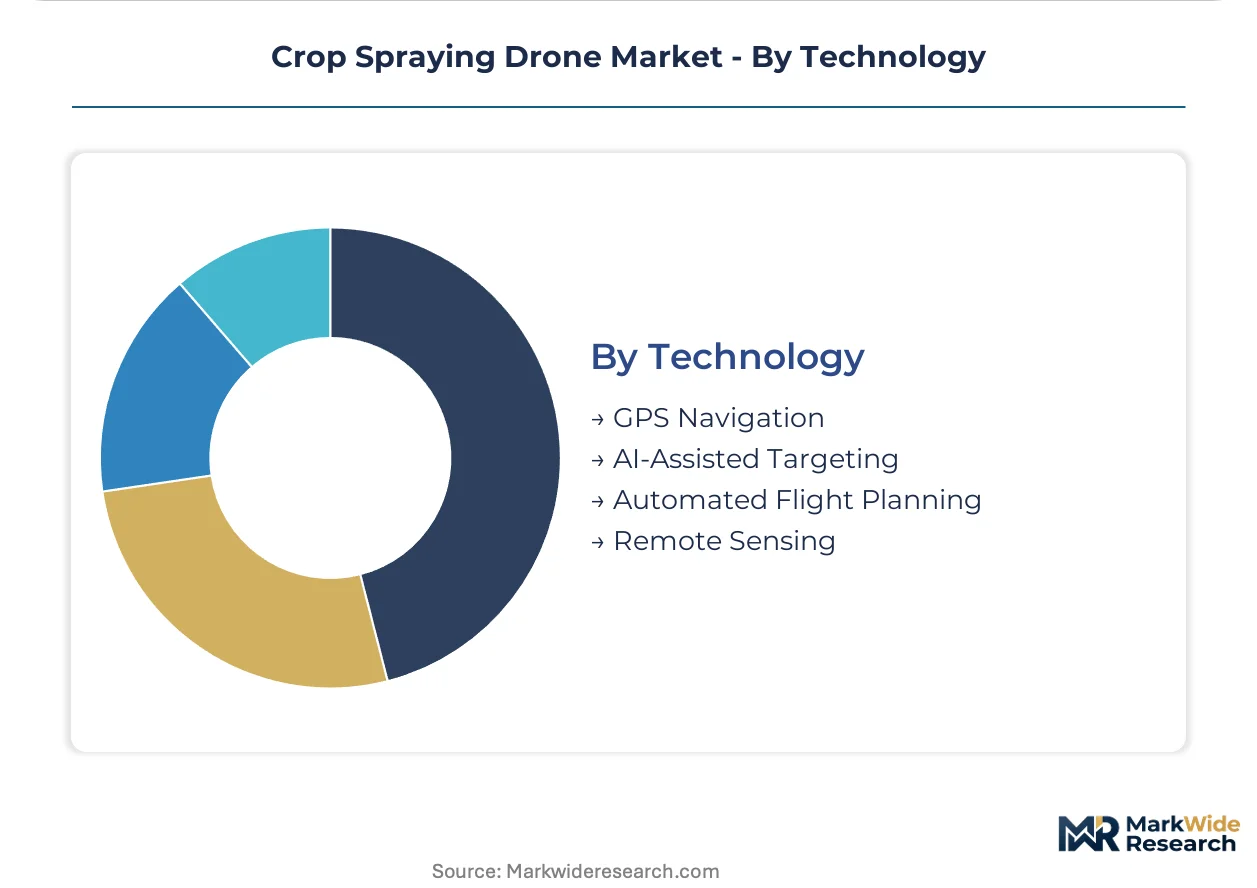
Technology:
Technology stack decisions hinge on integration friction with legacy farm management software and certification requirements under evolving ISO standards.
- AI-Assisted Targeting:Computer vision-enabled nozzle control reduces chemical overuse and satisfies tightening ESG-linked reduction mandates. XAG's deployment in East Asian markets demonstrates commercial viability at scale.
- GPS Navigation:RTK-GPS centimeter-level accuracy underpins prescription mapping and automated flight path execution. Regulatory acceptance varies by jurisdiction, with EASA open-category rules imposing operational altitude constraints.
- Automated Flight Planning:Cloud-based mission design reduces pilot training burdens and operational scaling bottlenecks.
- Remote Sensing:Multispectral payload integration enables variable-rate application and yield prediction modeling.
GPS navigation anchors baseline platform specifications while AI-assisted targeting climbs fastest on chemical reduction compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural service providers concentrate fleet purchasing power in four countries where soybean, corn, and rice operations generate contract volume. FAA, EASA, and CAAC regulations determine airspace access and pilot certification requirements across these markets.
United States
Soybean and corn operators in Iowa and Illinois outsource spraying to specialized fleet businesses. FAA Part 107 waivers expand commercial flight corridors beyond visual line of sight. California almond cooperatives in the Central Valley pilot electrostatic spray charging at scale.
Brazil
Mato Grosso and Goiás soybean belts drive pay-per-acre contract proliferation among agricultural service providers. ANVISA agrochemical registration timelines shape equipment deployment schedules. São Paulo-based leasing cooperatives fragment capital requirements across smallholder networks.
China
Heilongjiang rice belts and Guangdong fruit orchards generate multirotor platform demand. CAAC low-altitude economy policies accelerate unmanned traffic management corridor designation. Shenzhen manufacturing clusters compress unit costs for domestic agricultural service providers.
India
Cotton cooperatives in Maharashtra and Gujarat adopt equipment-leasing pools for holdings below five hectares. DGFT import duty structures on Li-ion batteries influence fleet procurement economics. Karnataka precision agriculture pilots integrate AI-assisted targeting with existing farm management systems.
Japan
Rice-farming cooperatives in Niigata and Aomori prefectures sustain demand for industrial-grade reliability standards. METI subsidies for smart agriculture equipment offset capital costs for specialized spraying businesses. Yamaha Motor anchors premium positioning through cooperative service contracts.
Crop Spraying Drone Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware manufacturing, software integration, and service provision tiers. The vendor base organizes around three strategic archetypes: Shenzhen-scale manufacturers leveraging production cluster economics, precision agriculture specialists bundling sensor-to-spray workflows, and industrial reliability providers serving cooperative networks. Consolidation pressures favor multi-client fleet operators over individual farm ownership. Geographic expansion and technology licensing dominate competitive moves as manufacturers seek regulatory approval across FAA, EASA, and CAAC jurisdictions.
Within the manufacturing-scale tier, DJI and XAG Co., Ltd occupy positions anchored by Guangdong and Guangzhou production cluster access. Yamaha Motor Co., Ltd exemplifies the industrial-reliability archetype through its Japanese cooperative service model. These three entities represent divergent strategic paths: volume-driven unit cost compression, AI-assisted targeting integration, and premium durability positioning for narrow planting-window operations.
| Leading Market Players |
|---|
| DJI |
| XAG Co., Ltd |
| Yamaha Motor Co., Ltd |
| AeroVironment, Inc. |
| Parrot SA |
| PrecisionHawk |
| AgEagle Aerial Systems |
| Autel Robotics |
| 3D Robotics |
| Others |
Pricing and Supply Chain Analysis
Shenzhen-Guangzhou freight corridors compress landed costs for multirotor platforms entering Brazilian and Indian markets, concentrating pricing power among Guangdong manufacturers while fragmenting downstream margins for agricultural service providers dependent on volume-based leasing economics.
Pricing Analysis
Cost-plus contracts with Li-ion cathode material indexation dominate procurement between agricultural service providers and equipment lessors. Three-tier pricing structure across premium, standard, and economy levels separates DJI-scale manufacturers from industrial-reliability specialists and white-label assemblers. Pricing pressure stems from battery supply volatility and EASA payload limit compliance costs. Smallholder cooperatives in India exhibit highest price sensitivity, while Japanese rice-farming cooperatives absorb premiums for narrow planting-window reliability.
Supply Chain Analysis
Contract manufacturing concentrates in Shenzhen and Guangzhou production clusters, with DJI and XAG anchoring captive assembly capacity. Lithium-ion cells, RTK-GPS modules, and carbon-fiber airframes constitute critical input dependencies. Single-source vulnerability in Chinese cathode refining creates geopolitical exposure for non-domestic fleet operators. Distribution runs through agricultural equipment dealerships and direct-to-cooperative service contracts, bypassing traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where FAA Part 107 certification backlogs and CAAC airspace corridor designations create switching costs that protect incumbent fleet operators from hardware commoditization.
For Market Incumbents: Pre-empt autonomous tractor-mounted spraying encroachment by securing exclusive pay-per-acre contracts with Brazilian soybean operators. Deepen backward integration into Li-ion battery pack assembly to offset cathode material cost volatility. Anchor fleet renewal cycles through ISO 21384-3 pre-certification to capture institutional buyer preference.
For New Entrants and Emerging Players: Pursue hyperspectral-LiDAR convergence for preventive spraying contracts ahead of visible pest damage thresholds. Target Indian equipment-leasing cooperatives serving holdings below five hectares, where capital fragmentation creates white-space penetration. Deploy AI-assisted targeting as a differentiated go-to-market wedge against hardware-centric incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant agricultural robotics divisions, where precision agriculture assets trade below standalone value. Long-term viability hinges on regulatory compliance scalability across FAA-EASA-CAAC jurisdictions. Monitor FAA remote pilot certification throughput as the critical inflection signal for service provider expansion capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Beyond-Visual-Line-of-Sight Certification | FAA Part 107 waiver expansion unlocks large-scale soybean and corn operations in Iowa and Illinois. |
| Electrostatic Spray Charging Scale-Up | California almond cooperatives validate droplet adhesion improvements that compress chemical volume requirements. |
| AI-Assisted Targeting Integration | XAG's computer vision-enabled nozzle control satisfies tightening ESG-linked chemical-reduction mandates. |
| Equipment-Leasing Cooperative Formation | São Paulo and Maharashtra pools fragment capital requirements across smallholder networks below five hectares. |
| Unmanned Traffic Management Corridor Designation | CAAC low-altitude economy policies enable fixed-wing penetration in Heilongjiang rice belts. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Field conversations with agricultural service provider fleet managers, FAA Part 107 certified pilots, cooperative procurement officers, and precision agriculture software engineers inform operational scaling constraints. Secondary sources include FAA waiver databases, EASA open-category rulemaking dockets, CAAC unmanned traffic management corridor designations, and ANVISA agrochemical registration timelines. Bottom-up equipment deployment estimates triangulate against top-down addressable acreage calculations.
Calibration against historical fleet procurement cycles and contract renewal patterns shapes the analytical framework. Segmentation dimensions span platform architecture, application type, end-user category, and technology stack across the projection horizon. CAGRs derive from acreage penetration curves, equipment replacement intervals, and regulatory access expansion trajectories. Hyperspectral-LiDAR integration timelines and electrostatic spray charging adoption rates constitute industry-specific forecast inputs.
Sensitivities concentrate around FAA remote pilot certification throughput, Li-ion battery supply disruptions, and EASA payload limit revisions. Forecasts reflect assumptions on airspace liberalization pace and cooperative capital formation velocity. Quarterly review of Part 107 waiver issuance rates and CAAC corridor designation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Battery Powered Sprayer Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Soil Aerators Market