
 Feed Preservatives Market | 2026-2036
Feed Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Preservatives Market Analysis
Asset-light contract manufacturing and third-party tolling arrangements is narrowing the capital barrier for regional preservative blenders seeking scale. Nutreco N.V. leverages integrated premix-to-farm distribution networks across European livestock corridors. BASF SE anchors its position through captive production of synthetic antioxidant intermediates. Kemin Industries specializes in natural antioxidant extraction from botanical sources, competing on clean-label positioning.
Feed preservatives are chemical or biological additives incorporated into animal feed matrices to inhibit oxidative rancidity, mold proliferation, and pathogenic bacterial colonization, typically dosed at 0.01% to 0.5% by weight depending on substrate moisture and ambient storage conditions. Their primary commercial purpose is to extend feed shelf stability, safeguard nutritional density, and reduce mycotoxin-induced productivity losses in intensive animal production systems. Organic acids command the fastest expansion trajectory as antibiotic-growth-promoter bans in major protein-exporting jurisdictions redirect formulation toward acidification-based pathogen suppression. Natural antioxidants attract premium positioning in dairy farm channels where residual carryover into milk fat influences processor acceptance criteria. Preservative blends concentrate margin pools through customized multi-active formulations that address simultaneous oxidative and microbial degradation pathways.
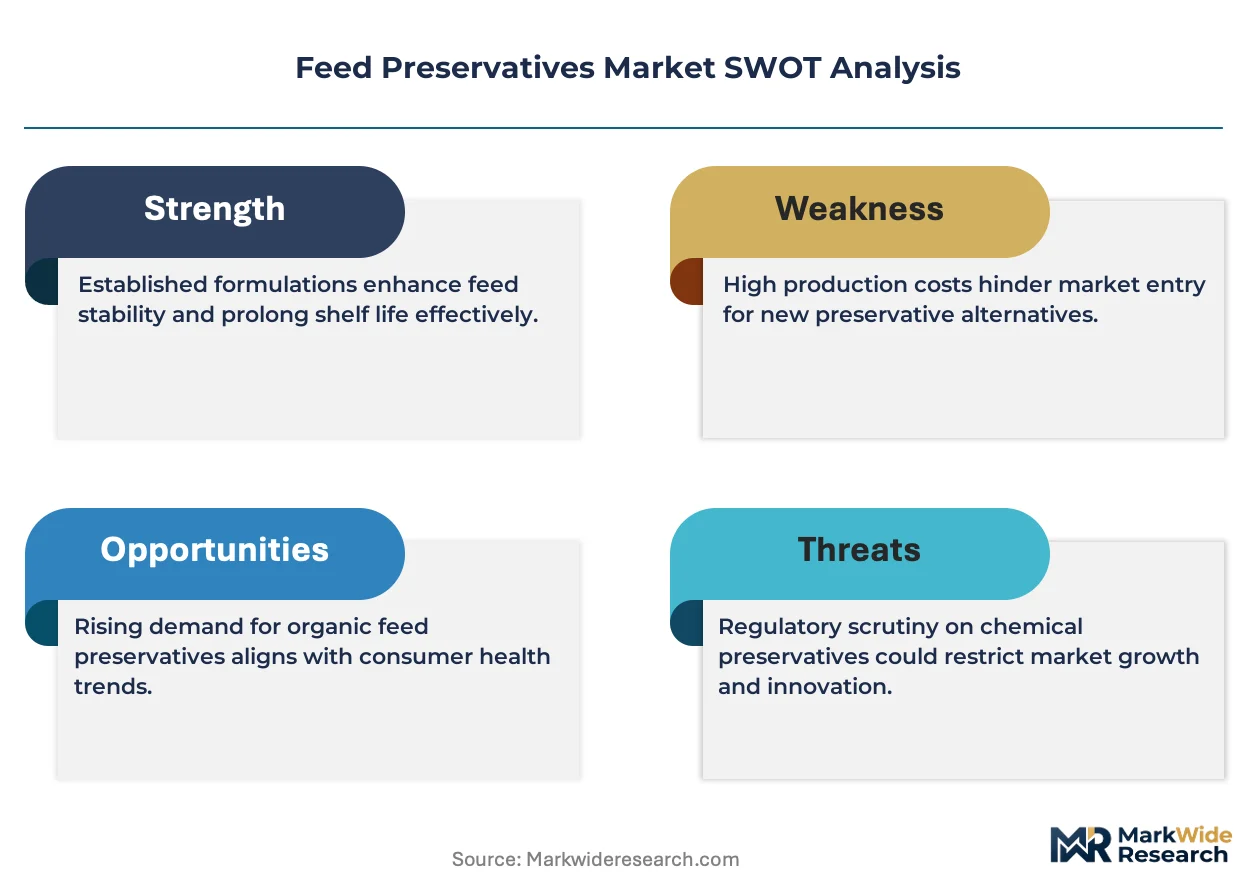
The EU Green Deal's Farm to Fork strategy, enforced through EFSA feed additive re-evaluation protocols, mandates reduced chemical preservitzer loadings while permitting organic acid and botanical alternatives. The FDA's Food Safety Modernization Act preventive controls for animal food impose hazard-analysis documentation on domestic and imported feed operations, elevating compliance costs for non-integrated suppliers. China's MEE environmental discharge standards tighten synthetic antioxidant manufacturing permits, constraining capacity additions. Stakeholders must monitor regulatory divergence between jurisdictions that privilege natural-label preservation and those that optimize on cost-per-unit-inhibition metrics.
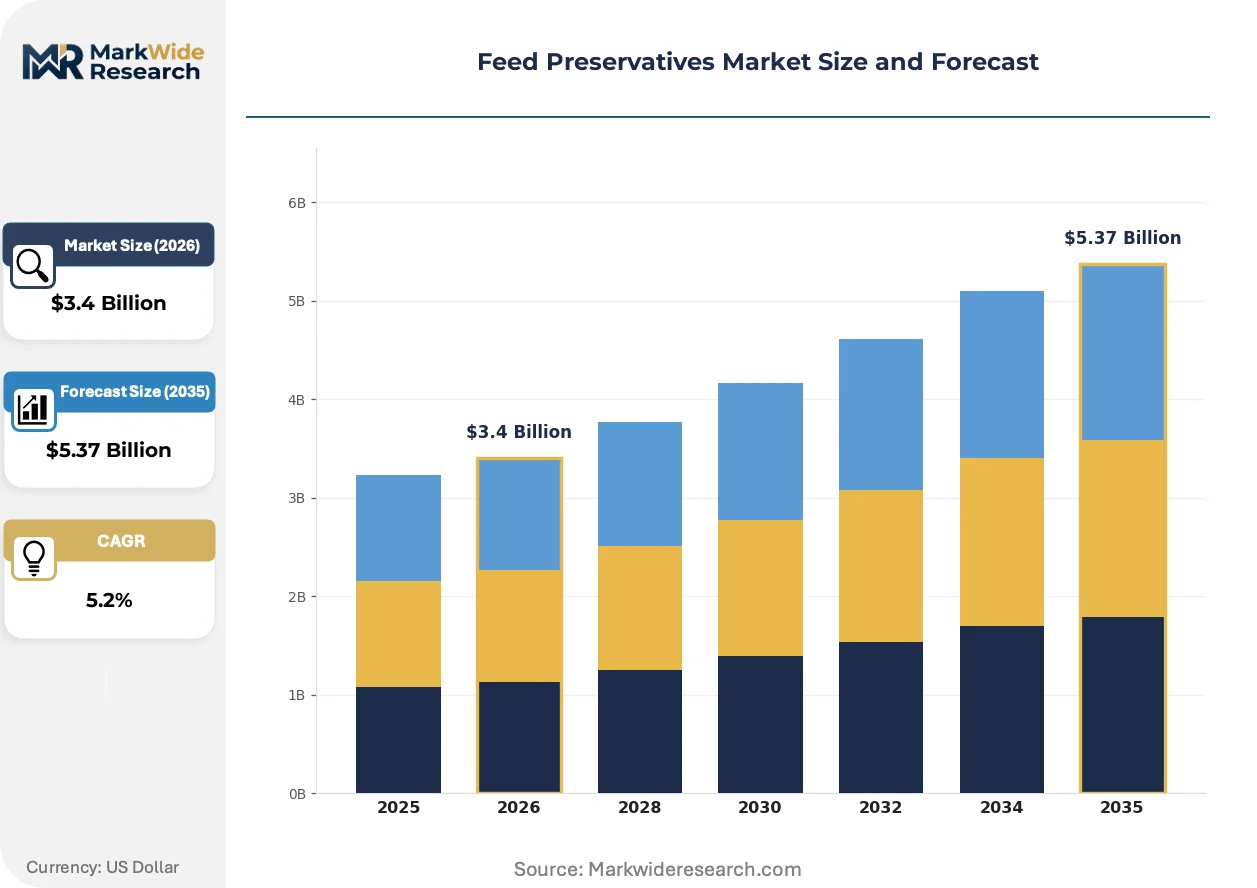
Market Dynamics
Antibiotic-growth-promoter bans across major protein-exporting jurisdictions are redirecting formulation spend toward acidification-based preservation systems, compressing traditional synthetic antioxidant demand while elevating organic acid blend procurement.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:EFSA feed additive re-evaluation protocols mandate reduced chemical preservative loadings while permitting organic acid and botanical alternatives, redirecting R&D investment toward compliant acid-based systems.
- Mycotoxin contamination intensification:Southeast Asian livestock feed manufacturers are expanding additive procurement as climate-induced humidity spikes elevate aflatoxin and fumonisin risks in stored grain.
- Vietnam Mekong Delta pork integration:Large-scale integrators now mandate preservative inclusion in compound feed rations, creating concentrated demand pull for multi-active preservation blends.
Market Restraints
- Propionic acid feedstock volatility:Petrochemical-derived organic acid precursors fluctuate with crude oil indices, compressing blender margins during energy price spikes.
- China MEE environmental discharge standards:Synthetic antioxidant manufacturing permits face tightening constraints, constraining capacity additions for butylated hydroxytoluene intermediates.
- Natural antioxidant yield limitations:Botanical extraction from rosemary and green tea leaves faces agricultural supply constraints, capping scale economies against petrochemical alternatives.
Strategic Opportunities
- Underpenetrated Indonesian poultry sector:Vertical integrators in Java and Sumatra lack systematic preservation protocols, presenting white-space for acid-blend technical service models.
- Precision fermentation-derived antioxidants:Biosynthesis platforms for tocopherol and ascorbic acid analogues are converging with enzymatic preservation systems, enabling clean-label positioning at synthetic cost parity.
- FDA Food Safety Modernization Act preventive controls:Hazard-analysis documentation mandates for imported feed operations elevate compliance service attach rates for preservative suppliers with integrated regulatory consulting.
Industry Challenges
- Formulation chemist scarcity:Multi-active blend optimization requires expertise in acid-pH interaction matrices and moisture-activity modeling, talent concentrated at legacy European premix houses.
- Dual certification timelines:Simultaneous EU feed additive registration and FDA GRAS affirmation processes extend commercialization cycles for novel preservation actives.
- Legacy ERP integration:Toll-manufacturing networks require real-time batch traceability systems compatible with distributor inventory platforms, creating IT expenditure burdens for mid-scale blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Preservatives Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Antioxidants, Synthetic Antioxidants, Organic Acids, Preservative Blends Application: Animal Feed, Silage, Aquaculture, Pet Food End User: Dairy Farms, Poultry Farms, Aquaculture Producers, Livestock Feed Manufacturers Form: Powder, Liquid, Granulated, Pelleted |
| Companies Covered | Nutreco N.V., Alltech, BASF SE, Novus International Inc., Biomin Holding GmbH, Cargill Inc., Adisseo France S.A.S., Perstorp Holding AB, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Preservatives Market Emerging Trajectories
Formulation science is converging microbiome-targeted acidification with oxidative stability engineering, creating preservation systems that address simultaneous degradation pathways rather than single-threat inhibition.
Encapsulated organic acid technologies are hybridizing slow-release matrix designs with targeted gut-delivery mechanisms. Vietnam's integrated pork operators are adopting these systems at accelerated procurement cycles. This hybridization is compressing demand for standalone mold inhibitors by consolidating microbial and oxidative protection into single-addition products.
REACH authorization requirements for synthetic antioxidants are tightening substance volume thresholds and elevating substitution pressure. Industrial users face reformulation timelines to maintain EU market access. Dairy farm channels are responding fastest, pivoting procurement toward tocopherol-rich natural extracts to preempt milk fat residue concerns.
Integrated premix-to-farm distribution networks are displacing traditional additive merchant channels. Large livestock operations in the Netherlands and Denmark now contract directly for customized preservation systems bundled with nutritional consulting. This channel consolidation is most visible in European pork corridors, where scale integrators negotiate multi-year supply agreements with technical performance guarantees.
Feed Preservatives Market Segmentation
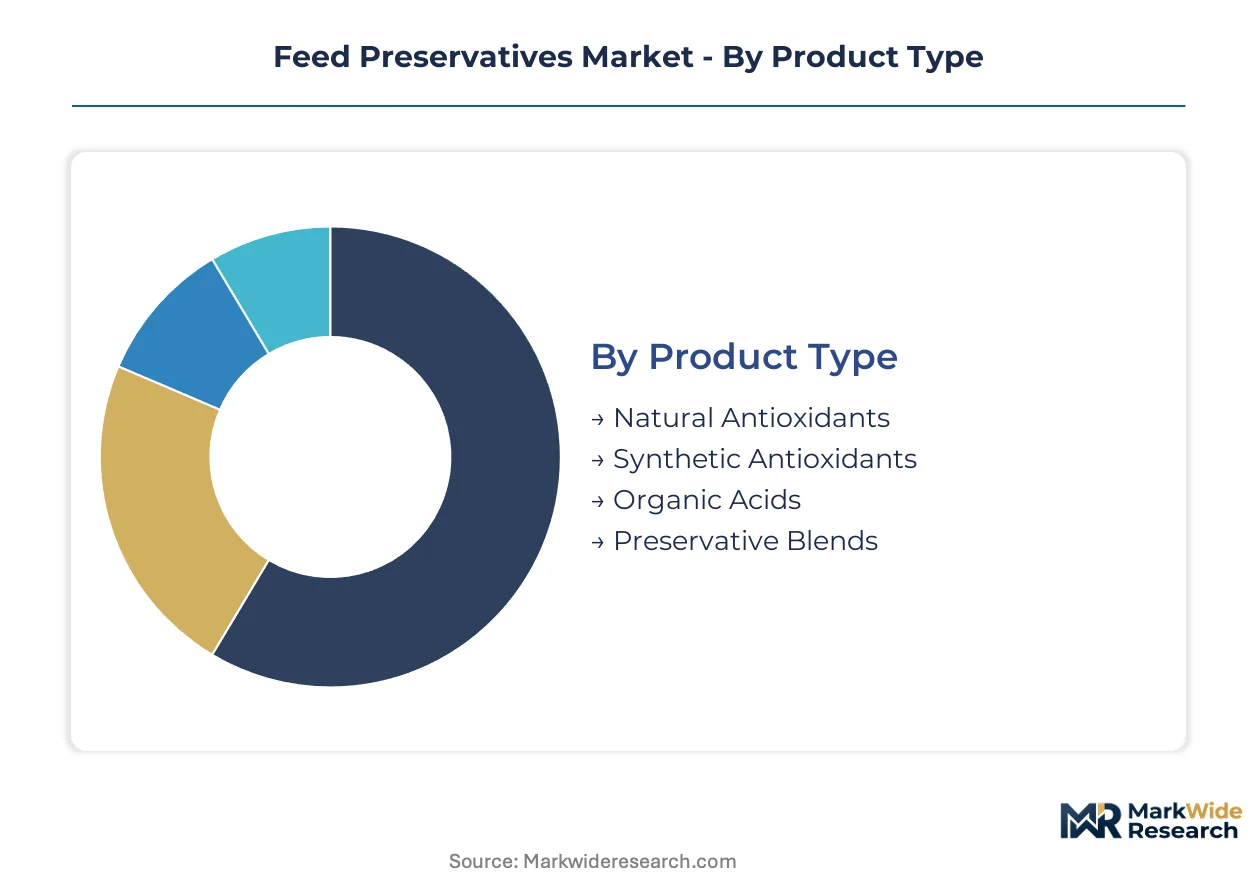
Preservative selection in animal nutrition hinges on substrate compatibility, storage logistics, and regulatory compliance thresholds. Formulators balance oxidative stability against microbial load reduction while managing moisture-activity interactions across diverse feed matrices. Segmentation reveals how technical service intensity varies dramatically by product chemistry and end-use channel.
Product Type:
After-sales technical support requirements peak with multi-active formulations requiring pH calibration and dosage optimization at farm level.
- Natural Antioxidants:Tocopherol and rosemary extract formulations compete on clean-label positioning for dairy processor acceptance. Vietnamese integrators specify these for export-channel milk production where residual carryover into milk fat triggers processor rejection of synthetic alternatives. Supply constraints from agricultural feedstock availability limit scale economies against petrochemical routes.
- Synthetic Antioxidants:Butylated hydroxytoluene and ethoxyquin derivatives offer cost-per-unit-inhibition advantages in bulk grain preservation. China's MEE discharge standards constrain manufacturing permit issuance, tightening supply availability for BHT intermediates. REACH authorization timelines pressure EU industrial users toward substitution planning.
- Organic Acids:Propionic, formic, and citric acid blends dominate antibiotic-free pathogen suppression protocols.
- Preservative Blends:Multi-active formulations combine acidification with oxidative stabilization for single-addition convenience.
By volume, synthetic antioxidants lead. By growth pace, organic acid systems are expanding most quickly.
Application:
Moisture content and storage duration determine preservation chemistry selection across feed categories.
- Animal Feed:Compound rations for swine and poultry require dual-pathway protection against mold proliferation and lipid oxidation. Vietnam's Mekong Delta integrators mandate inclusion rates calibrated to tropical humidity exposure during bulk storage. Formulation services attach at higher rates for multi-species operations with variable ration formulations.
- Silage:Fermentation stabilization demands rapid pH suppression to lock nutritional value in forage crops. European dairy cooperatives specify acid blends with proven Listeria inhibition for clamp-stored maize and grass silage. Anaerobic storage conditions favor liquid acid application systems over dry additives.
- Aquaculture:Extruded feed matrices for shrimp and finfish need water-stable preservation against tropical storage degradation.
- Pet Food:Premium positioning drives natural antioxidant specification for shelf-life extension in retail packaging.
Animal feed commands the largest volume position. Silage applications are climbing the fastest as European dairy intensifies.
End User:
Procurement sophistication varies from merchant compounders to vertically integrated farm operations.
- Dairy Farms:Milk quality premiums drive antioxidant selection toward tocopherol-rich extracts that preempt processor residue testing. Dutch and Danish cooperatives negotiate direct supply agreements with technical performance guarantees. Silage preservation acidification represents the second-largest additive expenditure after mineral supplementation.
- Poultry Farms:Broiler and layer operations prioritize organic acid inclusion for Salmonella suppression in antibiotic-restricted production systems. Indonesian vertical integrators in Java and Sumatra lack systematic preservation protocols, presenting technical service penetration opportunities.
- Aquaculture Producers:Shrimp feed manufacturers in Southeast Asia face mycotoxin pressure from humid storage conditions.
- Livestock Feed Manufacturers:Merchant compounders require flexible blending capabilities across species-specific formulations.
Livestock feed manufacturers move the greatest volume. Dairy farms are gaining share fastest on clean-label specification.
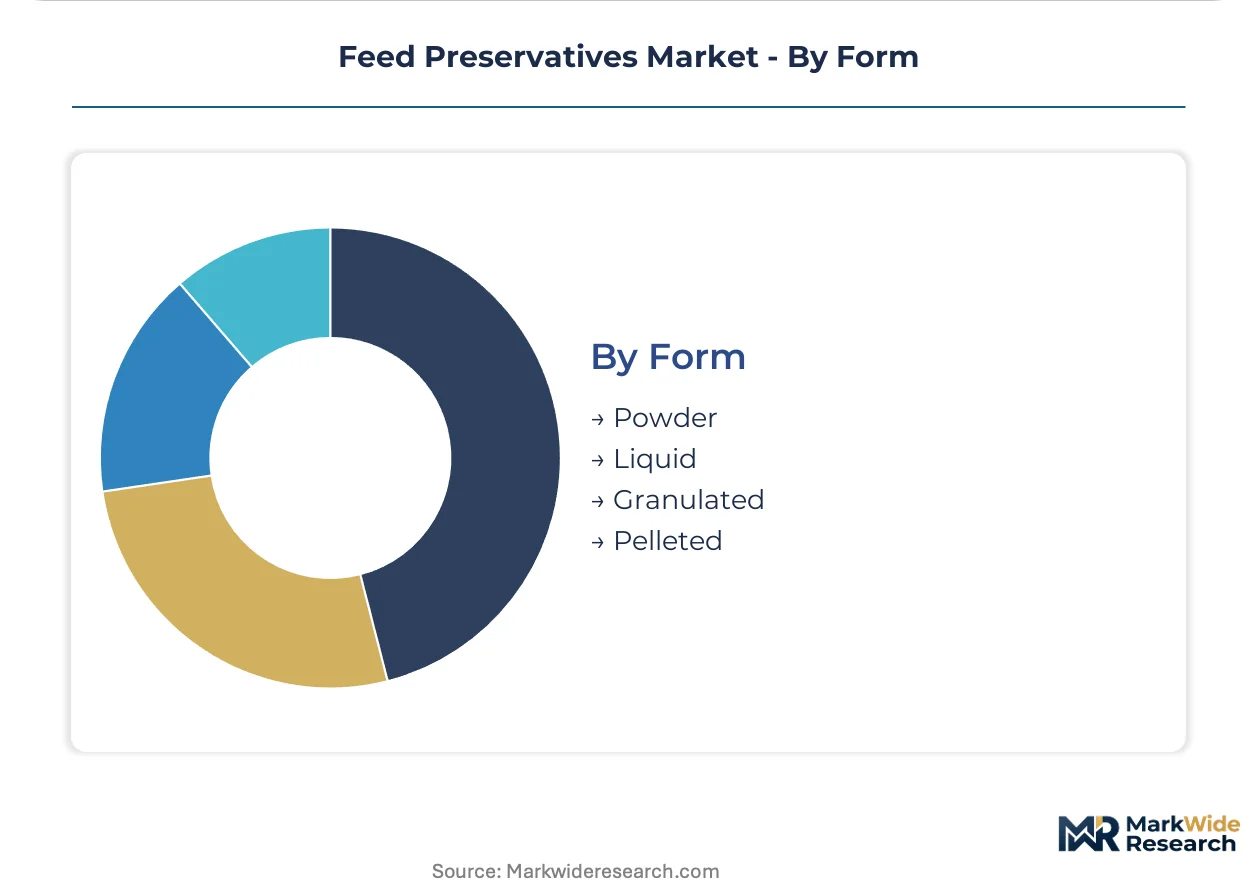
Form:
Physical presentation determines handling equipment compatibility and distribution economics.
- Powder:Fine-milled acid salts and antioxidant crystals suit premix incorporation with uniform dispersion requirements. Pneumatic handling systems at European premix houses favor free-flowing powder grades with specified particle size distributions.
- Liquid:Acid solutions enable spray application onto grain streams and silage surfaces with precise dosage control. Vietnam's integrated pork operators prefer liquid organic acids for automated dosing into bulk feed mixing systems.
- Granulated:Dust-free handling characteristics improve worker safety in high-volume feed mill environments.
- Pelleted:Slow-release matrix designs protect actives through pelleting heat exposure and target gut delivery.
Liquid forms dominate acid applications. Pelleted preservation is expanding most quickly on precision-delivery demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented protein producers in Vietnam and the Netherlands drive feed preservative procurement intensity, while import-dependent feed compounders in Indonesia and Mexico face mycotoxin management pressures that elevate additive specification rates.
United States
Integrated pork and poultry operators in Iowa and North Carolina mandate acid-based preservation systems to comply with FDA Food Safety Modernization Act preventive controls. The agency's hazard-analysis documentation requirements for imported feed operations elevate compliance service attach rates. Large-scale feed mills in the Midwest Corn Belt concentrate procurement of encapsulated organic acid technologies for automated dosing systems.
Vietnam
Mekong Delta integrated pork operations generate concentrated demand for multi-active preservation blends calibrated to tropical humidity exposure. Large-scale integrators now mandate preservative inclusion in compound feed rations at specified inclusion rates. Feed manufacturing clusters around Ho Chi Minh City and Can Tho are adopting liquid organic acid systems for bulk feed mixing automation.
Germany
Dairy cooperatives in Lower Saxony and Bavaria negotiate direct supply agreements for customized preservation systems bundled with nutritional consulting. EFSA feed additive re-evaluation protocols under the EU Green Deal redirect formulation spend toward compliant acid-based alternatives. Industrial feed premix operations in the North Rhine-Westphalia corridor concentrate technical service intensity for multi-species operations.
China
Synthetic antioxidant manufacturing faces tightening constraints from MEE environmental discharge standards that cap capacity additions for butylated hydroxytoluene intermediates. Feed compounders in Shandong and Guangdong provinces pivot procurement toward acidification-based preservation as antibiotic-growth-promoter bans intensify. Shrimp feed manufacturers in the Pearl River Delta confront mycotoxin pressure from humid storage conditions that elevate additive specification rates.
Indonesia
Vertical integrators in Java and Sumatra lack systematic preservation protocols, presenting white-space opportunities for acid-blend technical service models. Poultry farm operations prioritize organic acid inclusion for Salmonella suppression in antibiotic-restricted production systems. Feed manufacturing clusters around Jakarta and Surabaya remain underpenetrated relative to Southeast Asian benchmarks for preservative adoption intensity.
Feed Preservatives Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower formulation scope. The vendor base organizes around three functional layers: integrated premix-to-farm distributors, captive intermediate producers, and toll-manufacturing blenders. Strategic differentiation concentrates in multi-active formulation capabilities and regulatory consulting attach rates. Competitive moves center on backward integration into acid intermediate production and geographic expansion through technical service partnerships.
Among European-anchored platform operators, Nutreco N.V. and BASF SE occupy positions spanning premix distribution and captive antioxidant intermediate supply respectively. Kemin Industries exemplifies the botanical-extraction archetype competing on clean-label positioning. These three entities represent distinct strategic postures: system integration, upstream chemical manufacturing, and natural-source specialization.
| Leading Market Players |
|---|
| Nutreco N.V. |
| Alltech |
| BASF SE |
| Novus International Inc. |
| Biomin Holding GmbH |
| Cargill Inc. |
| Adisseo France S.A.S. |
| Perstorp Holding AB |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Shandong province's synthetic antioxidant manufacturing clusters face tightening MEE environmental discharge permits, constraining butylated hydroxytoluene intermediate supply and elevating pricing leverage for surviving producers serving downstream feed compounders. This capacity compression cascades through acid-blend markets where petrochemical feedstock volatility intersects with antibiotic-replacement demand pull.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tier adjustments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EFSA feed additive protocols and after-sales technical service bundling. Pricing pressure stems from propionic acid feedstock volatility tied to crude oil indices, compressing blender margins during energy price spikes. Merchant compounders in Southeast Asia exhibit highest price sensitivity, while Dutch dairy cooperatives prioritize technical performance guarantees over unit cost.
Supply Chain Analysis
Petrochemical-derived organic acid precursors draw from refineries in China, South Korea, and Singapore, with botanical antioxidant extraction resting on rosemary and green tea agricultural supply from Spain, Morocco, and China. Raw material dependencies include propionic acid intermediates, tocopherol concentrates, and encapsulated matrix polymers. Single-source vulnerability concentrates in European premix houses where formulation chemist scarcity limits multi-active blend optimization capacity. Distribution runs through integrated premix-to-farm networks displacing traditional additive merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's antibiotic-reduction mandates are accelerating a formulation disruption that redirects R&D investment toward acidification-based preservation systems at synthetic cost parity.
For Market Incumbents: Insulate margin pools through backward integration into propionic acid intermediate production and captive antioxidant manufacturing. Capacity additions in Vietnam's Mekong Delta corridor preempt emerging competitor positioning. EFSA feed additive re-evaluation timelines threaten non-compliant product portfolios. For New Entrants and Emerging Players: Indonesian poultry vertical integrators in Java and Sumatra represent the most penetrable entry point given systematic underpenetration of preservation protocols. Precision fermentation-derived tocopherol analogues enable clean-label positioning without agricultural feedstock constraints. Technical service partnerships with local toll-manufacturing blenders accelerate regulatory compliance attach rates. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence between natural-label privileging and cost-optimization markets creates persistent margin asymmetries. Acquisition targets should concentrate on multi-active formulation capabilities with EU feed additive registration dossiers. Monitor FDA Food Safety Modernization Act enforcement intensity as signal for compliance-service attach rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Intermediates | Captive propionic acid supply insulates blender margins from petrochemical volatility. |
| Precision Fermentation Scale-Up | Biosynthesis platforms for tocopherol analogues bypass agricultural yield limitations. |
| EU Feed Additive Registration Investment | EFSA-compliant dossiers unlock premium positioning in antibiotic-restricted jurisdictions. |
| Integrated Premix-to-Farm Distribution | Direct technical service contracts displace merchant channels in European pork corridors. |
| Encapsulated Delivery Technology Development | Slow-release matrix designs command premium in Vietnam's automated dosing systems. |
Methodological Framework
A standing panel of feed formulation chemists, livestock procurement directors, and regulatory affairs specialists provided ongoing calibration across the study. Primary interviews with technical service managers at premix houses, acid-blend production supervisors, and dairy cooperative supply chain officers combined with secondary validation from EFSA feed additive re-evaluation protocols, FDA Food Safety Modernization Act guidance documents, and China MEE environmental discharge standards. Bottom-up volume modeling across organic acid, antioxidant, and preservative blend categories triangulated against top-down protein production forecasts.
Scenario-bracketing around regulatory enforcement intensity and feedstock price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application substrate, end-user procurement sophistication, and physical form factor. CAGRs derived from logistic curve fitting to historical additive inclusion rate trends and forward-projected antibiotic-replacement trajectories. Industry-specific inputs encompass mycotoxin contamination indices for Southeast Asian grain belts and REACH authorization timelines for synthetic antioxidants.
Practitioners should monitor EFSA re-evaluation outcomes and China MEE permit issuance rates for early signals of supply constraint or regulatory redirection. Cross-checking against FAO protein production forecasts and regional feed manufacturing capacity utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
Europe Feed Antibiotics Market