
 Agricultural Grade Zinc Chemicals Market | 2026-2036
Agricultural Grade Zinc Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Grade Zinc Chemicals Market Outlook
Specialty crop growers is collapsing as the dominant buyer archetype in agricultural grade zinc chemicals, displacing commodity grain operations that historically anchored bulk fertilizer-grade demand. Zochem Inc leverages its North American manufacturing scale to supply high-purity zinc oxide for precision foliar applications. Syngenta Crop Protection AG anchors its position through integrated crop nutrition portfolios that bundle zinc chelates with proprietary delivery systems. UPL competes aggressively in emerging markets with technical-grade zinc sulfate formulations tailored to smallholder affordability thresholds.
Agricultural grade zinc chemicals encompass zinc-derived compounds—principally zinc sulfate heptahydrate, zinc oxide with 60-78% metallic zinc content, zinc carbonate, and zinc chelates such as EDTA-Zn—manufactured to crop safety and bioavailability specifications for plant and animal nutritional intervention. These compounds correct zinc deficiency in soils and feeds, a condition that reduces chlorophyll synthesis, stunts root development, and depresses livestock immune response in deficient rations. Zinc sulfate dominates volume flows across crop nutrition and fertilizer applications, though zinc chelate commands premium positioning in high-value horticulture where foliar uptake efficiency determines yield outcomes. Fertilizer grade products occupy the broadest addressable base, while feed grade specifications are tightening under residue monitoring protocols that favor certified suppliers with batch-traceable production.
The EPA governs zinc-containing pesticide formulations and tolerances under FIFRA, while the USDA's Natural Resources Conservation Service influences micronutrient adoption through cost-share conservation programs. India's FSSAI and BIS set complementary standards for feed-grade and fertilizer-grade zinc purity, creating dual compliance obligations for exporters targeting both animal nutrition and crop input channels. Stakeholders must monitor evolving soil testing mandates and micronutrient subsidy eligibility criteria, as these policy levers will determine which product grades and application modes capture public procurement flows.
Market Dynamics
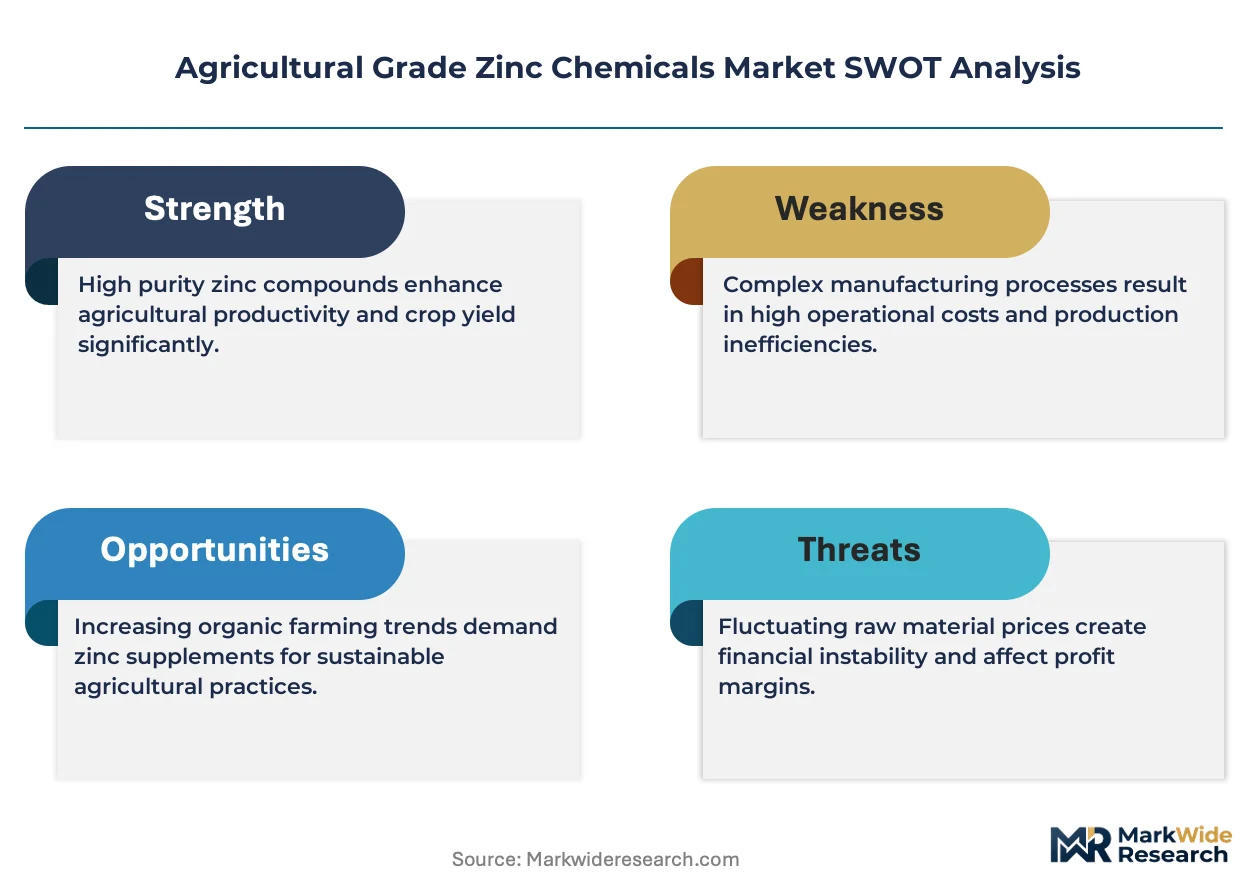
REACH and EU Fertilizing Products Regulation compliance requirements are elevating product purity standards and reshaping supplier certification burdens across agricultural grade zinc chemicals. Specialty crop producers are expanding micronutrient adoption as soil zinc deficiency intensifies across intensive farming belts, concentrating demand in high-value horticulture applications.
Growth Catalysts
- Soil Health Programs:India's government-backed soil health initiatives are accelerating zinc sulfate and chelate consumption among smallholder farmers. BIS certification requirements ensure product quality alignment with subsidy eligibility.
- REACH Compliance:Elevated purity standards under EU chemical regulations are driving technical-grade product upgrades across European fertilizer channels.
- Precision Foliar Technology:High-value horticulture operations are adopting EDTA-Zn chelates for enhanced nutrient uptake efficiency in intensive vegetable production systems.
Market Restraints
- Feedstock Volatility:Zinc metal price swings directly compress margin structures for sulfate and oxide manufacturers dependent on smelter supply.
- Supply Concentration:Technical-grade zinc sulfate production clusters in China create geographic vulnerability for importers facing freight and tariff exposure.
- Substitution Pressure:Organic zinc sources and microbial inoculants are gaining traction in premium organic farming segments resistant to synthetic inputs.
Strategic Opportunities
- Untapped Smallholder Access:India's eastern states present expansion potential for affordable zinc sulfate formulations through cooperative distribution networks.
- Integrated Nutrition Bundles:Zinc chelates paired with precision application equipment offer margin expansion in California and Florida specialty crop belts.
- EU Green Deal Alignment:Circular economy incentives for recovered zinc from industrial waste streams create certified sustainable product positioning.
Industry Challenges
- Dual Certification Burden:India's FSSAI feed-grade and BIS fertilizer-grade standards impose parallel compliance timelines on exporters targeting both channels.
- Soil Testing Infrastructure:Inadequate agronomic laboratory capacity in emerging markets delays deficiency diagnosis and zinc prescription adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Grade Zinc Chemicals Market |
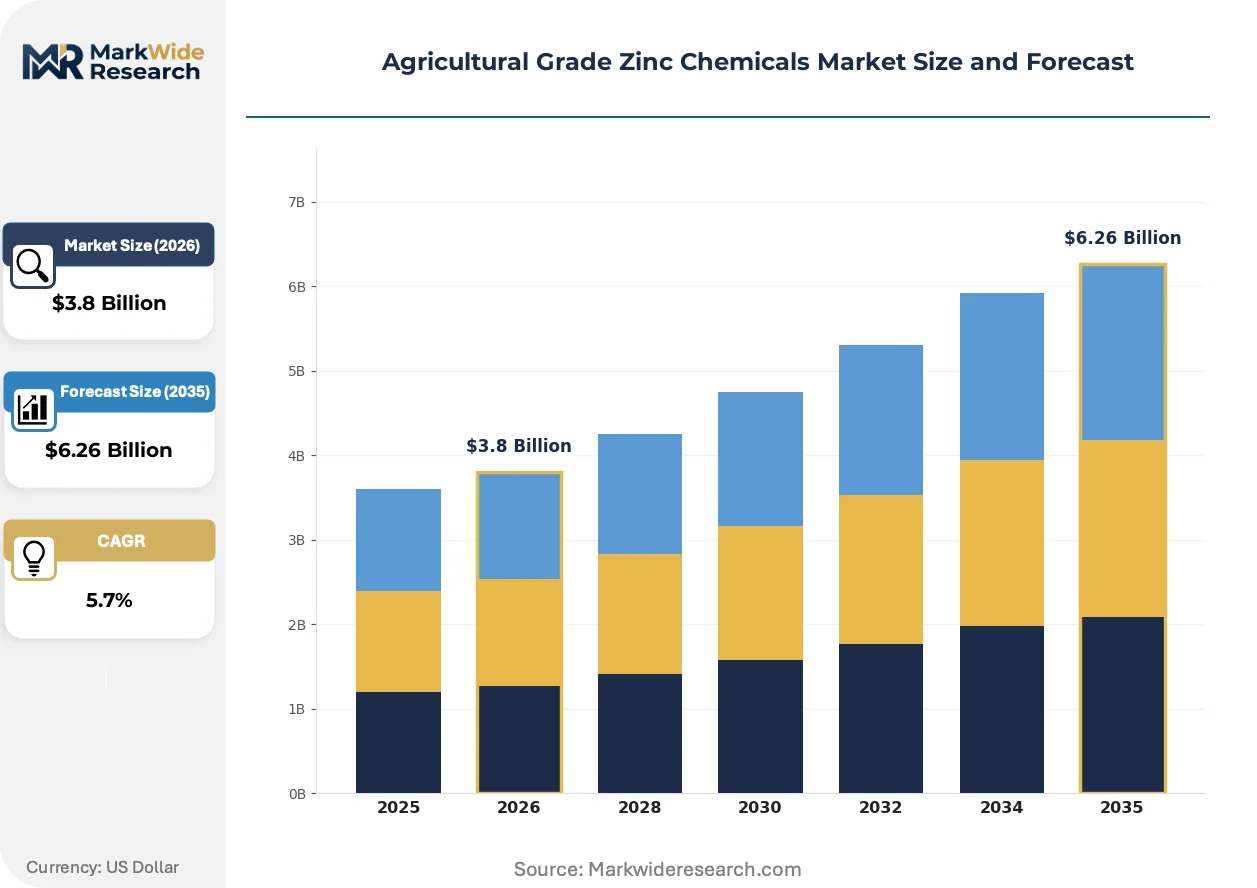
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc Sulfate, Zinc Oxide, Zinc Carbonate, Zinc Chelate Application: Crop Nutrition, Animal Feed, Soil Amendment, Fertilizers Grade: High Purity, Technical Grade, Feed Grade, Fertilizer Grade Packaging Type: Bags, Bulk Containers, Drums, Pallets |
| Companies Covered | Zochem Inc, Syngenta Crop Protection AG, UPL, Bionova, Rubamin, Yara International ASA, EverZinc, Aries Agro Limited, IFFCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Grade Zinc Chemicals Market Strategic Shifts
Nano-formulation technology and precision delivery systems are fragmenting traditional bulk fertilizer paradigms. Regulatory frameworks are tightening residue monitoring protocols while buyer sophistication accelerates specification differentiation.
Controlled-release nano-zinc oxide formulations are fragmenting conventional fertilizer application schedules. Specialty grape and citrus producers in Spain and Italy are adopting these materials at accelerated rates to reduce leaching losses. The technology is fragmenting seasonal demand patterns previously concentrated around planting windows.
EU Fertilizing Products Regulation harmonization is mandating CE-marked nutrient products across member states. Manufacturers must now demonstrate carbon footprint traceability and contaminant thresholds beyond legacy national standards. Zinc chelate suppliers serving Dutch greenhouse operations are restructuring supply chains to meet batch-traceable documentation requirements.
Direct-to-farm digital platforms are compressing traditional distributor margins in agricultural zinc procurement. Brazilian soybean growers and Australian broadacre wheat farmers are bypassing cooperative buying groups to source certified products through agronomic advisory apps. This channel shift is most pronounced in regions with mature precision agriculture infrastructure and reliable mobile connectivity.
Agricultural Grade Zinc Chemicals Market Segmentation
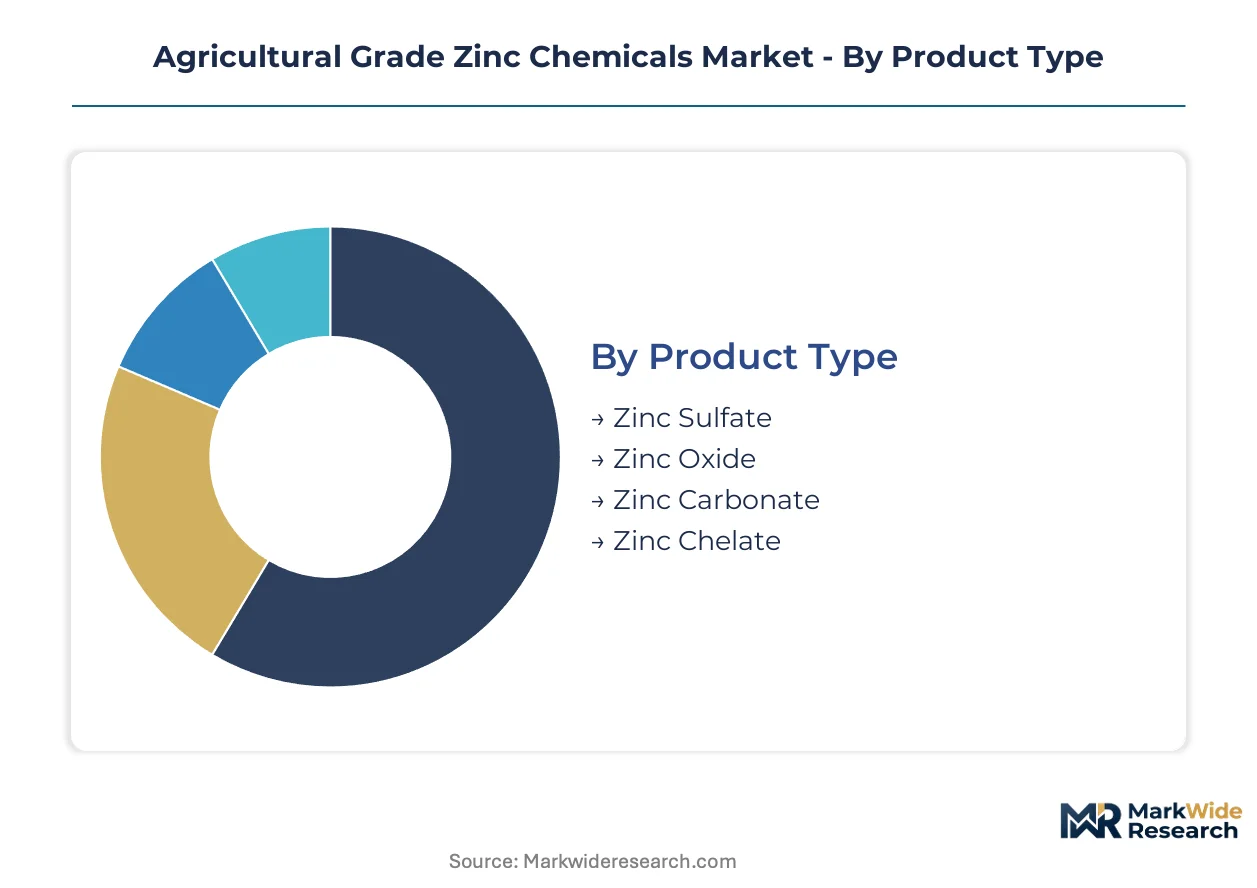
Segmentation in agricultural grade zinc chemicals reveals divergent margin structures across purity tiers and application channels. Product form and certification grade determine pricing power more than volume scale in this specification-driven market.
Product Type:
Margin pools concentrate in chelated formulations where bioavailability premiums offset higher production complexity.
- Zinc Sulfate:Manufactured as heptahydrate or monohydrate crystals with 21-22% metallic zinc content. Demand concentrates in India's government-subsidized fertilizer distribution networks, where smallholder affordability thresholds favor bulk commodity pricing.
- Zinc Chelate:EDTA-Zn and other organic complexes deliver 12-14% metallic zinc with superior foliar uptake efficiency. High-value horticulture operations in Spain and Italy absorb premium pricing for reduced leaching losses in intensive vegetable production systems.
- Zinc Oxide:Granular or powder forms with 60-78% metallic zinc serve precision foliar and feed fortification applications.
- Zinc Carbonate:Basic carbonate compounds function in slow-release fertilizer matrices and pH-buffered soil amendments.
Zinc sulfate holds installed capacity. Zinc chelate is rotating up the share rankings.
Application:
Volume distribution tilts toward soil-based interventions, though feed-grade specifications command tighter certification premiums.
- Crop Nutrition:Foliar sprays and fertigation systems deliver corrective zinc doses during critical plant growth stages. Specialty grape and citrus producers in Mediterranean climates prioritize uptake efficiency over input cost.
- Fertilizers:Bulk blending operations incorporate zinc sulfate into NPK formulations for broadacre grain production. India's soil health programs accelerate consumption through subsidized distribution channels.
- Animal Feed:Zinc oxide and sulfate fortify poultry and swine rations to support immune function and growth rates.
- Soil Amendment:Direct soil application corrects documented deficiencies identified through agronomic testing protocols.
Fertilizers anchor volume throughput. Crop nutrition is climbing the fastest as precision agriculture expands.
Grade:
Certification burden intensifies at higher purity tiers, fragmenting supplier participation across compliance thresholds.
- High Purity:Refined to pharmaceutical-adjacent specifications for sensitive horticultural and research applications. REACH compliance in European markets mandates contaminant thresholds that exclude secondary smelter feedstock.
- Feed Grade:Batch-traceable production under FSSAI and equivalent national standards supports residue monitoring in animal protein supply chains. Indian exporters face dual certification timelines for feed and fertilizer channels.
- Technical Grade:Industrial zinc derivatives meet minimum crop safety thresholds for bulk fertilizer incorporation.
- Fertilizer Grade:Standardized purity levels align with national subsidy eligibility criteria and soil testing recommendation systems.
Technical grade holds legacy capacity. High purity is expanding most quickly under regulatory pressure.
Packaging Type:
Logistics economics favor bulk formats for integrated fertilizer manufacturers, while distributor networks require unitized flexibility.
- Bulk Containers:Flexible intermediate bulk containers and tanker deliveries serve compound fertilizer plants with continuous processing lines. Freight efficiency improves for high-volume zinc sulfate flows between Chinese production clusters and Indian port terminals.
- Bags:25-50kg woven polypropylene units enable cooperative distribution to smallholder networks in eastern Indian states. Handling compatibility with existing fertilizer retail infrastructure preserves downstream margin.
- Drums:Steel and fiber containers protect hygroscopic chelate formulations from moisture degradation.
- Pallets:Unitized loads facilitate mechanized handling at precision agriculture depots and large-scale horticulture operations.
Bulk containers dominate import volume. Bags are gaining share fastest through cooperative channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical-grade zinc sulfate production clusters heavily in China, creating geographic vulnerability for importers facing freight and tariff exposure. Specialty chelate consumption concentrates in Mediterranean horticulture belts and subsidized Indian smallholder networks.
India
Government-backed soil health programs and rising horticulture output accelerate zinc sulfate and chelate consumption. BIS certification requirements ensure product quality alignment with subsidy eligibility criteria. Eastern states present expansion potential for affordable formulations through cooperative distribution networks.
China
Industrial zinc derivative manufacturing dominates global technical-grade sulfate capacity. MEE environmental compliance pressures reshape smelter feedstock sourcing. Shandong and Jiangsu provinces anchor export-oriented production clusters serving Indian and Southeast Asian fertilizer channels.
United States
Precision foliar applications in California and Florida specialty crop belts absorb premium zinc oxide and chelate volumes. EPA FIFRA oversight governs zinc-containing pesticide formulations and residue tolerances. Midwest bulk blending operations incorporate fertilizer-grade sulfate into broadacre grain nutrient programs.
Spain
Specialty grape and citrus producers adopt controlled-release nano-zinc oxide formulations to reduce leaching losses. EU Fertilizing Products Regulation harmonization mandates CE-marked nutrient products with carbon footprint traceability. Valencia and Murcia agricultural clusters drive Mediterranean zinc chelate uptake.
Brazil
Soybean growers bypass cooperative buying groups through agronomic advisory apps for certified product procurement. Direct-to-farm digital platforms compress traditional distributor margins. Mato Grosso and Rio Grande do Sul anchor precision agriculture infrastructure enabling channel shift acceleration.
Agricultural Grade Zinc Chemicals Market Competitive Environment
Concentration sits with diversified agrochemical conglomerates and specialized micronutrient manufacturers. The supplier base fragments across purity tiers and certification thresholds rather than consolidating around volume scale. Three archetypes dominate: North American high-purity oxide specialists, European chelate technology leaders, and emerging-market sulfate commodity suppliers. Competitive moves center on dual certification capacity builds and precision application equipment bundling.
Within the diversified agrochemical tier, Syngenta Crop Protection AG and Yara International ASA exemplify integrated crop nutrition portfolio strategies. Zochem Inc represents North American manufacturing scale positioned for high-purity oxide supply. UPL anchors emerging-market affordability positioning through technical-grade sulfate formulations. These three occupy distinct competitive vectors—technology integration, regional manufacturing scale, and price-accessible distribution—rather than competing directly for identical customer segments.
| Leading Market Players |
|---|
| Zochem Inc |
| Syngenta Crop Protection AG |
| UPL |
| Bionova |
| Rubamin |
| Yara International ASA |
| EverZinc |
| Aries Agro Limited |
| IFFCO |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu province capacity utilization rates above 85% anchor global technical-grade sulfate supply, compressing margin structures for smaller oxide and chelate manufacturers unable to match freight efficiency on Indian bulk imports. This scale concentration enables Chinese exporters to undercut regional producers on fertilizer-grade tenders while premium chelate suppliers in Europe and North America defend pricing power through REACH-compliant purity tiers and batch-traceable documentation.
Pricing Analysis
Volume-discount tiering structures separate certified high-purity zinc oxide for California precision foliar applications from commodity zinc sulfate flowing through India's subsidized distribution networks. Price differentiation rests on BIS certification grade and metallic zinc content thresholds, with feed-grade specifications commanding 15-25% premiums over fertilizer-grade equivalents. Cost compression in technical-grade sulfate is intensifying because Indian smallholder procurement aggregates through cooperative buying groups. Commodity grain operations in Brazil and Australia exhibit highest price sensitivity, while Mediterranean greenhouse operators absorb chelate premiums without volume negotiation.
Supply Chain Analysis
Inventory lead times for hygroscopic zinc chelate formulations extend to 8-12 weeks due to moisture-protected drum packaging requirements and specialized freight handling. Geographic supply concentration centers on China for technical-grade sulfate, India for domestic fertilizer-grade consumption, and Belgium/Netherlands for REACH-compliant chelate finishing. Raw material dependencies draw from zinc smelter output, sulfuric acid availability, and EDTA organic complexing agents. Single-source vulnerability concentrates in Shandong production clusters exposed to MEE environmental compliance disruptions. Distribution runs through compound fertilizer blenders for bulk sulfate, agronomic advisory platforms for direct-to-farm chelate procurement, and cooperative networks for eastern Indian smallholder access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural grade zinc chemicals constitute a defensive-moat market where regulatory entrenchment through dual certification requirements creates substantial switching costs for buyers and barriers for new suppliers.
For Market Incumbents: Secure backward integration into zinc smelter feedstock to buffer margin compression from metal price volatility and consolidate certification capacity builds for simultaneous FSSAI and BIS compliance. Channel control through exclusive agronomic advisory platform partnerships defends against direct-to-farm digital disintermediation threatening traditional distributor relationships. Capacity addition in Gujarat and Maharashtra preserves Indian subsidy eligibility proximity while REACH-aligned purity investments protect European chelate positioning against secondary smelter entrants. For New Entrants and Emerging Players: Differentiate on nano-formulation technology for controlled-release applications in Spanish and Italian specialty citrus production, where leaching-loss reduction commands premium absorption absent in commodity grain markets. White-space penetration concentrates in India's eastern states—Odisha, West Bengal, Jharkhand—where cooperative distribution infrastructure remains underdeveloped relative to northwestern fertilizer corridors. Go-to-market execution partners with precision agriculture equipment bundling rather than standalone chemical supply, capturing margin from application-system integration rather than input commodity competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among chelate suppliers serving Dutch greenhouse operations and California specialty crop belts through long-term offtake agreements tied to precision application equipment leases. Five-to-ten year viability favors manufacturers with demonstrated REACH documentation systems and batch-traceable production infrastructure rather than pure-play sulfate commodity positions. Acquisition target archetype: mid-scale European chelate specialists with CE-marking capabilities and established relationships with Mediterranean horticulture cooperatives. Signal to watch: Indian government soil health program subsidy expansion or contraction rates as inflection indicator for fertilizer-grade volume trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smelter Feedstock | Captive zinc supply buffers margin compression from London Metal Exchange volatility. |
| Dual Certification Capacity Build | Simultaneous FSSAI and BIS compliance unlocks both animal feed and fertilizer channels in India. |
| Nano-Formulation R&D Investment | Controlled-release zinc oxide reduces leaching losses for Spanish citrus producers facing EU nitrate directive pressure. |
| Precision Equipment Bundling | Application-system integration captures margin from California almond and grape growers adopting foliar delivery. |
| Direct-to-Farm Platform Partnership | Brazilian soybean grower app-based procurement bypasses cooperative distributor margin extraction. |
Study Parameters
Desk research of customs trade databases, BIS fertilizer subsidy disbursement records, and ECHA REACH registration filings preceded structured interviews with zinc smelter procurement directors, Indian state cooperative fertilizer managers, Mediterranean greenhouse operations managers, and EPA regulatory compliance officers. Primary fieldwork with compound fertilizer blenders in Mato Grosso and precision agriculture advisors in California's Central Valley validated secondary demand estimates. Bottom-up volume triangulation across product-grade consumption patterns was cross-checked against top-down metallic zinc flow analysis from smelter output to agricultural end-use.
Variance decomposition across the projection horizon isolates volume drivers (hectare expansion, deficiency diagnosis rates, subsidy eligibility shifts) from price drivers (zinc metal spot movements, freight rate fluctuations, certification cost inflation). Segmentation modeling incorporated grade tier, application mode, packaging format, and regional regulatory cluster dimensions. CAGRs were derived from slope-stability analysis of historical consumption trajectories adjusted for policy inflection points including India's soil health card program scaling and EU Fertilizing Products Regulation harmonization enforcement. Industry-specific forecast inputs included agronomic laboratory capacity build rates and precision agriculture equipment penetration curves.
Material uncertainties—zinc metal price volatility spikes, Indian monsoon failure patterns affecting fertilizer application timing, MEE environmental compliance disruptions in Shandong—sit outside the modeled envelope and could compress or expand actual market trajectories. Forecasts reflect documented assumptions regarding subsidy program continuity and REACH enforcement intensity without incorporating speculative regulatory reversals. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
China Castor Oil Market