
 South America Feed Binders Market | 2026-2036
South America Feed Binders Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Binders Market Analytics
Brazilian soybean processing capacity is realigning toward higher-margin feed ingredient derivatives. Cargill Incorporated leverages its port-terminal network along the Santos corridor to anchor supply chain efficiency. Archer Daniels Midland Company competes through backward integration into oilseed crushing. BASF SE differentiates via specialty binder chemistries tailored to tropical humidity conditions.
Feed binders are adhesive compounds, typically comprising lignin, starch, or cellulose derivatives, that agglomerate feed ingredients into durable pellets resistant to friability during handling and transport. Their primary function is to reduce feed waste, improve nutrient density per volume, and enable automated feeding systems in commercial livestock operations. Starch-based formulations occupy the largest volume share given abundant regional cassava and corn supply, while lignin binders sustain margin premiums in organic customer segments. Aquaculture applications represent the fastest-growing application category as shrimp and tilapia intensification accelerates across Ecuador and Colombia.
ANVISA governs feed additive safety assessments in Brazil, while Argentina's SENASA enforces parallel veterinary product standards that binder manufacturers must navigate for cross-border market access. Mercosur technical regulations increasingly harmonize maximum residue limits and labeling requirements, reducing compliance fragmentation for regional suppliers. Stakeholders must monitor pending updates to Brazil's Ministry of Agriculture livestock feed decree and Colombia's INVIMA feed ingredient registry to anticipate registration bottlenecks.
Market Dynamics
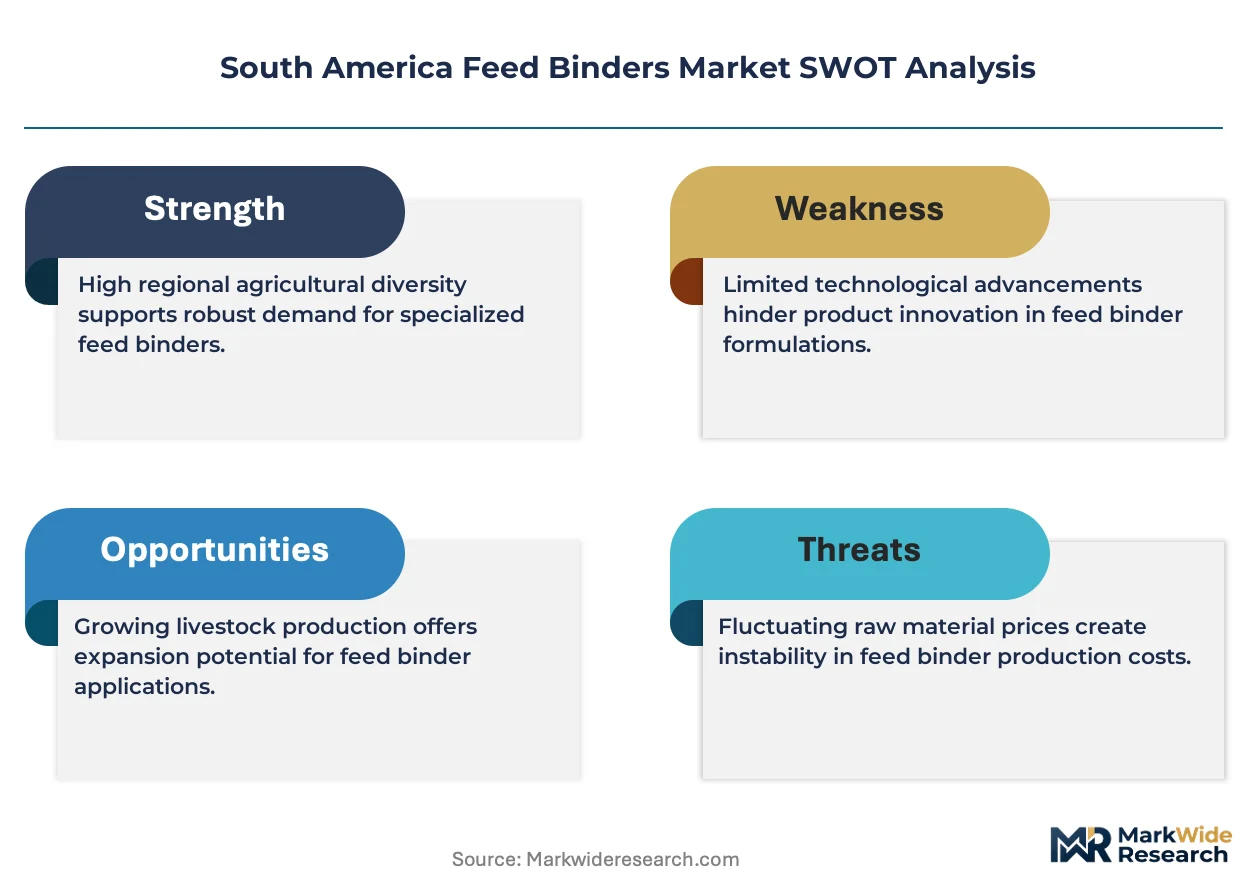
Brazil's commercial livestock intensification is compressing feed formulation cycles, forcing binder suppliers to align product development with ANVISA registration timelines and Mercosur harmonization protocols.
Growth Catalysts
- ANVISA Streamlined Registration:Brazil's consolidated feed additive safety framework reduces approval bottlenecks for lignin and starch-based binders entering the southeastern manufacturing corridor.
- Shrimp Aquaculture Intensification:Ecuadorian and Colombian producers deploy water-stable pellet systems requiring specialized tropical-grade binders resistant to humidity degradation.
- Mercosur Technical Harmonization:Aligned maximum residue limits and labeling standards enable cross-border formulation portability between São Paulo and Buenos Aires feed mills.
Market Restraints
- Cassava Price Volatility:Starch-based binder margins compress when Brazilian cassava harvests fluctuate due to irregular rainfall patterns in Minas Gerais.
- Import Dependency for Specialty Chemistries:Lignin sulfonate supply concentrates in southern Chilean pulp mills, creating single-source vulnerability for organic-certified feed operations.
- Substitution by Cold-Pelleting:Mechanical compaction technologies bypass binder requirements entirely in certain ruminant feed categories.
Strategic Opportunities
- Colombian Atlantic Coast Expansion:Underdeveloped feed manufacturing infrastructure in Barranquilla and Cartagena creates first-mover positioning for humidity-optimized binder portfolios.
- INVIMA Fast-Track Incentives:Colombia's streamlined feed ingredient registry rewards pre-submitted safety dossiers with accelerated market entry timelines.
- Precision Aquaculture Integration:Sensor-enabled feeding systems demand pellet durability specifications that conventional binders fail to meet, opening formulation white space.
Industry Challenges
- Tropical Formulation Expertise Scarcity:Binder chemists with humidity-stability specialization remain concentrated in European R&D centers, forcing Brazilian manufacturers to rely on remote technical support.
- Legacy Equipment Retrofit Costs:Converting Santos corridor feed mills from mash to pellet systems requires capital outlays that mid-scale operators defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Binders Market |
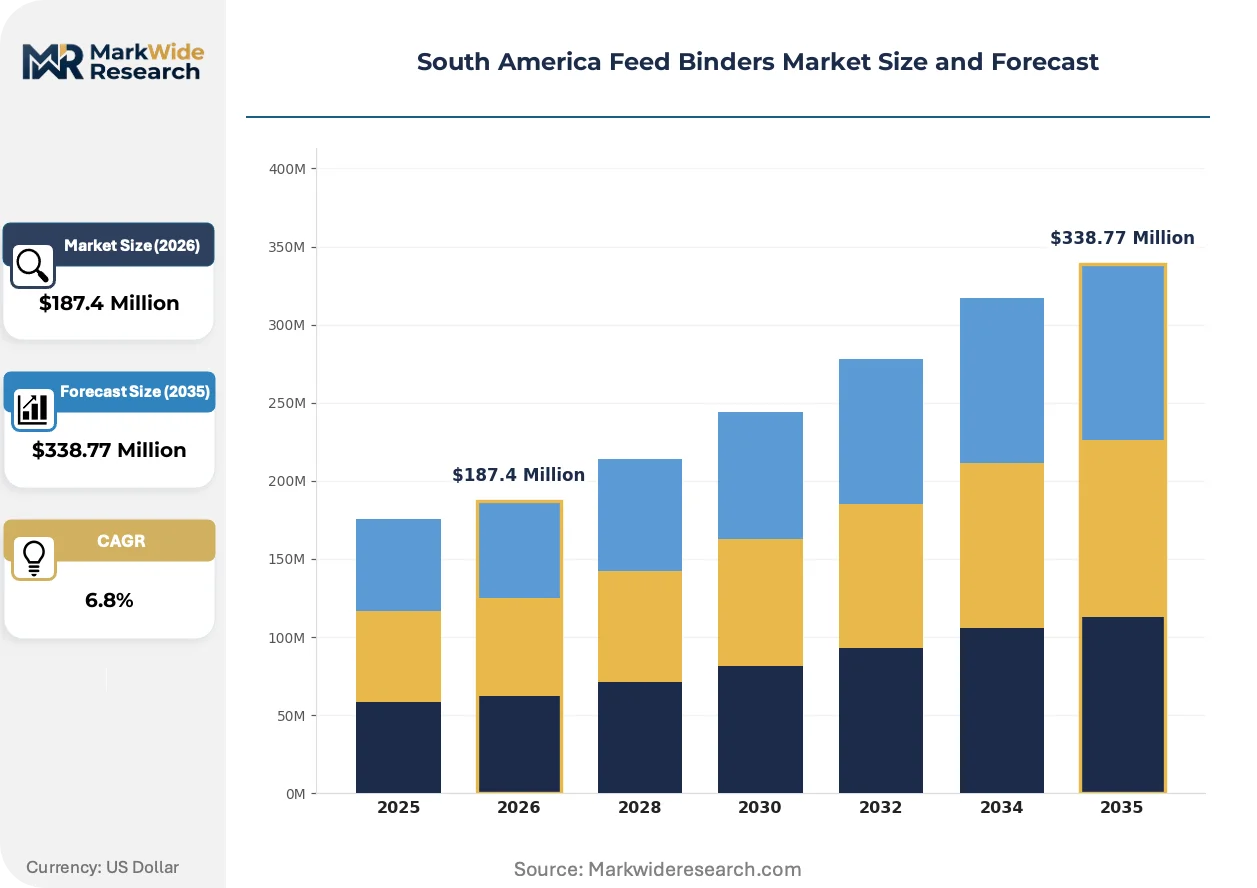
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Lignin, Starch, Gelatin Application: Animal Feed, Pet Food, Aquaculture, Livestock Supply Chain: Raw Materials, Manufacturing, Distribution, Retail Customer Segment: Commercial, Organic, Conventional, Specialty |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, BASF SE, Evonik Industries AG, Alltech Inc., Kemin Industries, Inc., Adisseo Nutrition, FMC Corporation, Bunge Limited, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Binders Market Evolving Landscape
Active reformulation of binder chemistries around tropical durability standards is reshaping competitive positioning in South American feed manufacturing.
Enzymatically modified starches with enhanced water resistance are overtaking conventional cassava-derived formulations in Brazilian poultry operations. Large integrators in São Paulo state specify these advanced binders for automated feeding systems. The technology is overtaking commodity starch suppliers unable to meet pellet durability indices above 95 percent.
Argentina's SENASA veterinary product standards are converging with Brazilian ANVISA protocols under Mercosur technical working groups. This alignment eliminates duplicate safety testing for cross-border binder shipments. Argentine feed manufacturers now access Brazilian-approved lignin formulations without parallel registration, accelerating regional supply chain integration.
Direct-procurement contracts between Ecuadorian shrimp farms and binder manufacturers are displacing traditional distributor intermediaries. Large aquaculture operations in Guayaquil and Manta negotiate volume-based pricing for humidity-stable pellet systems. This channel compression concentrates purchasing power among ten major producers controlling sixty percent of national shrimp output.
South America Feed Binders Market Segmentation
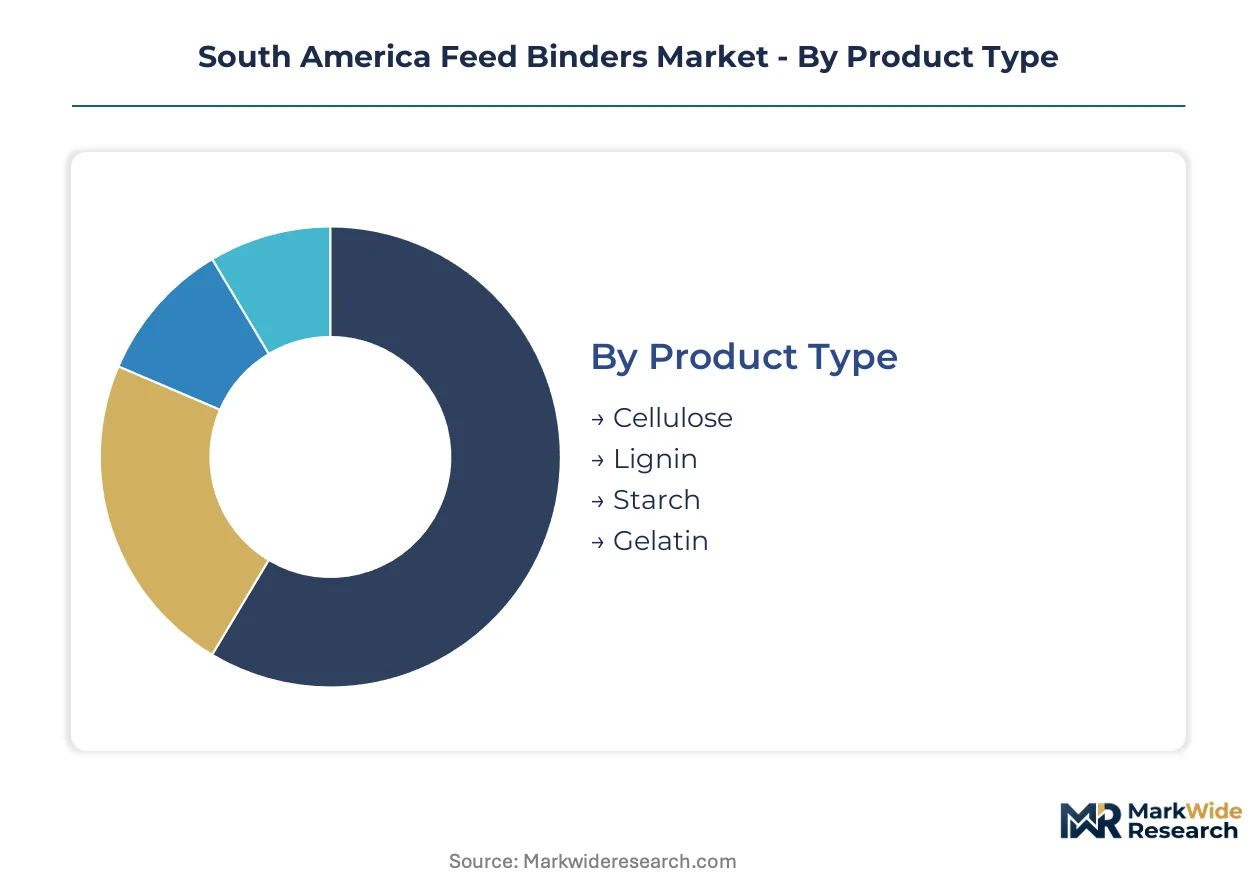
Feed binder procurement patterns diverge sharply across product chemistries and end-use specifications. Capital deployment decisions hinge on whether formulations serve commodity livestock operations or premium-certified segments requiring specialized registration pathways.
Product Type:
Capital intensity peaks with enzymatic modification infrastructure and tropical-stability R&D facilities.
- Starch:Cassava and corn-derived formulations dominate Brazilian poultry and swine operations. São Paulo integrators specify enzymatically modified variants for automated feeding systems requiring pellet durability indices above 95 percent. Minas Gerais processing capacity anchors regional supply.
- Lignin:Sulfonate and kraft lignin chemistries command margin premiums in organic-certified feed segments. Southern Chilean pulp mills supply concentrated feedstock, creating single-source dependency for Brazilian organic operators. Humidity-stability specifications differentiate tropical-grade offerings.
- Cellulose:Microcrystalline and carboxymethyl derivatives serve ruminant fiber supplementation with moderate capital barriers.
- Gelatin:Collagen-based binders occupy niche pet food applications with limited regional manufacturing presence.
Most installed capacity flows through starch derivatives. Expansion is steepest in lignin formulations.
Application:
End-use specifications determine formulation complexity and registration burden under national veterinary product frameworks.
- Animal Feed:Pelletized formulations for poultry, swine, and cattle concentrate demand in Brazil's southeastern manufacturing corridor. ANVISA registration timelines compress product development cycles for large integrators.
- Aquaculture:Water-stable pellet systems for Ecuadorian shrimp and Colombian tilapia operations require tropical-grade humidity resistance. Guayaquil and Manta producers negotiate direct-procurement contracts bypassing traditional distribution channels.
- Livestock:Ruminant applications face substitution pressure from cold-pelleting mechanical compaction technologies in certain feed categories.
- Pet Food:Palatability-focused formulations serve Brazil's expanding companion animal market with distinct sensory specifications.
Volume concentration sits with animal feed. Aquaculture climbs fastest.
Supply Chain:
Backward integration economics favor operators controlling oilseed crushing and port-terminal networks.
- Raw Materials:Cassava cultivation in Minas Gerais and lignin feedstock from Chilean pulp mills constitute primary input sourcing. Irregular rainfall patterns introduce harvest volatility affecting starch binder margins.
- Manufacturing:Pellet mill operations cluster along the Santos corridor, leveraging Cargill's port-terminal infrastructure for supply chain efficiency. Mid-scale operators defer capital outlays for mash-to-pellet equipment retrofits.
- Distribution:Traditional intermediaries face displacement in Ecuadorian aquaculture channels where large producers consolidate purchasing power.
- Retail:Direct-procurement contracts concentrate among ten major shrimp producers controlling sixty percent of Ecuadorian national output.
Manufacturing absorbs the heaviest capital deployment. Distribution restructuring accelerates most quickly.
Customer Segment:
Purchasing power fragmentation separates price-sensitive commodity buyers from specification-driven certified operations.
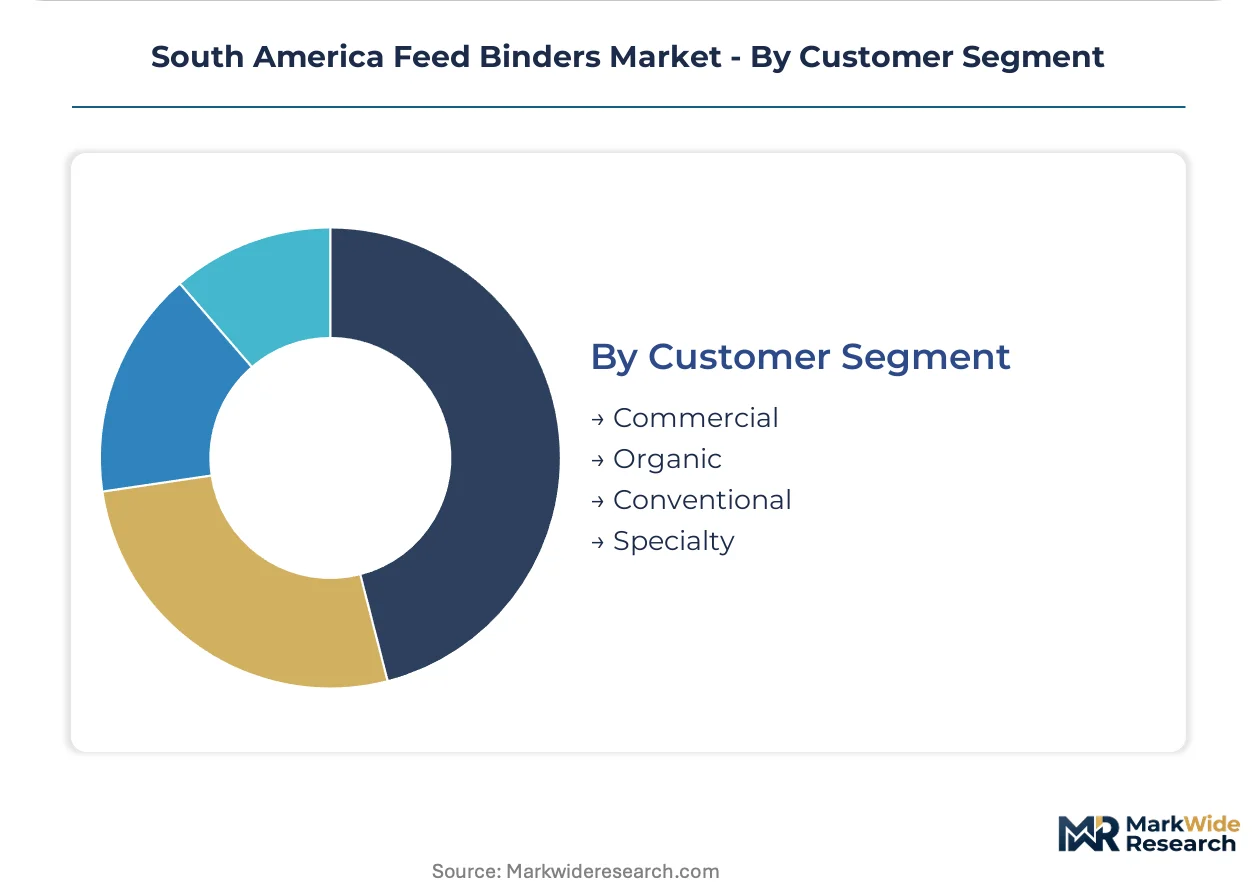
- Commercial:Large Brazilian integrators in São Paulo state drive standardization around automated feeding compatibility and ANVISA-compliant safety dossiers. Volume procurement compresses supplier margins.
- Organic:Certification requirements mandate lignin-based formulations with traceable supply chains. SENASA-ANVISA convergence under Mercosur harmonization reduces duplicate registration burdens for cross-border suppliers.
- Conventional:Mid-scale feed mills prioritize cost optimization over performance specifications, accepting commodity starch derivatives.
- Specialty:Precision aquaculture operators demand sensor-enabled feeding system compatibility, opening formulation white space beyond conventional binder capabilities.
Commercial buyers command dominant procurement volume. Specialty specifications expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography across South America as manufacturers relocate to jurisdictions with streamlined feed additive registration pathways. ANVISA's consolidated safety framework in Brazil attracts capacity that might otherwise locate in markets with fragmented veterinary product oversight.
Brazil
Poultry and swine integrators in São Paulo state drive pelletized feed standardization, specifying enzymatically modified starch binders for automated systems. ANVISA governs additive safety assessments with timelines that compress supplier product development cycles. The southeastern manufacturing corridor spanning São Paulo and Minas Gerais anchors national capacity, with Santos port terminals enabling export logistics.
Argentina
Cattle feedlot intensification in Buenos Aires province sustains demand for lignin-based ruminant formulations. SENASA veterinary product standards are converging with Brazilian protocols under Mercosur technical working groups, eliminating duplicate safety testing for cross-border shipments. Rosario's agro-industrial cluster hosts formulation facilities serving the Pampas grain belt.
Colombia
Tilapia aquaculture expansion across the Magdalena River basin requires water-stable pellet systems resistant to tropical humidity degradation. INVIMA maintains a streamlined feed ingredient registry that rewards pre-submitted safety dossiers with accelerated market entry timelines. Barranquilla and Cartagena on the Atlantic coast present underdeveloped manufacturing infrastructure where first-mover positioning remains available.
Ecuador
Shrimp farming intensification in Guayaquil and Manta drives procurement of specialized tropical-grade binders. Large producers negotiate direct-procurement contracts that displace traditional distribution intermediaries, consolidating purchasing power among ten major operations controlling sixty percent of national output. The coastal lowlands concentrate aquaculture feed demand.
Chile
Southern pulp mills supply concentrated lignin sulfonate feedstock for organic-certified Brazilian operations, creating single-source dependency for regional organic feed manufacturers. Salmon aquaculture in the Los Lagos region generates parallel demand for water-stable pellet binders. Temuco anchors forestry-processing infrastructure that feeds cross-border specialty chemical supply.
South America Feed Binders Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aquaculture-specialized formulations and tropical-stability R&D partnerships. The supplier base organizes around three maturity tiers: multinational agribusiness conglomerates with backward integration into oilseed crushing, regional chemical specialists with humidity-stability expertise, and commodity starch processors serving price-sensitive mid-scale feed mills. Strategic moves concentrate on port-terminal network control for supply chain efficiency and enzymatic modification capacity expansion for premium-tier product differentiation.
Among the integrated agribusiness tier, Cargill Incorporated anchors supply chain positioning through port-terminal infrastructure along the Santos corridor. Archer Daniels Midland Company exemplifies backward integration strategy with captive oilseed crushing capacity feeding binder ingredient supply. BASF SE represents the specialty chemical archetype, differentiating through tropical-grade formulation expertise. These three entities collectively illustrate competitive positioning vectors spanning scale, integration depth, and technical specialization.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Evonik Industries AG |
| Alltech Inc. |
| Kemin Industries, Inc. |
| Adisseo Nutrition |
| FMC Corporation |
| Bunge Limited |
| Others |
Value Network & Pricing Analysis
Ecuadorian shrimp farm consolidation into direct-procurement contracts strips distributor margins from the value chain and forces manufacturers to absorb logistics costs or cede volume to integrated competitors. This buyer-driven channel compression cascades backward into raw material sourcing decisions, where cassava price volatility in Minas Gerais and single-source lignin dependency from Chilean pulp mills amplify cost unpredictability.
Pricing Analysis
Distributor margin compression in Ecuadorian aquaculture channels has collapsed traditional markup layers from fifteen to five percent as ten major shrimp producers negotiate volume-based direct contracts. Pricing stratifies across premium, standard, and economy tiers, with enzymatically modified starch binders commanding premiums for automated feeding compatibility while commodity cassava derivatives face relentless cost pressure from cold-pelleting substitution in ruminant categories. Commercial integrators in São Paulo state exhibit highest price sensitivity, squeezing supplier margins through consolidated procurement, while organic-certified operations accept lignin premiums for traceable supply chains. Cost compression in standard-tier formulations is intensifying because Brazilian mid-scale feed mills defer capital outlays for pellet system retrofits, perpetuating mash-format demand.
Supply Chain Analysis
Skilled formulation chemists with tropical humidity-stability specialization remain concentrated in European R&D centers, forcing Brazilian manufacturers to rely on remote technical support and delaying product adaptation cycles. Supply concentrates in Brazil's southeastern manufacturing corridor, Chilean southern pulp mills, and Ecuadorian coastal aquaculture clusters, with raw material dependencies on Minas Gerais cassava cultivation, sulfonate lignin feedstock, and imported enzymatic modification catalysts. Single-source vulnerability for organic-certified lignin supply creates structural risk for cross-border Brazilian operators. Distribution runs through Cargill's Santos port-terminal network for integrated agribusiness tier, while regional chemical specialists depend on fragmented trucking and coastal shipping lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Feed Binders Market functions as a stable compounder anchored by irreversible livestock intensification trends across Brazilian poultry and swine operations. Regulatory harmonization under Mercosur technical working groups reduces cross-border friction and sustains predictable demand trajectories for compliant suppliers.
For Market Incumbents: Cement control over the Santos corridor port-terminal infrastructure to defend against backward-integrated oilseed competitors encroaching on logistics advantages. Prioritize enzymatic modification capacity expansion in Minas Gerais to meet São Paulo integrator specifications for pellet durability indices above ninety-five percent, neutralizing commodity starch substitution threats from cold-pelleting mechanical compaction technologies.
For New Entrants and Emerging Players: Tropical-grade humidity stability R&D partnerships offer entry into Colombian Atlantic coast feed manufacturing where Barranquilla and Cartagena infrastructure remains underdeveloped. Target INVIMA fast-track incentives for pre-submitted safety dossiers, leveraging accelerated market entry timelines against established Brazilian competitors facing ANVISA registration bottlenecks. Pursue direct-procurement relationships with precision aquaculture operators demanding sensor-enabled feeding system compatibility.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional chemical specialists possessing captive tropical-stability formulation expertise and INVIMA-registered product portfolios. Long-term viability centers on five-to-ten year feed additive registration asset durability under converging SENASA-ANVISA protocols. Monitor pending updates to Brazil's Ministry of Agriculture livestock feed decree as inflection indicator for regulatory-driven consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captive ingredient supply secures margin control against cassava price volatility in Minas Gerais. |
| Enzymatic Modification Capacity Expansion | São Paulo integrator specifications for automated feeding compatibility drive premium-tier product differentiation. |
| Port-Terminal Network Control | Santos corridor logistics dominance anchors supply chain efficiency for southeastern manufacturing scale. |
| INVIMA Fast-Track Registration | Pre-submitted safety dossiers unlock accelerated Colombian market entry ahead of competitor timelines. |
| Tropical Humidity Stability R&D Partnership | Specialized formulation expertise addresses Ecuadorian shrimp farm water-stable pellet requirements. |
Research Methodology
Bottom-up aquaculture and livestock modeling reconciled against top-down oilseed crushing and port-terminal capacity tracking forms the analytical core of this study. Primary interviews with feed mill operations managers, ANVISA regulatory affairs specialists, Ecuadorian shrimp farm procurement directors, and Chilean pulp mill technical sales teams combined with secondary validation from customs trade data, SEC 10-K filings of listed agribusiness conglomerates, ANVISA feed additive registry updates, and INVIMA ingredient safety dossier publications. Triangulation between demand-side procurement pattern analysis and supply-side manufacturing capacity assessment ensures cross-verified output integrity.
Input-output matrices mapping cassava cultivation volumes, lignin sulfonate pulp mill output, and pellet mill installed capacity across the analysis window feed segment-level projections. Modeled dimensions span product chemistry tier, end-use application intensity, customer certification requirement, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year consumption estimates, with cross-checks against Mercosur trade flow data and feed industry association production statistics. Humidity-stability specification adoption curves and automated feeding system penetration rates inform application-specific trajectory assumptions.
The model holds under sustained ANVISA-SENASA regulatory convergence and stable Brazilian commercial livestock intensification; deviation in Colombian infrastructure buildout pace or Ecuadorian shrimp disease outbreaks would shift volume and value projections. Forecasts reflect documented assumptions regarding cassava harvest yield patterns and Chilean pulp mill capacity utilization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Rape Seed Meal Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Animal Feed and Pet Food Market