
 Europe Feed Antioxidants Market | 2026-2036
Europe Feed Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Antioxidants Market Foresight
Synthetic ethoxyquin is recalibrating product economics across European compound feed operations as EFSA safety reviews trigger reformulation toward tocopherol and BHT alternatives. BASF SE leverages its Ludwigshafen antioxidant production complex to sustain supply security for German and Benelux feed mills. DSM-Firmenich AG anchors its positioning through R&D intensity in precision-delivery tocopherol forms, while Cargill Inc. competes via backward integration into oilseed processing that secures raw material flows for natural antioxidant extraction.
Feed antioxidants comprise chemical compounds or natural extracts added to animal feed to inhibit lipid oxidation, preserve vitamin potency, and maintain palatability, with typical inclusion rates ranging from 50 to 250 ppm depending on feed fat content and storage conditions. Their primary commercial purpose centers on extending feed shelf life and protecting nutritional value through the distribution chain from mill to farm. Tocopherols command expanding share as feed manufacturers respond to retailer and processor demands for reduced synthetic additive residues in poultry and swine production. Powder formulations dominate volume flows for large-scale mill integration, while liquid concentrates gain ground in aquaculture and specialized premix operations where uniform dispersion in high-moisture feeds proves critical.
EFSA re-evaluation protocols for feed additives, REACH chemical registration requirements, and EU Green Deal sustainability targets collectively reshape product approval timelines and formulation strategies across the continent. The F-Gas Regulation and national implementation measures in France and Germany further constrain solvent-based extraction processes used in synthetic antioxidant manufacturing. Stakeholders must monitor the trajectory of ECHA substance of very high concern designations and the EU's pending feed sustainability certification schemes to anticipate which antioxidant chemistries will retain market access.
Market Dynamics
REACH re-registration deadlines and EFSA feed additive re-evaluations are compressing formulation timelines across European compound feed operations, forcing manufacturers to pre-validate natural antioxidant alternatives before synthetic approvals expire.
Growth Catalysts
- EU Green Deal livestock sustainability targets:National implementation plans in France and Germany mandate reduced synthetic additive residues in poultry and swine supply chains, accelerating tocopherol adoption.
- Poland's poultry export expansion:Integrated processors in Greater Poland Voivodeship require extended feed shelf life for cross-border distribution, driving antioxidant inclusion rates upward.
- Precision-delivery encapsulation technologies:Micro-encapsulated tocopherol forms improve bioavailability in high-fat aquafeeds, opening formulation flexibility for Mediterranean marine farms.
Market Restraints
- Vegetable oil feedstock volatility:Crude sunflower and soybean oil price swings in Black Sea sourcing regions compress natural antioxidant margins unpredictably.
- Synthetic antioxidant supply concentration:Ethoxyquin production clusters in China's Shandong province create trans-shipment dependencies for European compounders seeking cost benchmarks.
- EFSA re-evaluation timelines:Eighteen-month safety review cycles for novel natural extracts delay product launches and tie up regulatory capital.
Strategic Opportunities
- Romania's underdeveloped feed premix sector:Low antioxidant penetration in Transylvania's expanding pig farming belt creates first-mover positioning for natural formulation suppliers.
- CSRD-aligned sustainability certification:Upcoming EU feed sustainability schemes will reward verifiable natural additive sourcing with preferential retail procurement status.
- Direct-to-farm liquid concentrate distribution:Bypassing traditional mill intermediaries via tanker delivery networks captures margin in Denmark's decentralized dairy operations.
Industry Challenges
- Analytical chemist scarcity:Compound feed mills across Spain's Aragon region struggle to hire specialists capable of running oxidative stability index testing for natural antioxidant validation.
- Legacy ERP integration with batch traceability systems:German Rhineland feed clusters face IT reconfiguration costs when linking antioxidant inclusion records to EU feed hygiene regulation audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Antioxidants Market |
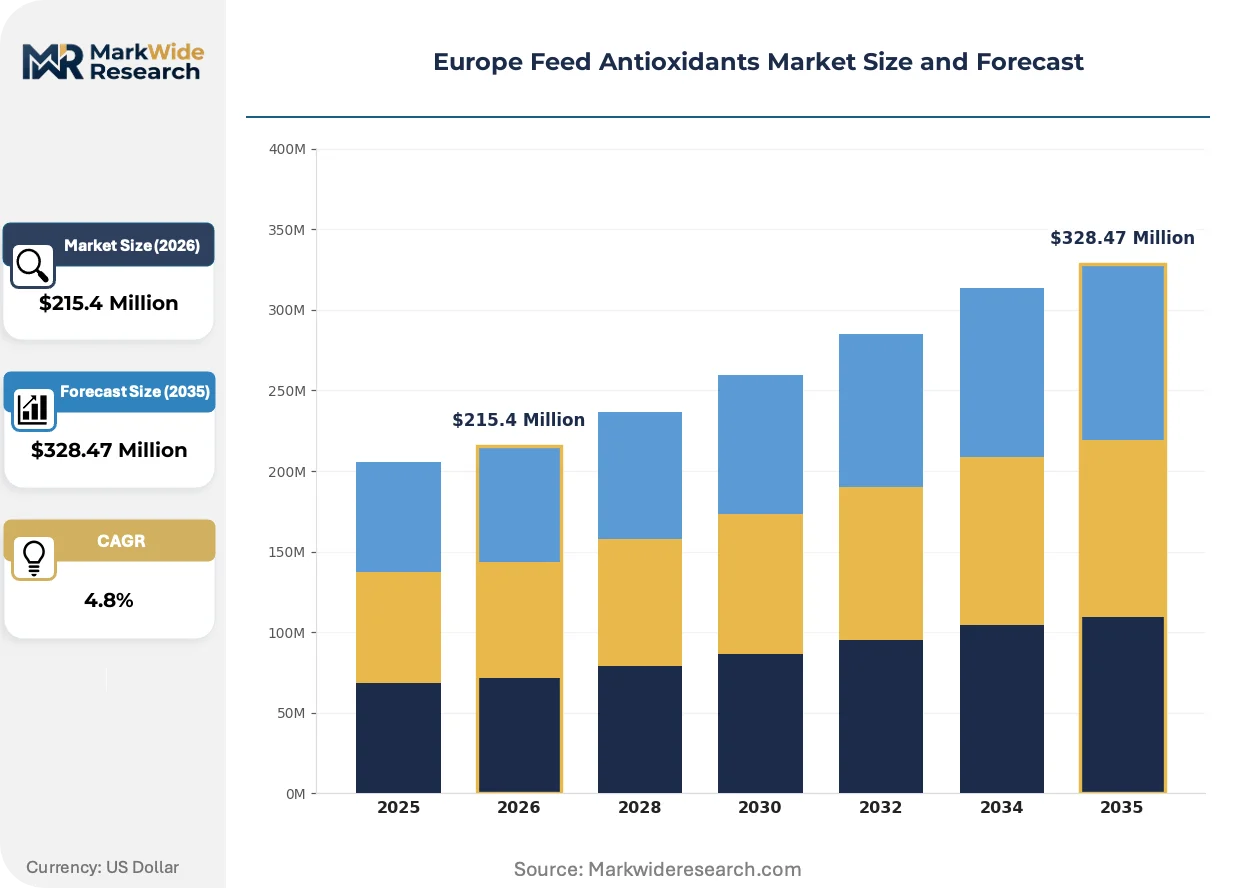
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $328.47 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BHA, BHT, Ethoxyquin, Tocopherols Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granule, Tablet End User: Feed Manufacturers, Livestock Farms, Pet Food Producers, Nutraceutical Companies |
| Companies Covered | Archer Daniels Midland Company, BASF SE, DSM-Firmenich AG, Cargill Inc., Kemin Europa, Adisseo France SAS, AllTech, Novus International, Danisco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Antioxidants Market Shifts & Advancements
Formulation science and regulatory compliance systems are converging to redefine how European feed manufacturers specify, source, and verify antioxidant performance across species-specific applications.
Near-infrared spectroscopy coupled with machine learning algorithms is automating real-time antioxidant potency verification at mill intake points. Large poultry integrators in Brittany deploy these systems to reject tocopherol shipments falling below declared activity levels. Quality control labor costs compress while batch consistency tightens across high-throughput operations.
REACH Article 33 disclosure obligations for substances of very high concern are forcing antioxidant suppliers to document full supply chain chemistry. ECHA's 2024-2025 candidate list expansion threatens certain BHT impurities, pushing compounders toward tocopherol-only formulations ahead of regulatory deadlines. German feed mills are pre-emptively reformulating to avoid downstream liability exposure.
Retailer-driven residue auditing is shortening antioxidant specification cycles in poultry procurement. French supermarket chains now require feed additive disclosure to farm level, bypassing traditional processor intermediaries. Brittany and Pays de la Loire integrators respond by consolidating antioxidant sourcing to single-supplier contracts with full traceability documentation.
Europe Feed Antioxidants Market Segmentation
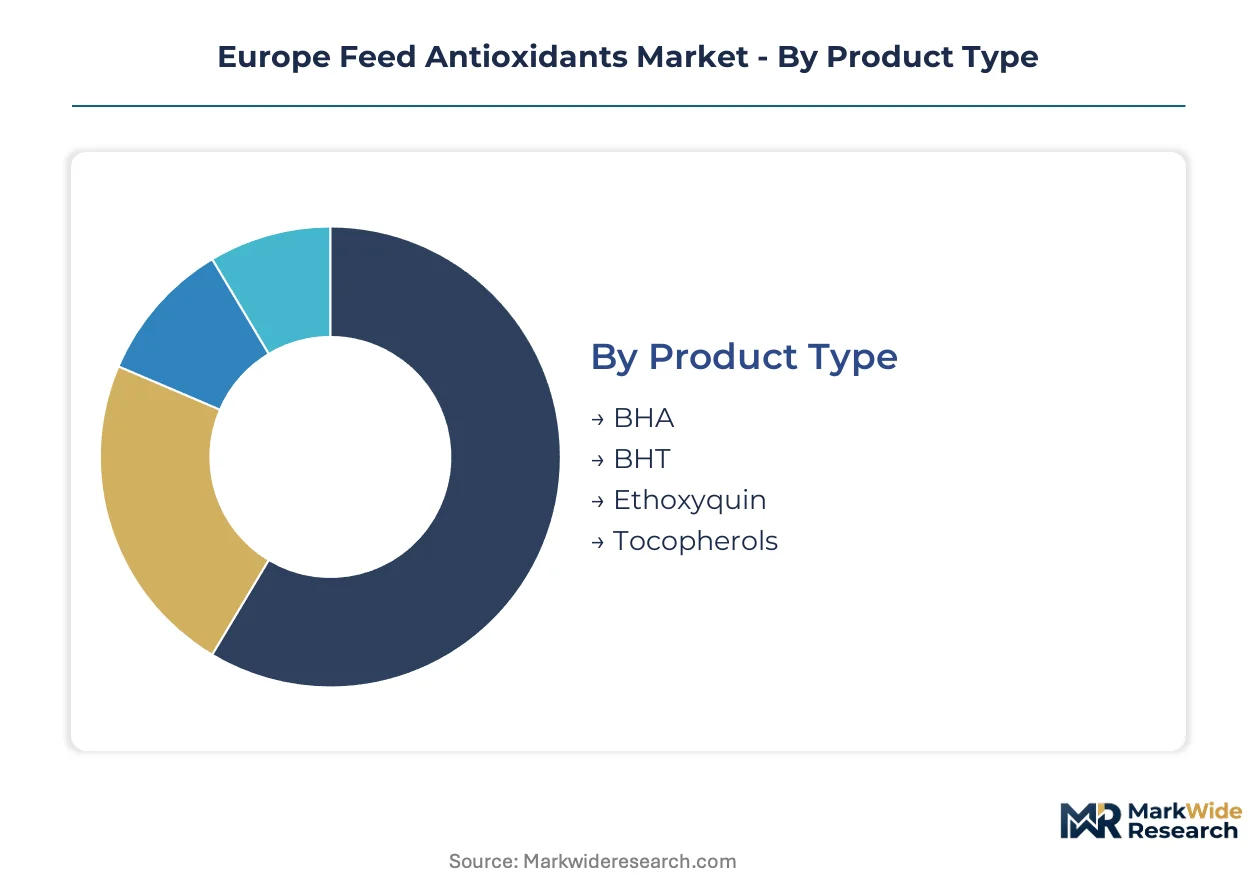
Antioxidant specification varies sharply across species, formulation chemistry, and distribution channel, with each axis demanding distinct production assets and regulatory compliance postures. Compound feed mills in Germany's Rhineland cluster and France's Brittany corridor configure procurement differently depending on which segmentation lens dominates their supply agreements.
Product Type:
Capital intensity concentrates in synthetic manufacturing infrastructure, while natural extraction facilities demand flexible feedstock handling systems.
- Tocopherols:Vitamin E-derived compounds extracted from vegetable oils through molecular distillation. Demand concentrates in Brittany poultry integrators responding to French supermarket chain residue disclosure mandates. REACH Article 33 compliance costs accelerate reformulation away from synthetic alternatives.
- BHT:Synthetic phenolic antioxidant manufactured via alkylation of p-cresol with isobutylene. Polish compound feed mills in Greater Poland Voivodeship rely on BHT for cost-effective shelf-life extension in cross-border poultry feed distribution. ECHA substance of very high concern screening threatens certain impurity profiles.
- BHA:Butylated hydroxyanisole synthesized from p-methoxyphenol and isobutylene, deployed in high-fat aquafeed matrices.
- Ethoxyquin:Quinoline-based antioxidant facing EFSA re-evaluation pressure, with supply chains concentrated in trans-shipment corridors through Rotterdam.
Tocopherols absorb the bulk of installed capacity; tocopherols are expanding most quickly.
Application:
Species-specific metabolism drives inclusion rate differentiation and bioavailability requirements.
- Poultry:Broiler and layer operations require antioxidants at 100-200 ppm to protect fat-soluble vitamins during pelleting and storage. Spain's Aragon region processors specify tocopherol-only formulations for EU Green Deal compliance.
- Aquaculture:Marine and freshwater species demand higher inclusion rates due to elevated dietary lipid content. Mediterranean farms in Greece deploy micro-encapsulated tocopherol forms for uniform dispersion in high-moisture extruded feeds.
- Swine:Grower-finisher diets incorporate antioxidants to prevent vitamin A and E degradation in extended storage.
- Ruminants:Dairy and beef operations show lower per-tonne inclusion rates due to rumen bypass protection requirements.
Poultry commands the dominant share of volume; aquaculture posts the steepest expansion trajectory.
Form:
Physical state determines blending equipment requirements and dispersion uniformity in target matrices.
- Powder:Standardized particle size distributions enable direct pneumatic conveying into large-scale mill mixing lines. German Rhineland feed clusters process powder tocopherol at throughputs exceeding 50 tonnes per hour.
- Liquid:Concentrates require heated storage and metered injection systems for uniform distribution. Denmark's decentralized dairy operations receive tanker-delivered liquid antioxidants bypassing traditional mill intermediaries.
- Granule:Agglomerated forms reduce dust exposure and improve handling characteristics in manual farm-level dosing.
- Tablet:Compressed units serve niche premix and specialty supplement applications requiring precise unit dosing.
Powder captures the majority of production assets; liquid concentrates gain share fastest.
End User:
Customer scale and integration level reshape procurement sophistication and specification stringency.
- Feed Manufacturers:Large compounders in Germany and France operate centralized antioxidant procurement with multi-year supply agreements and REACH documentation requirements. Near-infrared spectroscopy verification systems validate potency at intake points.
- Livestock Farms:Direct farm sourcing concentrates in Denmark's cooperative dairy structure and Netherlands' pig farming collectives, demanding simplified liquid delivery logistics.
- Pet Food Producers:Premium positioning drives specification toward natural tocopherol forms with full supply chain traceability documentation.
- Nutraceutical Companies:Human-grade antioxidant extraction for supplement applications imposes GMP compliance burdens distinct from feed-grade standards.
Feed manufacturers deploy the greatest procurement volume; livestock farms are shifting sourcing patterns most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for feed antioxidants concentrates in Germany's Rhineland chemical corridor and France's Brittany livestock belt, where poultry integrators face the strictest retailer residue disclosure mandates. Spain's Aragon region and Poland's Greater Poland Voivodeship are emerging as high-growth pockets as export-oriented processors invest in extended shelf-life formulations.
Germany
REACH Article 33 disclosure obligations and the F-Gas Regulation constrain solvent-based extraction processes for synthetic antioxidants. EFSA re-evaluation timelines compress formulation windows for compound feed mills. The Rhineland feed cluster near Ludwigshafen processes powder tocopherol at throughputs exceeding 50 tonnes per hour while pre-emptively reformulating to avoid downstream liability exposure.
France
French supermarket chains now mandate feed additive disclosure to farm level, bypassing traditional processor intermediaries. The EU Green Deal's national implementation plan mandates reduced synthetic additive residues in poultry supply chains. Brittany integrators respond by consolidating antioxidant sourcing to single-supplier contracts with full traceability documentation.
Spain
Aragon region processors specify tocopherol-only formulations to comply with EU Green Deal sustainability targets for export-bound poultry production. Compound feed mills struggle to hire analytical chemists capable of running oxidative stability index testing for natural antioxidant validation. Near-infrared spectroscopy systems deploy at mill intake points to reject substandard tocopherol shipments.
Poland
Integrated poultry processors in Greater Poland Voivodeship require extended feed shelf life for cross-border distribution into German and Benelux markets. BHT remains the cost-effective workhorse for shelf-life extension despite ECHA substance of very high concern screening threats. Feed manufacturers accelerate natural antioxidant trials ahead of anticipated synthetic approval expirations.
Denmark
Decentralized dairy cooperative structures create demand for direct-to-farm liquid concentrate distribution bypassing traditional mill intermediaries. Tanker delivery networks capture margin in fragmented procurement environments. CSRD-aligned sustainability certification schemes reward verifiable natural additive sourcing with preferential retail procurement status.
Europe Feed Antioxidants Market Competitive Landscape
Backward integration into oilseed processing dominates the current landscape as compounders secure captive supply of raw material flows for natural antioxidant extraction. The vendor base organizes around three strategic archetypes: multinational chemical conglomerates with integrated manufacturing complexes, specialty nutrition houses with precision-delivery R&D capabilities, and agricultural traders leveraging upstream commodity control. Capacity expansion and portfolio diversification toward natural formulations represent the two dominant competitive moves as synthetic approvals face compression.
Among diversified chemical conglomerates, BASF SE anchors the synthetic manufacturing tier through its Ludwigshafen production complex, while DSM-Firmenich AG occupies a position exemplifying R&D intensity in precision-delivery tocopherol forms. Cargill Inc. represents the agricultural trading archetype, leveraging in-house oilseed processing to secure extraction feedstocks. These three entities collectively illustrate how competitive positioning in European feed antioxidants increasingly depends on upstream control over vegetable oil supply chains rather than standalone formulation chemistry.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BASF SE |
| DSM-Firmenich AG |
| Cargill Inc. |
| Kemin Europa |
| Adisseo France SAS |
| AllTech |
| Novus International |
| Danisco |
| Others |
Supply & Pricing Matrix
Family-owned vegetable oil processors in Germany's Rhineland corridor anchor supply security for natural antioxidant extraction, translating upstream feedstock control into pricing discipline that resists volatility from Black Sea oilseed markets. Their captive sourcing arrangements compound pricing power when REACH compliance costs squeeze synthetic alternatives out of formulation portfolios.
Pricing Analysis
Volume flows concentrate in standard-grade tocopherol powder for large-scale mill integration, while margin capture concentrates in precision-delivery liquid concentrates for aquaculture and direct-to-farm dairy operations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified natural extracts from legacy synthetic formulations and unverified import alternatives. Pricing pressure stems from vegetable oil feedstock volatility in sunflower and soybean sourcing regions. Compound feed manufacturers in Poland's Greater Poland Voivodeship exhibit highest price sensitivity, while Brittany poultry integrators facing supermarket chain residue mandates show lowest sensitivity.
Supply Chain Analysis
Refurbished solvent extraction equipment from decommissioned synthetic antioxidant plants in Germany's industrial belt is redeployed for natural tocopherol distillation, extending asset life cycles while reducing capital intensity for mid-scale processors. Supply concentrates in Germany, France, and Spain for formulation and blending, with raw material dependencies on Ukrainian sunflower oil, Argentine soybean meal, and Malaysian palm fatty acid distillates. Single-source vulnerability runs through Rotterdam trans-shipment corridors for ethoxyquin imports. Distribution runs through centralized mill procurement in Germany and France, with direct-to-farm tanker networks gaining share in Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-delivery encapsulation technologies are displacing conventional powder formulations across species-specific applications, creating technology-transition dynamics that favor R&D-intensive suppliers over commodity chemical producers.
For Market Incumbents: To counter EFSA re-evaluation timelines that threaten synthetic product registrations, accelerate backward integration into oilseed crushing assets in the Black Sea region and pre-validate natural extract formulations ahead of regulatory deadlines. Invest in near-infrared spectroscopy verification systems at customer intake points to lock in multi-year supply agreements with traceability documentation. For New Entrants and Emerging Players: Micro-encapsulated tocopherol forms for high-moisture aquafeeds offer the most penetrable wedge, targeting Mediterranean marine farms in Greece and Spain where dispersion uniformity commands premium positioning. Enter through technical service partnerships with regional premix distributors rather than direct mill sales, leveraging formulation support capabilities to bypass entrenched supply relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap natural extraction specialists in Romania and Bulgaria with underutilized vegetable oil processing capacity and proximity to expanding Transylvania pig farming demand. Monitor ECHA substance of very high concern designations for BHT impurities as the inflection signal that would accelerate incumbent reformulation spending and expand addressable market for natural alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Captive supply of tocopherol feedstock secures margin against Black Sea price volatility. |
| Precision-Delivery Encapsulation R&D | Micro-encapsulated forms capture aquaculture premium and open Mediterranean farm access. |
| REACH Compliance Pre-Validation | Early natural formulation certification avoids downstream liability from synthetic re-evaluations. |
| Direct-to-Farm Liquid Distribution | Tanker networks bypass mill intermediaries and capture margin in Denmark's dairy cooperatives. |
| Near-Infrared Spectroscopy Deployment | Real-time potency verification at intake points locks in multi-year supply agreements with integrators. |
Research Methodology
Multi-period observation of EFSA feed additive re-evaluation timelines, REACH registration deadlines, and EU Green Deal national implementation milestones anchored the trend analysis, supplemented by interviews with compound feed mill procurement directors, vegetable oil extraction plant managers, poultry integrator nutritionists, and aquaculture farm operations managers. Secondary validation drew from ECHA candidate list publications, customs trade data for antioxidant imports, Cefic chemical industry reports, and SEC filings of diversified chemical conglomerates. Bottom-up volume estimates from country-level feed production statistics triangulated against top-down market sizing from supplier revenue disclosures.
Input-output matrices mapped tocopherol extraction yields from vegetable oil processing through formulation blending to end-use inclusion rates across poultry, swine, aquaculture, and ruminant applications. Segmentation dimensions modeled included product chemistry, species application, physical form, and customer scale tier. CAGRs derived from regression analysis of historical feed production growth, antioxidant penetration rates, and regulatory-driven substitution elasticities. Industry-specific forecast inputs incorporated EFSA safety review cycle durations and EU feed sustainability certification scheme development trajectories.
Several conditions sit outside the modeled scope, including abrupt EFSA safety findings that could accelerate synthetic withdrawal timelines, and geopolitical disruptions to Black Sea oilseed supply corridors. Forecasts reflect documented assumptions about regulatory implementation pacing and feed manufacturer reformulation behavior. Practitioners should monitor ECHA substance of very high concern list expansions and supermarket chain procurement policy shifts for early signals of demand acceleration toward natural alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
Plant Growth Regulators Market