
 Aquaculture Pumps Market | 2026-2036
Aquaculture Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Pumps Market Insights
Norway's expansion of land-based and semi-closed containment systems is reshaping pump procurement patterns across Atlantic salmon aquaculture. Grundfos Holding A/S leverages its energy-efficient submersible portfolio to anchor contracts with Nordic integrators. Xylem Inc. competes through advanced monitoring capabilities that reduce unplanned downtime in high-density tanks. Pentair plc differentiates via backward integration into water treatment systems, offering bundled circulation and filtration packages.
Aquaculture pumps are engineered fluid-handling devices designed to move, aerate, or filter water in controlled aquatic production environments, typically constructed from corrosion-resistant materials such as stainless steel or thermoplastics to withstand continuous saltwater or high-organic-load exposure. Their primary function is maintaining dissolved oxygen levels, waste removal, and hydraulic turnover rates critical to species survival in intensive farming operations. Submersible pumps dominate installed capacity due to reliability in submerged conditions, while centrifugal configurations capture margin pools in large-volume flow applications. Electric technology leads technology segmentation by unit volume, though solar-powered variants gain traction in off-grid hatcheries and remote shellfish operations where grid connection costs prove prohibitive.
EPA effluent guidelines in the United States and EU Water Framework Directive standards enforced by national regulators constrain discharge parameters, directly elevating demand for precision pumping and integrated filtration systems that maintain compliance. China's MEE implements stricter aquaculture wastewater mandates under dual carbon goals, compelling domestic farms toward higher-efficiency equipment. Japan's METI promotes energy conservation in marine product processing chains, indirectly tightening pump performance benchmarks. Stakeholders must weigh total cost of ownership against regulatory trajectory when specifying systems for new capacity.
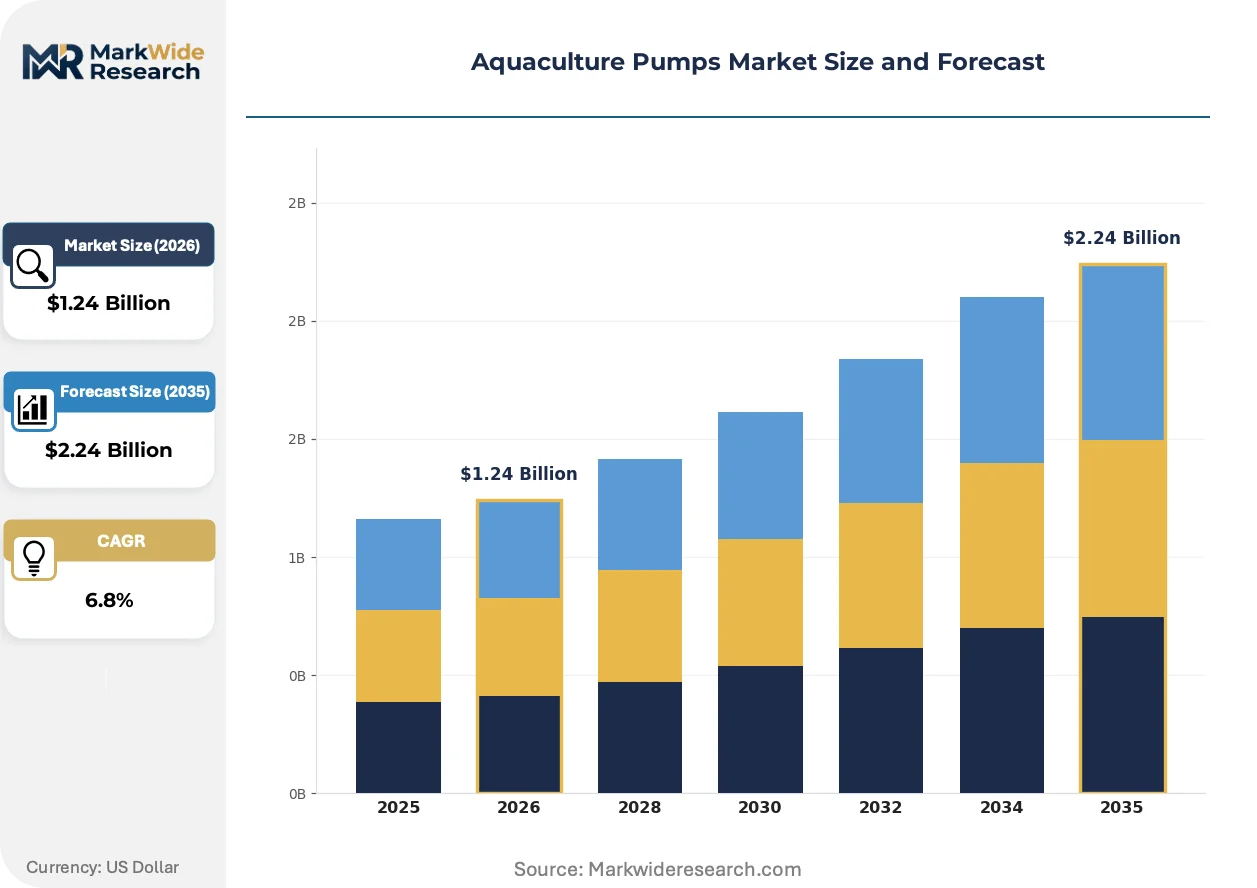
Market Dynamics
Recirculating aquaculture system adoption in Atlantic salmon farming is compressing equipment replacement cycles as operators pursue higher stocking densities and tighter water quality control. This structural shift elevates pump specifications from volume handling toward precision flow management with integrated monitoring.
Growth Catalysts
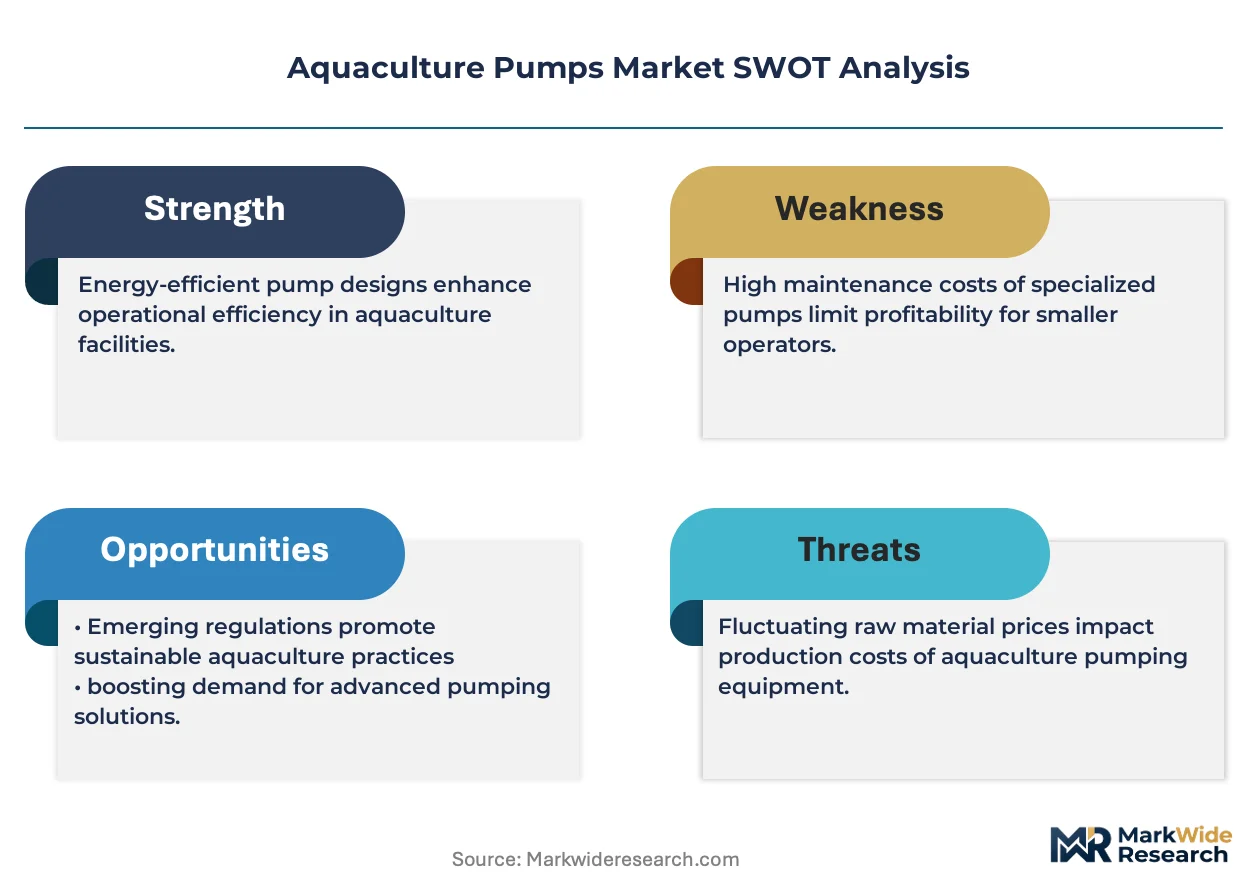
- EU Water Framework Directive enforcement:Stricter discharge parameters across European member states mandate precision pumping with integrated filtration, forcing equipment upgrades in existing facilities.
- Submersible pump reliability:Corrosion-resistant stainless steel and thermoplastic constructions extend operational lifespans in continuous saltwater exposure, reducing unplanned downtime in offshore net-pen operations.
- China's MEE wastewater mandates:Dual carbon goals tighten aquaculture effluent standards, compelling domestic farms toward higher-efficiency circulation systems with lower energy intensity.
Market Restraints
- Stainless steel price volatility:Raw material cost swings for corrosion-resistant alloys compress manufacturer margins and complicate long-term contract pricing.
- Supply concentration in Nordic pump assembly:Geographic clustering of specialized marine-grade component suppliers creates vulnerability to regional logistics disruptions.
- Technical limitation in high-organic-load handling:Biofouling and solids accumulation in intensive recirculating systems accelerate wear on impeller mechanisms.
Strategic Opportunities
- Underpenetrated remote shellfish operations:Off-grid hatcheries in coastal Southeast Asia present demand for solar-powered pump variants where grid connection costs prove prohibitive.
- Technology convergence of pumping and aeration:Integrated water movement and oxygenation systems reduce capital footprint in land-based salmon smolt facilities.
- Japan's METI energy conservation promotion:Processing chain efficiency benchmarks tighten performance requirements, creating specification advantages for variable-frequency drive configurations.
Industry Challenges
- Marine hydraulics engineering talent scarcity:Specialized expertise in saltwater corrosion dynamics and biofouling management remains concentrated among aging practitioner cohorts.
- Legacy control system integration friction:Retrofitting precision monitoring capabilities into existing tank infrastructure demands customized interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Pumps Market |
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Diaphragm, Centrifugal, Gear Application: Water Circulation, Aeration, Filtration, Feeding End User: Fish Farms, Shellfish Farms, Hatcheries, Integrated Farms Technology: Electric, Solar, Hydraulic, Pneumatic |
| Companies Covered | Xylem Inc., Pentair plc, Grundfos Holding A/S, Sulzer Ltd., KSB SE & Co. KGaA, Tsurumi Manufacturing Co., Ltd., Flowserve Corporation, Franklin Electric Co., Inc., Ebara Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Pumps Market Trends and Innovations
Digital twin architectures are penetrating aquaculture pump specification as operators seek predictive maintenance capabilities and real-time performance optimization across distributed farming sites.
Sensor-embedded submersible units with edge computing capabilities are virtualizing traditional preventive maintenance schedules into condition-based interventions. Norwegian Atlantic salmon integrators deploy these configurations most aggressively, compressing service intervals from calendar-based to degradation-triggered. This virtualization is collapsing the distinction between equipment supplier and water management service provider.
China's NMPA tightened aquaculture water discharge standards create compliance-driven specification pressure across domestic intensive farming operations. The regulatory framework elevates mandatory filtration integration with circulation equipment, effectively bundling previously separate procurement categories. Domestic operators respond by consolidating vendor relationships toward full-system suppliers capable of unified compliance documentation.
After-sales service unbundling is fragmenting traditional pump procurement as large-scale operators internalize routine maintenance while outsourcing specialized overhauls. This bifurcation disrupts incumbent distribution channels built on bundled spare parts and field service contracts. The pattern is most visible in Norway's land-based salmon facilities where in-house technical teams manage daily operations.
Aquaculture Pumps Market Segmentation
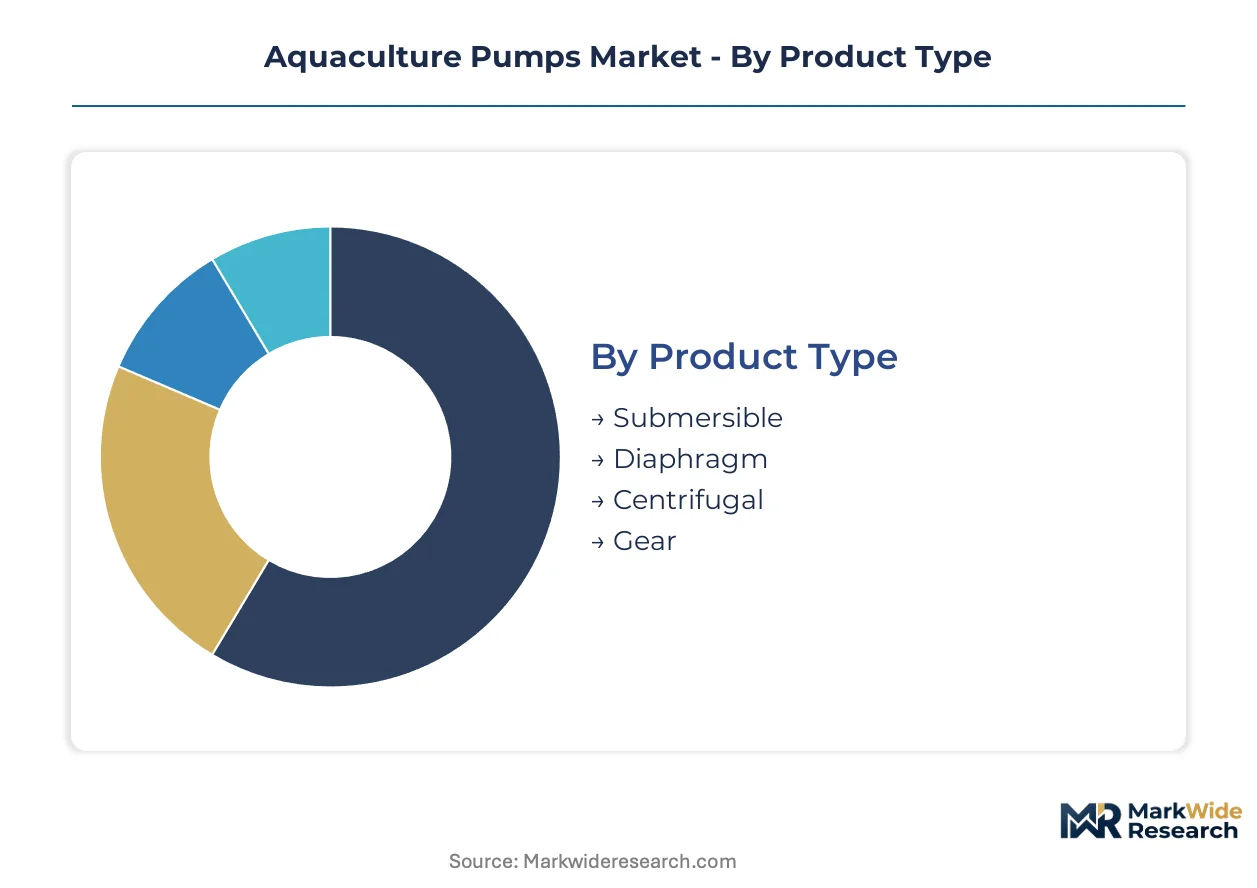
Pump specification in aquaculture diverges sharply across production intensity levels, with recirculating systems demanding precision flow management while extensive shellfish operations prioritize energy autonomy. Understanding these segment boundaries clarifies procurement patterns and vendor positioning strategies across the value chain.
Product Type:
After-sales service intensity varies dramatically by pump architecture, with submersible configurations requiring specialized diving crews for maintenance while surface-mounted alternatives permit in-house technical teams.
- Submersible:These units operate fully immersed, constructed from corrosion-resistant stainless steel or thermoplastics to withstand continuous saltwater exposure. Norwegian Atlantic salmon integrators deploy sensor-embedded variants with edge computing capabilities, compressing service intervals from calendar-based to degradation-triggered interventions. Demand concentrates in offshore net-pen operations where reliability failures carry catastrophic biomass loss.
- Centrifugal:Surface-mounted configurations handle large-volume flow applications in land-based smolt facilities and processing plants. China's domestic farms favor these units for integrated filtration compliance under MEE wastewater mandates, bundling previously separate procurement categories.
- Diaphragm:Positive displacement mechanisms excel in precise dosing applications for chemical treatment and medication delivery systems.
- Gear:Compact rotary designs serve niche high-pressure requirements in hydraulic transfer systems and slurry handling.
Submersible configurations hold the largest share; momentum sits with centrifugal variants in land-based containment expansion.
Application:
Capital deployment patterns shift markedly across functional roles, with aeration and filtration commanding premium pricing due to regulatory compliance burdens while circulation operates as a commoditized volume category.
- Water Circulation:The foundational hydraulic turnover function maintains tank exchange rates critical to species survival in intensive operations. Norwegian land-based salmon facilities drive specification toward variable-frequency drive configurations that align flow rates with real-time biomass loading.
- Filtration:Integrated solids removal and biological treatment systems elevate pump specifications from volume handling toward precision pressure management. China's NMPA discharge standard tightening forces domestic operators toward full-system suppliers capable of unified compliance documentation.
- Aeration:Dissolved oxygen maintenance combines water movement with gas injection, collapsing equipment categories in advanced recirculating system designs.
- Feeding:Hydraulic feed delivery systems demand gentle product handling to preserve pellet integrity during distribution.
Water circulation commands the installed base; filtration is climbing the fastest as discharge regulations tighten across major producing jurisdictions.
End User:
Technical sophistication gradients separate customer segments, with integrated multi-species operations demanding system-wide optimization while single-species farms prioritize unit reliability.
- Fish Farms:Atlantic salmon producers in Norway's fjord systems and Chile's Los Lagos region anchor demand for high-reliability submersible portfolios. These operators pursue higher stocking densities through recirculating adoption, elevating specifications toward precision flow management with integrated monitoring.
- Hatcheries:Early-life-stage facilities require exceptional water quality stability, driving demand for redundant pumping architectures and backup power integration.
- Shellfish Farms:Remote coastal operations in Southeast Asia present underpenetrated demand for solar-powered variants where grid connection costs prove prohibitive.
- Integrated Farms:Multi-species, multi-stage operations consolidate vendor relationships toward single-source accountability across species transfer and processing stages.
Fish farms dominate procurement volume; hatcheries show the steepest specification escalation as genetic improvement programs intensify production density.
Technology:
Energy sourcing decisions reflect grid infrastructure maturity and carbon accounting pressures, with electric dominance challenged by autonomy requirements in frontier production zones.
- Electric:Grid-connected configurations lead unit volume through reliability and power density advantages. Japan's METI energy conservation promotion tightens performance benchmarks, creating specification advantages for variable-frequency drive configurations in processing chain applications.
- Solar:Photovoltaic-powered variants gain traction in off-grid hatcheries and remote shellfish operations across Indonesia, Vietnam, and the Philippines where grid extension economics fail.
- Hydraulic:Fluid power systems serve explosive atmosphere requirements and heavy-duty slurry applications in integrated farm waste handling.
- Pneumatic:Compressed air-driven pumps address specific safety and corrosion challenges in chemical dosing and volatile environment operations.
Electric technology retains the largest installed base; solar configurations are expanding most quickly in Southeast Asian coastal development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore grid interconnect and Baltic Pipe energy corridor underpin Norway's position as the dominant demand center for marine-grade pumping infrastructure.
Norway
Land-based Atlantic salmon containment expansion and semi-closed fjord systems drive precision pump procurement. The Norwegian Food Safety Authority encloses stricter sea lice and effluent discharge protocols under the Traffic Light System. Bergen and Trøndelag clusters host the densest concentration of recirculating system integrators upgrading hydraulic infrastructure.
China
Intensive shrimp and tilapia farming in Guangdong and Hainan provinces accelerates wastewater treatment equipment deployment. The MEE implements progressively tighter aquaculture effluent standards under dual carbon policy frameworks. The Yangtze River Delta concentration of pump manufacturers is pivoting toward integrated filtration-circulation systems for domestic compliance.
United States
Catfish operations in the Mississippi Delta and salmon hatcheries in the Pacific Northwest expand recirculating capacity. EPA effluent limitation guidelines constrain discharge parameters for concentrated aquatic animal production facilities. Seattle-Tacoma industrial corridor suppliers are bundling monitoring technologies with circulation hardware.
Japan
Yellowtail and amberjack farming in Kagoshima Bay and Ehime Prefecture intensifies hydraulic turnover requirements. METI energy conservation promotion tightens performance benchmarks across marine product processing chains. The Seto Inland Sea industrial belt concentrates variable-frequency drive adoption for flow optimization.
Chile
Atlantic salmon operations in the Los Lagos and Aysén regions confront escalating water quality management costs. The national fisheries service enforces area-based management regulations that elevate treatment infrastructure standards. Puerto Montt supplier networks are consolidating toward full-system accountability for discharge compliance.
Aquaculture Pumps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base stratifies across three functional layers: full-system suppliers bundling circulation with filtration, standalone pump manufacturers defending volume positions, and materials specialists supplying corrosion-resistant alloys and thermoplastic components. Dominant competitive moves include backward integration into water treatment modules and geographic anchoring through Nordic assembly partnerships.
Within the integrated-system tier, Pentair plc and Grundfos Holding A/S occupy positions exemplifying bundled filtration-circulation offerings. Xylem Inc. represents the monitoring-embedded archetype where sensor integration differentiates submersible configurations. These three anchors illustrate how specification pressure from discharge regulations is collapsing procurement categories toward unified compliance documentation.
| Leading Market Players |
|---|
| Xylem Inc. |
| Pentair plc |
| Grundfos Holding A/S |
| Sulzer Ltd. |
| KSB SE & Co. KGaA |
| Tsurumi Manufacturing Co., Ltd. |
| Flowserve Corporation |
| Franklin Electric Co., Inc. |
| Ebara Corporation |
| Others |
Pricing and Supply Chain Analysis
Bergen's marine-grade pump assembly corridor concentrates specialized corrosion-resistant alloy fabrication capacity, anchoring procurement leverage for Nordic integrators while transmitting stainless steel volatility downstream into contract renegotiation cycles across Atlantic salmon operations.
Pricing Analysis
EU Water Framework Directive enforcement dictates the pricing tier structure across European aquaculture pump procurement. Three-tier pricing structure across premium sensor-embedded, standard mechanical, and economy basic circulation levels separates compliance-bundled systems from standalone units. Stainless steel price volatility compresses margins in premium tiers most acutely. Small-scale shellfish operators in Southeast Asia exhibit highest price sensitivity; Norwegian land-based salmon integrators show lowest due to biomass loss risk from equipment failure.
Supply Chain Analysis
Specialized foundries in Norway, Denmark, and Germany hold contract-manufacturing concentration for marine-grade stainless impeller castings and thermoplastic housing production. Supply draws from nickel alloy suppliers in Finland, precision bearing manufacturers in Sweden, and electronic sensor module producers in Japan. Single-source vulnerability concentrates in Nordic marine-grade alloy finishing capacity. Distribution runs through OEM-direct contracts for large integrators and regional distributor networks for mid-scale farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against air-lift aeration systems and passive hydraulic designs that displace mechanical pumping in low-intensity shellfish operations.
For Market Incumbents: Pre-empt sensor-embedded pump commoditization by anchoring long-term service contracts with Norwegian land-based salmon facilities. Deepen backward integration into water treatment module production to defend margin position against full-system bundling pressure from filtration specialists. Lock exclusive alloy supply agreements with Finnish nickel processors before contract renegotiation windows open.
For New Entrants and Emerging Players: Remote Indonesian and Vietnamese shellfish hatcheries present the most penetrable white-space for solar-powered pump variants where grid extension economics fail. Target single-species shrimp operations in Guangdong with simplified centrifugal configurations designed for MEE compliance documentation bundling. Pursue OEM private-label partnerships with Yangtze River Delta pump assemblers lacking marine-grade corrosion expertise.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because discharge standard tightening across China, EU, and Chile creates sustained replacement demand regardless of protein price cycles. Acquisition target archetype: mid-scale sensor-embedded submersible specialists with existing Nordic integrator relationships. Monitor NMPA enforcement variance across Chinese provincial MEE offices as early signal for compliance-driven specification escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filtration Modules | Captures bundled procurement collapsing circulation and treatment categories under EU Water Framework Directive enforcement. |
| Sensor-Embedded Product Launch | Compresses maintenance intervals from calendar-based to degradation-triggered for Norwegian Atlantic salmon integrators. |
| Joint Venture with Nordic Alloy Foundries | Secures captive supply of marine-grade stainless components against raw material price volatility. |
| Geographic Expansion into Southeast Asian Shellfish | Addresses underpenetrated off-grid hatchery demand for solar-powered variants in Indonesia and Vietnam. |
| Long-term Service Contract Anchoring | Locks recurring revenue streams as large operators unbundle after-sales and internalize routine maintenance. |
Research Methodology
A standing panel of aquaculture operations managers, marine equipment procurement leads, and pump system maintenance directors provided ongoing calibration across primary field engagement. Secondary validation drew from MEE discharge filings, Norwegian Food Safety Authority inspection records, EU Water Framework Directive implementation reports, and customs trade data on corrosion-resistant alloy imports. Bottom-up equipment installation tracking and top-down protein production volume modeling were triangulated against regulatory mandate timelines.
Scenario-bracketing framed analytical approach across conservative, baseline, and accelerated regulatory enforcement pathways over the projection horizon. Segmentation dimensions modeled include pump architecture type, application function, end-user production intensity, and energy sourcing technology, with additional cross-cutting by regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression rates and stocking density escalation curves specific to Atlantic salmon recirculating system adoption.
Practitioners should monitor stainless steel alloy price indices, NMPA provincial enforcement variance, and Norwegian Traffic Light System recalibration schedules for early signals of specification or procurement pattern shifts. Quarterly review of MEE discharge violation penalties and Nordic integrator capital expenditure disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Aquaponics Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Global Precision Aquaculture Market