
 Seed Binders Market | 2026-2036
Seed Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Binders Market Analytics
The EU Green Deal is rebalancing formulation priorities across European seed treatment supply chains, compelling binder suppliers to reformulate around reduced synthetic polymer loads. DSM-Amulix leverages its bio-polymer platform to capture premium positioning in sustainable seed coating systems. Croda International anchors its competitive stance through lipid-based delivery technologies that improve active ingredient adhesion. Bayer SeedGrowth competes on integrated seed-treatment-to-binder pipelines that streamline grower procurement.
Seed binders are adhesive or cohesive formulations—typically comprising natural gums, synthetic polymers, or modified starches applied at 0.5-5% weight-to-seed ratios—that secure active ingredients, nutrients, or biologicals onto seed surfaces to ensure uniform coverage and planting performance. Liquid binders dominate volume throughput in high-speed commercial coating operations, while film coating agents command superior margins due to precision application requirements and compatibility with sensitive biological actives. Powder binders sustain relevance in smallholder-oriented supply chains where equipment simplicity and ambient storage conditions predominate.
The EPA regulates seed treatment chemicals under FIFRA, while the EU's REACH framework governs polymer registration and environmental release thresholds for coated seeds entering European cultivation. India's Central Insecticides Board imposes distinct residue limits that shape export-bound formulation specifications for suppliers targeting South Asian markets. Stakeholders must monitor evolving bio-polymer performance standards and regional registration timelines to align R&D pipelines with divergent compliance landscapes.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing permissible synthetic chemistries in seed coatings, compelling binder suppliers to rebuild formulation platforms around bio-based polymer systems while maintaining field performance standards.
Growth Catalysts
- Regenerative Agriculture Commitments:Agricultural cooperatives across the United States Corn Belt and Brazil's Cerrado are scaling film-coated seed treatment purchases to meet verified soil health targets and carbon sequestration protocols.
- Biological Actives Compatibility:Modified starch and lipid-based binders enable viable coating of living microbial inoculants that synthetic polymers denature, opening formulation partnerships between binder suppliers and biological input developers.
- Precision Planting Equipment:High-speed commercial planters in Iowa and Mato Grosso require treated seed uniformity that only advanced film-coating binders deliver, locking in technical specifications across equipment fleets.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic polymer binders remain exposed to propylene and ethylene price swings that compress margin predictability for formulators serving price-sensitive commodity crop segments.
- REACH Registration Burden:The EU's polymer registration requirements impose multi-year compliance timelines and environmental release testing costs that deter mid-tier suppliers from European market entry.
- Equipment Retrofit Requirements:Smallholder-oriented coating operations in South Asia face capital barriers when shifting from powder to liquid binder systems, preserving legacy technology lock-in.
Strategic Opportunities
- Underpenetrated Biologicals Integration:India's Punjab and Haryana rice-wheat systems represent untapped demand for binders compatible with nitrogen-fixing bacterial coatings as chemical fertilizer subsidies face phased reduction.
- Carbon Credit Verification:Bio-based binder platforms qualify for EU carbon farming certification schemes, creating premium pricing corridors for suppliers with third-party lifecycle assessments.
- Vertical Distribution Partnerships:Direct technical service relationships with multi-state agronomy retailers in Illinois and Indiana bypass traditional distribution markups while capturing planting-season demand concentration.
Industry Challenges
- Formulation Chemistry Expertise Gap:The transition from synthetic to bio-based polymer systems requires polymer scientists with seed physiology knowledge, a skill intersection scarce in agricultural input labor markets.
- Multi-Jurisdiction Registration Synchronization:Binder suppliers must align EPA FIFRA submissions with EU REACH dossiers and India's Central Insecticides Board residue protocols, fragmenting R&D timelines across regulatory calendars.
- Legacy Coating Equipment Integration:Retrofitting established treater lines for lower-viscosity bio-binder chemistries without throughput degradation demands engineering coordination that stretches supplier technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Binders Market |
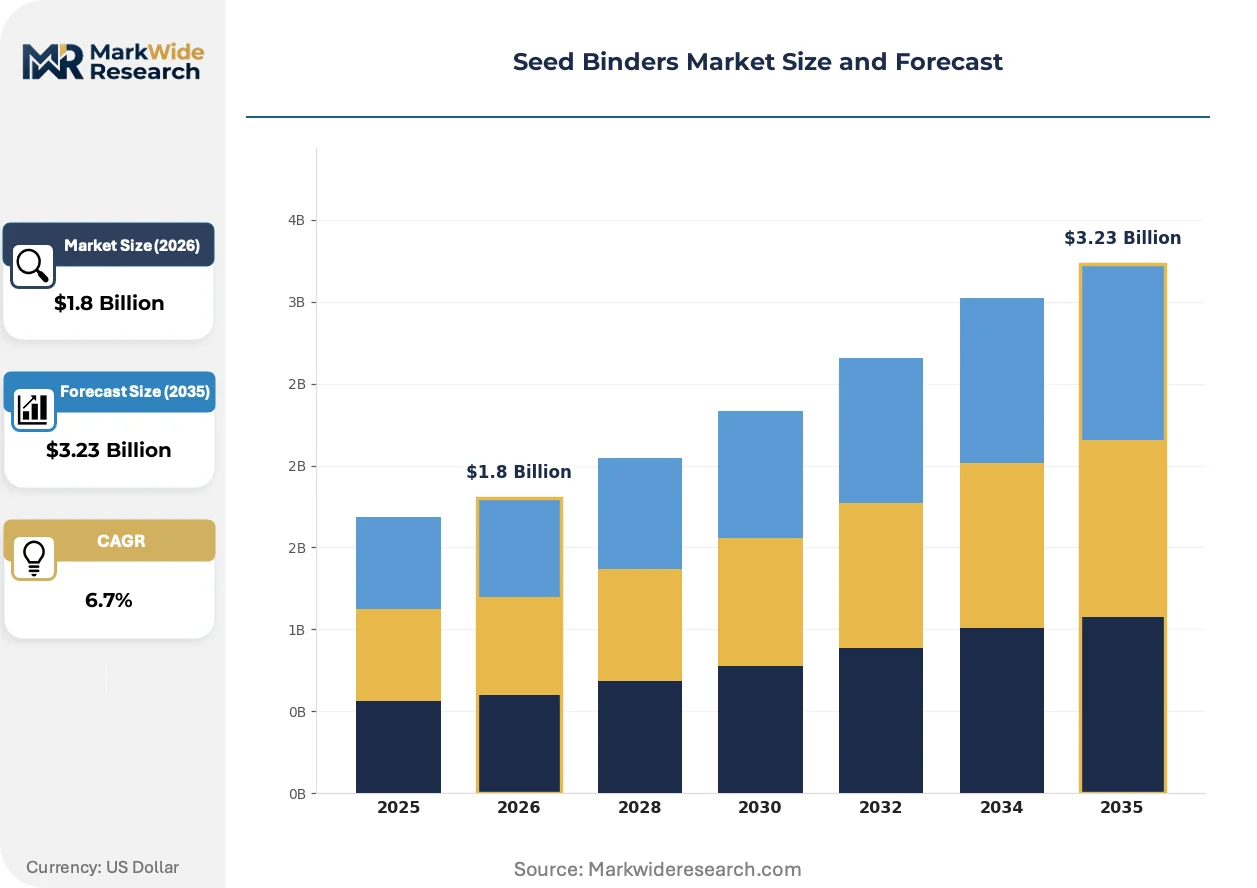
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Binders, Granular Binders, Powder Binders, Film Coating Agents Application: Agricultural Seeds, Horticultural Seeds, Turf Seeds, Specialty Seeds End User: Seed Manufacturers, Agricultural Cooperatives, Research Institutions, Retailers Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Wholesalers |
| Companies Covered | Centor Europe, DSM-Amulix, Croda International, Bayer SeedGrowth, Sekisui Specialty Chemicals America, GLOBACHEM, Germains Seed Technology, Michelman, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Binders Market Evolving Landscape
Formulation chemistry is pivoting from petrochemical-derived adhesives toward bio-polymer platforms that satisfy tightening environmental release standards without sacrificing planting performance metrics.
Film-coating technology is overtaking conventional slurry coating in high-volume commercial operations. These systems apply binders in precise 0.5-2% weight-to-seed ratios through continuous-flow atomization. Large-scale operators in Brazil and the United States are adopting film-coating equipment at replacement cycle points. This transition is compressing demand for legacy powder binder formats while elevating technical service requirements for precision application support.
REACH polymer registration thresholds are tightening environmental release testing for coated seeds entering European cultivation. The regulation now mandates aquatic toxicity dossiers for binder chemistries previously exempt under lower-volume thresholds. Formulators serving export-oriented seed houses are restructuring supply chains to source pre-registered bio-polymer feedstocks, shifting procurement toward DSM-Amulix and similar platforms with established EU compliance documentation.
Certification-driven purchasing is reconfiguring buyer-supplier relationships in North American agricultural retail. Agronomy cooperatives in Minnesota and Wisconsin now require third-party verified bio-content percentages in seed treatment specifications as a condition of procurement. This behavioral shift elevates binder suppliers with ISO-compliant carbon accounting and lifecycle assessment capabilities while marginalizing synthetic-only portfolios in premium channel access.
Seed Binders Market Segmentation
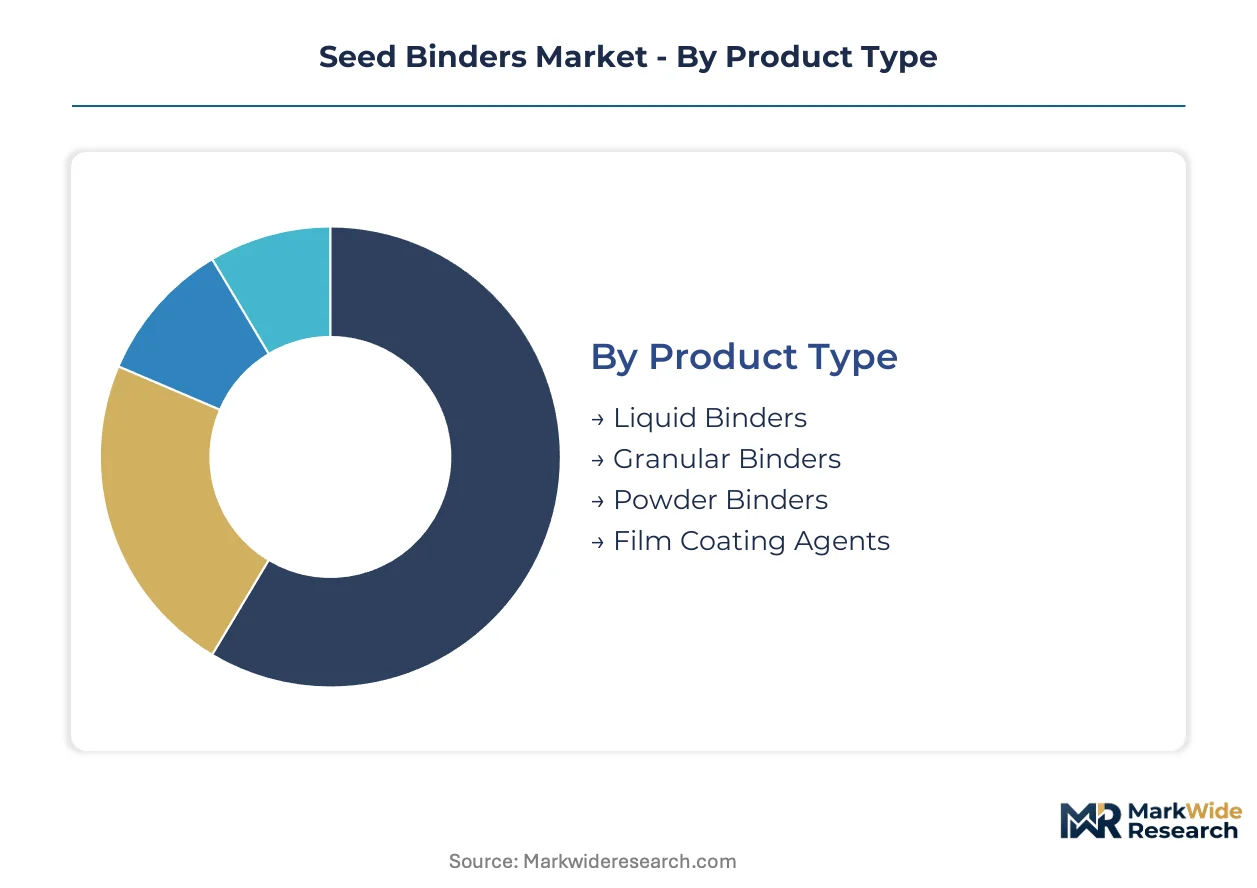
Seed binder procurement patterns diverge sharply between high-volume commercial operators and smallholder-oriented supply chains. Technical specifications for planting equipment compatibility and regulatory compliance requirements create distinct purchasing logics across each segment category.
Product Type:
Cost tier determines equipment compatibility and application precision requirements across buyer profiles.
- Liquid Binders:Polymer-based aqueous formulations applied through continuous-flow atomization systems at 0.5-3% weight-to-seed ratios. Demand concentrates in Brazil's Mato Grosso and Iowa's commercial corn operations where high-speed film-coating equipment mandates low-viscosity, pumpable chemistries. Precision planting requirements lock in technical specifications across equipment fleets.
- Film Coating Agents:Specialized polymer systems enabling sub-2% application rates with micron-level thickness control for sensitive biological actives. European seed houses under EU Green Deal compliance pressure prioritize these systems for microbial inoculant compatibility. REACH-registered bio-polymer platforms command procurement preference.
- Granular Binders:Solid-phase adhesive systems for rotary drum coating operations requiring minimal equipment modification.
- Powder Binders:Dry-mix formulations sustaining relevance in South Asian smallholder supply chains where ambient storage and manual application predominate.
Volume sits with liquid systems; growth tilts toward film coating agents.
Application:
Application context shapes performance specifications for field durability and planting uniformity.
- Agricultural Seeds:High-volume commodity crop treatments for corn, soybean, and wheat requiring abrasion resistance through mechanical planting. The United States Corn Belt and Brazil's Cerrado expansion zones prioritize treated seed flowability for 24-row planter compatibility. Carbon sequestration protocols drive bio-based binder adoption.
- Horticultural Seeds:Vegetable and flower seed coatings demanding precision germination timing and seedling vigor optimization. Protected cultivation systems in the Netherlands and Spain specify low-dust, high-adhesion formulations for automated greenhouse sowing lines. Active ingredient load flexibility distinguishes procurement criteria.
- Turf Seeds:Grass seed treatments for golf course and landscaping applications emphasizing uniform establishment.
- Specialty Seeds:Niche crop and heritage variety coatings with small batch, high-customization requirements.
Revenue concentrates in agricultural applications; margin expansion favors horticultural segments.
End User:
Customer scale determines technical service intensity and formulation customization depth.
- Seed Manufacturers:Integrated treatment operations at Bayer, Corteva, and Syngenta facilities requiring binder supply security at 10,000+ ton annual volumes. Multi-jurisdiction registration synchronization demands suppliers with EPA FIFRA and EU REACH dossier capabilities. Direct technical partnerships predominate over distributor relationships.
- Agricultural Cooperatives:Regional purchasing consortia in Minnesota and Wisconsin aggregating demand for certified sustainable seed treatments. Third-party bio-content verification now conditions procurement decisions. Carbon farming certification eligibility influences supplier selection.
- Research Institutions:Small-batch experimental coating requirements for germplasm development programs.
- Retailers:Final-mile distribution points with limited formulation technical capability.
Procurement volume aggregates at seed manufacturers; specification influence is shifting toward cooperatives.
Distribution Channel:
Channel selection reflects buyer technical sophistication and order fragmentation patterns.
- Direct Sales:Technical service-intensive relationships with seed manufacturers and major cooperatives requiring application engineering support. DSM-Amulix and Croda International deploy field technical staff for equipment retrofit coordination and formulation optimization. Multi-year supply agreements lock in volume commitments.
- Online Sales:Emerging procurement pathway for standardized liquid binder grades among mid-tier regional seed treaters. Digital platforms enable transparent bio-content certification documentation for sustainability-verified purchasing. Logistics complexity limits penetration for temperature-sensitive formulations.
- Retail Outlets:Local agricultural supply points serving smallholder and specialty crop segments.
- Wholesalers:Inventory aggregation for price-sensitive commodity binder grades.
Direct relationships capture premium formulation segments; online channels are gaining share fastest in standard grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Des Moines anchors North American seed binder procurement intensity. The Iowa-Illinois corridor concentrates precision planter fleets and commercial coating operations. Regional demand patterns diverge sharply between mature regulatory environments and emerging agricultural frontiers.
United States
EPA FIFRA registrations govern synthetic polymer binders entering the Corn Belt. Iowa and Illinois seed treaters prioritize film-coating compatibility with 24-row planter specifications. DSM-Amulix maintains technical service presence in Des Moines for equipment retrofit coordination.
Brazil
Mato Grosso soybean operators scale film-coated seed purchases for Cerrado expansion zones. ANVISA regulates active ingredient residues on export-bound seed lots. Campinas clusters formulation R&D partnerships between binder suppliers and biological input developers.
Germany
EU REACH polymer registration thresholds tighten environmental release testing for coated cereals. ECHA mandates aquatic toxicity dossiers previously exempt under lower-volume thresholds. Leverkusen anchors integrated seed-treatment-to-binder pipelines serving Eastern European export markets.
India
Punjab rice-wheat systems generate untapped demand for nitrogen-fixing bacterial coating compatibility. The Central Insecticides Board imposes distinct residue limits shaping export-bound specifications. Ludhiana smallholder cooperatives face capital barriers shifting from powder to liquid binder systems.
Netherlands
EU Green Deal Farm to Fork strategy compresses permissible synthetic chemistries in vegetable seed coatings. EFSA governs microbial inoculant adhesion standards for greenhouse automation. Wageningen research clusters drive bio-polymer performance verification for carbon farming certification eligibility.
Seed Binders Market Competitive Landscape
The competitive structure tilts toward integrated agrochemical conglomerates with captive binder supply. Tiered specialization separates bio-polymer platform developers from synthetic polymer commodity suppliers. Three archetypes dominate: multinational seed-treatment integrators, bio-based polymer specialists, and regional formulation service providers. Capacity expansion and REACH registration dossier capabilities constitute the primary competitive moves.
Among bio-polymer specialists, DSM-Amulix and Croda International occupy positions aligned with EU Green Deal compliance trajectories. Bayer SeedGrowth exemplifies the integrated archetype through seed-treatment-to-binder pipeline control. These three anchors represent divergent strategic postures on synthetic-to-bio formulation transition timelines.
| Leading Market Players |
|---|
| Centor Europe |
| DSM-Amulix |
| Croda International |
| Bayer SeedGrowth |
| Sekisui Specialty Chemicals America |
| GLOBACHEM |
| Germains Seed Technology |
| Michelman |
| DuPont de Nemours |
| Others |
Value Network & Pricing Analysis
Seed manufacturer procurement concentration in the United States Corn Belt and Brazil's Cerrado locks in contract-based long-term offtake structures, with annual volume commitments traded against technical service bundling and REACH dossier access.
Pricing Analysis
Planting performance guarantees anchor value-based pricing for film-coating binders, with premiums tied to seed flowability metrics in 24-row planter compatibility tests. Three-tier pricing structure across premium bio-polymer grades, standard synthetic formulations, and economy powder binders separates suppliers by EU Green Deal certification status and carbon farming eligibility. Cost compression in synthetic polymer tiers is intensifying because petrochemical feedstock volatility erodes margin predictability for commodity crop segments. Smallholder-oriented powder binder buyers in South Asia exhibit highest price sensitivity, while European seed houses under REACH compliance pressure show lowest sensitivity to bio-polymer premiums.
Supply Chain Analysis
Freight costs for temperature-sensitive liquid bio-polymer formulations constrain distribution radius, favoring regional blending facilities over centralized production. Supply concentrates in the Netherlands for bio-polymer R&D platforms, Germany for integrated seed-treatment-to-binder pipelines, and the United States for high-volume commercial coating operations. Raw material dependencies include modified starch feedstocks, lipid-based delivery compounds, and synthetic polymer resins. Single-source vulnerability around REACH-registered bio-polymer platforms creates supply chain risk as ECHA tightens environmental release thresholds. Distribution runs through direct technical service relationships with seed manufacturers and major agricultural cooperatives, bypassing traditional wholesale markups in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH polymer registration timelines function as a cost-of-compliance barrier, creating durable moats for suppliers with established ECHA dossiers while excluding mid-tier competitors from European market participation.
For Market Incumbents: To counter biological actives compatibility demands from microbial inoculant developers, DSM-Amulix and Croda International should deepen backward integration into modified starch and lipid feedstock supply. Capacity addition in Campinas for Brazil's Cerrado expansion zones secures geographic proximity to Mato Grosso soybean operators scaling film-coated seed purchases. For New Entrants and Emerging Players: Online procurement platforms for standardized liquid binder grades offer the lowest-friction entry path, enabling transparent bio-content certification documentation for sustainability-verified purchasing. India's Punjab and Haryana rice-wheat systems represent the most penetrable geography, with nitrogen-fixing bacterial coating compatibility serving as the specific go-to-market angle as chemical fertilizer subsidies face phased reduction. For Investors and Strategic Acquirers: Distressed-cycle entries favor bio-polymer platform developers with established EU compliance documentation in the Netherlands and Germany, where REACH registration investments have already been sunk. Long-term viability over a multi-year horizon hinges on carbon farming certification scheme alignment. The signal to watch is agronomy cooperative procurement specification shifts toward mandatory third-party bio-content verification in Minnesota and Wisconsin.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polymer Feedstocks | DSM-Amulix secures modified starch supply security against REACH-registered competitor lockouts. |
| Campinas R&D Partnership Expansion | Brazilian biological input developers gain localized formulation support for microbial inoculant compatibility. |
| Carbon Farming Certification Program | Suppliers with ISO-compliant lifecycle assessments capture premium pricing corridors in EU Green Deal compliance markets. |
| Direct Technical Service Deployment | Field engineering presence in Des Moines and Mato Grosso locks in equipment retrofit coordination revenue. |
| Long-Term Supply Agreement Restructuring | Seed manufacturers secure multi-jurisdiction registration synchronization capabilities across EPA FIFRA and EU REACH dossiers. |
Research Methodology
Independent corroboration across seed treatment formulators, agricultural cooperative procurement directors, and polymer R&D scientists underwrites the qualitative findings. Primary interviews with plant managers at commercial coating facilities, technical service leads at bio-polymer suppliers, and regulatory affairs specialists navigating EPA FIFRA submissions combined with secondary validation from ECHA registration databases, USDA planting equipment specifications, and ANVISA residue limit protocols. Bottom-up volume estimates from state-level seed treatment operations triangulated against top-down market sizing from agricultural input trade flows.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type (liquid binders, film coating agents, powder binders), application context (agricultural seeds, horticultural seeds), end-user scale (seed manufacturers, agricultural cooperatives), and regional regulatory cluster (EPA FIFRA, EU REACH, India's Central Insecticides Board). CAGRs derive from equipment replacement cycle timing, bio-polymer performance standard adoption curves, and precision planter fleet expansion patterns in Iowa and Mato Grosso.
The model holds under stable REACH registration timelines and continued EU Green Deal Farm to Fork enforcement; deviation in ECHA aquatic toxicity threshold revisions or ANVISA export residue protocol shifts would alter bio-polymer adoption velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
China Herbicide Market