
 Cameroon Agriculture Market | 2026-2036
Cameroon Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Cameroon Agriculture Market Insights
A capital-intensity divergence between state-backed plantations and lean private operators is redrawing competitive boundaries in Cameroon agriculture. Cameroon Development Corporation (CDC) leverages its integrated palm oil and rubber estates to sustain throughput across coastal processing facilities. Sodecoton anchors cotton ginning capacity in the northern savanna, controlling seed distribution and fiber collection networks that smaller growers cannot replicate. YFarmer competes through digital farm-management platforms that extend advisory services to fragmented smallholders outside formal cooperative structures.
Cameroon agriculture encompasses the cultivation, breeding, and harvesting of crops, livestock, and aquatic organisms across tropical highland and equatorial lowland agro-ecological zones, with cocoa pods requiring 150-180 days from flowering to maturity and robusta coffee thriving at altitudes below 800 meters. Its primary commercial purpose is to supply raw and semi-processed commodities to domestic food processors and international commodity traders. Crops dominates output value through cocoa, coffee, and banana exports, while Livestock remains structurally underdeveloped with fragmented cattle ranching in the Adamawa plateau. Aquaculture is the fastest-growing product type as pond farming of tilapia expands in the West and Northwest regions, though Horticulture captures premium margin pools through year-round vegetable production near urban centers.
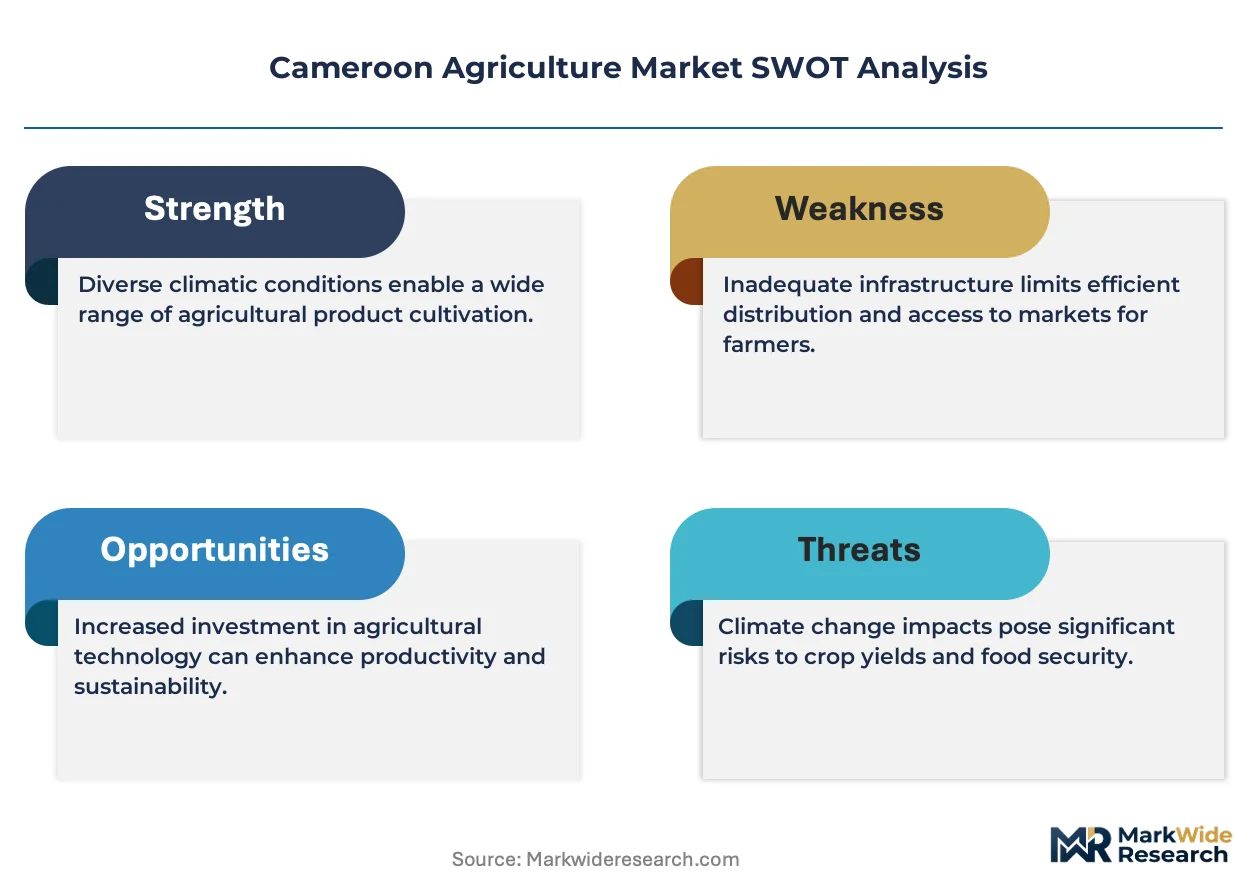
MINADER phytosanitary certification requirements and the National Cocoa and Coffee Board (ONCC) quality grading system shape export market access and price realization for commodity producers. The Central African Economic and Monetary Community (CEMAC) customs union and harmonized standards influence regional trade flows for processed agricultural goods. Stakeholders must monitor how climate adaptation funding and irrigation infrastructure commitments reshape planting decisions across Cameroon's ten agro-ecological zones.
Market Dynamics
MINADER phytosanitary enforcement is compressing export readiness timelines for commodity producers while concentrating compliance capacity among operators with integrated quality infrastructure.
Growth Catalysts
- ONCC quality grading:Certification premiums for Grade 1 cocoa and Arabica coffee beans pull investment into post-harvest processing infrastructure.
- Agro-industrial zone clustering:Processing capacity concentrates around Yaoundé and Douala, creating captive input demand for surrounding smallholders.
- Tilapia pond farming:Aquaculture expansion in the West and Northwest regions diversifies protein supply and reduces import dependency.
Market Restraints
- Fertilizer import dependency:Cameroon lacks domestic nitrogen production, exposing cotton and cereal growers to global urea price volatility.
- Seed distribution concentration:Sodecoton controls certified cotton seed networks in the northern savanna, limiting varietal choice for independent growers.
- Phytosanitary compliance costs:MINADER inspection fees and laboratory testing requirements disproportionately burden operators below fifty-hectare scale.
Strategic Opportunities
- Northwest horticulture corridor:Year-round vegetable production near Bamenda captures premium urban demand with shorter logistics loops than imports.
- CEMAC harmonized standards:Processed food exporters gain single-market access across six member states without duplicate certification.
- Digital advisory convergence:Mobile extension platforms combine weather data with input financing to reach cooperatives outside CDC and Sodecoton networks.
Industry Challenges
- Agronomic technician scarcity:Cocoa rehabilitation and coffee grafting require specialized skills concentrated among aging extension agents.
- Post-harvest infrastructure capex:Fermentation boxes, solar dryers, and storage silos demand upfront investment that fragmented smallholders cannot aggregate.
- Organic certification timelines:Three-year conversion periods for synthetic-input-free cocoa lock producers into conventional pricing during transition.
Report Scope
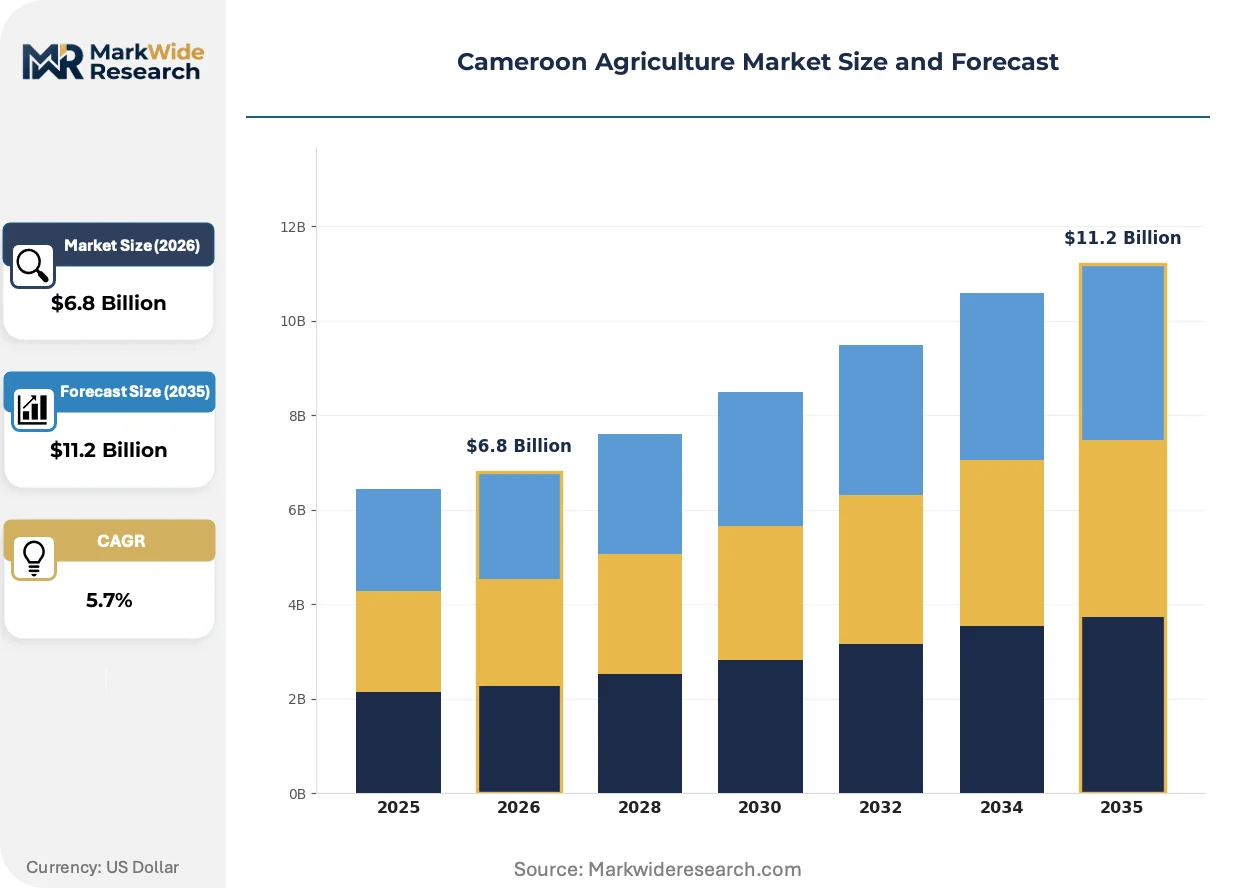
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cameroon Agriculture Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Livestock, Aquaculture, Horticulture End Use Industry: Food Processing, Export, Local Consumption, Biofuel Production Distribution Channel: Direct Sales, Cooperatives, Wholesalers, Retail Outlets Cultivation Technique: Organic Farming, Conventional Farming, Hydroponics, Mixed Methods |
| Companies Covered | Cameroon Development Corporation (CDC), Sodecoton, YFarmer, Ethos SARL, Farms Solution, Crésus Agro, Mboa'gri, ClinicAgro, AIT Group (PFMS), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cameroon Agriculture Market Trends and Innovations
Digital farm-management platforms are redrawing how knowledge and credit reach fragmented smallholders outside formal cooperative structures.
Sensor-based soil monitoring is supplanting visual crop assessment as the dominant input decision tool. Medium-scale operators in the Centre Region are adopting handheld NPK probes at accelerating rates. This technology is compressing fertilizer misapplication rates while enabling variable-rate application that reduces input costs per hectare.
MINADER phytosanitary digitization mandates now require electronic traceability certificates for all cocoa and coffee exports. The policy forces investment in blockchain-enabled tagging systems at cooperative collection points. Exporters to European Union markets face the steepest compliance curves as EUDR deforestation regulations converge with domestic certification requirements.
Food processors are consolidating procurement through direct-origin contracts that bypass traditional auction systems. This channel compression concentrates volume commitments among three to five verified cooperatives per commodity. The Adamawa plateau cattle sector exhibits the most visible disintermediation as abattoirs establish forward contracts with ranchers for specific breed and weight specifications.
Cameroon Agriculture Market Segmentation
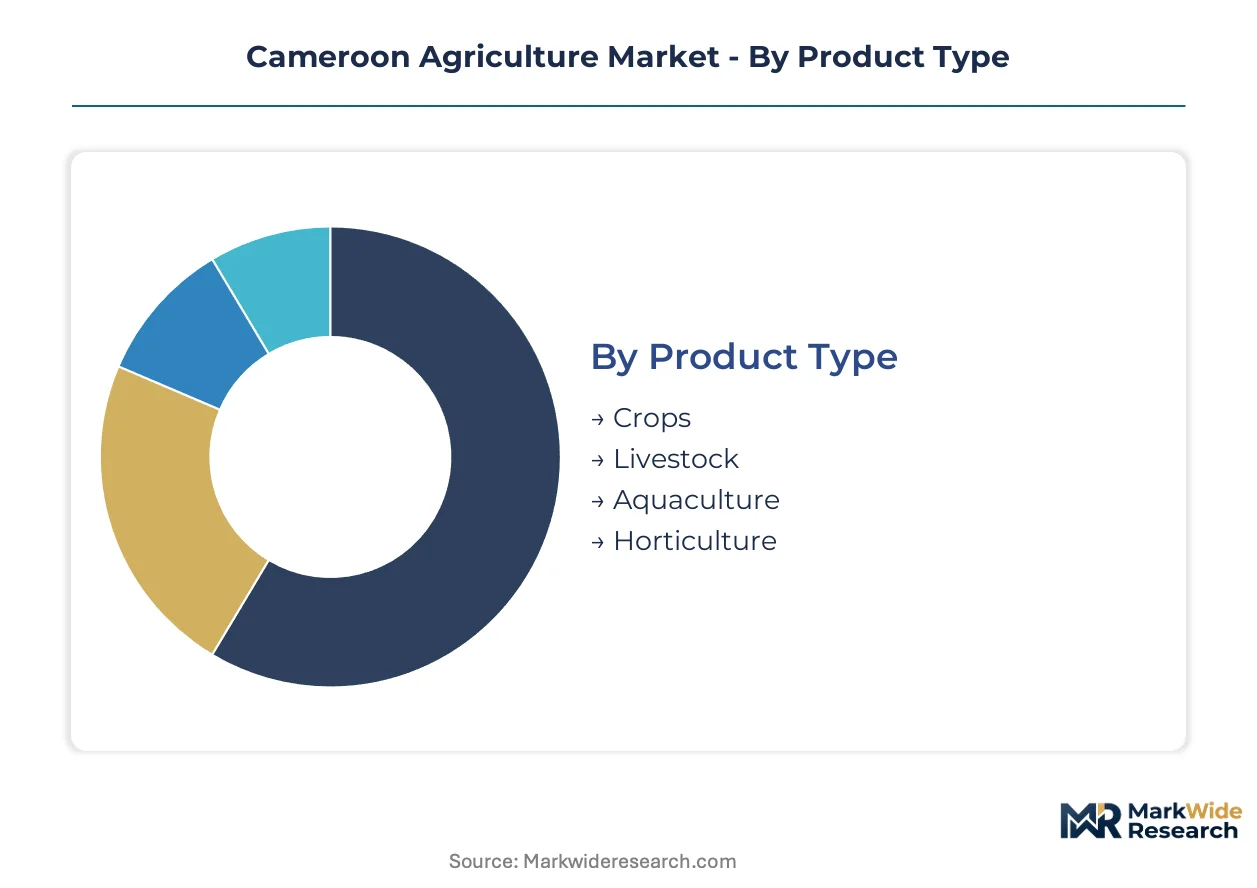
Segmentation in Cameroon agriculture reveals how regulatory frameworks and infrastructure access fragment commercial opportunity across product types and distribution channels. Understanding these divides helps operators align capital deployment with MINADER compliance requirements and regional logistics constraints.
Product Type:
MINADER phytosanitary standards apply differentially across commodity categories, with export-oriented segments facing steeper certification burdens than domestically consumed outputs.
- Crops:Cocoa, coffee, and bananas dominate export revenue through ONCC quality grading protocols. Centre and Littoral region processors concentrate demand for certified beans, pulling investment into post-harvest fermentation and drying infrastructure.
- Aquaculture:Tilapia pond farming in the West and Northwest regions expands fastest as protein import substitution gains policy support. Shorter value chains and lower phytosanitary complexity attract private capital outside CDC and Sodecoton networks.
- Livestock:Fragmented cattle ranching across the Adamawa plateau serves domestic beef demand with limited export penetration.
- Horticulture:Year-round vegetable production near Bamenda and Yaoundé captures premium urban pricing through shortened logistics loops.
Established volume favors Crops; emerging adoption favors Aquaculture.
End Use Industry:
Cost tier differentiation separates commodity flows destined for sophisticated processing infrastructure from those circulating through informal channels.
- Food Processing:Certified cocoa and coffee beans enter agro-industrial zones around Douala and Yaoundé for chocolate and soluble coffee production. ONCC Grade 1 premiums justify traceability investments that smaller operators cannot amortize.
- Export:EUDR deforestation regulations and MINADER electronic traceability mandates converge to raise compliance thresholds for EU-bound consignments. Blockchain-enabled tagging systems now required at cooperative collection points.
- Local Consumption:Informal distribution dominates food staple circulation, bypassing formal quality infrastructure.
- Biofuel Production:Palm oil byproduct streams from CDC estates supply limited domestic biodiesel capacity.
Margin concentration sits with Food Processing; volume scale sits with Export.
Distribution Channel:
Customer type fragmentation determines access to credit, technical assistance, and premium pricing mechanisms across the value chain.
- Cooperatives:Consolidated procurement through verified cooperative structures enables direct-origin contracts with food processors. Three to five cooperatives per commodity now capture volume commitments that bypass traditional auction systems.
- Direct Sales:Adamawa plateau abattoirs establish forward contracts with ranchers for specific breed and weight specifications, compressing intermediary margins.
- Wholesalers:Traditional commodity aggregation persists for uncertified cocoa and domestic horticulture flows.
- Retail Outlets:Urban supermarket channels expand for packaged horticulture with traceability labeling.
Supply concentration favors Cooperatives; disintermediation momentum favors Direct Sales.
Cultivation Technique:
Application context and input access divide adoption patterns across Cameroon's ten agro-ecological zones.
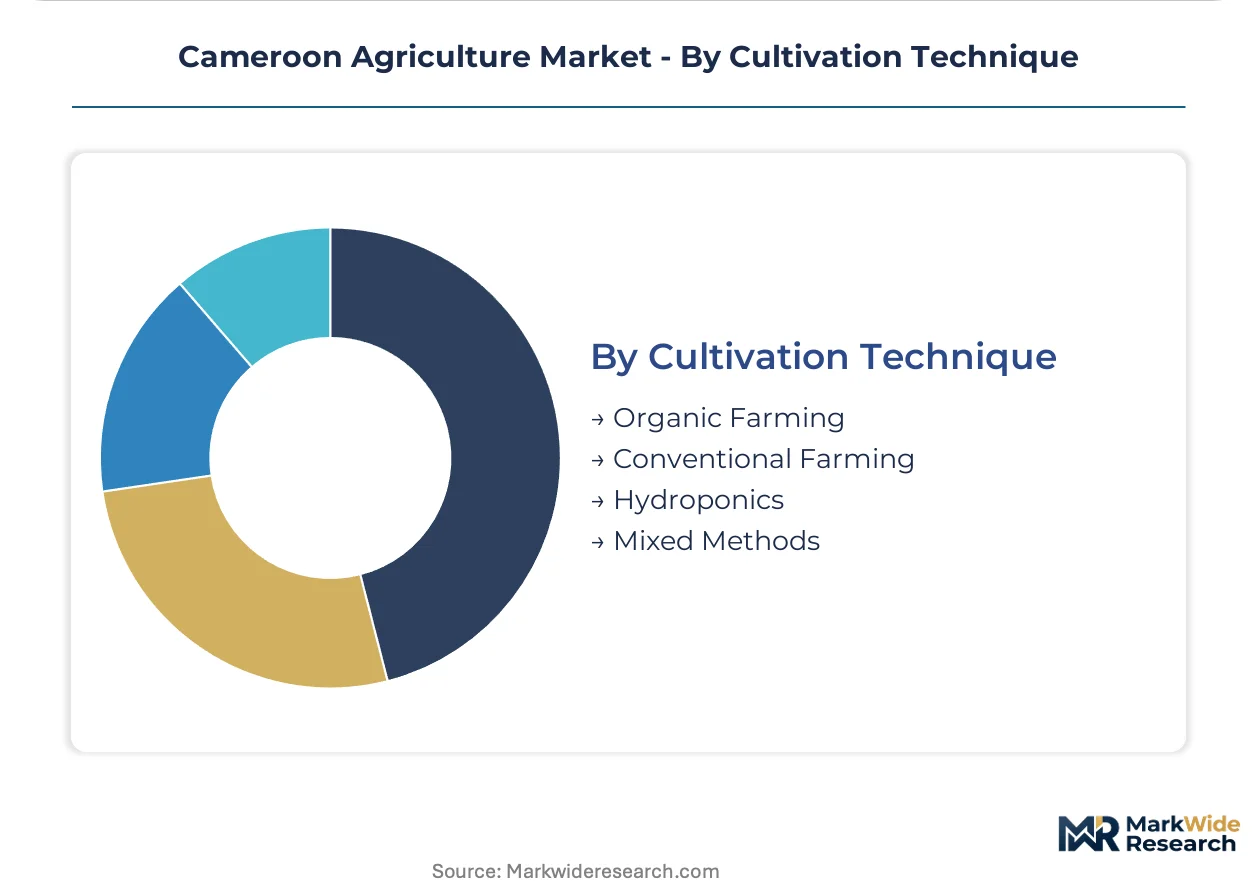
- Conventional Farming:Synthetic input dependence dominates cocoa rehabilitation and cotton production in the northern savanna. Sodecoton's certified seed distribution networks lock growers into established agronomic packages.
- Organic Farming:Three-year conversion timelines for synthetic-input-free cocoa lock producers into conventional pricing during transition, constraining adoption despite European premium demand.
- Mixed Methods:Medium-scale operators in the Centre Region combine sensor-based soil monitoring with targeted fertilizer application to reduce input costs per hectare.
- Hydroponics:Limited to peri-urban horticulture near Douala with high capital requirements and technical skill barriers.
Operational scale favors Conventional Farming; certification premium capture favors Organic Farming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cameroon's agricultural export surplus concentrates in coastal processing corridors, while import dependency for fertilizers and equipment shapes regional production costs. The Centre and Littoral regions anchor agro-industrial capacity, with secondary clusters emerging in the Northwest and West as aquaculture and horticulture expand.
Centre Region
Cocoa fermentation facilities and coffee washing stations cluster around Yaoundé, pulling certified bean volumes from surrounding smallholders. MINADER maintains regional phytosanitary laboratories that enforce export readiness timelines. Sensor-based soil monitoring spreads among medium-scale operators near Mbalmayo, compressing fertilizer misapplication rates.
Littoral Region
Palm oil processing throughput at CDC estates sustains coastal biodiesel and food oil supply chains. Douala's port infrastructure handles the majority of cocoa and coffee export volumes. ONCC grading facilities concentrate here, creating captive demand for Grade 1 certification from upstream cooperatives.
Northwest Region
Year-round vegetable production near Bamenda captures premium urban pricing through shortened logistics loops to Douala and Yaoundé. Tilapia pond farming expands in highland watersheds with lower disease pressure than lowland alternatives. ClinicAgro and digital advisory platforms penetrate this zone outside formal cooperative structures.
West Region
Coffee rehabilitation programs target aging robusta plantations with grafting and shade management techniques. Aquaculture investment flows to private pond operators outside CDC and Sodecoton networks. Crésus Agro and Mboa'gri extend input financing to fragmented growers bypassing traditional credit channels.
Adamawa Plateau
Cattle ranching serves domestic beef demand with limited processing infrastructure for export-grade cuts. Abattoirs establish forward contracts with ranchers for specific breed specifications, compressing intermediary margins. Pasture degradation and veterinary service gaps constrain herd productivity gains.
Cameroon Agriculture Market Competitive Landscape
Concentration sits with state-backed plantation operators and input distribution monopolies. CDC controls integrated palm oil and rubber estates with captive coastal processing capacity. Sodecoton anchors northern cotton ginning and certified seed networks. Private digital platforms and regional cooperatives fragment the advisory and aggregation tiers. Competitive moves center on backward integration into seed genetics and forward contracting to bypass auction systems.
Among Yaoundé and Douala-based operators, Cameroon Development Corporation anchors the integrated plantation archetype with coastal processing assets. Sodecoton occupies the input distribution monopoly position in the northern savanna. YFarmer exemplifies the digital platform vector extending advisory services to smallholders outside formal cooperative structures. Ethos SARL, Farms Solution, and Crésus Agro represent mid-scale private operators competing through direct-origin contracts and localized input financing.
| Leading Market Players |
|---|
| Cameroon Development Corporation (CDC) |
| Sodecoton |
| YFarmer |
| Ethos SARL |
| Farms Solution |
| Crésus Agro |
| Mboa'gri |
| ClinicAgro |
| AIT Group (PFMS) |
| Others |
Pricing and Supply Chain Analysis
MINADER phytosanitary certification gates both supply qualification and price differentiation simultaneously, compressing export readiness timelines while concentrating premium realization among operators with integrated quality infrastructure. The ONCC quality grading system creates a bifurcated pricing environment where Grade 1 cocoa and Arabica beans command substantial premiums over conventional grades, rewarding cooperatives that invest in post-harvest fermentation and drying capacity.
Pricing Analysis
The customization-premium spread separates configured-to-order direct-origin contracts from standard auction-based sales. Pricing stratifies across Grade 1 certified, Grade 2 commercial, and uncertified commodity tiers, with ONCC grading and EUDR traceability requirements driving differentiation. Cost compression in conventional grades is intensifying because food processors consolidate procurement through three to five verified cooperatives per commodity, squeezing intermediary margins. Smallholders outside formal cooperative structures exhibit the highest price sensitivity, while integrated plantation operators with CDC-scale processing assets capture the most pricing power.
Supply Chain Analysis
Inventory lead times stretch from pod flowering through ONCC laboratory certification, creating working capital intensity that fragments supply chain participation. Geographic supply concentration centers on Cameroon's Centre and Littoral regions, with secondary clusters emerging in the Northwest and West. The supply chain draws from imported nitrogen fertilizers, certified cotton seed networks controlled by Sodecoton, and fragmented cattle genetics across the Adamawa plateau. Single-source vulnerability in seed distribution constrains varietal choice for independent growers. Distribution runs through cooperative collection points with blockchain-enabled tagging, bypassing traditional auction systems for processor-direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cameroon agriculture is entering a high-growth disruption phase as MINADER electronic traceability mandates and EUDR deforestation regulations converge, forcing capital deployment into compliance infrastructure that reshapes competitive boundaries.
For Market Incumbents: Compound defensive positioning through backward integration into seed genetics and captive supply of post-harvest processing infrastructure. CDC and Sodecoton should deepen control over coastal palm oil throughput and northern cotton ginning capacity respectively, while investing in blockchain-enabled tagging systems at cooperative collection points to preempt digital platform disintermediation from YFarmer and ClinicAgro. For New Entrants and Emerging Players: Anchor in the Northwest horticulture corridor and West Region aquaculture expansion, where shorter value chains and lower phytosanitary complexity attract private capital outside established plantation networks. Target peri-urban vegetable production near Bamenda and tilapia pond farming in highland watersheds, leveraging digital advisory platforms to extend input financing and weather data to fragmented smallholders bypassing traditional cooperative structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale private operators like Ethos SARL and Crésus Agro that have assembled direct-origin contract relationships but lack integrated processing capacity. Long-term viability over a five-to-ten year horizon hinges on exposure to CEMAC harmonized standards and climate adaptation funding flows. The signal to watch is consolidation momentum among three to five verified cooperatives per commodity as food processors compress procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Genetics | Sodecoton's certified cotton seed monopoly demonstrates how upstream control locks growers into established agronomic packages. |
| Blockchain-Enabled Traceability Deployment | MINADER digitization mandates force investment at cooperative collection points to satisfy EUDR deforestation regulations. |
| Direct-Origin Contract Consolidation | Food processors bypass traditional auction systems by concentrating volume commitments among verified cooperatives. |
| Digital Advisory Platform Expansion | YFarmer and ClinicAgro extend services to smallholders outside CDC and Sodecoton networks, fragmenting the advisory tier. |
| Climate Adaptation Infrastructure Investment | Irrigation commitments across Cameroon's ten agro-ecological zones reshape planting decisions and input demand patterns. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MINADER regulatory filings, ONCC grading protocols, CEMAC customs union documentation, and agro-industrial zone investment disclosures. Primary interviews engaged cooperative managers, CDC plantation operations directors, Sodecoton ginning facility supervisors, digital platform engineers at YFarmer, and food processor procurement leads. Secondary validation drew from customs trade data, phytosanitary certification records, and agricultural input import statistics. Bottom-up volume aggregation across product types and cultivation techniques triangulates against top-down macroeconomic indicators and regional production surveys.
Segmentation dimensions modeled include product type, end-use industry, distribution channel, and cultivation technique across the projection horizon. The analytical framework incorporates agro-ecological zone differentiation, regional infrastructure access, and regulatory compliance tiering. CAGRs derive from historical production trajectories, export volume trends, and investment flow patterns. Industry-specific forecast inputs encompass cocoa pod maturity cycles, coffee grafting rehabilitation timelines, and tilapia pond farming expansion rates.
Decision-makers should treat outputs as directional under assumptions of sustained MINADER enforcement intensity and CEMAC trade integration; material deviation in climate adaptation funding or fertilizer import cost structures would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
United States Compound Feed Market