
 Fatty Amines Market | 2026-2036
Fatty Amines Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Amines Market Analysis
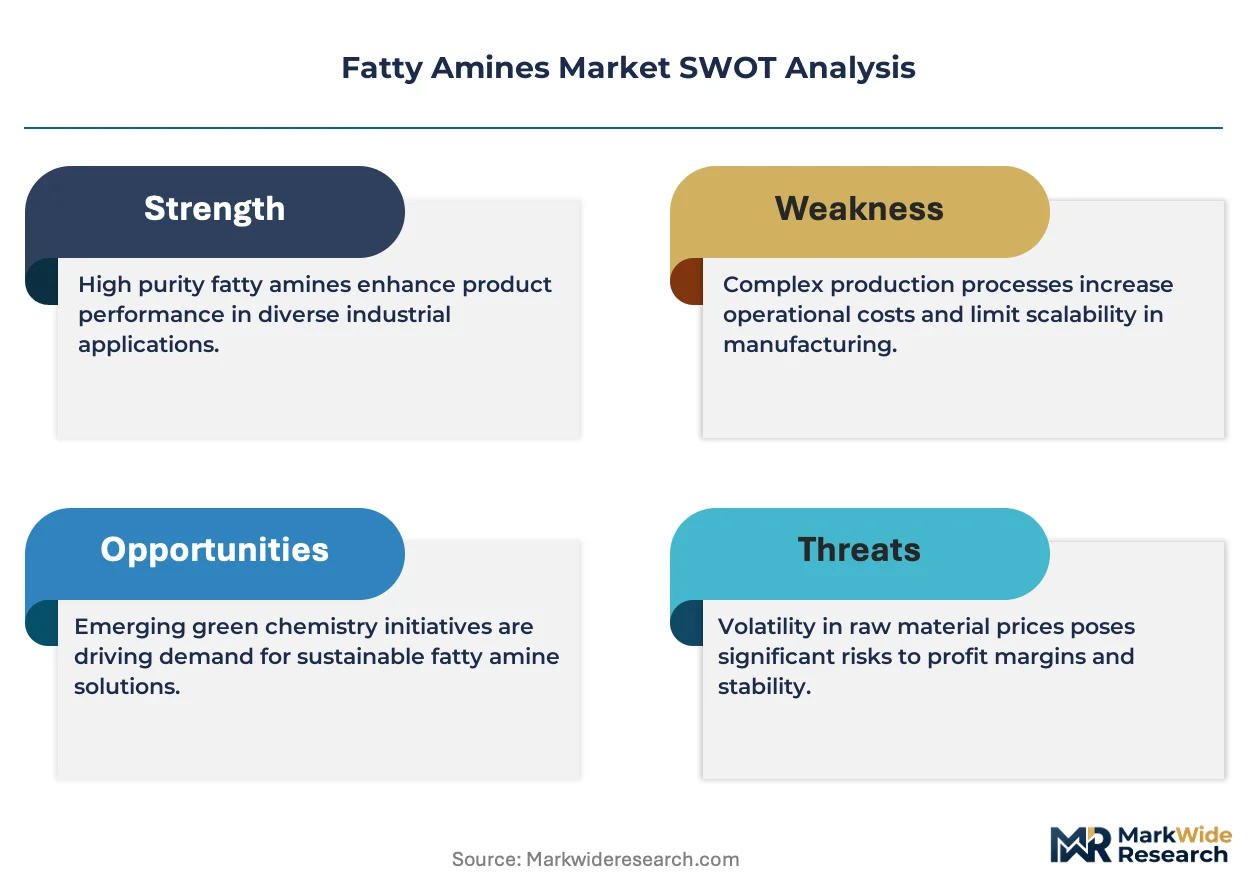
Project finance tied to bio-based feedstock facilities is reconfiguring capital requirements for new entrants in fatty amines production. Nouryon leverages its integrated alkylamine chain to sustain cost discipline across European and Asian operations. Evonik Industries AG anchors its position through R&D intensity in specialty tertiary amines for personal care formulations. Arkema competes via geographic dominance in quaternary ammonium salt production for water treatment markets.
Fatty amines are nitrogen-containing organic compounds derived from natural fats and oils, typically featuring alkyl chains of eight to twenty-two carbon atoms attached to an amino group; manufacturers produce them through ammonia or amine reactions with fatty alcohols or acids, yielding products with cationic surface-active properties essential for adhesion, emulsification, and antimicrobial functions. Primary amines lead volume production due to their role as intermediates for agrochemical and oilfield chemical synthesis, while quaternary ammonium compounds represent the fastest-expanding category as end users reformulate disinfectants and biocides under stricter antimicrobial efficacy standards. Surfactant applications occupy the largest share of value consumption, though corrosion inhibitor demand is concentrating in offshore oil and gas markets where amine-based film-forming chemistry protects subsea infrastructure.
REACH registration requirements in Europe mandate full toxicological dossiers for amine imports, raising compliance costs for non-European suppliers. EPA antimicrobial pesticide regulations in the United States govern quaternary ammonium compound claims, directly shaping product development cycles for biocide manufacturers. China's MEE enforces wastewater discharge limits on amine production facilities, pushing domestic producers toward closed-loop manufacturing. Stakeholders must monitor regulatory divergence between jurisdictions to determine where certification investments yield durable market access advantages.
Market Dynamics
REACH compliance in Europe is compressing supplier margins while simultaneously accelerating consolidation among amine producers capable of funding full toxicological dossiers. This regulatory pressure is redrawing competitive boundaries between integrated majors and import-dependent distributors.
Growth Catalysts
- Quaternary ammonium biocide demand:Water treatment facilities across Asia-Pacific are expanding procurement of cationic disinfectants for municipal and industrial wastewater systems.
- Agrochemical intermediate consumption:China and India together concentrate demand growth for amine-derived herbicide and fungicide precursors.
- Offshore corrosion protection:Amine-based film-forming chemistry is displacing chromate alternatives in subsea oil and gas infrastructure maintenance protocols.
Market Restraints
- Feedstock volatility:Palm kernel and coconut oil price swings directly compress margins for natural-fatty-alcohol-derived amine producers.
- Supply concentration:European alkylamine capacity clusters in the Netherlands and Germany, creating geographic vulnerability to energy cost spikes.
- Substitution pressure:Silane coupling agents are capturing share in glass fiber sizing applications previously dominated by aminosilane chemistry.
Strategic Opportunities
- Bio-based feedstock pivot:Project finance for renewable palm and tallow alternatives is reconfiguring capital requirements for new production facilities.
- Personal care formulation premiumization:Specialty tertiary amines for conditioning and emulsification command price premiums in Southeast Asian cosmetics markets.
- Closed-loop manufacturing:China's MEE wastewater discharge mandates are creating first-mover advantages for domestic producers investing in solvent recovery systems.
Industry Challenges
- REACH dossier compilation:Full toxicological data packages for amine imports demand 18-24 month lead times and seven-figure investment, excluding smaller traders from European market access.
- Process safety expertise:Exothermic amination reactions require specialized chemical engineering talent that concentrates at legacy producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Amines Market |
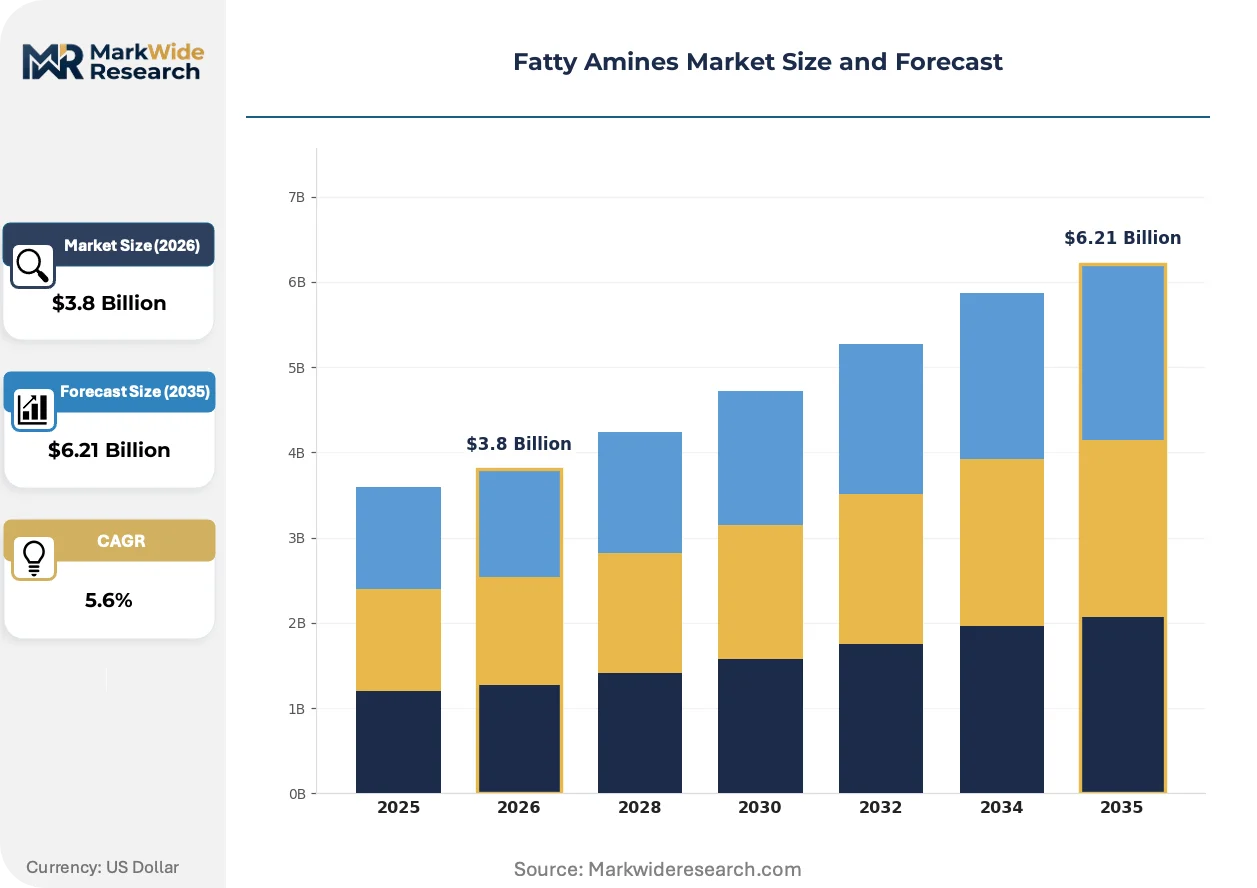
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary, Secondary, Tertiary, Quaternary Application: Surfactants, Corrosion Inhibitors, Emulsifiers, Personal Care End User: Agrochemicals, Oil & Gas, Textiles, Automotive Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Evonik Industries AG, Nouryon, Arkema, Kao Corporation, BASF, Clariant, Huntsman International LLC, Solvay, Global Amines Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Amines Market Emerging Trajectories
Enzymatic catalysis is displacing conventional high-pressure hydrogenation in amine synthesis, cutting energy intensity and enabling smaller-scale distributed production. This technological inflection is compressing minimum efficient scale thresholds.
Continuous-flow reactor technology is rendering obsolete batch-wise fatty amine production. Specialty chemical manufacturers in Germany and Japan are retrofitting pilot plants with microreactor systems. The shift is compressing capital requirements for tertiary amine diversification while tightening purity specifications beyond REACH baselines.
EPA antimicrobial pesticide regulations are hardening efficacy claim substantiation for quaternary ammonium compounds. Biocide manufacturers must now generate standardized kill-curve data against emerging viral pathogens. The rule change is forcing reformulation cycles among surface disinfectant suppliers serving US healthcare and food processing verticals.
Direct procurement from integrated producers is displacing distributor-mediated spot purchasing among large water treatment operators. Municipal utilities in Australia and Saudi Arabia are consolidating annual volume contracts with single-source suppliers. The pattern is compressing spot market liquidity while rewarding producers with captive alkylamine back-integration.
Fatty Amines Market Segmentation
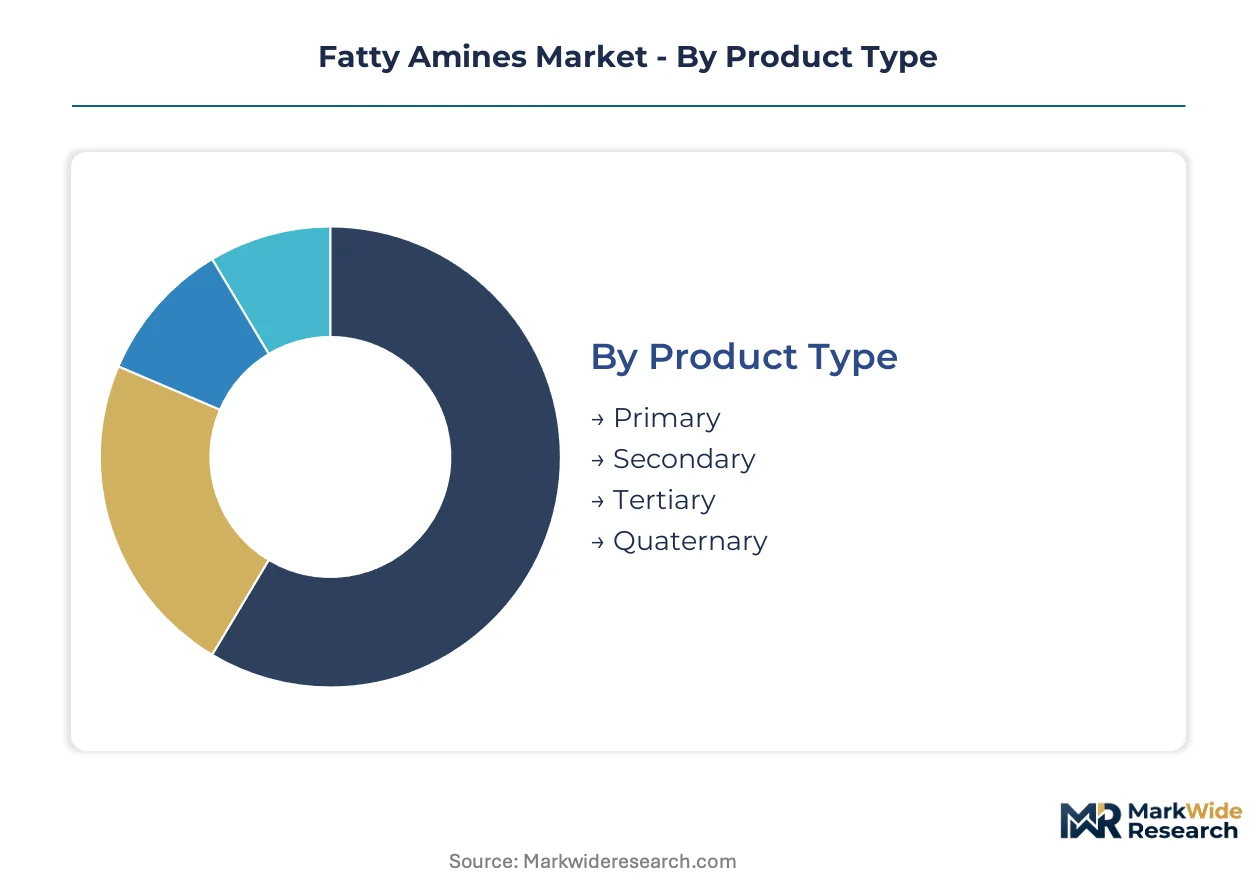
Segmentation in fatty amines reveals distinct technical requirements and margin profiles across product chemistries and end-use verticals. Procurement patterns diverge sharply between commodity intermediates and specialty formulations, reshaping how producers allocate technical service resources.
Product Type:
After-sales intensity escalates from primary through quaternary grades, with specialty amines demanding formulation support and regulatory documentation.
- Primary:Single-alkyl-chain structures with terminal amino groups serve as chemical intermediates for agrochemical and oilfield synthesis. Demand concentrates in China and India where herbicide precursor manufacturing is expanding, though feedstock volatility in palm kernel and coconut oil squeezes producer margins.
- Quaternary:Permanently cationic surfactants with four alkyl substituents deliver antimicrobial efficacy for disinfectant and biocide applications. Water treatment facilities across Asia-Pacific are expanding procurement of these compounds under stricter municipal wastewater standards, with EPA efficacy rules forcing reformulation cycles among US healthcare suppliers.
- Secondary:Dialkylamine structures function as rubber processing chemicals and intermediate feedstocks.
- Tertiary:Trialkylamine configurations provide neutralization and catalysis functions in pharmaceutical and petrochemical processes.
Primary amines hold the largest share; momentum sits with quaternary compounds.
Application:
Cost tiers separate commodity surfactant volumes from premium personal care formulations requiring REACH-compliant documentation.
- Surfactants:Cationic and amphoteric surface-active agents derived from fatty amines enable wetting, foaming, and dispersing functions. Textile softener and industrial cleaning formulations in Southeast Asia absorb the highest volumes, with enzymatic catalysis reducing energy intensity in production.
- Personal Care:Specialty tertiary amines for conditioning, emulsification, and pH adjustment command price premiums in cosmetics markets. Southeast Asian formulators are driving demand for bio-based conditioning agents as consumers reject petrochemical-derived alternatives.
- Corrosion Inhibitors:Film-forming amine chemistry protects metal surfaces in aggressive environments.
- Emulsifiers:Stabilization of oil-water interfaces supports agricultural and industrial formulations.
Surfactants dominate volume consumption; personal care offers the steepest expansion trajectory.
End User:
Customer type determines contract structure, with agrochemical and oilfield buyers consolidating annual volumes while automotive remains fragmented.
- Agrochemicals:Amine-derived precursors for herbicides, fungicides, and plant growth regulators constitute a critical intermediate demand pool. China and India together concentrate growth for glyphosate and fungicide synthesis, with domestic producers investing in closed-loop manufacturing to meet MEE wastewater mandates.
- Oil & Gas:Amine-based corrosion inhibitors and gas sweetening chemicals protect subsea infrastructure and process sour gas. Offshore markets in the North Sea and Gulf of Mexico are displacing chromate alternatives with film-forming amine chemistry.
- Textiles:Softening agents and dye-fixing chemicals leverage cationic amine functionality.
- Automotive:Metalworking fluids and coatings incorporate fatty amine derivatives for lubrication and adhesion.
Agrochemicals anchor volume demand; oil and gas delivers the fastest-growing application segment.
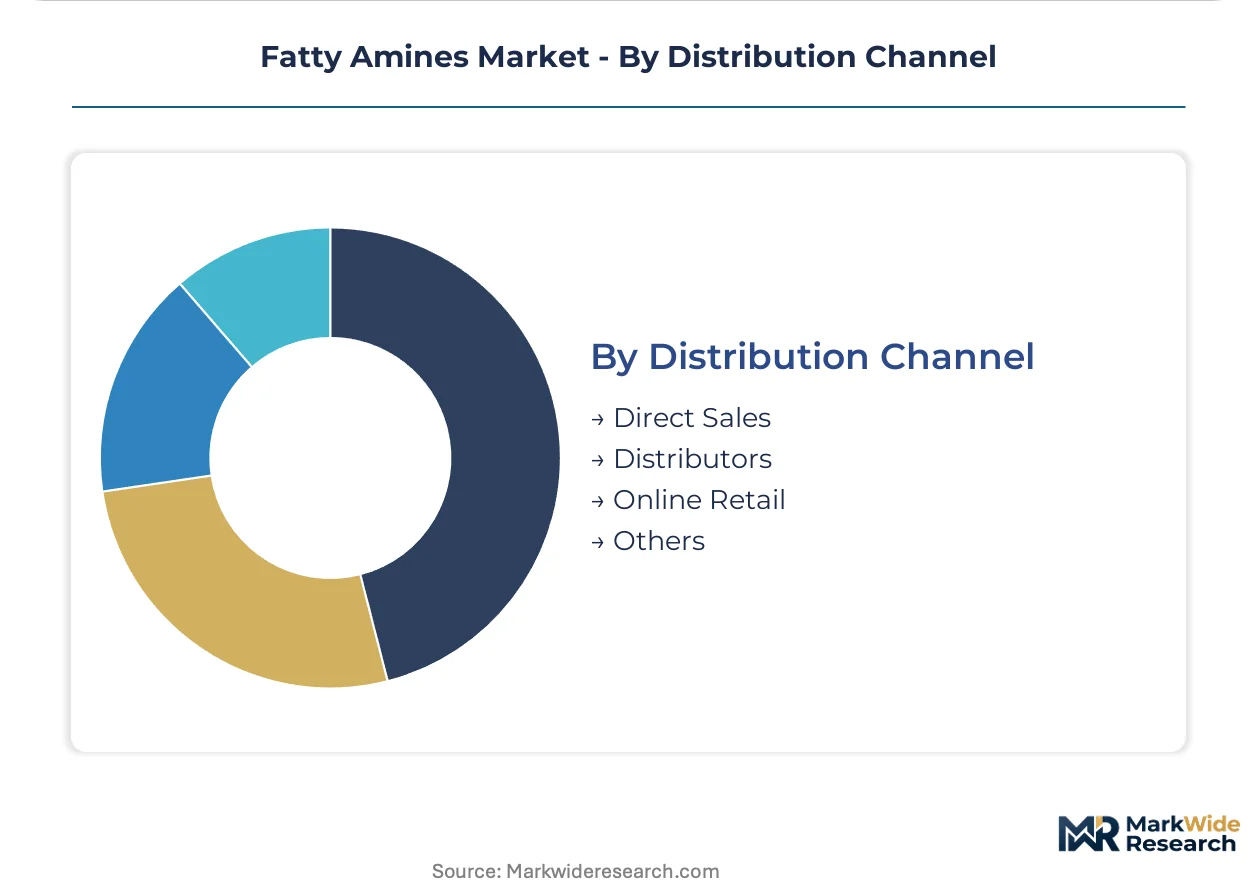
Distribution Channel:
Supply concentration favors direct relationships with integrated producers, compressing distributor margins in bulk commodity grades.
- Direct Sales:Large water treatment operators and agrochemical manufacturers negotiate annual volume contracts with single-source suppliers. Municipal utilities in Australia and Saudi Arabia have consolidated procurement, rewarding producers with captive alkylamine back-integration.
- Distributors:Regional chemical distributors serve mid-sized formulators requiring smaller lot sizes and technical support. European REACH dossier costs are excluding smaller traders from direct import access, concentrating distributor power among compliant specialists.
- Online Retail:E-commerce platforms facilitate spot purchasing for research quantities and specialty grades.
- Others:Agent-mediated sales and cooperative procurement arrangements serve niche applications.
Direct sales capture the largest share; online channels are expanding most quickly for specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for bio-based chemical production are redirecting investment flows across major manufacturing jurisdictions. Domestic procurement preferences in water treatment and agrochemical end-uses are strengthening regional supply chain localization. Regulatory divergence on purity standards and wastewater discharge is fragmenting compliance pathways.
China
Provincial governments in Jiangsu and Zhejiang are subsidizing enzymatic catalysis retrofits for fatty amine producers. MEE wastewater discharge mandates are accelerating closed-loop manufacturing investments. The Yangtze River Delta chemical cluster houses the majority of domestic primary amine capacity serving agrochemical intermediate demand.
Germany
REACH dossier requirements are compressing supplier margins while rewarding integrated producers with full toxicological documentation. The country's national chemical regulator enforces stringent purity specifications for amine-based emulsifiers. The North Rhine-Westphalia industrial corridor maintains concentration in specialty tertiary amine production for personal care formulations.
United States
EPA antimicrobial pesticide regulations are reshaping quaternary ammonium compound development cycles for biocide manufacturers. Municipal utilities in Texas and California are consolidating direct procurement contracts with integrated suppliers. The Gulf Coast petrochemical corridor anchors corrosion inhibitor demand from offshore oil and gas operators.
India
BIS quality certification requirements are tightening import specifications for amine-based surfactants. The country's national chemical regulator is harmonizing standards with REACH frameworks to facilitate export access. Gujarat and Maharashtra industrial zones concentrate domestic primary amine production for herbicide precursor synthesis.
Saudi Arabia
SFDA pharmaceutical-grade chemical standards are elevating purity requirements for amine imports into personal care and healthcare applications. Municipal water treatment operators are expanding cationic biocide procurement under stricter wastewater reuse targets. The Eastern Province industrial cities are attracting alkylamine back-integrated investments to serve regional agrochemical demand.
Fatty Amines Market Vendor Landscape
Channel-controlling players compete with product-specialist players across diverging margin structures in the fatty amines sector. Integrated majors with captive alkylamine supply dominate annual volume contracting with municipal utilities and agrochemical manufacturers. Three archetypes define competitive positioning: backward-integrated petrochemical conglomerates, specialty amine pure-plays, and regional distributors with REACH compliance capabilities. Capacity expansion and portfolio diversification toward bio-based feedstocks represent the dominant competitive moves reshaping facility investment decisions.
Among European-integrated chemical conglomerates, Evonik Industries AG and Nouryon occupy positions exemplifying R&D-intensive specialty amine development. Arkema represents the geographic concentration archetype in quaternary ammonium production. These three companies anchor the competitive structure through differentiated positioning across product chemistry, regional manufacturing presence, and end-market specialization rather than undifferentiated scale competition.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Nouryon |
| Arkema |
| Kao Corporation |
| BASF |
| Clariant |
| Huntsman International LLC |
| Solvay |
| Global Amines Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European alkylamine production is compressing spot market premiums while simultaneously tightening contract discipline among integrated majors, creating divergent pricing power between back-integrated producers and import-dependent distributors.
Pricing Analysis
REACH certification tiers create the primary spread between commodity and specialty grades, with full toxicological dossier documentation commanding substantial premia over basic technical specifications. Three-tier pricing structure across REACH-compliant specialty, industrial-standard, and technical-economy levels stratifies the market, with personal care formulators absorbing the highest premia for tertiary amine purity. Cost compression in technical grades is intensifying because palm kernel oil volatility feeds directly into natural-fatty-alcohol-derived amine margins. Agrochemical intermediate buyers exhibit the sharpest price sensitivity, while personal care formulators prioritize certification compliance over unit cost.
Supply Chain Analysis
Palm kernel and coconut oil feedstock sourcing centers on Southeast Asian plantation networks, with tallow alternatives anchored in North American and European rendering operations. Manufacturing capacity clusters in the Netherlands, Germany, and the Yangtze River Delta, creating geographic vulnerability to energy cost spikes and MEE wastewater enforcement. Single-source vulnerability concentrates in quaternary ammonium biocide precursors, where alkylamine back-integration determines supply security. Distribution runs through direct annual contracts with municipal utilities and agrochemical manufacturers, compressing spot market liquidity and distributor margins in commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic catalysis adoption represents a technological inflection that will disrupt minimum efficient scale thresholds and redistribute competitive advantage toward producers capable of retrofitting distributed production networks.
For Market Incumbents: Harden REACH dossier capabilities to exclude smaller traders from European market access, while accelerating closed-loop manufacturing investments ahead of MEE wastewater mandate expansion. Defensive consolidation around captive alkylamine supply insulates against feedstock volatility, with enzymatic catalysis retrofits compressing energy intensity below legacy hydrogenation benchmarks.
For New Entrants and Emerging Players: Pursue white-space positioning in bio-based feedstock specialty amines for Southeast Asian personal care markets, where consumer rejection of petrochemical-derived alternatives creates formulation partnership opportunities. Target municipal water treatment procurement in Australia and Saudi Arabia through direct annual contracting models, leveraging technical service capabilities to displace distributor-mediated spot purchasing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive alkylamine back-integration and multi-year municipal utility contracts. Long-term viability hinges on certification asset durability and enzymatic catalysis retrofit completion, with acquisition focus on European and Asian specialists possessing full REACH documentation. Monitor EPA antimicrobial efficacy rule implementation as a demand inflection signal for quaternary ammonium biocide volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkylamine Feedstock | Captive supply of ammonia and fatty alcohol precursors insulates margin compression from palm kernel oil volatility. |
| Enzymatic Catalysis Retrofit | Microreactor and enzyme-based synthesis cuts energy intensity below conventional high-pressure hydrogenation benchmarks. |
| REACH Dossier Completion | Full toxicological documentation excludes non-compliant traders and secures durable European market access. |
| Closed-Loop Manufacturing Investment | Solvent recovery systems create first-mover advantage under China's MEE wastewater discharge mandates. |
| Direct Municipal Contracting | Annual volume agreements with water treatment operators compress distributor margins and lock in alkylamine demand. |
Methodological Framework
Cross-validation between executive interviews and customs trade data anchors the qualitative findings in measurable import-export flows. Primary discussions with fatty amine plant managers, agrochemical procurement leads, personal care formulators, and water treatment chemical buyers combined with secondary analysis of ECHA REACH registrations, EPA antimicrobial pesticide filings, and ACC industry reports. Bottom-up capacity modeling triangulates against top-down end-use consumption estimates across surfactant, personal care, and agrochemical applications.
Calibration against historical capacity utilization rates and feedstock price elasticity informs the projection framework across the analysis window. Segmentation dimensions include amine chemistry tier, end-use vertical, geographic production hub, and certification grade. CAGRs derive from supply-demand balance modeling incorporating enzymatic catalysis adoption curves and regulatory enforcement timelines. Forecast inputs integrate palm kernel oil futures volatility and municipal wastewater treatment capital expenditure patterns.
Macroeconomic conditions sit as an overlay; deviation in energy costs, currency exchange rates, or agricultural commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding REACH implementation pace and EPA efficacy rule enforcement. Cross-checking against ECHA registration database updates and MEE inspection disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Formaldehyde Market