
 Global Antifreeze/Coolant Market | 2026-2036
Global Antifreeze/Coolant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antifreeze/Coolant Market Foresight
Asset-light leasing models for chemical blending facilities are narrowing the capital barrier for regional formulators. BASF SE leverages its Ludwigshafen integrated site to sustain backward integration into ethylene oxide precursors. ExxonMobil Corporation anchors its position through control of base stock supply chains across North American refineries. Shell plc differentiates via proprietary additive packages that extend coolant service intervals for heavy-duty commercial transport fleets.
Antifreeze/coolant comprises glycol-based heat transfer fluids—typically ethylene glycol or propylene glycol mixed with corrosion inhibitors, antifoam agents, and pH buffers—engineered to depress freezing points below minus thirty-seven degrees Celsius and elevate boiling points above one hundred six degrees Celsius for internal combustion and electric vehicle thermal management. Ethylene glycol formulations dominate volume due to cost efficiency in passenger vehicles and commercial transport, while propylene glycol and hybrid organic acid technology capture margin pools in construction equipment and agricultural machinery where biodegradability and extended drain intervals command price premiums. Engine coolant applications lead value generation, though industrial refrigeration and power generation segments are expanding as data center cooling and renewable energy storage systems adopt glycol-based thermal regulation.
The EPA regulates coolant disposal under RCRA hazardous waste rules, while REACH restricts borates and certain amine-based corrosion inhibitors in European formulations, forcing reformulation investments. China's MEE enforces GB standards on glycol emissions from blending plants, tightening market access for uncertified imports. Stakeholders must monitor evolving OEM coolant specifications for electric vehicle battery thermal management, as these diverge sharply from traditional internal combustion engine requirements and will determine which additive portfolios retain relevance.
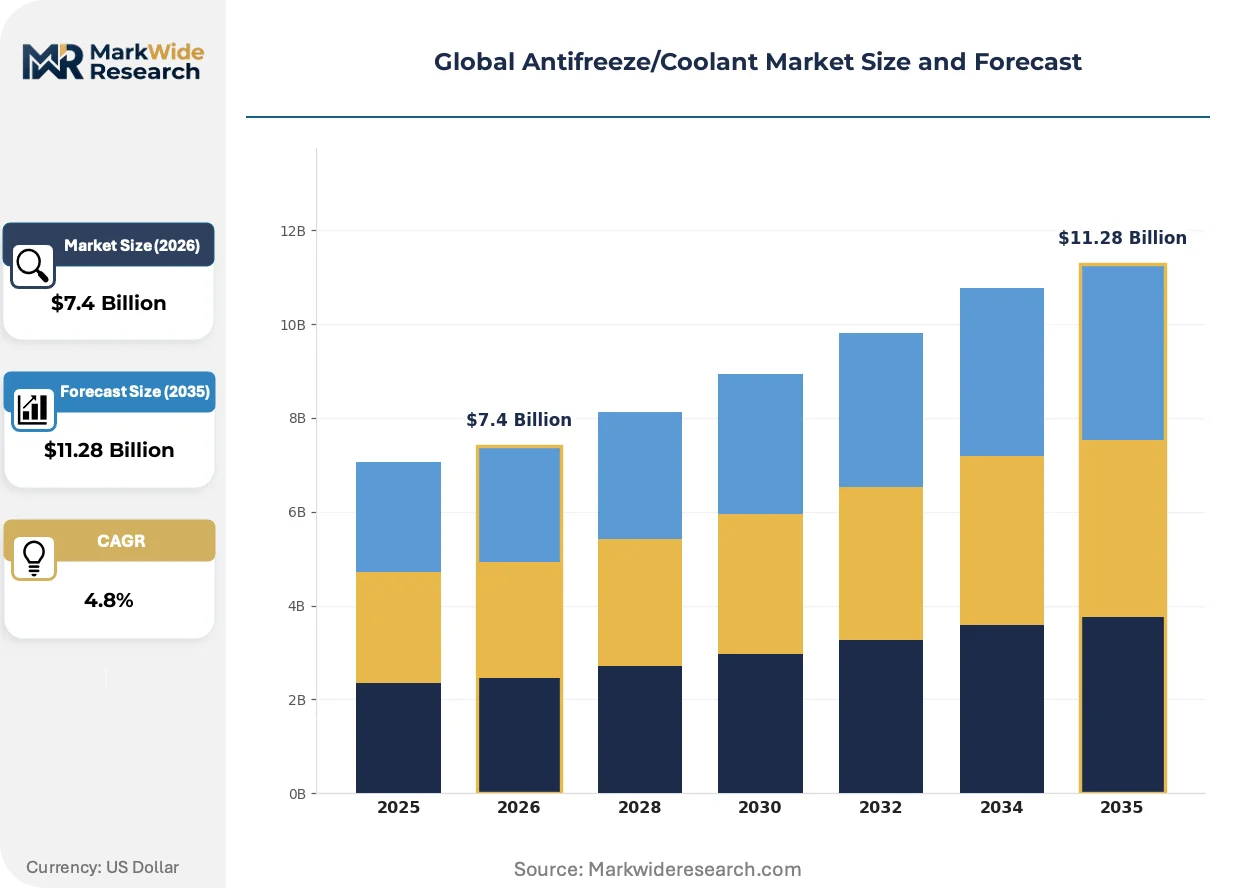
Market Dynamics
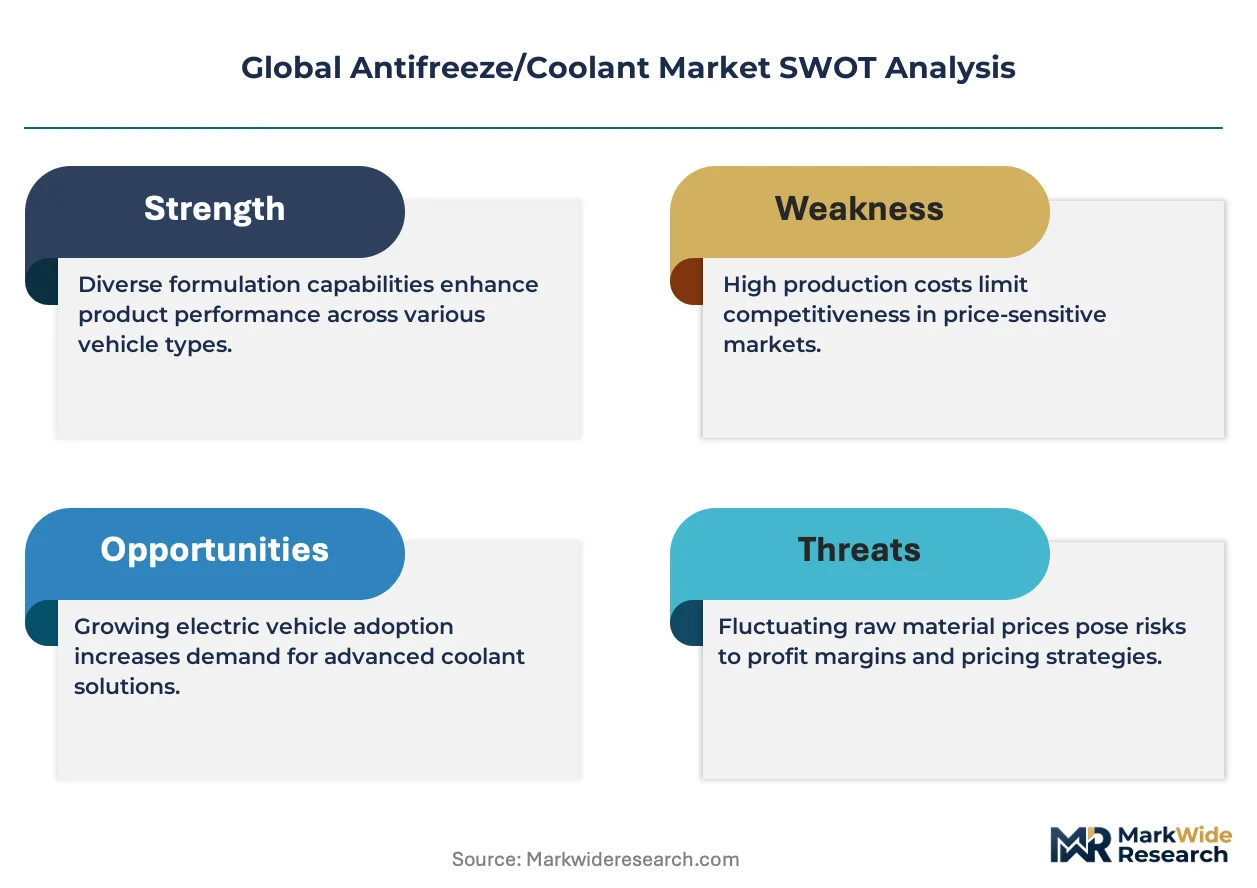
The transition from internal combustion engines to electric vehicle thermal architectures is collapsing traditional coolant specifications and forcing additive suppliers to reformulate corrosion inhibitor packages for battery thermal management systems.
Growth Catalysts
- China's NEV mandate:Domestic production quotas for new energy vehicles are accelerating demand for specialized low-conductivity coolants in battery packs and power electronics.
- REACH boron restrictions:European formulators are replacing borate-based inhibitors with carboxylate alternatives, opening margin pools for hybrid organic acid technology suppliers.
- Data center liquid cooling:Hyperscale operators in the United States are adopting glycol-based immersion and direct-to-chip cooling for AI training clusters.
Market Restraints
- Ethylene oxide feedstock concentration:Gulf Coast petrochemical complexes control over sixty percent of North American ethylene glycol precursor supply, creating geographic vulnerability.
- Propylene glycol cost premium:Bio-based feedstock routes and lower production scale keep propylene glycol formulations priced above ethylene glycol equivalents by thirty to fifty percent.
- Amine corrosion inhibitor phase-out:ECHA restrictions on certain amine compounds are forcing reformulation investments without immediate cost recovery mechanisms.
Strategic Opportunities
- India's commercial vehicle fleet expansion:Heavy-duty truck parc growth and extended drain interval requirements are creating demand for long-life organic acid technology coolants.
- Second-life battery thermal regulation:Stationary energy storage installations require glycol-based temperature management for retired EV battery modules.
- Leased blending infrastructure:Toll manufacturing agreements are lowering capital barriers for regional formulators to serve fragmented agricultural and construction equipment markets.
Industry Challenges
- EV coolant specification divergence:OEM battery thermal management requirements vary by cell chemistry and pack architecture, fragmenting formulation standards.
- Additive package compatibility testing:Validation timelines for new inhibitor combinations against multiple elastomer and metal alloys extend eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antifreeze/Coolant Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Hybrid Organic Acid Technology, Inorganic Acid Technology, Others End User Industry: Passenger Vehicles, Commercial Transport, Construction Equipment, Agricultural Machinery, Marine Vessels Application: Heat Transfer Fluid, Engine Coolant, HVAC Systems, Industrial Refrigeration, Power Generation Packaging Type: Bulk Shipment, Plastic Containers, Metal Drums, Bags, IBC Tanks |
| Companies Covered | BASF SE, ExxonMobil Corporation, Shell plc, Chevron Corporation, Valvoline Inc., TotalEnergies SE, Old World Industries, LLC, Prestone Products Corporation, BP p.l.c., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antifreeze/Coolant Market Shifts & Advancements
Formulation chemistry and thermal management system design are converging as electric vehicle architectures demand coolants that manage battery temperature while maintaining dielectric properties and material compatibility across heterogeneous component sets.
Hybrid organic acid technology is collapsing the service interval gap between passenger car and heavy-duty applications by combining carboxylate inhibitors with silicate stabilizers. Fleet operators in European long-haul transport are adopting these formulations to synchronize maintenance windows with vehicle inspection cycles. The technology is collapsing aftermarket demand for traditional supplemental coolant additives as factory-fill intervals extend beyond six hundred thousand kilometers.
EPA Safer Choice certification is gaining traction among municipal and school bus fleet procurement specifications in the United States. Formulators seeking this designation must eliminate boron, certain amines, and nitrite compounds, driving investment in alternative corrosion inhibition chemistries. Municipal procurement departments in California and New York are prioritizing certified products in RFP scoring matrices.
Direct-to-fleet distribution models are compressing traditional aftermarket channel margins as commercial vehicle operators source coolant in bulk through maintenance contracts. Large logistics operators in Germany are negotiating multi-year supply agreements that bypass regional distributors and jobber networks. This pattern is most visible in temperature-controlled transport segments where fleet standardization reduces inventory complexity.
Global Antifreeze/Coolant Market Segmentation
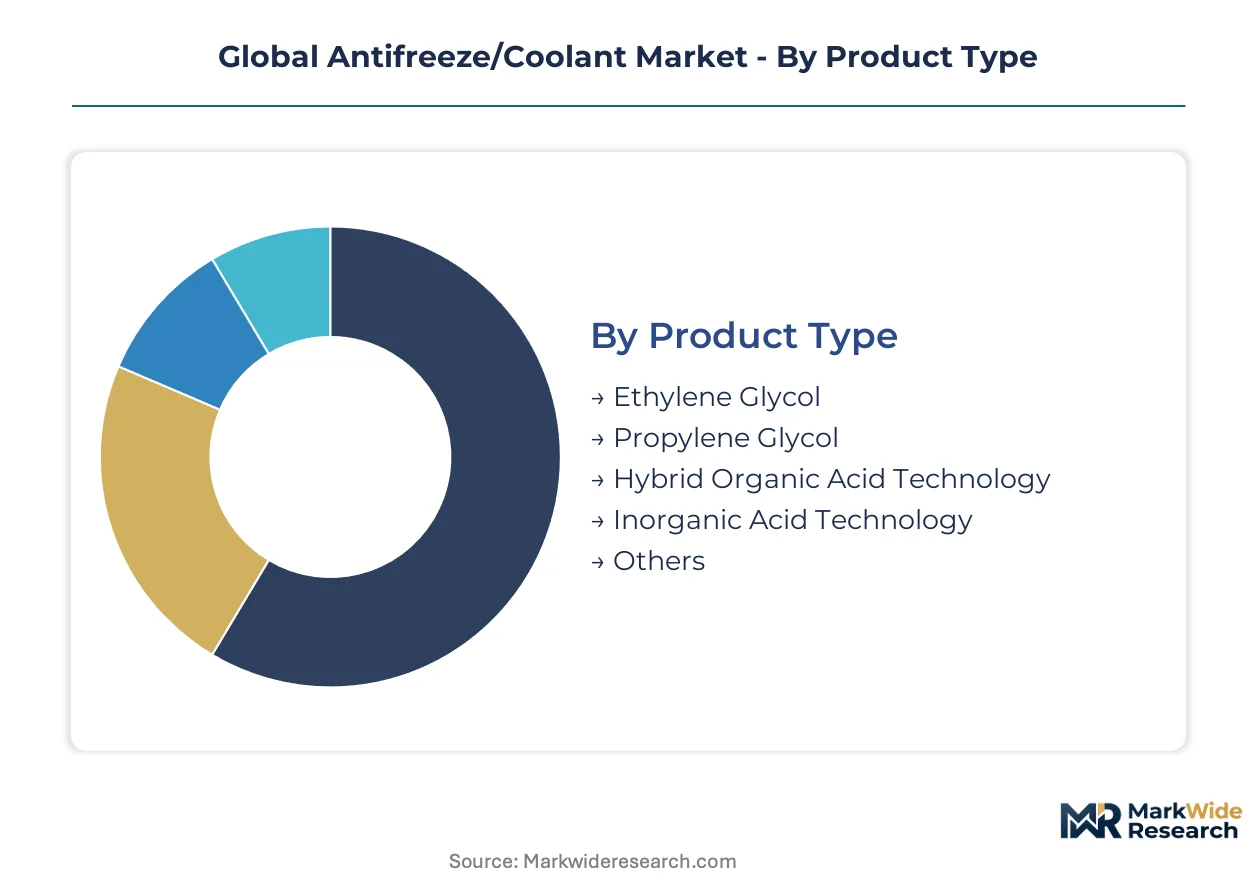
Antifreeze/coolant segmentation reveals divergent chemistry requirements across thermal management applications. Product formulation, end-use specifications, and packaging logistics each create distinct margin pools and competitive barriers for suppliers.
Product Type:
Mature commodity formulations coexist with emerging technology blends as regulatory pressure and electrification reshape inhibitor chemistry.
- Ethylene Glycol:Petroleum-derived base fluid formulated with silicate, phosphate, or hybrid inhibitor packages for cost-sensitive volume applications. Passenger vehicle OEM factory-fill and aftermarket replacement in China, India, and the United States sustain dominant throughput despite toxicity handling requirements.
- Propylene Glycol:Less toxic alternative derived from propylene oxide or bio-based feedstock routes, carrying thirty to fifty percent price premium over ethylene glycol equivalents. Municipal fleet procurement in California and New York under EPA Safer Choice specifications accelerates share gains in school bus and government vehicle segments.
- Hybrid Organic Acid Technology:Carboxylate-silicate inhibitor blends extending service intervals beyond six hundred thousand kilometers for European heavy-duty transport.
- Inorganic Acid Technology:Traditional phosphate-borate-silicate formulations requiring supplemental coolant additive maintenance in legacy commercial fleets.
- Others:Glycerin-based and ionic liquid experimental formulations for specialized aerospace and military thermal management.
Ethylene Glycol handles the majority of throughput; Propylene Glycol is the fastest mover on share.
End User Industry:
Customer type determines formulation complexity, with electrified transport segments demanding dielectric-compatible low-conductivity specifications.
- Passenger Vehicles:Internal combustion engine coolants dominate current volume, though battery electric vehicle thermal management fluids are fragmenting specifications by cell chemistry and pack architecture. Chinese NEV production quotas under MIIT mandates are accelerating specialized coolant qualification timelines.
- Commercial Transport:Long-haul trucking and temperature-controlled logistics fleets in Germany prioritize extended drain interval organic acid technology to synchronize maintenance with inspection cycles. Direct-to-fleet procurement contracts are compressing traditional aftermarket distributor margins.
- Construction Equipment:Biodegradability requirements for groundworks machinery in European Union markets under REACH environmental standards.
- Agricultural Machinery:Seasonal demand patterns and soil contamination sensitivity drive propylene glycol preference in precision farming equipment.
- Marine Vessels:IMO environmental regulations and saltwater corrosion resistance specifications for auxiliary engine cooling.
Passenger Vehicles retains the largest installed base; Commercial Transport is expanding most quickly as fleet standardization reduces inventory complexity.
Application:
Functional use case separates fluid performance requirements across temperature ranges, material compatibility, and thermal conductivity specifications.
- Heat Transfer Fluid:Industrial process cooling and solar thermal systems utilizing inhibited glycol solutions for freeze protection down to minus thirty-seven degrees Celsius. Data center liquid cooling for AI training clusters in United States hyperscale facilities is emerging as a volume driver.
- Engine Coolant:Traditional internal combustion engine thermal regulation combining freezing point depression, boiling point elevation, and multi-metal corrosion protection. This application anchors current formulation chemistry investments and additive package validation timelines.
- HVAC Systems:Geothermal heat pumps and commercial building climate control requiring long-term thermal stability.
- Industrial Refrigeration:Food processing and cold chain logistics with ammonia-glycol secondary loop configurations.
- Power Generation:Wind turbine gearbox cooling and natural gas peaker plant thermal management.
Engine Coolant commands the established revenue base; Heat Transfer Fluid is climbing the fastest as electrification and data center buildouts accelerate.
Packaging Type:
Supply chain configuration determines working capital intensity and geographic reach for formulators of varying scale.
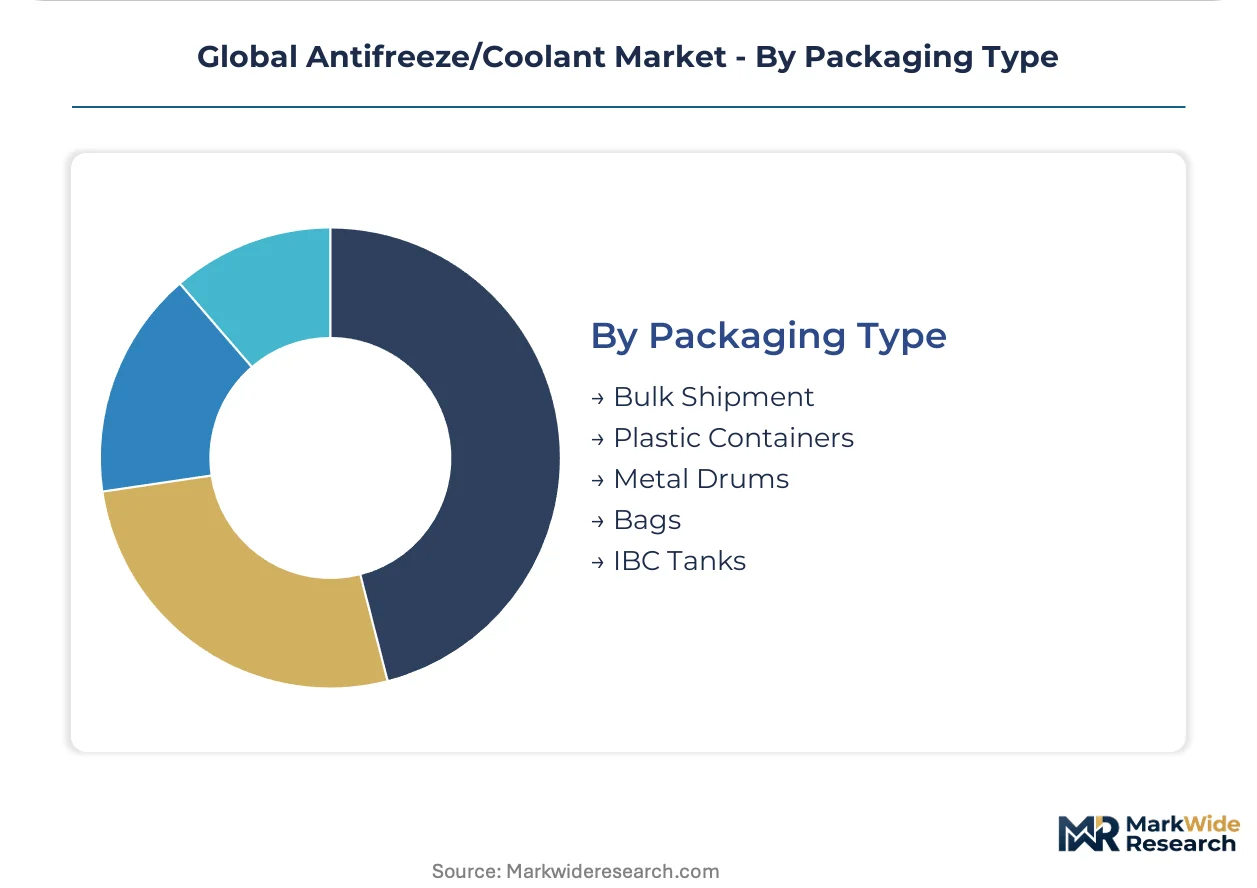
- Bulk Shipment:Tanker truck and railcar delivery to OEM coolant blending facilities, fleet maintenance depots, and toll manufacturing sites. Asset-light leasing models for regional blending infrastructure are narrowing capital barriers for mid-scale formulators serving fragmented markets.
- Plastic Containers:One-liter to twenty-liter retail and professional service packaging for aftermarket replacement and DIY consumers.
- Metal Drums:Two-hundred-liter industrial containers for commercial vehicle service bays and equipment dealers.
- Bags:Flexible intermediate bulk containers for construction and agricultural equipment field service.
- IBC Tanks:Thousand-liter intermediate bulk containers balancing portability with volume efficiency for mid-sized industrial users.
Bulk Shipment moves the greatest volume tonnage; IBC Tanks are gaining share fastest among regional formulators targeting construction and agricultural equipment segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dominance in ethylene glycol feedstock production has inverted traditional import flows, with domestic blending capacity now supplying neighboring markets. Germany and the United States remain formulation technology exporters, though both face pressure from Asian cost structures. India's commercial vehicle fleet expansion is absorbing surplus regional glycol supply.
China
Domestic ethylene glycol production from coal-to-chemical complexes in Ningxia and Inner Mongolia has displaced imports for regional formulators. MIIT production quotas for new energy vehicles mandate specialized low-conductivity coolants, accelerating qualification timelines for battery thermal management fluids. The Yangtze River Delta clustering around Shanghai hosts the largest concentration of NEV coolant blending facilities serving BYD and CATL supply chains.
Germany
Long-haul trucking fleets operating from North Rhine-Westphalia prioritize extended drain interval organic acid technology to synchronize maintenance with inspection cycles. ECHA restrictions on borate and amine-based corrosion inhibitors under REACH Annex XVII are forcing reformulation investments at Ludwigshafen and Leverkusen chemical parks. The Baden-Württemberg automotive corridor drives factory-fill specifications for Mercedes-Benz and Porsche thermal management systems.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are adopting glycol-based immersion cooling for AI training clusters. EPA Safer Choice certification requirements are reshaping municipal fleet procurement in California and New York, favoring propylene glycol formulations. Gulf Coast petrochemical complexes in Texas and Louisiana control the majority of domestic ethylene oxide precursor supply.
India
Heavy-duty truck parc growth along the Delhi-Mumbai Industrial Corridor is creating demand for long-life organic acid technology coolants with extended drain intervals. BIS certification requirements under IS 5759 standards are tightening market access for uncertified imports. The Gujarat chemical belt around Vadodara and Ahmedabad is emerging as a regional blending hub serving construction and agricultural equipment markets.
Japan
Automotive OEMs in the Aichi Prefecture Toyota supply chain are qualifying next-generation coolants for solid-state battery thermal management systems. METI carbon neutrality roadmaps are pressuring formulators to reduce glycol production emissions. The Kanto region around Tokyo-Yokohama maintains specialized formulation capabilities for marine vessel auxiliary cooling systems under IMO environmental regulations.
Global Antifreeze/Coolant Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petrochemical majors with captive ethylene oxide supply and regional toll manufacturers serving fragmented agricultural and construction equipment markets. Three strategic archetypes dominate: backward-integrated global majors controlling precursor supply chains, mid-scale regional blenders leveraging leased infrastructure, and specialty additive houses licensing proprietary inhibitor packages. Competitive intensity centers on M&A activity targeting regional formulators with fleet maintenance contracts and capacity expansion in low-cost glycol production zones.
Among the integrated petrochemical majors, BASF SE exemplifies the backward-integrated archetype through its Ludwigshafen complex operations, while ExxonMobil Corporation anchors the North American supply position through refinery-integrated base stock control. Shell plc occupies a differentiated position via proprietary additive technology for heavy-duty commercial applications. These three represent distinct competitive vectors: manufacturing scale, feedstock security, and formulation specialization.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| Valvoline Inc. |
| TotalEnergies SE |
| Old World Industries, LLC |
| Prestone Products Corporation |
| BP p.l.c. |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta clustering around Shanghai concentrates ethylene glycol blending capacity and transmits pricing power downstream to battery thermal management fluid buyers. Capacity additions at Ningxia coal-to-chemical complexes compress feedstock costs for domestic formulators while import-dependent buyers in Germany and the United States absorb elevated logistics premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers. Price differentiation hinges on certification grade—EPA Safer Choice or REACH Annex XVII compliance—and volume scale commitments from fleet operators. Cost compression in standard-grade ethylene glycol intensifies as Chinese domestic production displaces import volumes. Municipal procurement departments exhibit highest price sensitivity due to budget constraints, while data center operators demonstrate lowest sensitivity given thermal management criticality.
Supply Chain Analysis
Ethylene oxide feedstock production concentrates in China, the United States, and Saudi Arabia, with Gulf Coast petrochemical complexes and Ningxia coal-chemical hubs anchoring global precursor supply. Formulators draw from ethylene oxide, propylene oxide, and bio-based feedstock routes depending on end-use toxicity requirements. Single-source vulnerability persists around specialized additive packages for electric vehicle low-conductivity specifications. Distribution runs through bulk tanker shipments to OEM blending facilities, with regional toll manufacturers serving fragmented agricultural and construction equipment markets via IBC tank configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Antifreeze/Coolant Market sits in early-cycle expansion as electric vehicle thermal management fluid adoption outpaces traditional internal combustion engine replacement rates. Battery pack cooling requirements for new energy vehicle production quotas represent the dominant penetration tailwind.
For Market Incumbents: Harden backward integration into ethylene oxide precursors at Ludwigshafen-scale integrated sites to defend against feedstock cost volatility from Gulf Coast concentration. Prioritize certification investment for EPA Safer Choice and REACH Annex XVII compliance to lock municipal and European fleet procurement channels against emerging regional blenders. For New Entrants and Emerging Players: India's Delhi-Mumbai Industrial Corridor offers underpenetrated white-space for long-life organic acid technology coolants as heavy-duty truck parc expansion outpaces qualified domestic supply. Target second-life battery stationary storage thermal regulation applications through toll manufacturing agreements that bypass capital-intensive blending infrastructure ownership. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors divesting non-core coolant additive portfolios as electrification fragments traditional formulation standards. Five-to-ten-year viability favors specialists with validated battery thermal management fluid qualifications. Monitor OEM coolant specification divergence by cell chemistry as the inflection signal for additive portfolio relevance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF's Ludwigshafen complex demonstrates how captive precursor supply insulates margin against feedstock volatility. |
| EPA Safer Choice Certification | California and New York municipal fleet procurement scoring matrices now require elimination of boron and nitrite compounds. |
| Long-term Supply Agreement with NEV OEMs | CATL and BYD supply chains in the Yangtze River Delta are qualifying specialized low-conductivity coolant formulations. |
| Toll Manufacturing Partnership | Asset-light leasing models for regional blending infrastructure narrow capital barriers for mid-scale formulators. |
| Hybrid Organic Acid Technology R&D | European long-haul fleets adopting carboxylate-silicate blends to synchronize six-hundred-thousand-kilometer drain intervals with inspection cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, and ACC industry reports. Plant managers at ethylene glycol production facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at additive suppliers provided operational validation. Bottom-up volume estimates from regional blending capacity and top-down demand triangulation from vehicle production databases and data center capex disclosures were cross-referenced for convergence.
Forecast inputs include propulsion architecture segmentation, content-per-vehicle thermal management fluid volumes, and regional production cluster capacity utilization across the projection horizon. Grade tier, end-use industry, packaging format, and regional production hub dimensions were modeled separately. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution. Electric vehicle battery pack cooling requirements and REACH regulatory phase-out timelines served as primary demand and supply-side forecast inputs.
Practitioners should monitor ethylene oxide feedstock price volatility, OEM coolant specification divergence by cell chemistry, and REACH Annex XVII amendment proposals for early signals requiring forecast revision. Cross-checking against IHS Markit vehicle production databases and hyperscaler data center cooling capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Global Industrial Separators Market