
 Clinical Grade Disinfectant Market | 2026-2036
Clinical Grade Disinfectant Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Grade Disinfectant Market Analysis
Long-term care facilities is decoupling from historical hospital-centric procurement patterns as post-acute settings face intensified CMS infection control mandates. Ecolab, Inc. anchors North American institutional supply through captive distribution and on-site service integration. Steris PLC specializes in instrument sterilization systems that bundle chemical consumables with capital equipment. 3M Company competes in hand hygiene protocols through persistent antimicrobial formulations and clinical workflow design.
Clinical grade disinfectants are EPA-registered antimicrobial formulations, typically containing quaternary ammonium compounds, hydrogen peroxide, or chlorine derivatives at concentrations proven effective against nosocomial pathogens including C. difficile spores and multidrug-resistant organisms. These chemistries are manufactured under current Good Manufacturing Practice standards with validated kill-claim testing against AOAC or EN methodology before hospital deployment. Alcohol-based surface disinfectants lead hospital formulary adoption due to rapid dry times and broad material compatibility, though hydrogen peroxide chemistries represent the fastest-expanding segment as sporicidal claims become standard for terminal cleaning. Quaternary ammonium compounds occupy the largest volume position in long-term care and outpatient settings where lower-cost daily disinfection dominates procurement budgets.
The EPA regulates disinfectant efficacy claims through its Office of Pesticide Programs, requiring substantiated kill data and emerging pathogen protocol compliance before market authorization. FDA oversight extends to disinfectants classified as medical devices, particularly high-level sterilants used on semi-critical instruments. OSHA's Bloodborne Pathogens Standard mandates appropriate surface disinfection in healthcare worker exposure plans. Stakeholders must monitor pending EPA re-registration reviews for quaternary ammonium chemistries and emerging state-level green procurement mandates that could restrict certain active ingredients in California and New York healthcare systems.
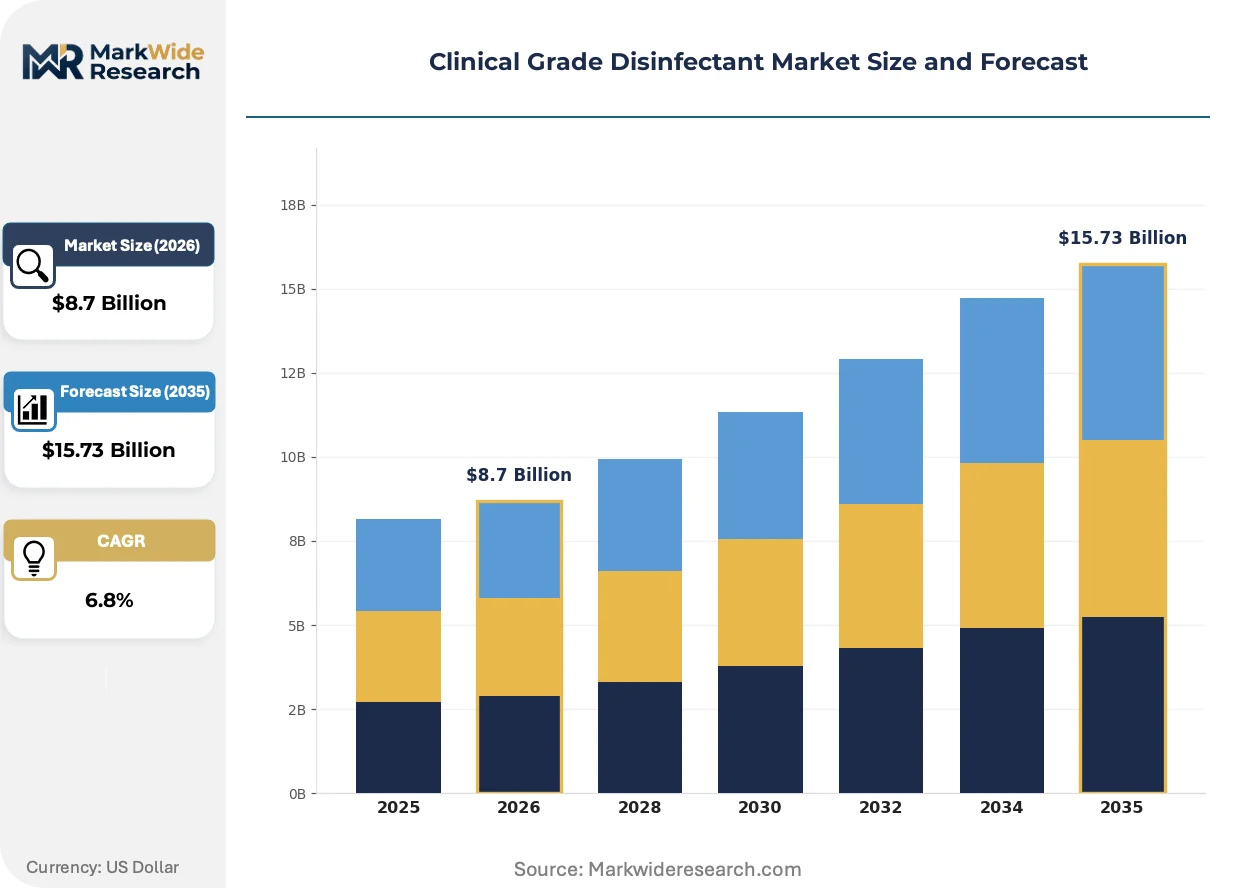
Market Dynamics
Hospital infection control budgets are expanding under intensified CMS mandates for terminal cleaning protocols, while EPA re-registration reviews for quaternary ammonium chemistries are forcing reformulation investments across institutional supply chains.
Growth Catalysts
- CMS Infection Control Mandates:Post-acute care facilities face expanded federal requirements for surface disinfection documentation, driving procurement of sporicidal chemistries in long-term care networks.
- Emerging Viral Pathogen Protocol:EPA's accelerated designation process requires manufacturers to validate kill claims against novel pathogens, creating competitive differentiation for compliant formulations.
- Terminal Cleaning Automation:Robotic disinfection systems in ambulatory surgical centers are bundling chemical consumables with capital equipment, locking in recurring revenue streams.
Market Restraints
- Active Ingredient Supply Concentration:Quaternary ammonium precursor manufacturing clusters in Chinese chemical hubs expose formulators to shipping volatility and tariff exposure.
- Reformulation Cost Burden:EPA re-registration data requirements for legacy chemistries demand toxicology studies costing several million dollars per active ingredient.
- UV-C Disinfection Substitution:Non-chemical terminal cleaning technologies are capturing high-value operating room contracts from hydrogen peroxide vapor systems.
Strategic Opportunities
- Green Procurement Mandates:New York and California healthcare systems are restricting certain quaternary ammonium concentrations, opening demand for peracetic acid and citric acid alternatives.
- Home Healthcare Expansion:Discharge planning protocols are extending clinical-grade surface disinfection into residential settings for immunocompromised patients.
- On-Site Service Integration:Chemical suppliers are embedding technical staff within hospital environmental services departments, converting product sales to subscription-based stewardship contracts.
Industry Challenges
- Validated Kill-Claim Testing Bottlenecks:AOAC and EN methodology laboratories face capacity constraints, extending product launch timelines for sporicidal formulations.
- Legacy Equipment Compatibility:New hydrogen peroxide chemistries corrode aluminum and copper surfaces in older endoscopy suites, requiring capital upgrades before adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Grade Disinfectant Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-based, Chlorine-based, Hydrogen Peroxide, Quaternary Ammonium Compounds End User: Hospitals, Clinics, Long-term Care Facilities, Laboratories Application: Surface Disinfection, Instrument Sterilization, Hand Hygiene, Medical Waste Treatment Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Reckitt Benckiser Group plc, Steris PLC, Ecolab, Inc., S.C. Johnson & Son, Inc., 3M Company, Henry Schein Inc., The Clorox Company, Diversey, Inc., Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Grade Disinfectant Market Emerging Trajectories
Reformulation pressures and automation integration are converging to reshape how clinical disinfectants are specified, purchased, and deployed across healthcare delivery networks.
Hydrogen peroxide-based sporicidal formulations are overtaking legacy quaternary ammonium compounds in hospital formulary reviews. Acute care facilities are adopting these chemistries for terminal cleaning of C. difficile patient rooms. The technology is overtaking alcohol-based protocols in surgical suites where material compatibility concerns previously blocked adoption.
REACH authorization requirements for biocidal active substances are forcing European manufacturers to submit comprehensive dossiers on quaternary ammonium environmental fate. Industrial consequence includes withdrawal of several legacy actives from the EU market. German and French hospital purchasing cooperatives are responding by consolidating procurement around compliant hydrogen peroxide and peracetic acid platforms.
Environmental services departments are consolidating supplier relationships around integrated chemical-plus-service contracts. Group purchasing organizations are displacing traditional distribution intermediaries by negotiating direct manufacturer agreements with embedded technical training. This concentration is most visible in United States multi-hospital systems where standardization across dozens of facilities generates volume leverage.
Clinical Grade Disinfectant Market Segmentation
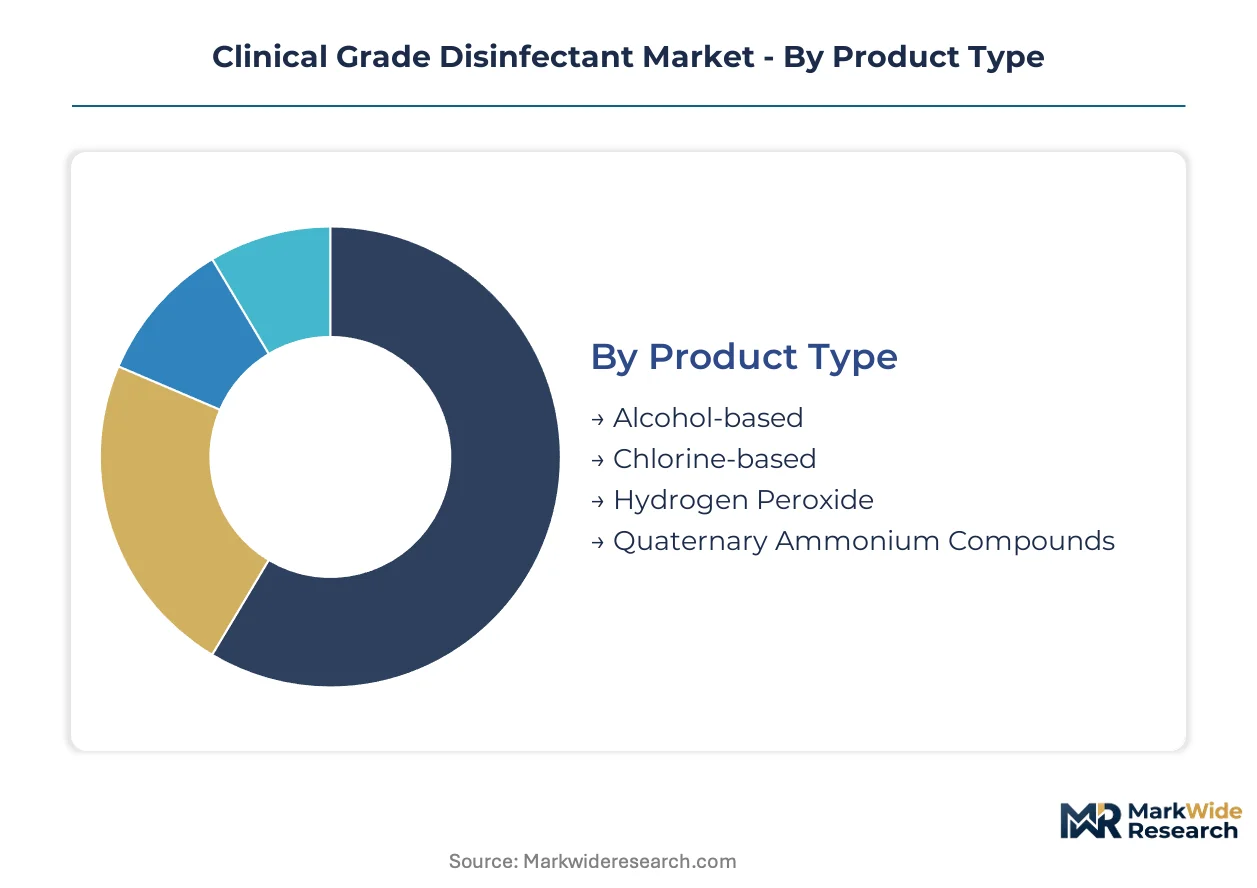
Formulation chemistry determines material compatibility and kill-claim validation requirements across healthcare settings. End-use specialization drives divergent procurement patterns between acute care networks and outpatient facilities. Distribution channel selection reflects capital intensity and service integration demands.
Product Type:
Active ingredient selection governs sporicidal efficacy, surface compatibility, and regulatory re-registration exposure.
- Hydrogen Peroxide:Stabilized aqueous formulations achieve sporicidal claims against C. difficile and Bacillus species without quaternary ammonium environmental persistence concerns. Acute care facilities in the United States are converting terminal cleaning protocols to vapor and spray variants as CMS documentation mandates intensify.
- Quaternary Ammonium Compounds:Cationic surfactant blends dominate daily disinfection volume in long-term care and outpatient settings where cost-per-application drives procurement. EPA re-registration reviews for benzalkonium chloride and didecyl dimethyl ammonium chloride are forcing manufacturers toward shorter-chain homologs with reduced aquatic toxicity profiles.
- Alcohol-based:Ethanol and isopropanol formulations deliver rapid dry times and broad material compatibility for non-porous surface protocols in emergency departments and ambulatory surgical centers.
- Chlorine-based:Sodium hypochlorite solutions retain niche positioning for bloodborne pathogen decontamination in dialysis units and trauma bays despite corrosive effects on stainless steel instruments.
Mature deployment sits with quaternary ammonium compounds. Newer deployment is concentrated in hydrogen peroxide platforms.
End User:
Facility type dictates infection control budget scale, documentation requirements, and capital equipment bundling opportunities.
- Hospitals:Integrated delivery networks command the highest per-bed chemical expenditure as environmental services departments professionalize around terminal cleaning validation. Robotic disinfection system deployments in United States academic medical centers are locking in recurring hydrogen peroxide consumable contracts.
- Long-term Care Facilities:Post-acute settings face expanded CMS infection control mandates for surface disinfection documentation, driving procurement of EPA-registered sporicidal chemistries previously concentrated in acute care. Multi-facility chains are consolidating formulary standards across dozens of properties.
- Clinics:Federally qualified health centers and physician-owned ambulatory surgery centers prioritize rapid-turnover alcohol-based protocols compatible with limited storage infrastructure.
- Laboratories:Biosafety level containment facilities require validated sterilants for biological safety cabinet decontamination and pipette sterilization cycles.
Procurement consolidation is reshaping hospital supply relationships. Long-term care networks are emerging as independent volume aggregators.
Application:
Use case determines contact time requirements, material compatibility constraints, and occupational exposure protocols.
- Surface Disinfection:Environmental services departments specify one-step cleaner-disinfectants for high-touch surfaces in patient rooms and operating suites, with hydrogen peroxide chemistries displacing legacy quaternary ammonium protocols in C. difficile isolation units.
- Instrument Sterilization:High-level disinfection of semi-critical endoscopes and ultrasound probes requires chemistries with validated tuberculocidal and sporicidal claims per FDA medical device guidance, favoring hydrogen peroxide and peracetic acid platforms over aldehyde alternatives.
- Hand Hygiene:Alcohol-based rubs and chlorhexidine gluconate formulations compete for surgical scrub and point-of-care protocols based on persistent antimicrobial residual claims.
- Medical Waste Treatment:On-site chemical treatment systems for sharps and pathological waste employ chlorine-derived or peracetic acid chemistries to achieve state-defined disinfection standards before landfill disposal.
Surface disinfection commands the largest chemical volume. Instrument sterilization carries the highest per-procedure value.
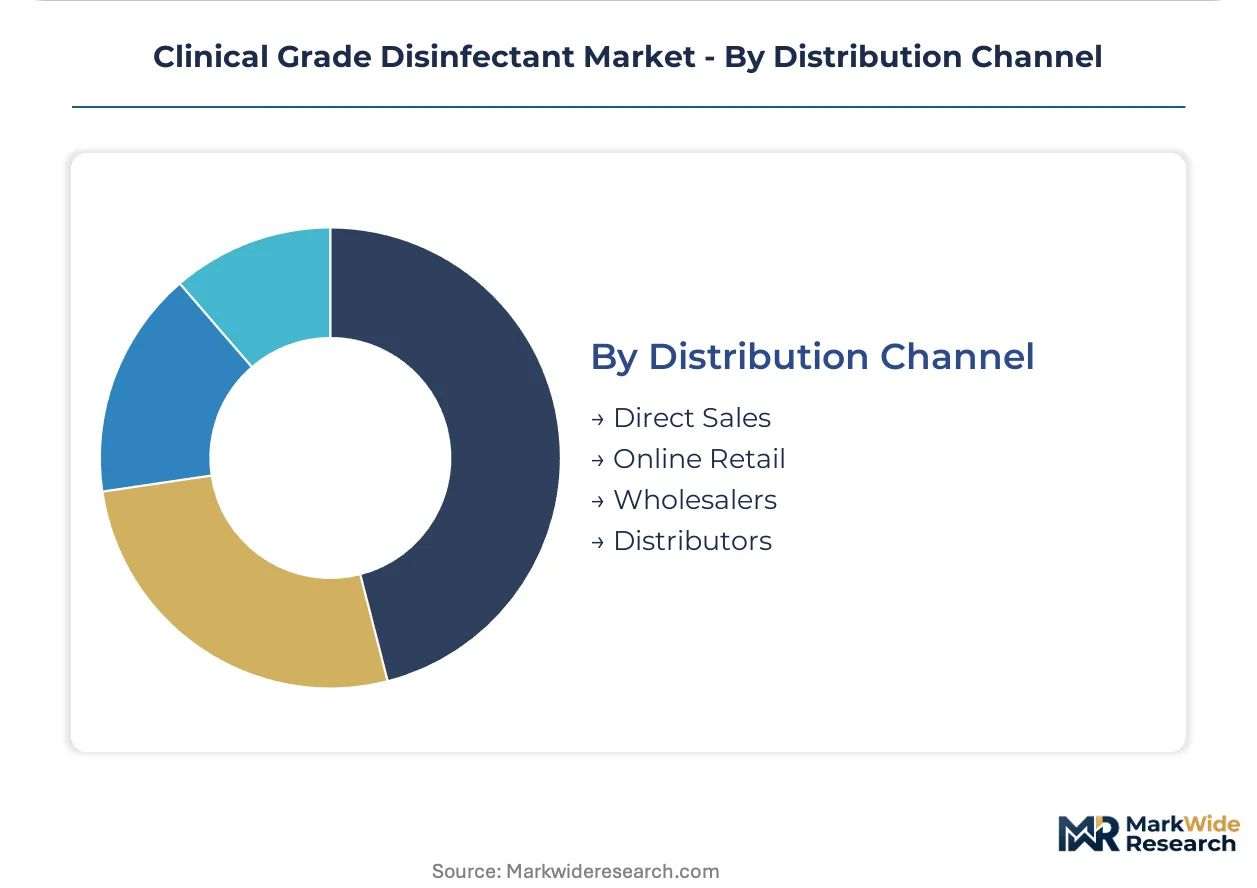
Distribution Channel:
Channel selection reflects technical service requirements, capital equipment bundling, and procurement centralization trends.
- Direct Sales:Manufacturers embed technical service staff within hospital environmental services departments, converting product transactions to subscription-based stewardship contracts with guaranteed compliance documentation.
- Distributors:Regional healthcare supply intermediaries maintain inventory positions for mid-size hospital systems and independent long-term care facilities lacking direct manufacturer negotiation leverage.
- Wholesalers:Broad-line medical-surgical distributors serve outpatient clinics and physician offices with consolidated pharmaceutical and disinfectant procurement.
- Online Retail:E-procurement platforms capture small-volume orders from home healthcare agencies and residential care settings outside institutional supply contracts.
Direct sales relationships dominate hospital system procurement. Distributor intermediaries retain long-term care and clinic volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for chemical manufacturing in China and the United States concentrate active ingredient production for clinical disinfectant formulators.
United States
Academic medical centers in Boston and Houston are deploying robotic hydrogen peroxide vapor systems for terminal cleaning. The EPA's emerging viral pathogen designation protocol requires manufacturers to submit accelerated kill-claim data. Gulf Coast chemical clusters near Houston supply stabilized hydrogen peroxide precursors to domestic formulators.
Germany
Hospital purchasing cooperatives in Baden-Württemberg are consolidating procurement around REACH-compliant hydrogen peroxide platforms. The ECHA biocidal products regulation is forcing withdrawal of legacy quaternary ammonium actives from EU markets. Frankfurt-Rhine-Main chemical manufacturers are expanding peracetic acid production capacity for instrument sterilization applications.
China
Long-term care facility construction in Jiangsu and Zhejiang provinces is driving demand for low-cost daily disinfection chemistries. The National Medical Products Administration is aligning disinfectant registration requirements with international sporicidal testing standards. Yangtze River Delta chemical hubs manufacture benzalkonium chloride precursors for export to Southeast Asian formulators.
Japan
Ambulatory surgical centers in Osaka and Nagoya are adopting alcohol-based protocols for rapid-turnover endoscopy suites. The Ministry of Health, Labour and Welfare's infection control guidelines mandate documented surface disinfection in dialysis facilities. Kanto region distributors are embedding technical service staff within hospital environmental services departments.
India
Multi-specialty hospital chains in Maharashtra and Karnataka are upgrading from quaternary ammonium to hydrogen peroxide terminal cleaning protocols. The Central Drugs Standard Control Organization is harmonizing disinfectant efficacy labeling with FDA medical device guidance. Gujarat pharmaceutical manufacturing zones are backward-integrating into active ingredient synthesis for captive disinfectant production.
Clinical Grade Disinfectant Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional supply chains favoring integrated service-plus-chemical contracts while retail channels reward brand recognition. The vendor base clusters around three strategic archetypes: multinational chemical conglomerates with captive distribution networks, specialized infection control companies bundling equipment with consumables, and diversified consumer goods groups leveraging retail pharmacy relationships. Dominant competitive moves include vertical integration into precursor manufacturing and geographic expansion through distributor acquisitions in emerging hospital markets.
Among diversified industrial suppliers, 3M Company and Ecolab, Inc. represent the integrated service archetype, embedding technical personnel within customer environmental services departments to convert transactional product sales into subscription-based stewardship contracts. Steris PLC exemplifies the equipment-bundling specialist model, positioning instrument sterilization systems as platforms for recurring chemical consumable revenue.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| Steris PLC |
| Ecolab, Inc. |
| S.C. Johnson & Son, Inc. |
| 3M Company |
| Henry Schein Inc. |
| The Clorox Company |
| Diversey, Inc. |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
Captive integration into precursor manufacturing anchors both supply security and pricing power for clinical disinfectant formulators. Ecolab and Steris control hydrogen peroxide stabilization chemistry through proprietary reactor designs, insulating terminal pricing from benzalkonium chloride spot volatility in Yangtze River Delta hubs.
Pricing Analysis
Short lead-time premiums separate emergency stockpiles from contract-scheduled deliveries in hospital system procurement. Three-tier pricing structure across EPA-registered sporicidal, daily-use quaternary ammonium, and economy chlorine derivatives reflects kill-claim validation intensity. Cost compression in the quaternary ammonium tier stems from Chinese precursor oversupply. Long-term care networks exhibit highest price sensitivity; academic medical centers prioritize validated documentation over per-gallon cost.
Supply Chain Analysis
Regional distribution centers in Memphis and Indianapolis operate hub-and-spoke patterns serving multi-hospital systems within 24-hour delivery windows. Active ingredient manufacturing concentrates in China, Germany, and the United States. Stabilized hydrogen peroxide precursors, benzalkonium chloride homologs, and peracetic acid intermediates feed formulation plants. Single-source vulnerability clusters around Jiangsu province quaternary ammonium output. Distribution runs through direct sales teams embedded in environmental services departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
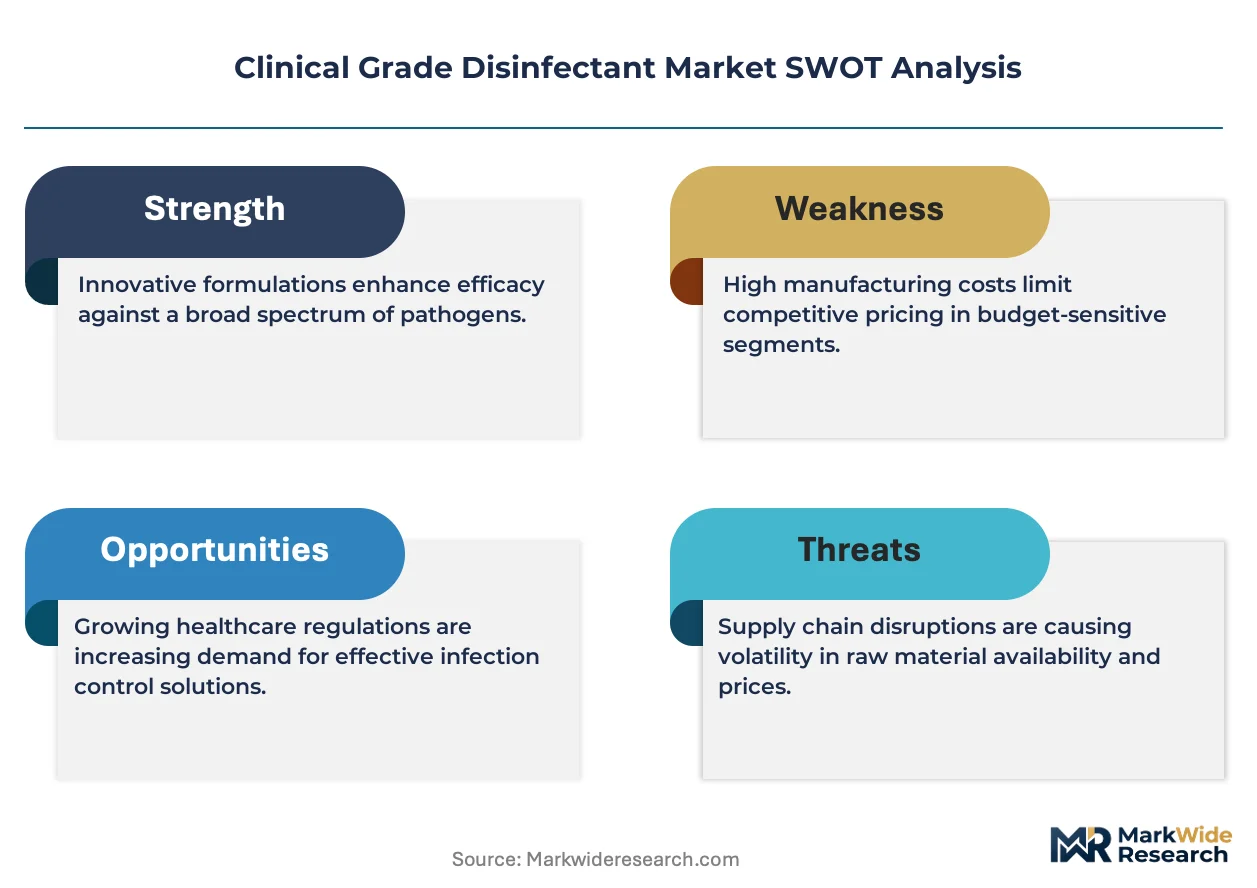
The clinical disinfectant market reads as a cost-of-compliance story where EPA re-registration requirements for legacy quaternary ammonium actives erect barrier-to-entry moats for players with validated toxicology dossiers.
For Market Incumbents: To counter UV-C terminal cleaning substitution in operating room contracts, backward integration into hydrogen peroxide precursor synthesis secures margin control. Expand technical service headcount within IDN environmental services departments to convert transactional sales into multi-year stewardship agreements with guaranteed compliance documentation. For New Entrants and Emerging Players: Launch via home healthcare agency distribution partnerships targeting immunocompromised patient discharge protocols. The residential clinical-grade segment remains penetrable by regional formulators lacking hospital GPO access. White-space concentrates in peracetic acid alternatives for New York and California green procurement mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified chemical conglomerates seeking infection control platform expansion. Long-term viability favors formulators with captive EPA registration expertise and hospital system direct sales infrastructure. Watch EPA re-registration timeline acceleration as the inflection signal for quaternary ammonium market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Acceleration | Validated emerging pathogen claims differentiate hospital formulary positioning against legacy competitors. |
| On-Site Service Embedding | Technical staff integration converts product transactions to recurring subscription revenue with compliance guarantees. |
| Green Chemistry Reformulation | Peracetic acid and citric acid platforms capture procurement share in California and New York healthcare systems. |
| Robotic System Bundling | Hydrogen peroxide vapor consumables lock into capital equipment deployments across ambulatory surgical centers. |
| Home Healthcare Channel Development | Residential clinical-grade protocols extend addressable market beyond institutional supply contracts. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital environmental services directors, GPO contracts managers, EPA registration consultants, and chemical plant operations heads combined with FDA 510(k) databases, EPA Office of Pesticide Programs registration logs, and CMS infection control mandate documentation. Bottom-up facility-level procurement estimates triangulated against top-down chemical consumption models.
Granularity-level modeling deployed formulation chemistry, end-use facility type, application protocol, and distribution channel as core segmentation dimensions. CAGRs derived from weighted regression across historical procurement patterns and projected CMS mandate expansion. Kill-claim validation timelines and EPA re-registration review schedules fed scenario-based forecast adjustments across the projection horizon.
EPA re-registration delays, active ingredient supply disruptions, and UV-C technology cost curves are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on regulatory timeline adherence and hospital capital expenditure continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Warehouse Fumigants Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Aerosol Disinfectants Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market