
 Chemical Reactors Market | 2026-2036
Chemical Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Reactors Market Outlook
ASME Boiler and Pressure Vessel Code certification is rotating competitive positioning among chemical reactor suppliers. Pfaudler Group leverages its glass-lined reactor expertise to dominate pharmaceutical-grade installations across North America. De Dietrich Process Systems sustains European market presence through specialized corrosion-resistant alloy fabrication. Corning Incorporated differentiates via advanced flow reactor technology for continuous processing applications.
Chemical reactors are enclosed process vessels designed to contain controlled reactions at specified temperatures, pressures, and residence times, typically constructed from stainless steel, glass-lined steel, or exotic alloys with wall thicknesses engineered for internal pressures ranging from vacuum to several hundred bar. These systems serve as the foundational unit operation for transforming raw feedstocks into intermediate and finished chemical products across industrial value chains. Continuous stirred tank reactor configurations anchor the largest installed base due to their operational flexibility in polymer production and bulk chemical synthesis. Catalytic process technology leads growth trajectory as refiners and specialty chemical producers retrofit fixed bed reactor systems to accommodate stricter emissions protocols.
FDA cGMP guidelines govern reactor validation protocols for pharmaceutical manufacturing installations in the United States, while REACH and the EU Green Deal mandate material traceability and energy efficiency benchmarks for European process equipment procurement. China's SAMR enforces GB standards for pressure vessel integrity that directly shape import qualification requirements for foreign reactor suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading impact on reactor material sourcing decisions.
Market Dynamics
Continuous flow reactor technology is compressing batch processing economics across pharmaceutical and fine chemical value chains, forcing incumbent vessel fabricators to reengineer product portfolios around modular, skid-mounted architectures.
Growth Catalysts
- EU Green Deal compliance mandates:REACH material traceability requirements are accelerating stainless steel and glass-lined reactor replacements across German specialty chemical clusters.
- Petrochemical expansion in Shandong province:China's refining capacity additions are driving continuous stirred tank reactor procurement for polymer synthesis and bulk chemical production.
- Catalytic process retrofits:Fixed bed reactor system upgrades are proliferating as refiners adapt to stricter emissions protocols in multiple jurisdictions.
Market Restraints
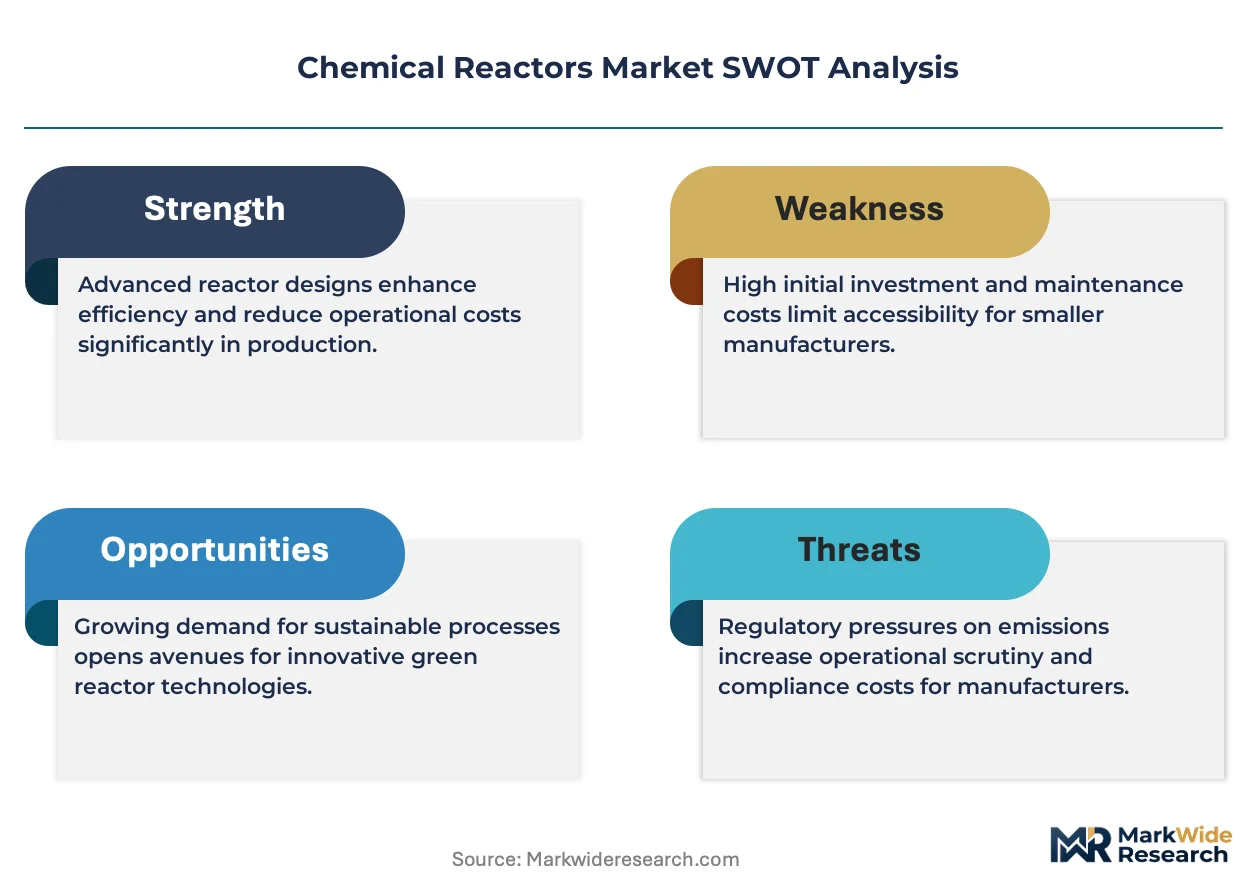
- Nickel and chromium price volatility:Austenitic stainless steel input costs swing unpredictably, squeezing fabrication margins for standard vessel configurations.
- ASME certification concentration:Pressure vessel code authority rests with a limited pool of accredited inspection bodies, creating qualification bottlenecks for new market entrants.
- Glass-lined steel technical ceiling:Thermal shock limitations and pH range constraints prevent deployment in high-temperature catalytic cracking applications.
Strategic Opportunities
- Modular flow chemistry skids:Pharmaceutical manufacturers in India are adopting compact continuous processing units to bypass capital-intensive traditional plant construction.
- Corrosion-resistant alloy fabrication:Hastelloy and titanium reactor demand is rising for aggressive chemistries in fluorinated compound synthesis.
- Carbon border adjustment mechanisms:EU CBAM implementation is creating premium positioning for European-sourced reactor materials with verified low-carbon production footprints.
Industry Challenges
- ASME Section VIII certification timelines:Pressure vessel design review and shop inspection queues extend project delivery schedules by 8-14 months.
- Legacy DCS integration complexity:Modern reactor automation systems require costly retrofitting to communicate with existing distributed control architectures in brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Reactors Market |
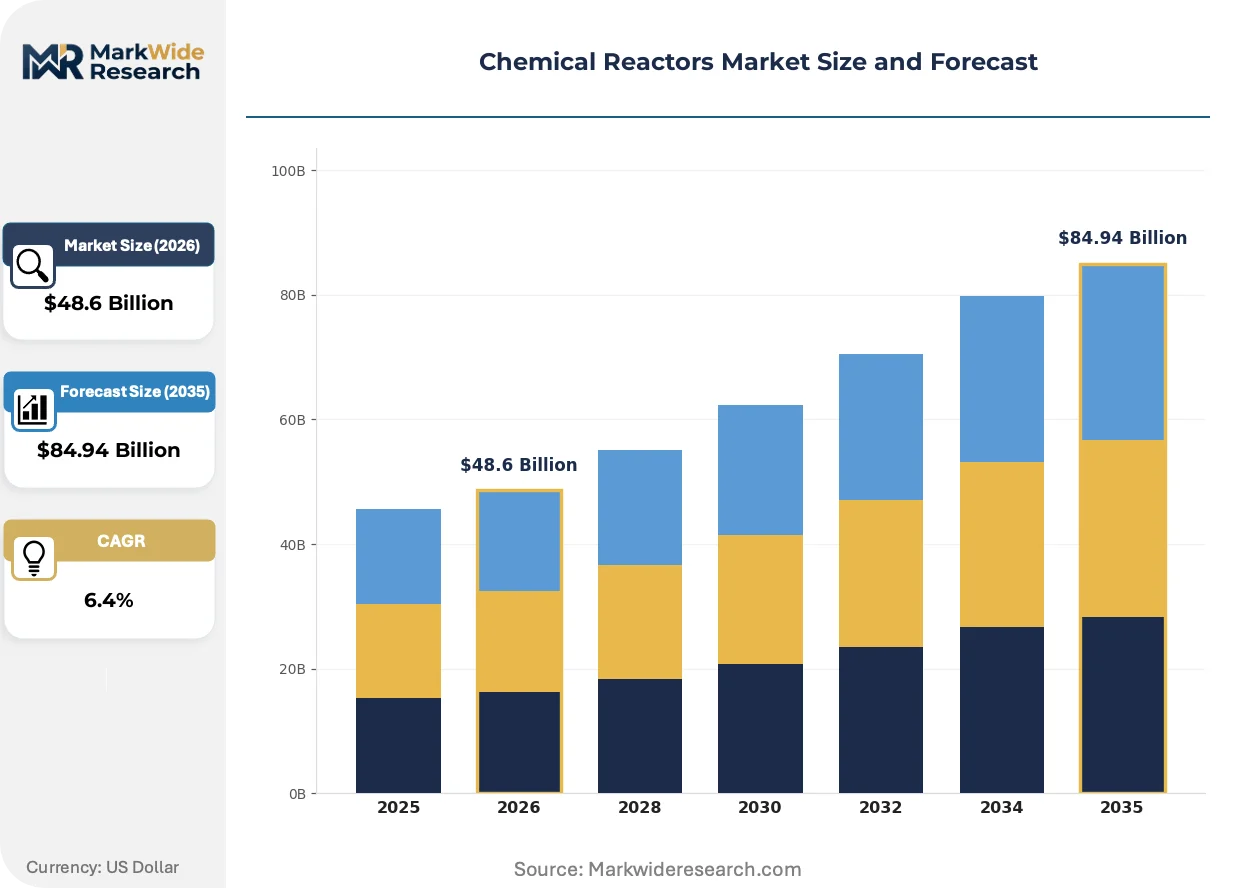
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Stirred Tank Reactor, Batch Reactor, Plug Flow Reactor, Fixed Bed Reactor Application: Chemical Synthesis, Polymer Production, Pharmaceutical Manufacturing, Waste Treatment Technology: Thermal Process, Catalytic Process, Biochemical Process, Electrochemical Process End User: Chemicals Industry, Pharmaceuticals Sector, Food & Beverage Industry, Energy Sector |
| Companies Covered | Amar Equipment Pvt. Ltd., Premex Solutions Group AG, Büchi AG, De Dietrich Process Systems, Pfaudler Group, Parr Instrument Company, Chemglass Life Sciences, Corning Incorporated, Syrris Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Reactors Market Strategic Shifts
Reactor technology trajectories center on intensification, material science advances, and compliance automation that together compress capital cycles and expand operable chemistry windows.
Advanced flow reactor technology is displacing conventional batch vessels in pharmaceutical intermediate manufacturing. Sanofi and Lonza have deployed Corning's Advanced-Flow reactors for nitration and hydrogenation steps. This shift is compressing facility footprints by 70% while enabling reaction conditions impossible in stirred tanks.
REACH substance restriction updates are forcing material substitutions in European reactor procurement. ECHA's candidate list expansions for SVHCs are disqualifying certain gasket and lining compounds. German chemical producers are now specifying perfluoroalkoxy-lined vessels for high-purity applications previously served by PTFE.
Service unbundling is fragmenting traditional reactor supply relationships. End-users in China's Shandong province now separate vessel procurement from installation supervision and commissioning support. Third-party engineering firms are capturing margin pools that integrated suppliers previously controlled.
Chemical Reactors Market Segmentation
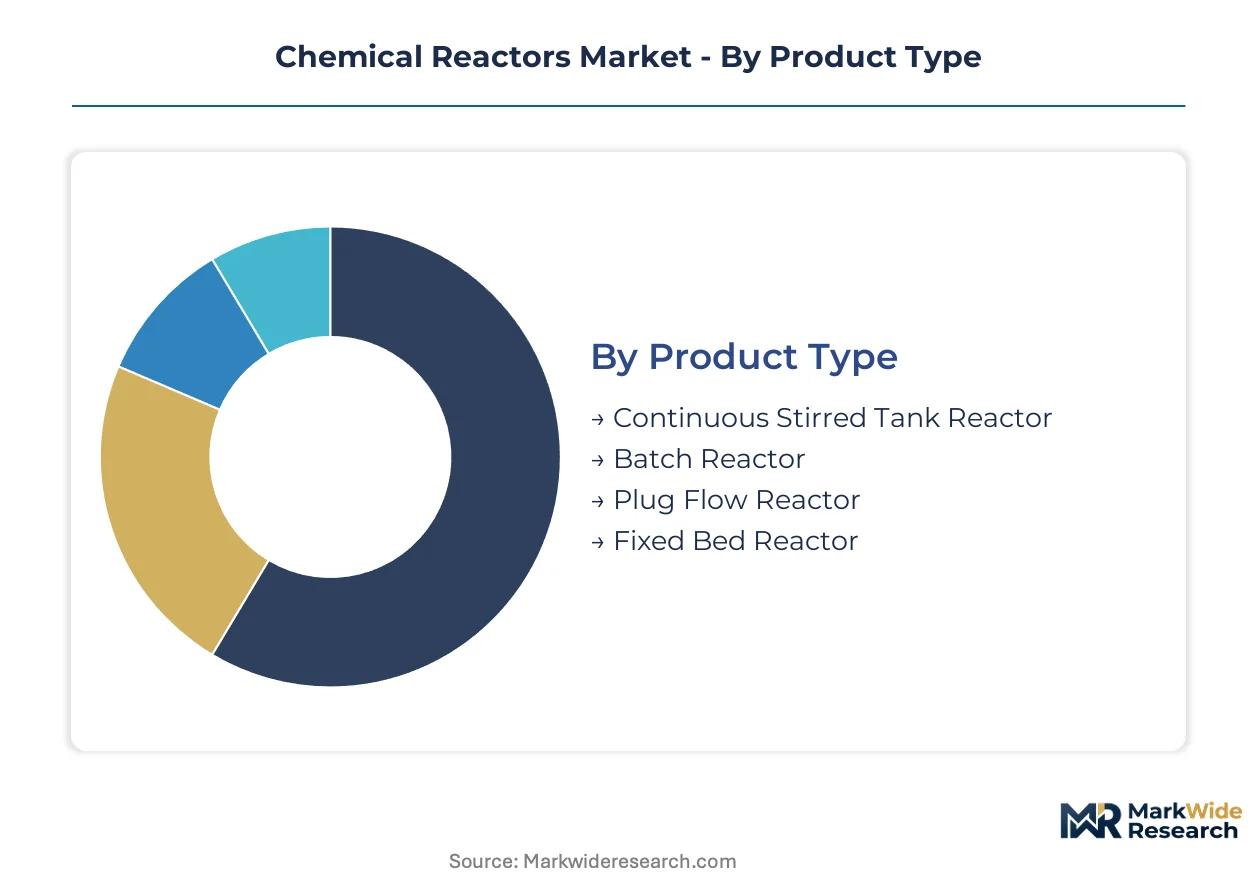
Reactor procurement decisions split across four distinct axes: vessel configuration determines capital intensity and operability range; application chemistry dictates material specifications and regulatory pathway; process technology governs energy efficiency and yield profiles; end-user verticals impose divergent certification requirements and maintenance protocols.
Product Type:
Margin pools concentrate in configurations offering operational flexibility for multi-product campaigns.
- Continuous Stirred Tank Reactor:These vessels maintain uniform composition through mechanical agitation and continuous feed/withdrawal, enabling steady-state operation ideal for polymerization kinetics. Demand clusters in China's Shandong province where petrochemical expansions require scalable bulk chemical production with rapid product changeover capability.
- Batch Reactor:Discrete charge-and-discharge operation supports campaign-based manufacturing of high-value specialty chemicals with traceable lot integrity. Pharmaceutical manufacturers in Germany favor these units for API synthesis under FDA cGMP and EMA validation protocols where batch records must demonstrate complete process control.
- Plug Flow Reactor:Tubular configurations achieve high conversion per unit volume for fast reactions with minimal back-mixing, common in oxidation and chlorination chemistries.
- Fixed Bed Reactor:Packed catalyst beds dominate refinery hydroprocessing and syngas conversion where solid-fluid contact efficiency determines throughput economics.
The dominant share belongs to Continuous Stirred Tank Reactor installations, while Plug Flow Reactor configurations are gaining share fastest in continuous processing retrofits.
Application:
Application segmentation tracks where reactor utilization rates and replacement cycles generate recurring revenue.
- Chemical Synthesis:Intermediate and fine chemical production demands corrosion-resistant alloys and precise temperature control across exothermic reaction profiles. Specialty chemical producers in Germany are expanding procurement for complex multi-step syntheses under REACH substance restriction compliance.
- Polymer Production:Bulk polymerization requires precise control of molecular weight distribution through residence time management and heat removal systems. China's expanding PTA and polyester capacity drives stirred tank reactor demand for step-growth polymerization at scale.
- Pharmaceutical Manufacturing:API and intermediate synthesis under FDA cGMP mandates validated cleaning protocols and material traceability for product contact surfaces.
- Waste Treatment:Advanced oxidation and neutralization processes deploy specialized reactor geometries for hazardous effluent destruction.
Chemical Synthesis commands the largest installed base, though Pharmaceutical Manufacturing is expanding most quickly as continuous flow technology penetrates validated production environments.
Technology:
Technology choice determines energy intensity and catalyst consumption economics.
- Thermal Process:Direct heat transfer through jacketed vessels or internal coils supports non-catalytic reactions where temperature is the primary conversion lever. High-temperature applications in petrochemical cracking favor refractory-lined steel construction.
- Catalytic Process:Heterogeneous and homogeneous catalyst systems accelerate reaction rates while improving selectivity toward desired products. Refiners across multiple jurisdictions are retrofitting fixed bed and fluidized bed systems to meet stricter emissions protocols.
- Biochemical Process:Fermentation and enzymatic conversion operate at mild conditions with living catalysts requiring sterile operation and precise pH control.
- Electrochemical Process:Direct electron transfer enables oxidation and reduction without stoichiometric reagent consumption, gaining traction in chlorine and specialty chemical production.
Catalytic Process technology anchors the largest revenue pool, while Electrochemical Process methods are climbing the fastest as electrification decarbonizes chemical production.
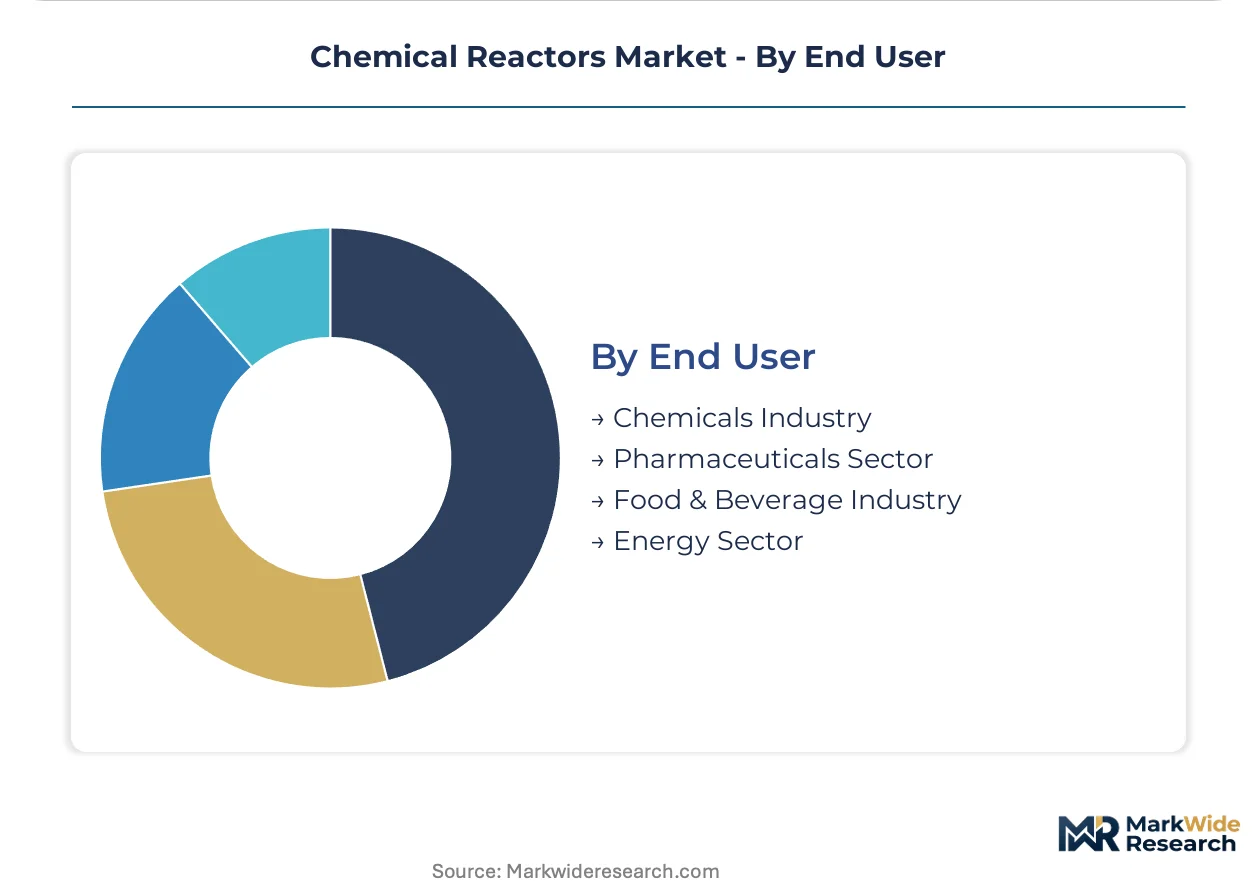
End User:
End-user segmentation reveals divergent procurement authority structures and lifecycle service expectations.
- Chemicals Industry:Commodity and specialty chemical producers prioritize throughput reliability and materials compatibility for aggressive process chemistries. Corrosion-resistant alloy fabrication from Hastelloy and titanium suppliers is rising for fluorinated compound synthesis campaigns.
- Pharmaceuticals Sector:Drug manufacturers demand documented compliance with FDA cGMP, EMA, and national pharmaceutical regulator standards across validation, change control, and batch release protocols.
- Food & Beverage Industry:Edible oil hydrogenation and ingredient processing requires food-grade surface finishes and allergen management procedures.
- Energy Sector:Biofuel refineries and power-to-chemical installations employ reactors for syngas conditioning and synthetic fuel synthesis.
The Chemicals Industry retains dominant procurement volume, though the Pharmaceuticals Sector is capturing margin expansion fastest through premium pricing for validated, inspection-ready systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority clusters with specialty chemical producers in Germany, petrochemical refiners in China's Shandong province, and pharmaceutical manufacturers on the US East Coast. Each geography imposes distinct certification regimes and material specifications that reshape supplier qualification requirements.
United States
FDA cGMP validation protocols govern pharmaceutical reactor installations across New Jersey and Massachusetts manufacturing corridors. EPA emissions standards accelerate catalytic retrofit investments in Gulf Coast refineries. Houston-area petrochemical clusters drive continuous stirred tank reactor demand for polymer synthesis at scale.
Germany
EU Green Deal carbon benchmarks and REACH substance restrictions force stainless steel replacement cycles across Baden-Württemberg specialty chemical plants. ECHA SVHC list expansions disqualify legacy gasket materials. BASF and Evonik supply chain concentration in Ludwigshafen anchors corrosion-resistant alloy procurement volumes.
China
SAMR GB pressure vessel standards reshape import qualification for foreign fabricators serving Shandong province petrochemical expansions. Dual carbon policy targets accelerate energy-efficient reactor retrofits. Qingdao and Yantai refining clusters dominate continuous stirred tank reactor installations for PTA and polyester production.
India
CDSCO pharmaceutical manufacturing rules and PLI scheme incentives compress continuous flow reactor adoption timelines across Maharashtra and Gujarat API hubs. BIS pressure equipment certification creates domestic sourcing preferences. Mumbai-Pune chemical belt demand concentrates in modular skid-mounted configurations for cost-constrained projects.
Japan
METI carbon neutrality roadmaps and JIS pressure vessel standards guide reactor material selection in Osaka-Kobe chemical manufacturing zones. PMDA pharmaceutical regulations enforce validated cleaning protocols for active ingredient synthesis. Chubu region specialty chemical producers prioritize compact flow reactor technology for high-value intermediate production.
Chemical Reactors Market Competitive Environment
Player mix skews toward specialized fabricators with ASME and pressure vessel code authority, creating tiered competitive dynamics around certification depth and alloy processing capability. Market structure concentrates margin capture with incumbents holding multi-jurisdiction code stamps. Strategic archetypes split between glass-lined specialists, corrosion-resistant alloy fabricators, and flow technology innovators. Dominant competitive moves include capacity expansion in Hastelloy and titanium fabrication, plus technology licensing partnerships for modular continuous processing architectures.
Among European-headquartered specialists, De Dietrich Process Systems and Pfaudler Group occupy positions anchored in corrosion-resistant fabrication traditions. Corning Incorporated exemplifies the flow technology archetype through its Advanced-Flow reactor platform. These three entities represent distinct competitive vectors: alloy expertise, glass-lined heritage, and continuous processing innovation respectively.
| Leading Market Players |
|---|
| Amar Equipment Pvt. Ltd. |
| Premex Solutions Group AG |
| Büchi AG |
| De Dietrich Process Systems |
| Pfaudler Group |
| Parr Instrument Company |
| Chemglass Life Sciences |
| Corning Incorporated |
| Syrris Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85% at German and Chinese specialty alloy mills compress margin buffers for vessel fabricators while simultaneously elevating price floors for ASME-certified reactor deliveries. This scale concentration enables incumbent suppliers to enforce cost-plus contracts indexed to nickel and chromium price movements, leaving smaller fabricators exposed to raw material volatility without corresponding pricing power.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and ferrochrome benchmarks dominate procurement arrangements for stainless steel reactor vessels. Price differentiation separates ASME-stamped premium fabrications from standard pressure vessels lacking multi-jurisdiction certification. Cost compression in standard vessel tiers is intensifying because Chinese fabricators are absorbing margin erosion to maintain Shandong province market share. Pharmaceutical manufacturers demonstrate least price sensitivity due to FDA cGMP validation requirements, while commodity chemical producers in bulk polymerization exhibit highest sensitivity to unit capital costs.
Supply Chain Analysis
Extended lead times for Hastelloy and titanium mill products stretch reactor delivery schedules by 8-14 months, forcing fabricators to pre-position alloy inventories. Supply concentrates in Germany, China, and Japan for pressure vessel-grade steel and specialty corrosion-resistant alloys. Raw material sourcing draws from Indonesian nickel laterite, South African chromium, and Australian titanium sponge. Single-source vulnerability sits with ASME-accredited inspection bodies concentrated in North America. Distribution runs through direct OEM relationships for large installations and third-party engineering procurement firms for modular skid configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow reactor platforms are redefining competitive boundaries as pharmaceutical manufacturers demand interoperable modular skids rather than custom-engineered vessels. This ecosystem shift rewards suppliers with standardized control architectures and punishes legacy fabricators wedded to project-specific engineering.
For Market Incumbents: Compound ASME certification depth by acquiring accredited inspection capabilities in Europe and Asia, reducing qualification bottlenecks that delay project delivery. Defend against modular flow technology substitution by licensing continuous processing architectures from technology partners rather than relying solely on in-house batch vessel engineering. Prioritize captive supply of Hastelloy and titanium fabrication capacity to insulate margins from alloy price volatility.
For New Entrants and Emerging Players: Certification fast-track through partnership with established ASME code shops offers the most viable entry path for corrosion-resistant alloy specialists. White-space concentrates in India's Maharashtra and Gujarat API hubs, where CDSCO rules and PLI incentives compress adoption timelines for cost-constrained modular units. Target pharmaceutical contract manufacturers seeking validated continuous processing without capital-intensive greenfield construction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flow reactor innovators with pharmaceutical validation records over legacy batch vessel fabricators facing retrofit pressure. Long-term viability over the next decade rests on electrification-readiness and carbon footprint verification for EU CBAM compliance. Watch for inflection when carbon border adjustment mechanisms trigger material sourcing audits that disqualify high-carbon alloy suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Melting | Captive supply of Hastelloy and titanium secures margin control against LME volatility. |
| Flow Technology Licensing Partnership | Access to Corning-style continuous processing architectures defends against platform substitution. |
| Multi-Jurisdiction Certification Expansion | ASME-EU-China triple-stamp capability eliminates qualification bottlenecks for global projects. |
| Modular Skid Standardization Program | Interoperable control architectures capture pharmaceutical demand for rapid deployment. |
| Low-Carbon Material Verification System | Verified production footprints command premium positioning under EU CBAM implementation. |
Study Parameters
A standing panel of plant engineers at German specialty chemical producers, procurement leads at Shandong province petrochemical clusters, and regulatory affairs directors at pharmaceutical manufacturers provided ongoing calibration across primary interview rounds. Secondary validation drew from SAMR GB standards filings, ECHA REACH substance restriction updates, FDA cGMP guidance documents, and SEC 10-K disclosures from listed process equipment suppliers. Bottom-up vessel shipment tallies triangulated against top-down capital expenditure forecasts from downstream end-use industries.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled reactor demand by vessel configuration, application chemistry, material grade tier, and regional production hub. CAGRs were derived from segmented growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated SAMR pressure vessel import qualification timelines and ECHA SVHC list expansion trajectories.
Underlying assumptions cover sustained nickel price volatility, REACH compliance enforcement intensity, and pharmaceutical continuous processing adoption curves, with deviation risk concentrated in ASME certification timeline extensions and carbon border adjustment implementation scope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Soil Treatment Chemicals Market