
 Global Fabric Softener Sheet Market | 2026-2036
Global Fabric Softener Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fabric Softener Sheet Market Foresight
Plant-derived cationic surfactant formulations is reshaping how fabric softener sheets are engineered and positioned on shelf. Procter & Gamble leverages its North American manufacturing scale to sustain cost leadership in fragrance-dominant SKUs. Henkel anchors its European presence through concentrated R&D on cold-water soluble sheet substrates.
Fabric softener sheets are thin, non-woven or woven carrier substrates impregnated with quaternary ammonium compounds or silicone-based softening agents, designed to deposit lubricating films on textiles during mechanical drying cycles to reduce static cling and improve hand feel. The fragrance sheet segment dominates volume in mainstream retail, while eco-friendly sheets built around biodegradable substrates and naturally derived actives capture the fastest growth trajectory as ingredient transparency becomes a purchasing filter. Within applications, commercial laundry and hospitality sector demand now outpaces home laundry growth in developed economies, driven by operational standardization needs across multi-property chains.
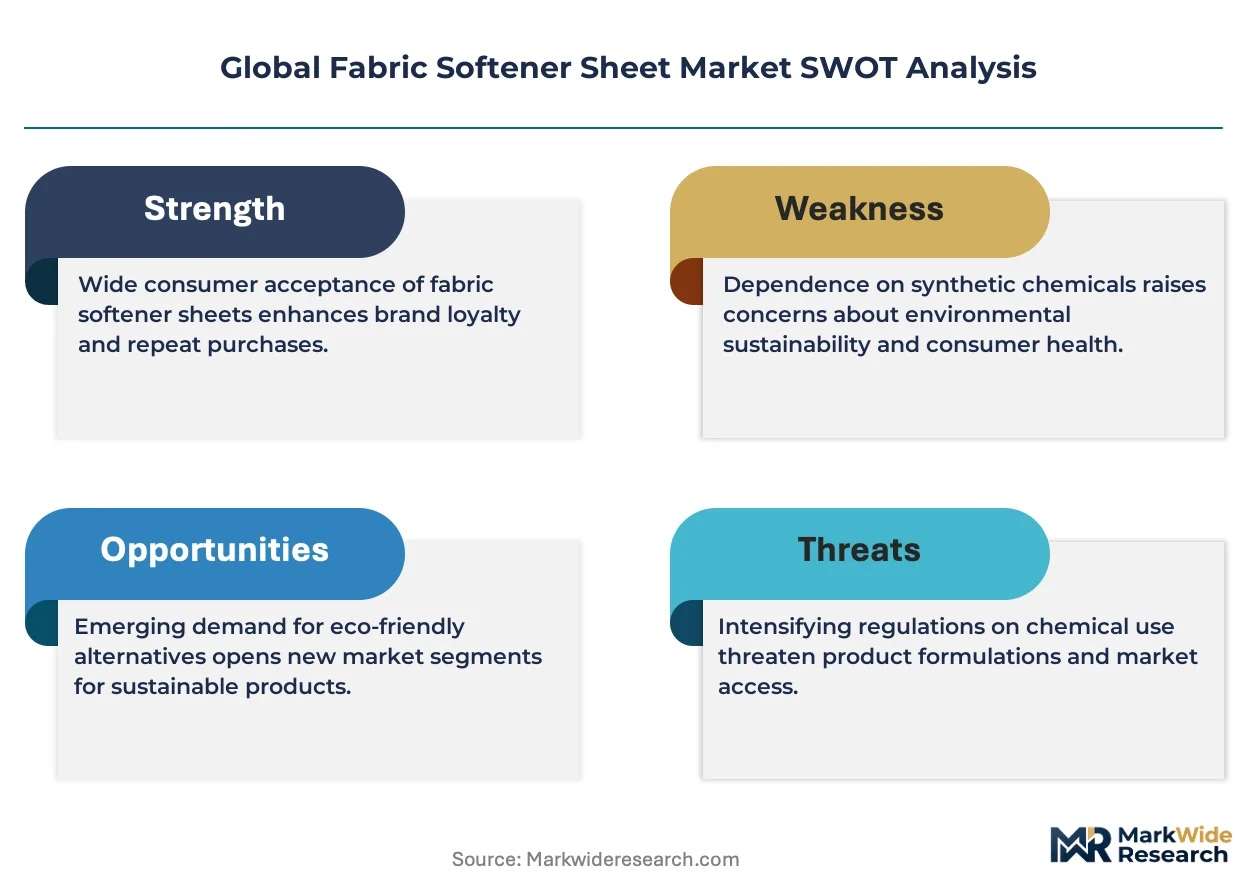
The EPA regulates volatile organic compound emissions from consumer textile care products in the United States, while the EU REACH framework and ECHA classification rules govern quaternary ammonium compound safety thresholds and labeling requirements across European markets. These frameworks push manufacturers toward reformulation cycles that favor lower-toxicity chemistries and expanded safety documentation. Stakeholders must monitor how divergent regional chemical disclosure standards affect cross-border formulation strategies and raw material sourcing flexibility.
Market Dynamics
Hotels and hospitality chains are standardizing procurement of commercial-grade fabric softener sheets across multi-property portfolios, compressing supplier bases while elevating performance specifications for static control and fragrance retention.
Growth Catalysts
- EU REACH Disclosure Mandates:Tighter ingredient transparency requirements are accelerating reformulation toward biodegradable substrates and plant-derived quaternary ammonium alternatives.
- Commercial Laundry Automation:Industrial tunnel washers and automated dispensing systems in hospitality chains require sheet formats compatible with mechanized feeding mechanisms.
- Cold-Water Solubility R&D:Advances in substrate engineering enable effective softening agent release at reduced dryer temperatures, aligning with energy efficiency mandates.
Market Restraints
- Petrochemical Feedstock Volatility:Quaternary ammonium compound production depends on palm-derived and petroleum-based precursors subject to price swings.
- Midwest US Manufacturing Concentration:Non-woven substrate production clusters heavily in Ohio and Indiana, creating geographic vulnerability to weather disruptions.
- Textile Compatibility Limitations:Silicone-based softening agents reduce absorbency in microfiber and athletic performance fabrics, restricting application scope.
Strategic Opportunities
- India Mass-Market Penetration:Rising washing machine ownership in tier-2 cities creates first-mover potential for affordable sheet formats.
- Healthcare Linen Applications:Hypoallergenic formulations meeting hospital infection control standards open institutional procurement channels.
- Refillable Dispenser Systems:Subscription-based sheet replenishment models bypass traditional retail shelf competition.
Industry Challenges
- Reformulation Timeline Compression:EPA volatile organic compound emission limits and EU ECHA classification updates force accelerated R&D cycles.
- Fragrance Chemist Talent Scarcity:Specialized expertise in encapsulation technology for dryer-heat-stable scent release commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fabric Softener Sheet Market |
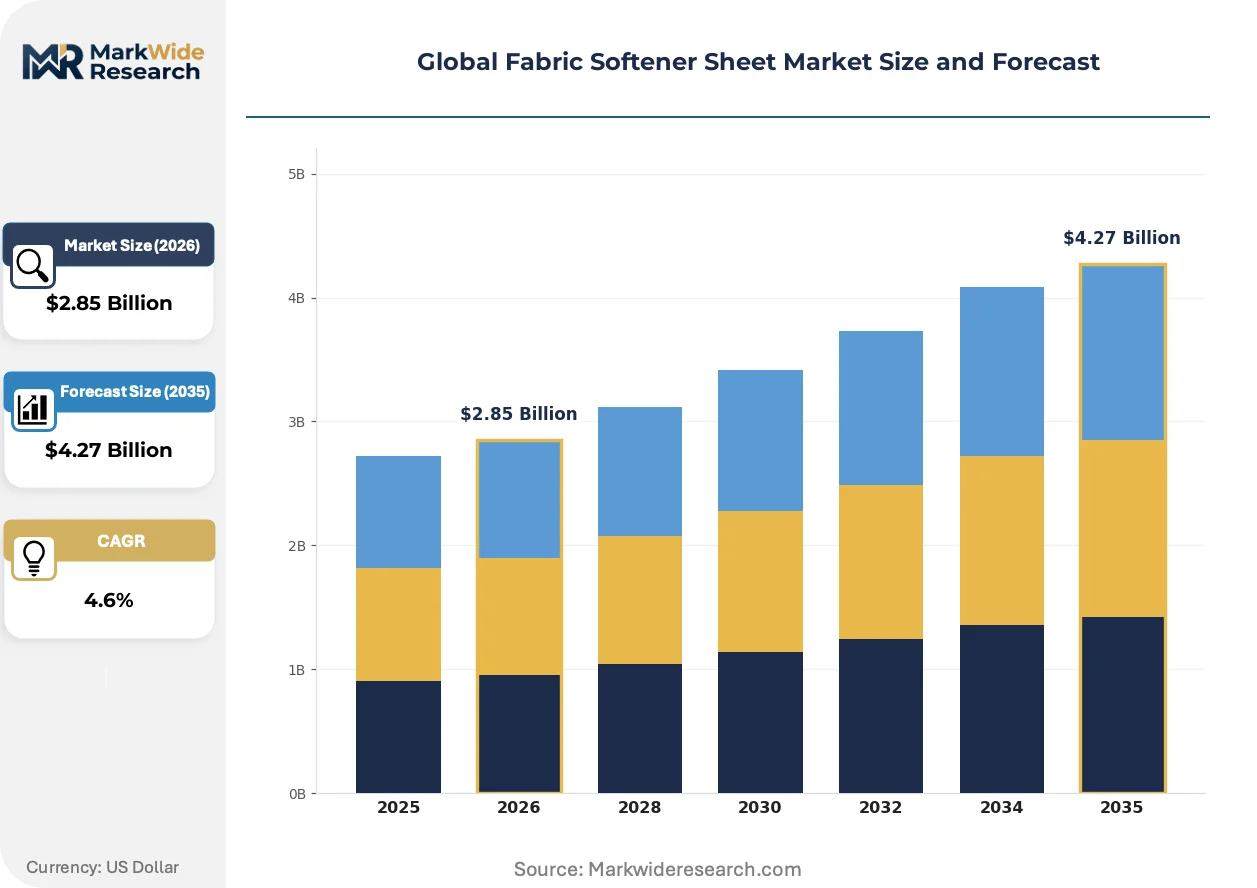
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.27 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrance Sheets, Hypoallergenic Sheets, Antistatic Sheets, Scent Booster Sheets, Eco-Friendly Sheets Application: Home Laundry, Commercial Laundry, Hospitality Sector, Healthcare Laundry, Institutional Washing End User: Households, Laundromats, Hotels, Hospitals, Educational Facilities Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale Suppliers, Direct Manufacturer Sales |
| Companies Covered | Kao Corporation, Colgate-Palmolive, Procter & Gamble, Werner & Mertz, SC Johnson, Unilever, Church & Dwight, Sodalis, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fabric Softener Sheet Market Shifts & Advancements
Formulation chemistry and substrate engineering are converging to redefine performance benchmarks, with sustainability credentials now functioning as gatekeepers to retail shelf placement rather than premium positioning alone.
Water-soluble polyvinyl alcohol film substrates are replacing traditional non-woven carriers in premium eco-segments. European formulators are adopting these films fastest, driven by biodegradability certifications demanded by German and French retailers. The technology is rendering obsolete conventional polyester-based sheets in markets where compostability labeling influences purchasing decisions.
EPA volatile organic compound emission thresholds for consumer textile care products are tightening fragrance loading limits in US formulations. Manufacturers are responding with microencapsulation technologies that reduce airborne release while maintaining scent perception. Home laundry applications face the steepest compliance costs, pushing reformulation investment toward lower-VOC silicone alternatives.
Direct-to-hospitality procurement contracts are displacing distributor-mediated sales in the commercial segment. Marriott and Hilton procurement consortia now negotiate multi-year supply agreements specifying custom fragrance profiles and sheet dimensions. This channel consolidation is most advanced in the United States, where property management companies centralize textile care purchasing across hundreds of locations.
Global Fabric Softener Sheet Market Segmentation
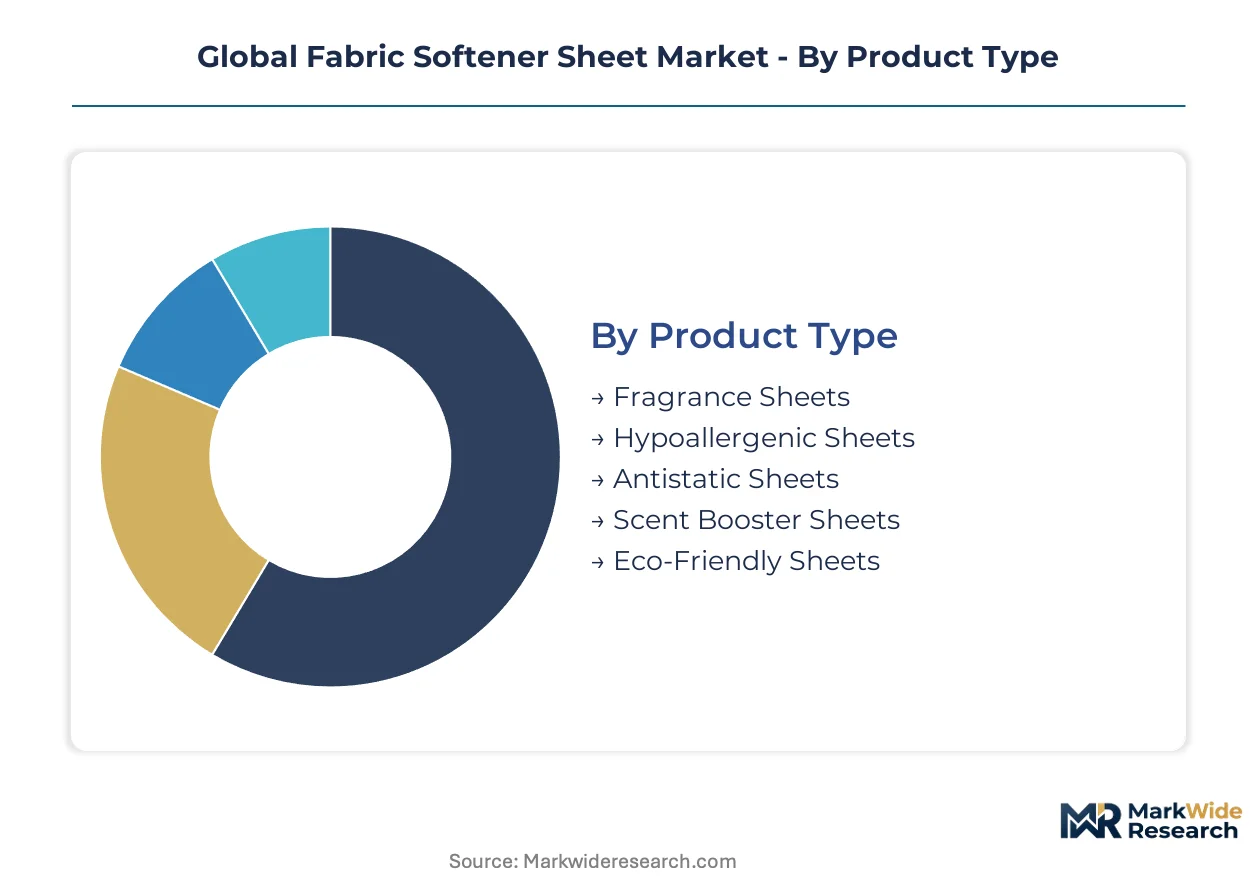
Segmentation in fabric softener sheets reveals how formulation chemistry, use environment, and procurement authority split demand into discrete profit pools with divergent margin structures and regulatory exposure.
Product Type:
Mature fragrance-dominant formats coexist with emerging substrate technologies that reset performance benchmarks and sustainability credentials.
- Fragrance Sheets:Polyester or cellulose carriers loaded with 5-15% perfume oil microcapsules designed for heat-triggered scent release during mechanical drying. United States mass retail channels concentrate demand here, where private-label penetration deepens and scent retention drives repeat purchase frequency.
- Eco-Friendly Sheets:Polyvinyl alcohol film substrates or biodegradable non-wovens impregnated with plant-derived quaternary ammonium compounds. German and French retailers are accelerating adoption fastest, as EU REACH disclosure mandates and compostability certifications function as shelf-placement gatekeepers.
- Hypoallergenic Sheets:Fragrance-free formulations with reduced quat concentrations for sensitive skin applications.
- Antistatic Sheets:Silicone-based or conductive polymer formulations targeting synthetic fiber static control.
- Scent Booster Sheets:High-load fragrance carriers designed as supplemental laundry additives rather than standalone softeners.
Fragrance Sheets handle the majority of throughput; Eco-Friendly Sheets are climbing the fastest on share.
Application:
Volume splits sharply between consumer convenience purchasing and institutional procurement governed by operational standardization mandates.
- Commercial Laundry:Industrial tunnel washer-compatible sheet formats with mechanized feeding compatibility and bulk packaging specifications. United States hospitality chains concentrate demand here, where Marriott and Hilton procurement consortia negotiate multi-year supply agreements specifying custom dimensions and fragrance profiles.
- Home Laundry:Standard dryer-sheet formats for consumer mechanical drying cycles, typically sold in 80-240 count boxes. This segment faces the steepest EPA volatile organic compound compliance costs, pushing reformulation toward lower-VOC silicone alternatives.
- Hospitality Sector:Property management company-centralized purchasing across multi-location portfolios.
- Healthcare Laundry:Infection control-compliant formulations with hypoallergenic and residue-minimization specifications.
- Institutional Washing:Educational facilities and government laundry operations with bid-based procurement.
Home Laundry maintains volume dominance; Commercial Laundry is expanding most quickly as channel consolidation accelerates.
End User:
Procurement authority concentrates differently across customer types, with intermediated laundromat purchasing contrasting against direct manufacturer relationships in hospital systems.
- Hotels:Multi-property chains standardizing textile care operations across hundreds of locations with specification-controlled supply agreements. Direct-to-hospitality contracts are displacing distributor-mediated sales fastest in the United States.
- Households:Individual consumers purchasing through retail or subscription channels, with fragrance preference and price sensitivity as primary decision filters.
- Laundromats:Small-business operators purchasing through wholesale suppliers with volume discount structures.
- Hospitals:Central supply departments with infection control committee oversight of chemical residue thresholds.
- Educational Facilities:University and school district procurement with sustainability preference clauses.
Households generate the highest absolute unit volume; Hotels are gaining share fastest as procurement centralization compresses supplier bases.
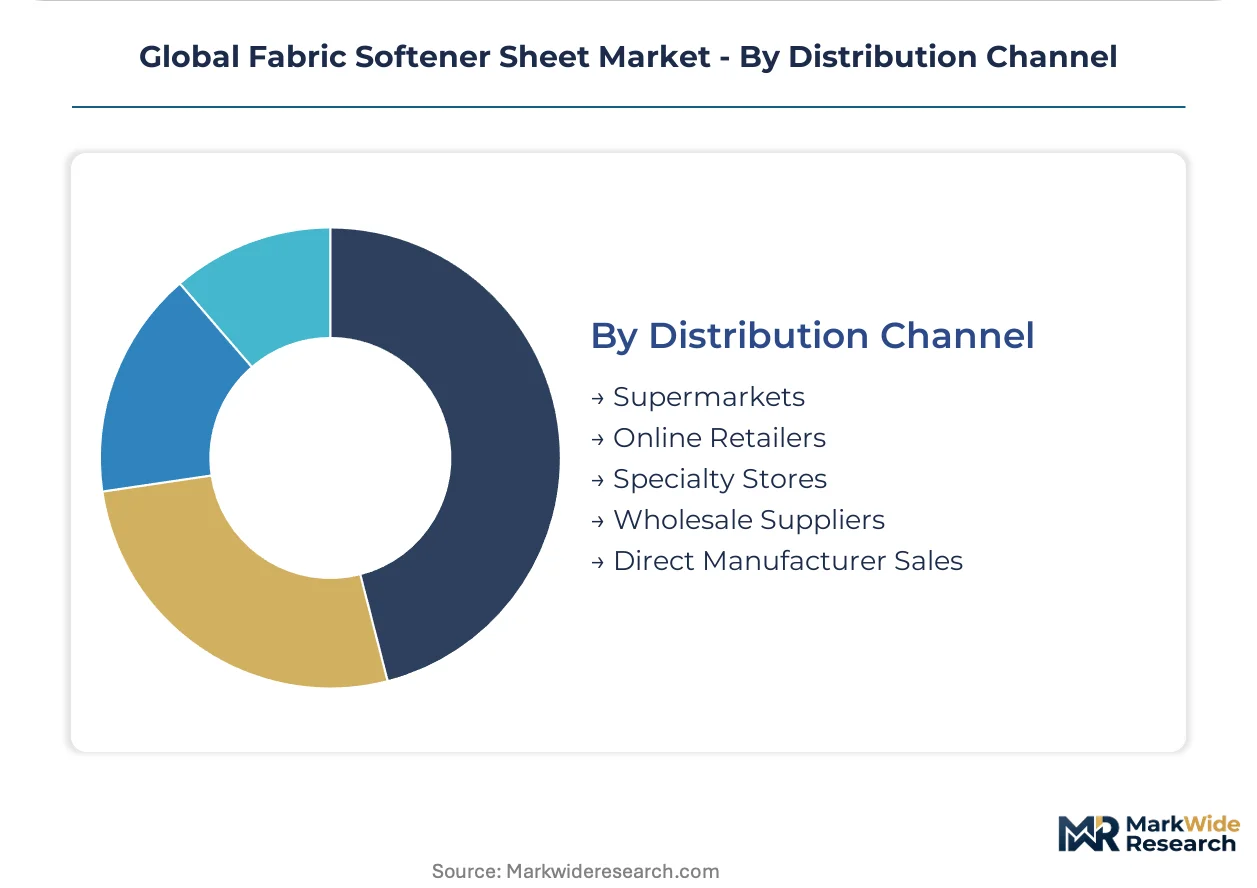
Distribution Channel:
Channel economics diverge between high-frequency replenishment through physical retail and emerging subscription models that bypass shelf competition entirely.
- Online Retailers:E-commerce platforms and direct-to-consumer subscription services with auto-replenishment algorithms and personalized fragrance profiling. Refillable dispenser systems are emerging here as a wedge against traditional retail saturation.
- Supermarkets:Mass retail shelf placement with slotting fee structures and private-label competition, dominant in United States consumer purchasing.
- Specialty Stores:Premium and natural-product retailers with sustainability certification requirements.
- Wholesale Suppliers:Distributor intermediaries serving laundromats and small commercial accounts.
- Direct Manufacturer Sales:Bypass relationships with hospitality chains and hospital systems.
Supermarkets still process the majority of consumer transactions; Online Retailers are expanding most quickly as subscription models capture replenishment loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export biodegradable sheet substrates to French and Dutch retail channels under EU REACH compliance frameworks, establishing the Rhine corridor as the primary trade artery for eco-formulation technologies.
United States
Private-label penetration in mass retail channels concentrates procurement power among Walmart, Target, and Costco buyers. EPA volatile organic compound emission thresholds force reformulation toward microencapsulated fragrance systems. Non-woven substrate production clusters in Ohio and Indiana, where Procter & Gamble operates integrated manufacturing campuses serving North American distribution networks.
Germany
Retailers in Berlin and Munich demand compostability certifications as shelf-placement gatekeepers for fabric care products. ECHA classification rules govern quaternary ammonium compound safety thresholds across German formulations. Henkel anchors concentrated R&D operations in Düsseldorf, developing cold-water soluble sheet substrates for European energy efficiency mandates.
France
Supermarket chains in Paris and Lyon accelerate adoption of polyvinyl alcohol film substrates ahead of stricter EU biodegradability deadlines. ANSM and CNIL oversight extends to chemical residue disclosure in consumer textile care. The Normandy region hosts specialty chemical suppliers serving fragrance encapsulation needs for premium sheet formats.
India
Rising washing machine ownership in tier-2 cities including Pune and Ahmedabad creates first-mover potential for affordable sheet formats. BIS standards govern textile care product safety labeling, though enforcement remains fragmented. Gujarat-based chemical processors supply quaternary ammonium precursors to domestic formulators expanding beyond detergent powders.
Japan
Compact housing and shared laundry facilities in Tokyo and Osaka sustain demand for space-efficient sheet formats over liquid softeners. METI energy efficiency guidelines favor low-temperature dryer compatibility. Kao Corporation maintains integrated production in Kanto, supplying fragrance-dominant SKUs through convenience store channels nationwide.
Global Fabric Softener Sheet Market Competitive Landscape
On the supply side, the industry is consolidating around multi-national consumer goods conglomerates with captive fragrance development capabilities and regional chemical processing assets. Mid-tier specialists compete through substrate engineering differentiation and private-label manufacturing contracts. Three archetypes dominate: vertically integrated FMCG giants, substrate technology specialists, and private-label converters. Competitive intensity manifests through multi-year hospitality procurement contracts and accelerated reformulation cycles responding to EPA and ECHA regulatory updates.
Among the integrated consumer goods tier, Procter & Gamble and Henkel exemplify scale-driven positioning through North American manufacturing concentration and European R&D anchoring respectively. Kao Corporation occupies a distinct geography-focused archetype, leveraging Japanese distribution density and compact-format expertise. Unilever and Colgate-Palmolive represent portfolio-diversified competitors where fabric softener sheets function as laundry category extensions rather than standalone strategic priorities. Church & Dwight and SC Johnson illustrate mid-cap specialists competing through fragrance innovation and retail channel specificity rather than vertical integration depth.
| Leading Market Players |
|---|
| Kao Corporation |
| Colgate-Palmolive |
| Procter & Gamble |
| Werner & Mertz |
| SC Johnson |
| Unilever |
| Church & Dwight |
| Sodalis |
| Henkel |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor connects German chemical processors to French retail distribution hubs, with transport cost dynamics amplifying pricing power for concentrated substrate suppliers while forcing downstream price differentiation between fragrance-dominant and eco-formulation tiers.
Pricing Analysis
Current-generation polyvinyl alcohol film substrates command premium positioning against prior-generation polyester carriers, while next-generation cold-water soluble formats are entering at super-premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates biodegradable certification holders from conventional formulations and private-label alternatives. Price differentiation hinges on EU REACH compliance documentation and fragrance encapsulation technology sophistication. Cost compression in economy-tier private-label SKUs is intensifying because Walmart and Target buyers extract slotting fee concessions. Laundromat operators exhibit highest price sensitivity; hospitality procurement consortia prioritize performance specifications over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier relationships with hospitality chains, compressing working capital for mid-tier converters. Quaternary ammonium compound production draws from palm-derived feedstocks in Malaysia and Indonesia, petroleum-based precursors from the United States, and cellulose substrates from Brazil. Single-source vulnerability concentrates in Ohio and Indiana non-woven manufacturing clusters exposed to weather disruption. Distribution runs through direct manufacturer sales to hospitality chains, bypassing traditional wholesale intermediaries fastest in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospitality procurement consortia, with Marriott and Hilton centralizing textile care purchasing across hundreds of properties and compressing supplier bases by two-thirds.
For Market Incumbents: Pre-empt private-label encroachment by securing exclusive multi-year fragrance development contracts with hospitality chains. Backward integration into captive quaternary ammonium compound production hedges against palm oil feedstock volatility. Accelerate cold-water soluble substrate R&D to meet METI energy efficiency guidelines before competitors achieve scale.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 city mass market before washing machine ownership saturates. Affordable sheet formats for first-time fabric softener users in Pune and Ahmedabad face minimal incumbent penetration. Pursue direct-to-consumer subscription models with auto-replenishment algorithms to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer goods conglomerates where fabric softener sheets represent non-core laundry category extensions. Five-to-ten year viability favors substrate technology specialists with biodegradable certification portfolios over fragrance-dependent commodity converters. Watch EPA volatile organic compound threshold announcements as inflection indicators for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Water Solubility R&D Investment | Henkel's Düsseldorf operations align with EU energy efficiency mandates reducing dryer temperatures. |
| Biodegradable Substrate Certification | German and French retailers gate shelf placement behind compostability labeling requirements. |
| Direct-to-Hospitality Contract Expansion | Marriott and Hilton consortia displace distributor-mediated sales with custom specification agreements. |
| Plant-Derived Quaternary Ammonium Scale-Up | EU REACH disclosure mandates accelerate reformulation away from petroleum-based precursors. |
| Microencapsulation Technology Acquisition | EPA emission thresholds force fragrance loading reductions while preserving scent perception. |
Research Methodology
A spread of perspectives from procurement directors at hospitality chains, fragrance encapsulation chemists, non-woven substrate plant managers, and retail category buyers converged on the working assumptions underlying this analysis. Primary interviews with supply planners at chemical processors and channel sales heads at wholesale distributors were cross-referenced against customs records, SEC 10-K filings, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application environment, end-user procurement authority, and distribution channel structure. CAGRs were derived from slope analysis of historical trajectory adjusted for regulatory inflection points. Forecast inputs incorporated EPA volatile organic compound compliance timelines and EU ECHA classification update schedules.
Stress conditions across palm oil price volatility, Midwest manufacturing weather disruption, and hospitality sector occupancy cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reformulation timelines and procurement centralization velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Phospholipid Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Titanium Fluoride Phosphate Market