
 Global Specialty Amines Market | 2026-2036
Global Specialty Amines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Amines Market Intelligence
The divide between high-purity, application-specific amines and lower-grade commodity variants is recalibrating competitive dynamics. BASF leverages its extensive manufacturing scale and integrated production network to serve large-volume contracts. In contrast, Evonik differentiates through its focus on developing specialized amines for high-margin pharmaceutical and personal care applications. Arkema specializes in unique chemistries for niche industrial uses, securing its position in specific segments.
Specialty amines are a class of organic compounds derived from ammonia where one or more hydrogen atoms are replaced by organic substituents. They function as critical chemical intermediates, curing agents, and pH adjusters in complex synthesis processes. Within the product landscape, ethylamines form a foundational category, while demand in the agrochemicals application is driven by the need for more effective and environmentally benign pesticides. The pharmaceuticals segment commands higher margins due to stringent purity requirements and complex synthesis pathways.
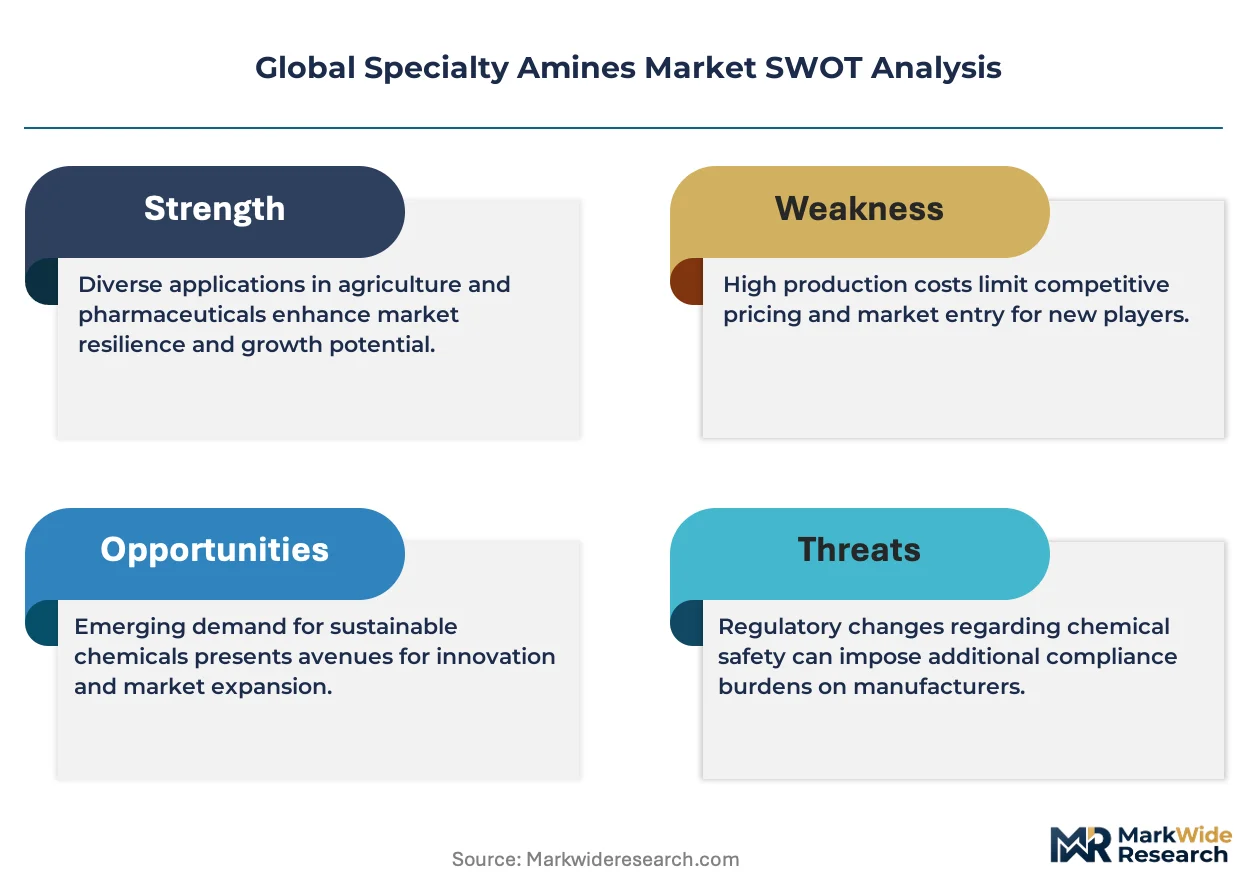
Europe's ECHA, through its REACH regulation, imposes strict registration and evaluation requirements on all chemical substances, influencing product composition. Similarly, mandates from the US EPA and China's MEE on emissions and chemical safety steer manufacturers toward cleaner production technologies. Navigating this complex, multi-jurisdictional regulatory environment is becoming a central strategic challenge for market participants.
Market Dynamics
The escalating complexity of global chemical regulations, exemplified by the EU's REACH framework and China's MEE mandates, is the central force compelling innovation in specialty amine composition, safety profiles, and production technologies across all end-use markets.
Growth Catalysts
- Agrochemical Advancement:The development of more effective, targeted, and environmentally benign pesticides and herbicides requires high-purity specialty amines as critical intermediates in complex synthesis.
- Regulatory-Driven Innovation:Stringent substance regulations under Europe's ECHA, including REACH, are pushing manufacturers to develop safer, high-performance alternatives to restricted chemicals.
- Pharmaceutical Expansion in China:China's expanding pharmaceutical manufacturing sector, governed by NMPA standards, creates significant demand for specialty amines that meet strict purity and synthesis requirements.
Market Restraints
- Input Cost Volatility:Price fluctuations in key feedstocks, particularly ammonia and its derivatives, create margin pressure and complicate long-term cost management for amine producers.
- Regulatory Compliance Burden:The high cost and lengthy timelines associated with navigating multi-jurisdictional chemical registration, such as with ECHA and the US EPA, act as barriers to entry.
- Substitution from Commodity Grades:In less demanding applications, lower-cost commodity amines can substitute for specialty variants, capping the addressable market for high-purity products.
Strategic Opportunities
- Bio-Based Feedstocks:Developing specialty amines from renewable, bio-based sources presents an opportunity to meet demand for sustainable chemicals in personal care and coatings applications.
- Agrochemicals in Brazil:Brazil's massive agricultural sector offers an underpenetrated market for advanced specialty amines used in next-generation crop protection formulations.
- High-Throughput Screening:The convergence of computational chemistry and automated screening enables rapid discovery of novel amines tailored for specific, high-value niche applications.
Industry Challenges
- Capital-Intensive Production:Building and upgrading manufacturing facilities to meet the stringent emission and safety standards set by regulators like China's MEE requires significant capital investment.
- Specialized Talent Scarcity:A shortage of organic chemists and process engineers with expertise in complex amine synthesis and purification hinders product development and process optimization efforts.
- Registration Delays:Protracted timelines for new chemical substance registration under frameworks like REACH can delay product launches by several years, impacting competitive timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Amines Market |
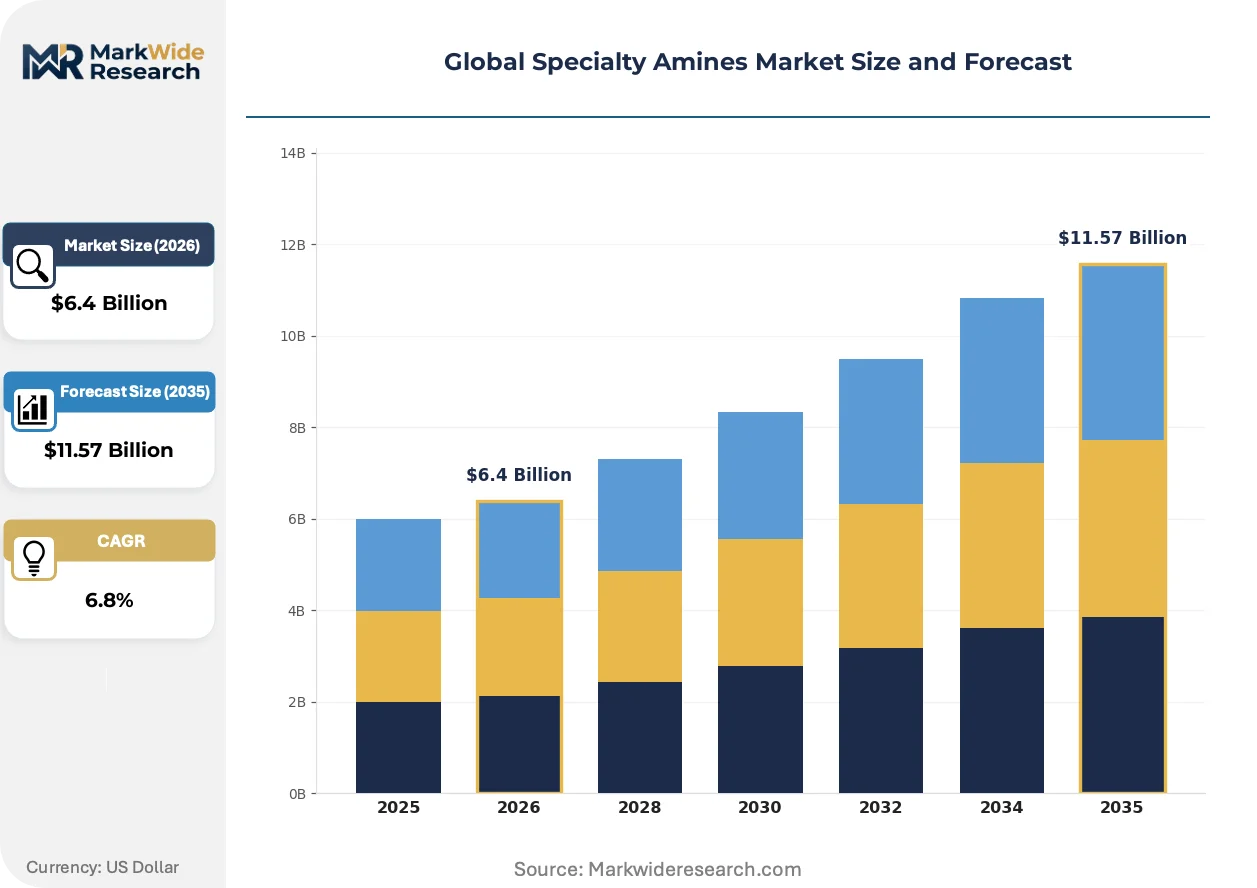
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylamines, Ethylamines, Propylamines, Specialty Amines Application: Agrochemicals, Pharmaceuticals, Industrial Chemicals, Personal Care Products End User: Agriculture, Pharmaceutical Companies, Manufacturing, Cosmetics Technology: Chemical Synthesis, Catalytic Processes, Biological Methods, Others |
| Companies Covered | Alkyl Amines Chemicals Limited, BASF, Arkema, Nouryon, Air Products and Chemicals, Eastman Chemical Company, Evonik, Solvay, Huntsman International LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Amines Market Strategic Shifts & Innovations
A systemic shift toward precision and sustainability defines the current innovation cycle. Manufacturers are moving beyond incremental improvements to adopt new design paradigms and feedstock sources in response to regulatory and customer pressures.
Computational chemistry provides tools for designing specialty amines with specific functional properties before synthesis. Pharmaceutical and agrochemical R&D teams are the primary adopters, accelerating their discovery pipelines. This digital-first approach is unifying the previously distinct phases of molecular design, process simulation, and performance validation, drastically shortening development cycles for new chemical entities.
Europe's REACH regulation continues to exert significant influence on product formulation beyond the EU's borders. The framework's mandate for comprehensive risk assessment of all chemical substances forces producers to invest heavily in toxicological testing and documentation. Manufacturers targeting the European market, especially in agrochemicals and personal care, are proactively reformulating products to avoid substances of very high concern.
Customer preference is shifting toward specialty amines derived from certified sustainable, bio-based, or circular feedstocks. This trend directly challenges the dominance of traditional synthesis routes based on petrochemical derivatives. The shift is most pronounced in consumer-facing applications within Europe and North America, where corporate sustainability reporting and brand image are significant procurement drivers.
Global Specialty Amines Market Segmentation
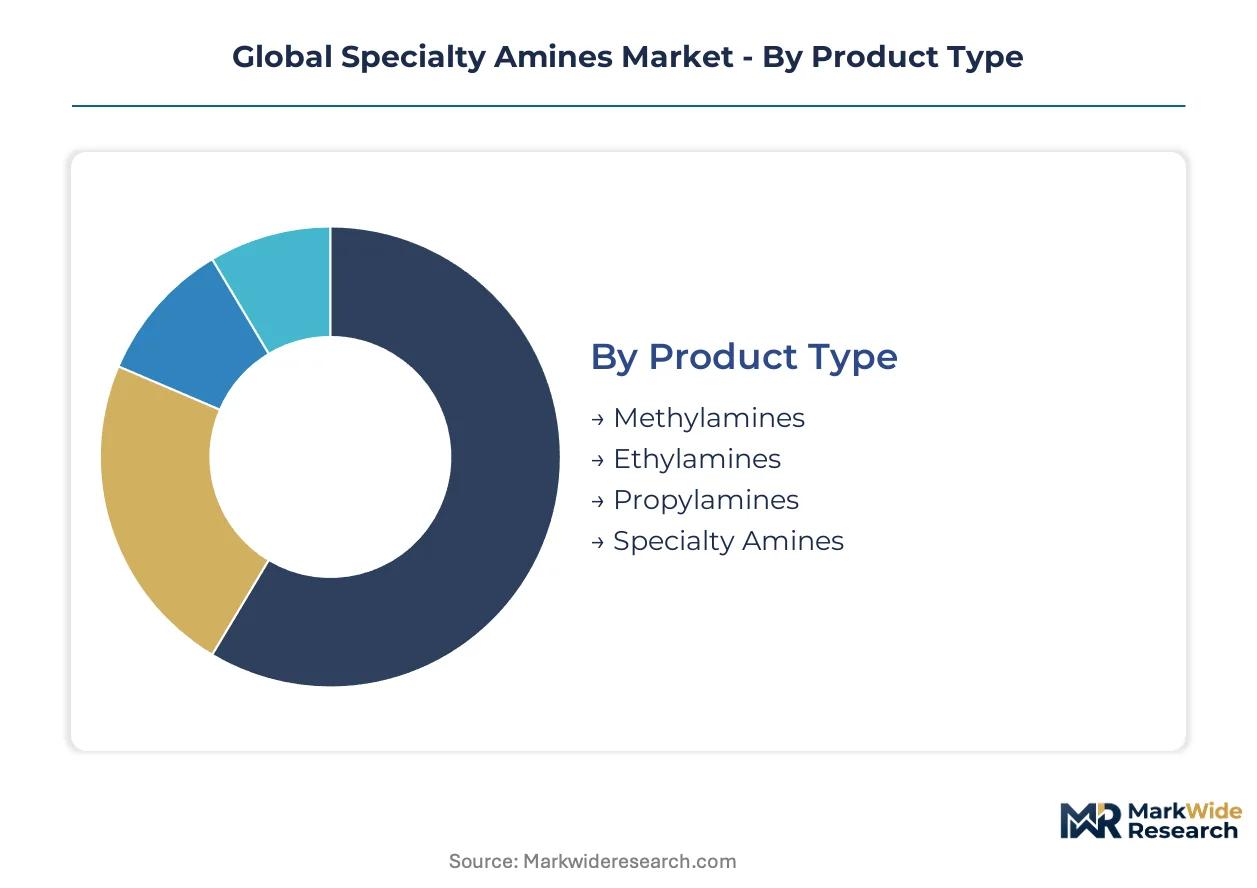
The segmentation analysis reveals distinct market dynamics influenced by product characteristics, end-use applications, and technological pathways. Understanding these divisions helps illuminate where value accumulates and how competitive strategies adapt to specific market requirements. This granular view is essential for identifying growth pockets and navigating regulatory complexities.
Product Type:
The capital intensity required for production facilities varies significantly across amine product types, influencing market entry barriers and scale advantages.
- Ethylamines:These foundational organic compounds, including mono-, di-, and triethylamine, serve as crucial intermediates in rubber chemicals, pharmaceuticals, and agricultural formulations. Demand for ethylamines is concentrating in China's rapidly expanding agrochemical sector due to their efficacy in pesticide synthesis.
- Specialty Amines:Tailored for specific performance requirements, these high-purity compounds often involve complex synthesis routes and stringent quality controls. Pharmaceutical manufacturing in Europe and North America drives significant demand for specialty amines, requiring high-purity inputs for drug synthesis.
- Methylamines:Derivatives of ammonia, methylamines find extensive use as solvents, surfactants, and intermediates in pharmaceuticals and agrochemicals.
- Propylamines:These compounds are utilized in the production of herbicides, rubber processing chemicals, and certain pharmaceutical ingredients globally.
Ethylamines absorb the bulk of installed capacity; Specialty Amines are expanding most quickly.
Application:
The margin profiles across different applications for specialty amines reflect varying regulatory burdens and performance requirements.
- Agrochemicals:Specialty amines function as critical intermediates in the synthesis of advanced herbicides, insecticides, and fungicides, enhancing their efficacy and environmental profiles. Brazil's vast agricultural sector drives substantial demand for these formulations, seeking improved crop protection solutions.
- Pharmaceuticals:Requiring ultra-high purity and precise molecular structures, amines are indispensable building blocks for active pharmaceutical ingredients and excipients. Stringent NMPA and EMA regulations in China and Europe necessitate specialized amine production for drug safety.
- Industrial Chemicals:This segment encompasses the use of amines as curing agents, corrosion inhibitors, and pH adjusters in various manufacturing processes.
- Personal Care Products:Amines contribute to formulations as emulsifiers, surfactants, and pH stabilizers in cosmetics and toiletries, driven by consumer preference.
The demand for pharmaceutical applications drives significant R&D investment, while agrochemicals offer consistent volume stability.
End User:
Procurement strategies for specialty amines differ significantly among end-user industries, reflecting their unique supply chain priorities and quality standards.
- Agriculture:End users in agriculture, including large-scale farming operations and agrochemical distributors, require reliable, cost-effective supplies for crop protection product manufacturing. The US agricultural market's scale creates substantial demand for amine-based pesticide ingredients.
- Pharmaceutical Companies:These companies demand amines meeting rigorous purity standards and comprehensive regulatory documentation for drug development and production. European pharmaceutical manufacturers prioritize suppliers with robust quality control and regulatory compliance.
- Manufacturing:This broad category includes diverse industries utilizing amines in processes like polymer production, water treatment, and textile manufacturing.
- Cosmetics:Formulators in the cosmetics industry seek specialty amines for their functional properties in skin care, hair care, and personal hygiene products.
Pharmaceutical companies prioritize product traceability and regulatory alignment, whereas agricultural end-users focus on consistent supply and competitive pricing.
Technology:
The maturity and innovation trajectories of production technologies for specialty amines influence capital expenditure and operational efficiency.
- Chemical Synthesis:This traditional method involves various chemical reactions, including amination, alkylation, and reduction, often requiring high temperatures and pressures. Established manufacturers in Germany and the US leverage chemical synthesis for large-scale production of commodity and specialty amines.
- Catalytic Processes:Employing catalysts to accelerate and control reactions, these processes enhance selectivity, reduce by-products, and improve energy efficiency in amine production. Innovation in catalytic processes, particularly in Japan, focuses on developing greener and more sustainable routes.
- Biological Methods:Emerging biological routes, such as enzymatic synthesis or fermentation, offer potential for sustainable amine production from renewable feedstocks.
- Others:This category encompasses various alternative or niche production methods, including electrochemical synthesis or advanced separation techniques.
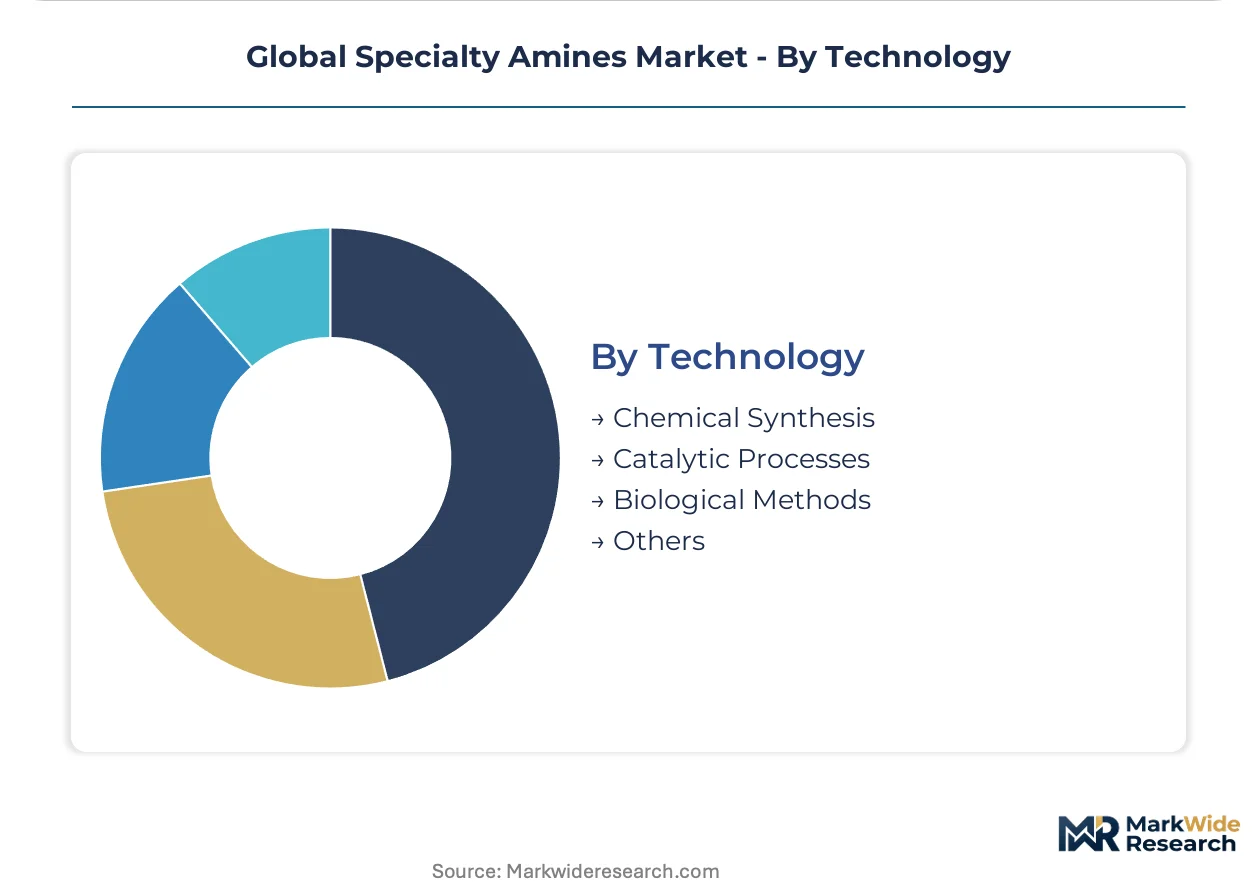
Chemical Synthesis remains the dominant production route, although Catalytic Processes are gaining traction for their efficiency and environmental benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's robust chemical industry hub drives significant specialty amines demand, particularly for advanced pharmaceutical intermediates. This concentration supports both domestic consumption and export-oriented manufacturing. The region's strategic importance extends to key agricultural and industrial applications.
China
China's expanding agricultural sector and pharmaceutical manufacturing fuel high demand for specialty amines. The Ministry of Ecology and Environment (MEE) mandates cleaner production technologies, influencing amine synthesis. The Yangtze River Delta region, with its numerous chemical parks, is a nexus for advanced amine production and innovation.
Germany
German pharmaceutical manufacturers require high-purity specialty amines for complex drug synthesis pathways. Europe's ECHA REACH regulation imposes stringent registration and evaluation requirements on chemical substances produced here. The Rhine-Main area, a historical chemical industry center, focuses on innovative catalytic processes for sustainable amine production.
United States
The United States agricultural market demands advanced specialty amines for effective crop protection formulations. US EPA regulations on emissions and chemical safety steer manufacturers toward cleaner production methods. The Gulf Coast chemical corridor remains a significant hub for large-scale chemical synthesis and amine manufacturing.
Brazil
Brazil's vast agricultural sector presents an underpenetrated market for advanced specialty amines in crop protection. ANVISA regulations for agrochemical formulations drive demand for environmentally benign and effective intermediates. São Paulo state, a major agricultural and industrial center, is seeing increased investment in agrochemical formulation facilities.
India
India's expanding pharmaceutical and agrochemical industries create substantial demand for various specialty amines. The Central Drugs Standard Control Organization (CDSCO) sets purity requirements for pharmaceutical intermediates. Gujarat, a prominent chemical manufacturing hub, is expanding its capacity for both commodity and specialty amine synthesis.
Global Specialty Amines Market Key Industry Players
Premium-margin players sit above commodity-margin players across product purity and application specificity. The market exhibits a tiered structure, with large integrated chemical producers competing on scale and specialized manufacturers focusing on niche, high-value segments. Strategic archetypes include volume-driven commodity suppliers, innovation-led specialty chemical providers, and application-focused solution developers. Dominant competitive moves involve strategic partnerships for R&D and targeted portfolio diversification into high-growth end-use markets.
On the premium-tier vector, German-based BASF AG exemplifies a large integrated chemical producer leveraging its extensive manufacturing scale to serve large-volume contracts. Evonik AG, another German chemical company, represents innovation-led specialty chemical providers, focusing on developing specialized amines for high-margin pharmaceutical and personal care applications. French-based Arkema SA occupies a position as an application-focused solution developer, specializing in unique chemistries for niche industrial uses and securing specific market segments. These companies, along with others like Alkyl Amines Chemicals Limited and Huntsman International LLC, collectively shape the competitive landscape, emphasizing product differentiation and adherence to stringent regulatory frameworks.
| Leading Market Players |
|---|
| Alkyl Amines Chemicals Limited |
| BASF |
| Arkema |
| Nouryon |
| Air Products and Chemicals |
| Eastman Chemical Company |
| Evonik |
| Solvay |
| Huntsman International LLC. |
| Others |
Cost & Logistics Intelligence
Pharmaceutical companies in Europe often encounter contract-based pricing for specialty amines, reflecting stringent purity requirements and long-term supply agreements. This model ensures consistent quality and regulatory compliance from suppliers.
Pricing Analysis
Value-based pricing for specialty amines ties directly to their performance in advanced agrochemical formulations. Price differentiation stems from product purity levels and the complexity of synthesis routes. Pricing softness reflects input cost volatility in ammonia derivatives. Pharmaceutical manufacturers exhibit lower price sensitivity compared to industrial chemical buyers.
Supply Chain Analysis
Workforce availability in Germany and China significantly influences specialty amine production capacity. Supply concentrates in chemical manufacturing hubs like the Yangtze River Delta and the US Gulf Coast, drawing from ammonia and petrochemical feedstocks. Single-source vulnerability for specific high-purity intermediates poses a structural risk. Distribution runs through specialized chemical distributors and direct manufacturer-to-customer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty amines market is witnessing a vertical-integration race, driven by producers seeking greater control over bio-based feedstock sourcing. This strategic move aims to secure sustainable supply chains.
For Market Incumbents: Deploy advanced catalytic processes to reduce production costs and meet stricter MEE emission standards. Consolidate market share through targeted acquisitions of smaller, specialized producers facing regulatory compliance burdens. Invest in R&D for next-generation agrochemical intermediates to counter substitution from commodity grades.
For New Entrants and Emerging Players: Niche personal care formulators represent an underserved buyer archetype seeking bio-based specialty amines. Target sustainable chemical certifications in Europe for high-margin cosmetic ingredients. Focus on direct sales channels to highlight product provenance and environmental benefits.
For Investors and Strategic Acquirers: The window for entry favors mid-cap chemical specialists with proven green chemistry expertise. Long-term viability hinges on companies demonstrating robust intellectual property in novel amine synthesis. Watch for increased M&A activity among feedstock suppliers as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | BASF expands ethylamine capacity in China to meet regional agrochemical demand. |
| Green Manufacturing Transition | Evonik invests in renewable energy for its German specialty amine plants. |
| Long-term Supply Agreement | Arkema secures multi-year contracts for unique industrial amine chemistries. |
| Backward Integration | Huntsman acquires a bio-based raw material producer for sustainable amines. |
| Joint Venture | Solvay partners with a Japanese firm for catalytic process innovation. |
Research Approach
Document review covered trade publications, company annual reports, and regulatory filings from ECHA and US EPA, complemented by interviews with chemical plant managers, R&D directors, and procurement leads at agrochemical and pharmaceutical firms. This comprehensive approach integrated primary insights with secondary validation. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
The quantitative model generated volume and value projections across the analysis window. This framework segmented the market by product type, end-use application, technology, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and anticipated shifts in feedstock availability. Forecast inputs included projected agrochemical demand in Brazil and pharmaceutical manufacturing expansion in China.
Revisions become necessary when significant shifts in global chemical regulations or feedstock prices materialize. Forecasts reflect current assumptions about market dynamics and technological adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Lithopone Market
Specialty Compounds
Tosyl Chloride Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Superacids Market
Specialty Compounds
Compounds Market
Specialty Compounds
Air-Laid Product Market