
 Hydrofluoric Acid (HF) for Semiconductor Market | 2026-2036
Hydrofluoric Acid (HF) for Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrofluoric Acid (HF) for Semiconductor Market Insights
Japanese fluorochemical producers is realigning capacity toward semiconductor-grade output as logic and memory fabs expand etching and cleaning requirements. Stella Chemifa Corporation leverages vertical integration from fluorspar mining to final purification, sustaining supply security for Taiwan and South Korean foundries. Honeywell International anchors North American supply through its Louisiana production complex, while Solvay competes on specialty-grade formulations for EUV lithography companion processes.
Hydrofluoric Acid for Semiconductor denotes ultra-high-purity aqueous hydrogen fluoride, typically at 49% concentration or higher dilutions, manufactured through multi-stage distillation and sub-boiling purification to achieve part-per-trillion metal impurity levels for silicon wafer processing. Electronic Grade dominates value capture due to stringent purity protocols and captive qualification cycles at leading fabs, while Etching applications within the Application dimension lead volume absorption as 3nm and 2nm node transitions deepen trench and gate-stack complexity. Foundries within the End User category represent the fastest-growing demand pool as pure-play operators expand capital intensity per wafer start.
The EPA governs HF handling and emissions in the United States through RMP and TSCA frameworks, while REACH and the EU F-Gas Regulation restrict fluorinated gas releases and mandate cradle-to-grave tracking in Europe. China's MEE enforces wastewater discharge limits that elevate capital costs for domestic suppliers including Zhejiang Kaiheng Electronic Materials and Do-Fluoride New Materials. Stakeholders must monitor how tightening environmental enforcement across Japan's METI guidelines and South Korea's K-REACH amendments reshapes cost structures and regional sourcing decisions for ultra-purity acid.
Market Dynamics
Sub-7nm node transitions at foundries in Taiwan and South Korea are intensifying consumption of part-per-trillion purity HF, tightening qualification cycles and compressing supplier switching timelines for etching and cleaning chemistries.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are redirecting fluorochemical capacity toward semiconductor-grade acid production, securing dedicated supply lines for advanced fabs.
- Hsinchu Science Park cluster:Taiwan's concentrated foundry ecosystem generates sustained pull for ultra-high-purity HF as TSMC and UMC expand 3nm and 2nm wafer starts.
- Dual carbon goals:China's MEE enforcement of wastewater discharge limits is accelerating domestic purification technology upgrades, expanding local supply capacity for captive fab consumption.
Market Restraints
- Fluorspar supply concentration:Over 60 percent of acid-grade fluorspar originates from Chinese mining operations, exposing purification facilities to export quota volatility and input cost spikes.
- Multi-stage distillation capex:Sub-boiling purification systems require 18-24 month installation cycles and specialized corrosion-resistant alloys, elevating barrier-to-entry for new electronic-grade entrants.
- REACH substance tracking:ECHA cradle-to-grave documentation requirements add compliance overhead for EU-sourced HF, disadvantaging smaller batch producers against integrated majors.
Strategic Opportunities
- India's semiconductor subsidy scheme:PLI incentives for domestic fab construction create virgin demand territory as Gujarat and Karnataka sites advance toward tool-in dates.
- EUV lithography companion processes:Post-EUV resist stripping and mask cleaning applications are opening incremental volume channels beyond traditional wet etching.
- Solvay's specialty-grade formulations:Belgium-based purification expertise positions EU suppliers to capture premium pricing for next-node chemistries as Brussels enforces stricter fluorochemical sourcing rules.
Industry Challenges
- Fab qualification timelines:Multi-year captive approval cycles at leading foundries lock out second-tier suppliers even when purity specifications are technically met.
- Specialized corrosion engineering talent:Shortage of process engineers experienced in HF-compatible materials of construction constrains capacity expansion at purification plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrofluoric Acid (HF) for Semiconductor Market |
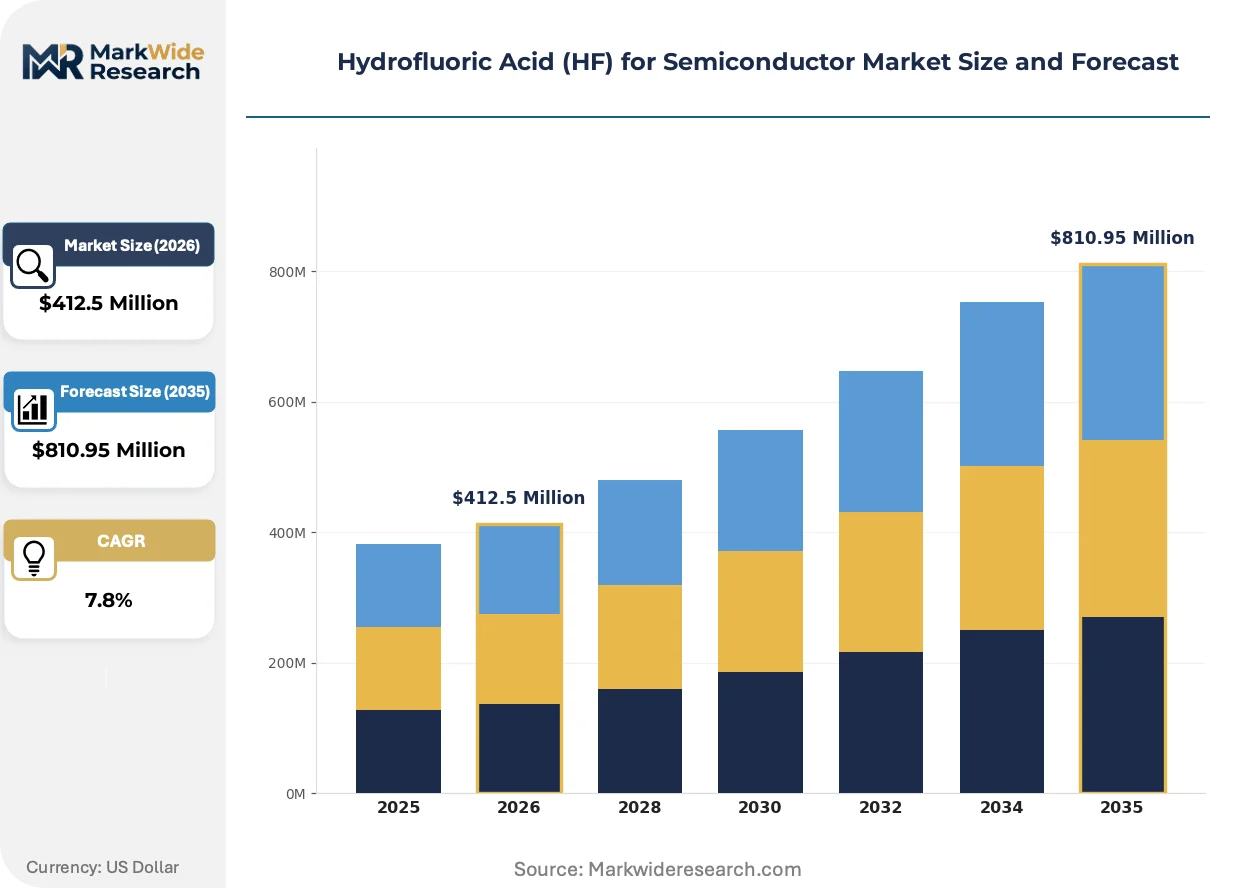
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Grade, Technical Grade, Reagent Grade, Specialty Grade Application: Etching, Cleaning, Surface Treatment, Deposition End User: Foundries, Integrated Device Manufacturers, Research Institutions, OEMs Packaging Type: Drums, Cylinders, IBC Totes, Bottles |
| Companies Covered | Stella Chemifa Corporation, Honeywell International Inc., Solvay, Morita Chemical Industries, Formosa Daikin Advanced Chemicals, Daikin Industries, Sunlit Chemical, Zhejiang Kaiheng Electronic Materials, Do-Fluoride New Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrofluoric Acid (HF) for Semiconductor Market Trends and Innovations
Point-of-use purification systems and closed-loop recycling architectures are displacing centralized bulk delivery models, enabling fabs to recover and reconstitute spent acid on-site while tightening impurity control.
Membrane-based purification is modularizing final polishing stages that previously required fixed distillation columns. Foundries in South Korea are piloting skid-mounted sub-ppm removal units adjacent to wet bench stations, compressing logistics exposure and enabling just-in-time purity verification before wafer contact.
EPA Risk Management Plan amendments are tightening HF storage and release reporting thresholds for US-based fabs and suppliers. Louisiana production complexes must now deploy real-time emission monitoring and enhanced secondary containment, elevating operational compliance costs while accelerating substitution toward lower-volume on-site generation systems.
Long-term offtake contracting is displacing spot market purchasing for electronic-grade volumes. Taiwan's pure-play foundries are locking three-to-five-year supply agreements with fixed purity escalation clauses, transferring inventory risk upstream and compressing working capital cycles for qualified Japanese and North American producers.
Hydrofluoric Acid (HF) for Semiconductor Market Segmentation
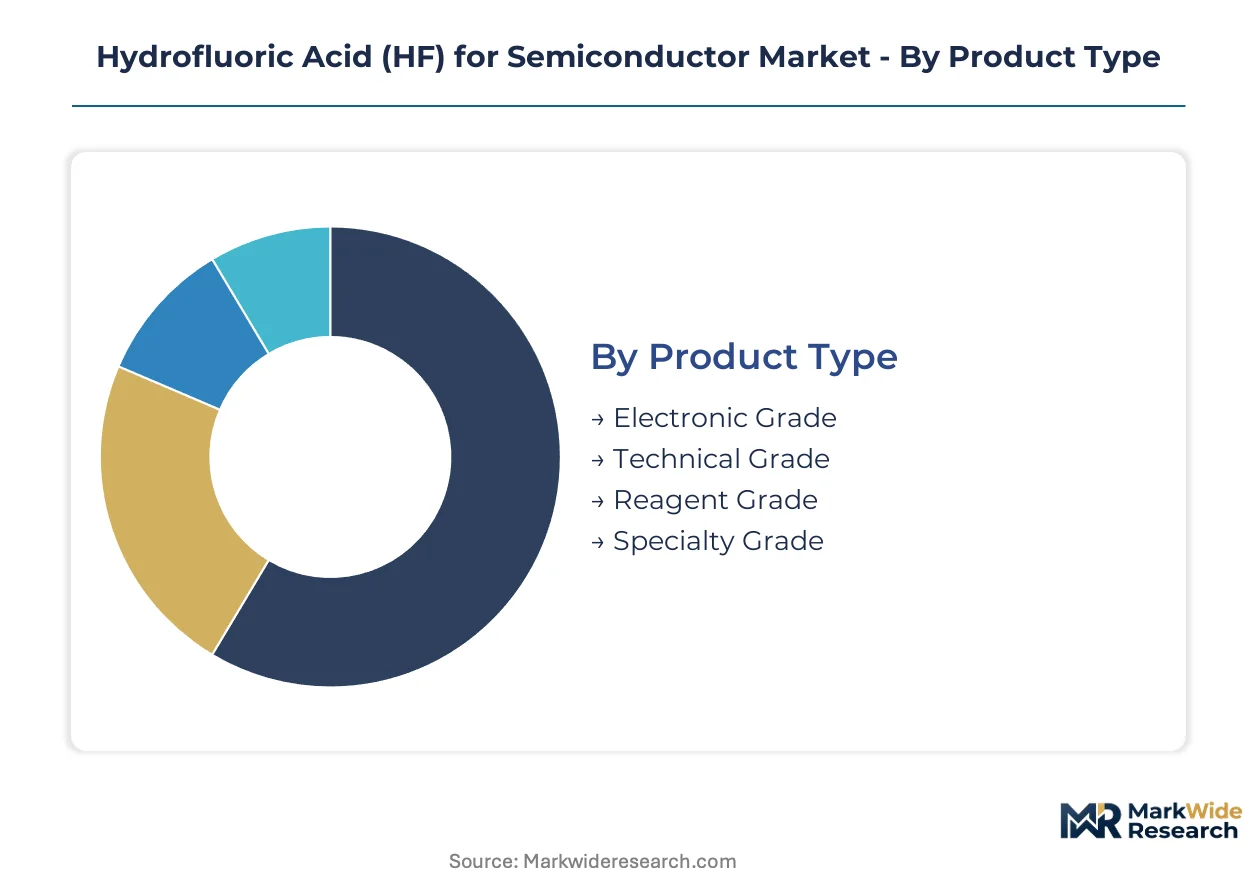
Segmentation in semiconductor-grade HF reveals how capital intensity, purity thresholds, and captive qualification cycles concentrate value capture. Suppliers must align capacity investments with the specific grade and packaging requirements of each downstream segment.
Product Type:
Capital intensity escalates sharply with purity specifications, as sub-ppb metal removal demands multi-stage distillation infrastructure and corrosion-resistant alloys.
- Electronic Grade:Ultra-high-purity aqueous hydrogen fluoride at 49% concentration or higher, manufactured through sub-boiling purification to achieve part-per-trillion metal impurity levels. Taiwan's Hsinchu Science Park cluster sources this grade exclusively for sub-7nm etching and cleaning processes as TSMC and UMC expand 3nm wafer starts.
- Specialty Grade:Formulations engineered for EUV lithography companion processes including post-resist stripping and mask cleaning, commanding premium pricing due to application-specific additive packages. Belgium-based purification expertise positions EU suppliers to capture this premium tier as Brussels enforces stricter fluorochemical sourcing rules.
- Technical Grade:Standard purity for industrial semiconductor applications with less stringent metal content requirements.
- Reagent Grade:Laboratory and analytical applications in research settings with moderate purity specifications.
Most installed capacity flows through Electronic Grade. Expansion is steepest in Specialty Grade.
Application:
Process complexity at advanced nodes is redistributing volume across wet chemistry applications, with trench and gate-stack architectures driving specification tightening.
- Etching:Wet chemical removal of silicon dioxide, silicon nitride, and metal layers through controlled HF exposure, dominating volume absorption as 3nm and 2nm node transitions deepen trench complexity. South Korean foundries are piloting point-of-use purification systems adjacent to wet bench stations to compress logistics exposure for this application.
- Cleaning:Particle and organic residue removal from wafer surfaces prior to subsequent processing steps, gaining share fastest as multi-patterning schemes multiply cleaning cycles per wafer.
- Surface Treatment:Controlled oxide removal and surface preparation for epitaxial growth and deposition processes.
- Deposition:Precursor chemistry and surface activation for thin-film deposition applications.
Etching commands the largest share of qualified supply. Cleaning is climbing the fastest.
End User:
Purchasing power and qualification timelines diverge sharply between captive integrated manufacturers and pure-play foundries.
- Foundries:Pure-play semiconductor manufacturers operating at highest capital intensity per wafer start, representing the fastest-growing demand pool as operators expand sub-7nm capacity. Taiwan's pure-play foundries are locking three-to-five-year supply agreements with fixed purity escalation clauses, transferring inventory risk upstream.
- Integrated Device Manufacturers:Captive fabrication facilities at memory and logic companies with longer internal qualification cycles and greater backward integration into chemical supply.
- Research Institutions:Universities and national laboratories with small-batch requirements and extended procurement timelines.
- OEMs:Equipment manufacturers incorporating HF chemistries into tool cleaning and maintenance protocols.
Integrated Device Manufacturers anchor current volume. Foundries are gaining share fastest.
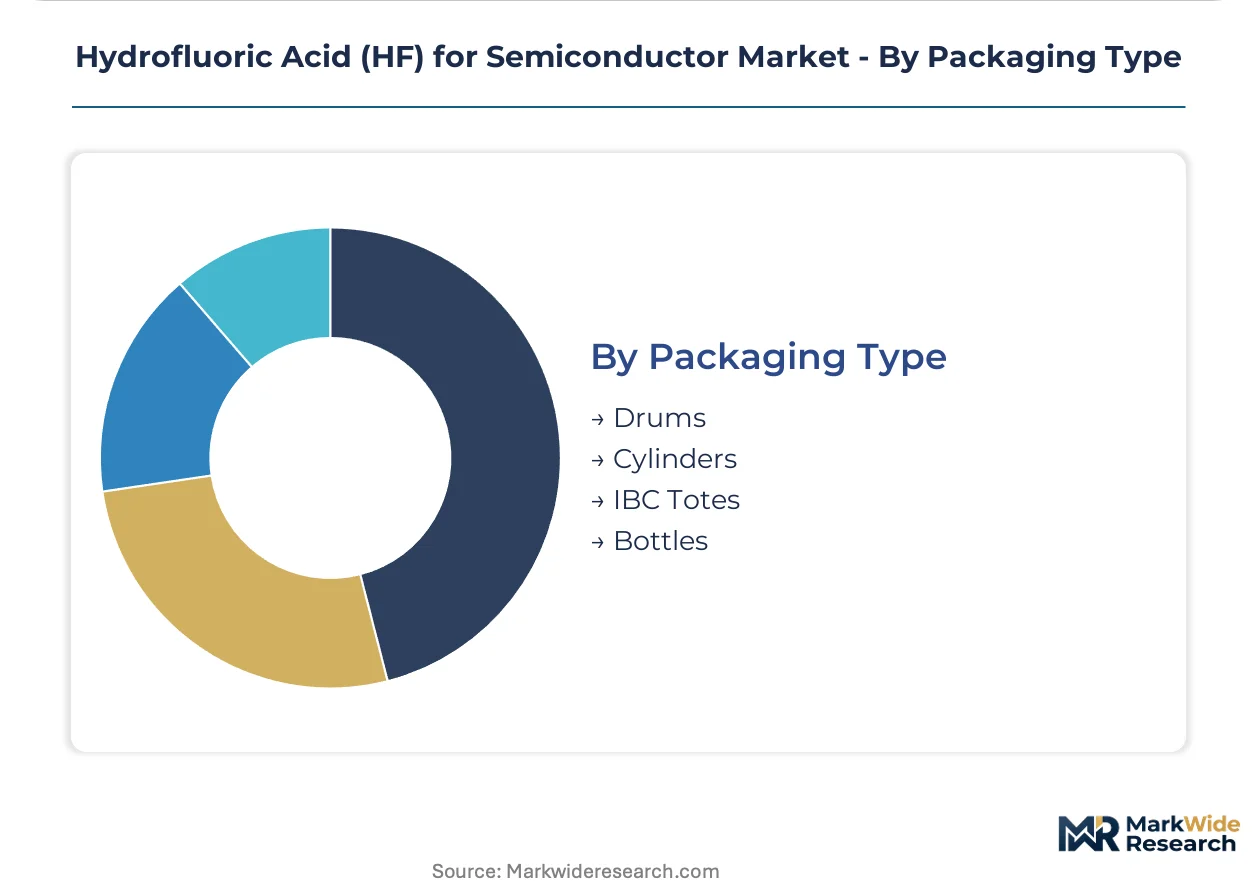
Packaging Type:
Logistics configuration and contamination risk determine packaging selection, with bulk formats dominating high-volume foundry supply.
- Cylinders:High-pressure containment for gaseous or anhydrous HF delivery, preferred by advanced fabs for point-of-use generation systems that minimize storage risk.
- IBC Totes:Intermediate bulk containers for electronic-grade liquid HF, standard for Taiwan and South Korean foundry clusters with dedicated chemical delivery infrastructure.
- Drums:Conventional liquid containment for technical and reagent grade applications with moderate volume requirements.
- Bottles:Small-format packaging for laboratory, research, and sampling applications with strict lot traceability.
IBC Totes handle the majority of electronic-grade volume. Cylinders are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting fluorochemical investment toward jurisdictions with streamlined environmental permitting and established semiconductor clusters, as purification facilities seek cost-of-compliance advantages alongside proximity to advanced fab demand.
Taiwan
TSMC and UMC are expanding 3nm and 2nm wafer starts at the Hsinchu Science Park cluster, generating concentrated pull for part-per-trillion purity HF. The island's environmental regulator enforces wastewater discharge protocols that favor closed-loop recycling investments by qualified suppliers. Tainan and Taichung science parks are adding dedicated chemical delivery infrastructure to support sub-7nm etching and cleaning volumes.
South Korea
Samsung Foundry and SK hynix are deepening trench complexity at Pyeongtaek and Yongin campuses, intensifying consumption of ultra-high-purity acid for gate-stack processing. K-REACH amendments are tightening substance tracking requirements for imported fluorochemicals, elevating compliance overhead for non-integrated suppliers. The Yongin semiconductor cluster is piloting point-of-use purification systems adjacent to wet bench stations.
Japan
Logic and memory fabs in the Kyushu and Tohoku regions are expanding etching requirements as node transitions accelerate. METI guidelines are reshaping cost structures for domestic purification plants through tightened fluorochemical handling standards. The Kanto region around Tokyo anchors specialty-grade formulation expertise for EUV lithography companion processes.
United States
Intel and GlobalFoundries are expanding advanced node capacity in Arizona and New York, creating new demand anchors for electronic-grade HF supply. EPA Risk Management Plan amendments are tightening storage and release reporting thresholds, elevating operational compliance costs for Louisiana production complexes. The Southwest region is attracting on-site generation system investments to minimize bulk storage risk.
China
Domestic foundries including SMIC are expanding mature-node capacity in Shanghai and Beijing, driving captive consumption of locally purified acid. MEE enforcement of wastewater discharge limits is accelerating technology upgrades at Zhejiang and Henan purification facilities. The Yangtze River Delta cluster is consolidating supply relationships for fabs seeking to reduce import dependency.
Hydrofluoric Acid (HF) for Semiconductor Market Competitive Landscape
Japanese producers anchor one tier; North American and European specialists hold differentiated positions in specialty-grade formulations. The market structure concentrates around integrated majors with captive fluorspar access and multi-stage distillation infrastructure, while smaller batch producers face compression from REACH documentation overhead and extended qualification timelines. Three archetypes dominate: vertically integrated miners-to-purifiers, regional production complexes with backward integration into feedstock, and specialty formulators targeting EUV companion processes. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as foundries lock three-to-five-year supply agreements.
Among Japanese integrated producers, Stella Chemifa Corporation and Morita Chemical Industries exemplify the miners-to-purifiers archetype with upstream control over fluorspar through final sub-boiling stages. Honeywell International Inc. anchors North American supply through its Louisiana production complex, representing the regional production archetype with captive infrastructure for electronic-grade volumes. Solvay occupies a position within the specialty-grade tier, leveraging Belgium-based purification expertise for EUV lithography companion chemistries as Brussels enforces stricter fluorochemical sourcing rules.
| Leading Market Players |
|---|
| Stella Chemifa Corporation |
| Honeywell International Inc. |
| Solvay |
| Morita Chemical Industries |
| Formosa Daikin Advanced Chemicals |
| Daikin Industries |
| Sunlit Chemical |
| Zhejiang Kaiheng Electronic Materials |
| Do-Fluoride New Materials |
| Others |
Pricing and Supply Chain Analysis
Pure-play foundries in Taiwan and South Korea concentrate procurement power for electronic-grade HF, compressing supplier margins through multi-year offtake contracts with fixed purity escalation clauses. This buyer concentration elevates contract-based long-term offtake as the dominant pricing model, transferring inventory risk upstream and locking out spot market flexibility for purification facilities.
Pricing Analysis
Distributor margins for specialty-grade formulations capture premium spreads over electronic-grade base chemistries, reflecting application-specific additive packages and EUV lithography companion process certification. Price differentiation rests on purity grade certification and volume scale, with sub-ppb metal removal commanding substantial premiums over standard electronic-grade specifications. Cost compression in technical-grade tiers is intensifying because Chinese domestic suppliers expand purification capacity under MEE wastewater enforcement. Memory fabs exhibit highest price sensitivity due to cyclical capital expenditure constraints, while leading logic foundries prioritize supply security over unit cost.
Supply Chain Analysis
Direct-to-foundry channels handle high-volume electronic-grade demand from Taiwan's Hsinchu Science Park cluster and South Korea's Yongin semiconductor complex, bypassing distributor layers for qualified suppliers. Geographic supply concentration centers on Japan, the United States, and Belgium, with purification infrastructure anchored by Stella Chemifa's fluorspar-to-final-distillation integration, Honeywell's Louisiana production complex, and Solvay's specialty-grade formulation expertise. Raw material dependencies draw from acid-grade fluorsspar mining, corrosion-resistant alloy fabrication for distillation columns, and high-purity water sourcing. Single-source vulnerability from Chinese fluorspar export quota volatility elevates supply chain risk. Distribution runs through dedicated chemical delivery infrastructure at science park clusters, with IBC totes standard for liquid HF and cylinders expanding for point-of-use generation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phase-down mandates function as a regulatory compounder, redirecting fluorochemical capacity toward semiconductor-grade acid production and securing dedicated supply lines for advanced fabs while tightening environmental compliance costs for purification facilities.
For Market Incumbents: To counter emerging Chinese domestic suppliers expanding under MEE enforcement, Stella Chemifa and Honeywell should deepen backward integration into fluorspar mining and accelerate corrosion-resistant alloy R&D for sub-boiling purification infrastructure. Capacity addition in the US Southwest region addresses EPA Risk Management Plan compliance costs through on-site generation system deployment. For New Entrants and Emerging Players: Enter via India's Gujarat and Karnataka fab construction sites under PLI incentives, where virgin demand territory lacks established supplier relationships and qualification cycles remain open. Target EUV lithography companion process formulations as the most penetrable application tier, leveraging membrane-based purification modularization for lower capital entry barriers. For Investors and Strategic Acquirers: Chemical majors with existing fluorochemical infrastructure represent the most active acquirer category in this space, seeking electronic-grade purification capabilities to offset F-Gas Regulation revenue displacement. Long-term viability over a multi-year horizon hinges on captive fluorspar access and multi-stage distillation qualification at leading foundries. Monitor K-REACH amendment enforcement timelines as the critical inflection indicator for non-integrated supplier margin compression in South Korea.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Taiwan's pure-play foundries lock three-to-five-year contracts with fixed purity escalation clauses. |
| Backward Integration | Japanese producers secure fluorspar mining access to buffer Chinese export quota volatility. |
| Capacity Expansion | Louisiana production complexes add sub-boiling purification trains to serve Arizona and New York fab construction. |
| Joint Venture | Belgium-based specialty-grade expertise partners with EU suppliers to capture EUV lithography companion chemistry premiums. |
| Green Manufacturing Transition | Closed-loop recycling architectures displace centralized bulk delivery models at South Korean pilot sites. |
Research Methodology
Coverage spans Taiwan, South Korea, Japan, the United States, and China, with primary inputs from each region combining interviews with plant managers at purification facilities, procurement leads at foundries and IDMs, distribution channel partners, and technical R&D directors for corrosion engineering. Secondary validation draws from customs and trade data, SEC 10-K filings for North American producers, METI industrial statistics, and MEE wastewater discharge records. Bottom-up and top-down triangulation cross-checks capacity installation timelines against qualified supply agreements.
Rate-of-change decomposition isolates volume drivers across grade tier, application, end-user category, and packaging format, with additional segmentation by regional production hub regulatory cluster. CAGRs were derived from installed capacity expansion schedules, node transition roadmaps, and offtake contract coverage ratios. Forecast inputs incorporate fluorspar export quota trajectories, EPA Risk Management Plan amendment implementation, and EU F-Gas Regulation phase-down milestones.
Inputs from plant managers, procurement leads, and trade databases were available through the study window; gaps in real-time foundry qualification cycle disclosure introduce uncertainty bands around supplier switching timeline assumptions. Forecasts reflect documented assumptions regarding node transition acceleration and environmental enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Global Silicone Fluid Market
Industrial Chemicals
Global Low GWP Refrigerants Market