
 Middle-East and Africa Surface Treatment Chemicals Market | 2026-2036
Middle-East and Africa Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Surface Treatment Chemicals Market Foresight
Multi-source procurement among metal finishing service providers is expanding across the Gulf states as OEMs diversify supply risk following pandemic-era disruptions. BASF SE leverages its integrated phosphate ester chemistry portfolio to anchor formulations supply for regional automotive plants. Henkel AG and Co. KGaA sustains technology leadership in thin-film pretreatment systems optimized for aluminum-intensive vehicle architectures. SurTec International GmbH competes through specialized zirconium-based conversion coatings that eliminate heavy metal effluent concerns.
Surface treatment chemicals encompass formulated preparations applied to metallic substrates to modify surface properties through cleaning, activation, conversion coating, or final finishing, typically operating within pH ranges of 2.0 to 12.0 and bath temperatures between 25°C and 95°C depending on process chemistry. These formulations serve primarily to enhance adhesion, corrosion resistance, wear performance, or electrical conductivity in downstream manufacturing operations. Corrosion inhibitors represent the most mature product category with established pricing benchmarks, while coatings capture differentiated margin pools through customized polyurethane and epoxy formulations for offshore oil infrastructure. Electroplating technology dominates volume consumption across the region's jewelry and electronics connector industries, though phosphating is displacing older iron phosphate systems in automotive pretreatment lines as OEMs adopt zinc phosphate standards for enhanced paint adhesion durability.
Saudi Arabia's SASO technical regulations and South Africa's NRCS compulsory specifications shape product registration requirements and chemical composition disclosures for imported surface treatment formulations. The UAE's Emirates Authority for Standardization and Metrology enforces Gulf Standard GSO 1928 restrictions on hazardous substance content in metal finishing chemicals, directly influencing formulation reformulation investments by suppliers seeking market access. Stakeholders must monitor the trajectory of Gulf Cooperation Council unified chemical registration frameworks and their convergence with EU REACH hazard classification protocols to anticipate compliance cost structures and qualification timelines for new product introductions.
Market Dynamics
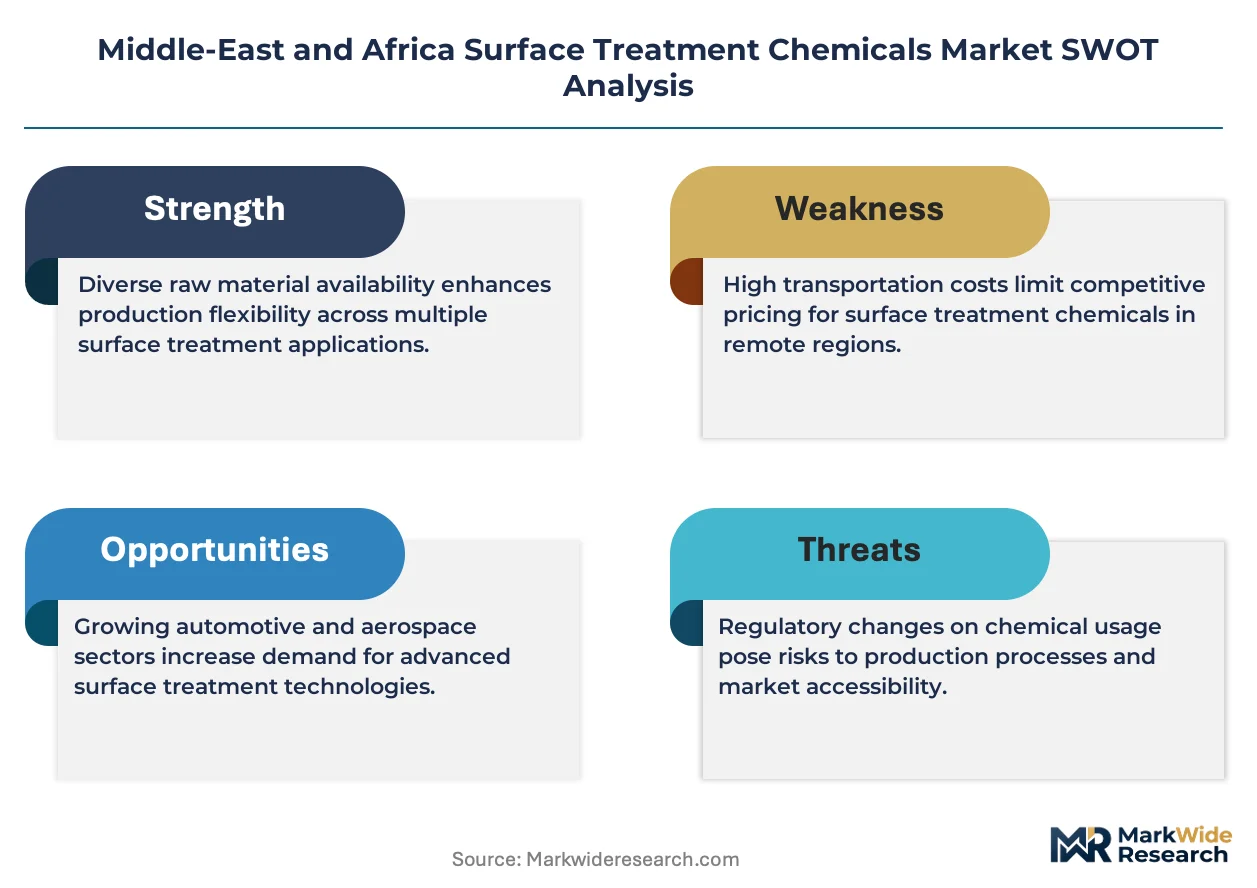
REACH-aligned regulatory harmonization across Gulf Cooperation Council states is forcing wholesale reformulation of hexavalent chromium systems toward trivalent passivation chemistries, compressing qualification timelines and redrawing supplier competitive positions.
Growth Catalysts
- Automotive OEM Expansion:Saudi Arabian and UAE vehicle manufacturers are expanding phosphate conversion coating capacity for chassis corrosion protection, pulling demand for zinc phosphate pretreatment systems.
- SASO Technical Regulations:Saudi Arabia's mandatory product registration framework is accelerating chemical composition disclosures, creating first-mover advantages for compliant formulation suppliers.
- Mining Equipment Refurbishment:South Africa's deep-level mining sector consumes substantial abrasive blast cleaning and protective coating volumes, anchoring regional pretreatment chemical demand.
Market Restraints
- Petrochemical Feedstock Volatility:Phosphate ester and solvent raw material costs fluctuate with regional hydrocarbon pricing, compressing formulation margin stability.
- Import Concentration Risk:Gulf states rely heavily on European and Asian chemical suppliers, exposing end-users to shipping disruption and currency fluctuation.
- Effluent Treatment Limitations:Existing wastewater infrastructure in secondary cities cannot handle heavy metal-laden rinse waters from conventional conversion coating lines.
Strategic Opportunities
- Egyptian Manufacturing Uplift:New automotive assembly investments in Suez Canal Economic Zone create greenfield demand for thin-film pretreatment systems optimized for aluminum body panels.
- Zirconium Conversion Coatings:Heavy metal-free chemistries eliminate effluent treatment burdens while meeting GSO 1928 hazardous substance restrictions.
- Digital Formulation Services:Remote bath monitoring and predictive chemistry management platforms reduce on-site technical service costs for distributed metal finishing operations.
Industry Challenges
- Specialized Technician Scarcity:Gulf metal finishing operations struggle to recruit qualified process engineers capable of managing multi-stage pretreatment line chemistry.
- REACH-GCC Convergence Complexity:Divergent hazard classification timelines between EU and emerging Gulf unified frameworks create dual-registration cost burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Surface Treatment Chemicals Market |
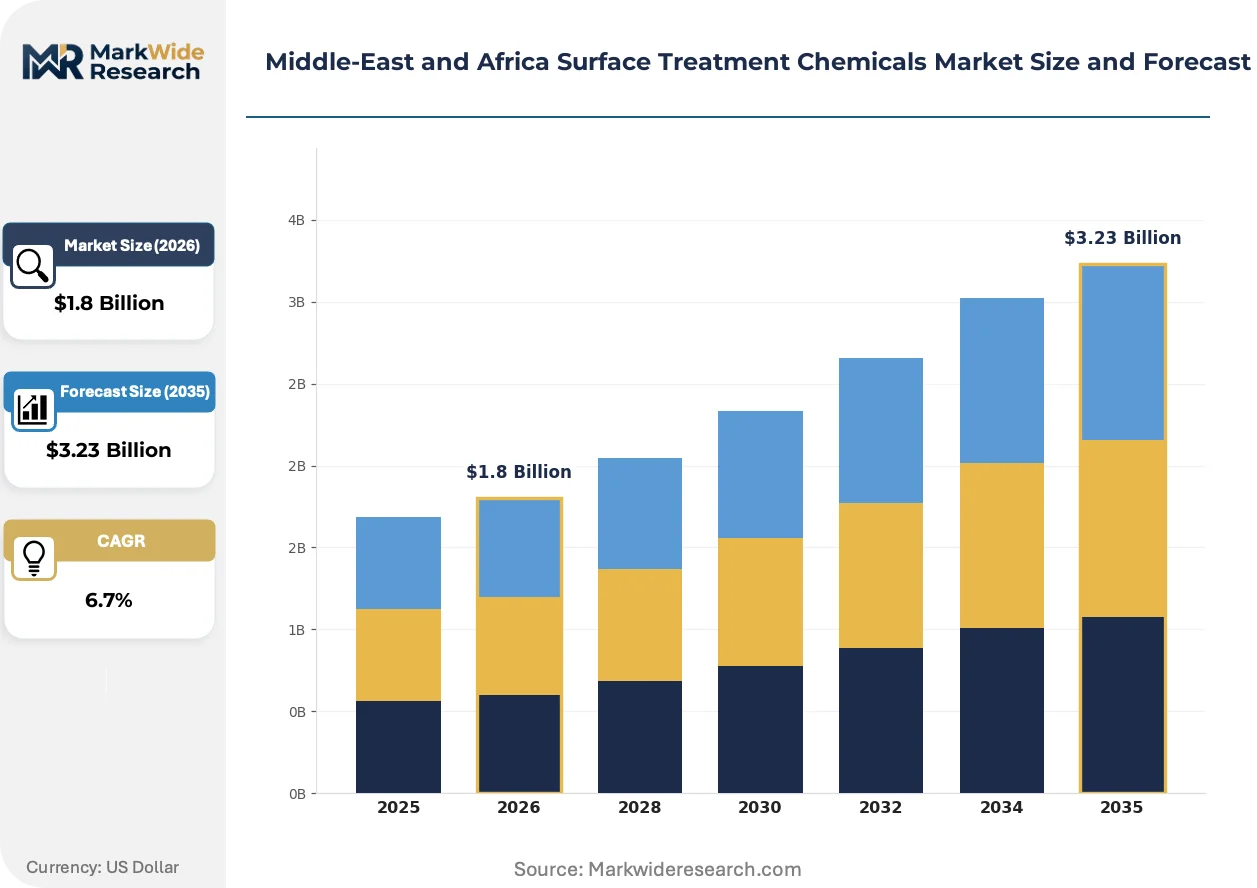
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clearing Agents, Corrosion Inhibitors, Coatings, Primers Application: Aerospace, Automotive, Electronics, Metalworking Technology: Electroplating, Anodizing, Galvanizing, Phosphating End User: Manufacturers, OEMs, Service Providers, Repair Shops |
| Companies Covered | SurTec International GmbH, Akzo Nobel N.V., BASF SE, PPG Industries, DuPont, Henkel AG and Co. KGaA, Chemetall, NOF Corporation, Element Solutions Inc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Surface Treatment Chemicals Market Shifts & Advancements
Formulation science is pivoting toward water-based, low-temperature systems that reduce energy intensity while maintaining adhesion performance on advanced substrate combinations.
Silane-based thin-film technologies are integrating nanoscale surface activation with organic polymer deposition, creating hybrid layers that automotive OEMs in the UAE and Saudi Arabia are adopting for aluminum-intensive vehicle architectures. This convergence is compressing the traditional iron phosphate-to-zinc phosphate transition timeline.
Gulf Standard GSO 1928 restrictions on hazardous substance content are compelling suppliers to accelerate trivalent chromium and zirconium-based system development. Metal finishing service providers across the UAE and Qatar are reallocating capital toward effluent-neutral process lines to maintain market access.
Multi-source procurement patterns now dominate among Gulf metal finishing service providers, with OEMs mandating qualified secondary suppliers following pandemic-era supply disruptions. This behavior is most visible in Saudi Arabia's automotive tier network, where buyers unbundle chemical supply from equipment provider packages.
Middle-East and Africa Surface Treatment Chemicals Market Segmentation
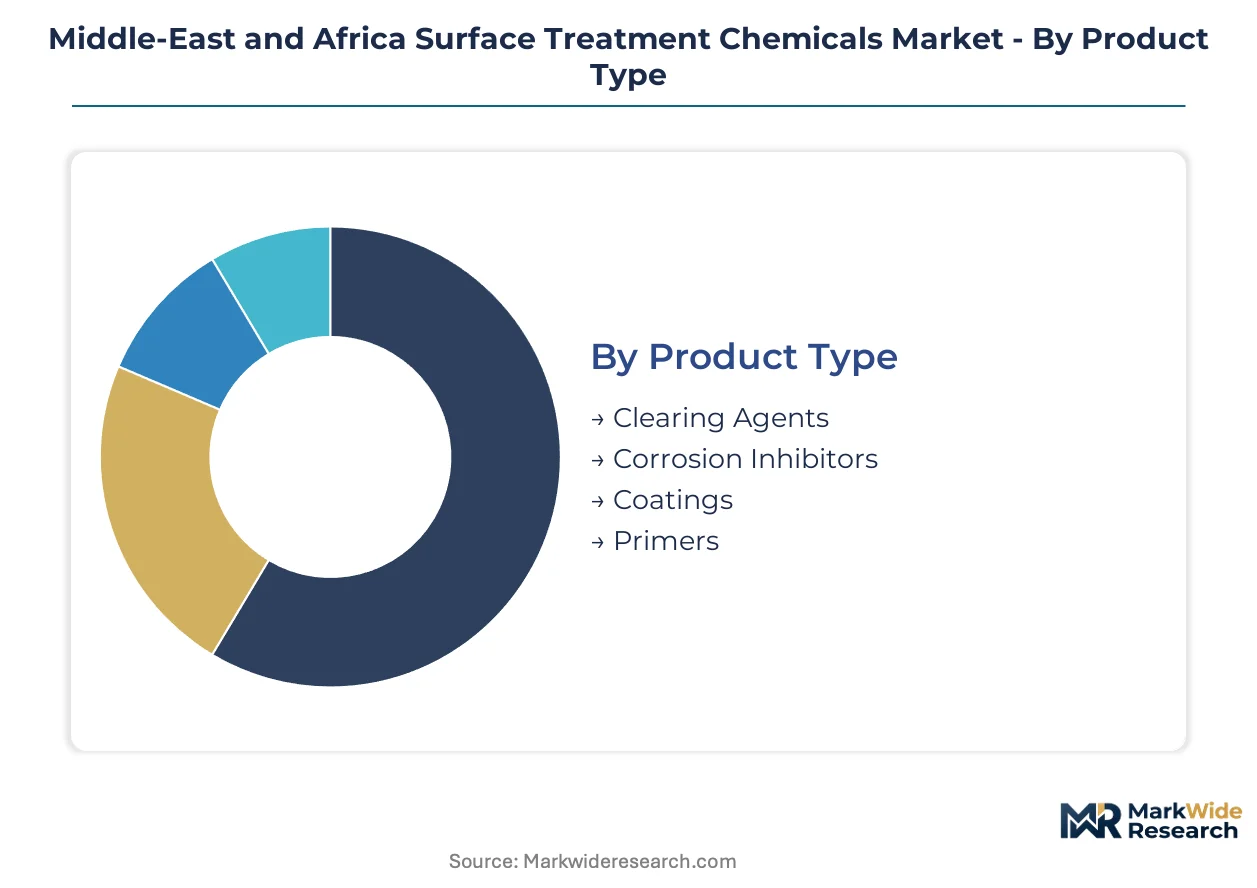
Surface treatment chemicals serve distinct process requirements across the Middle-East and Africa, with formulation chemistry and application method determining specification tiers, regulatory compliance burdens, and supplier qualification pathways for regional buyers.
Product Type:
Chemical functionality defines performance benchmarks and pricing architecture, with active ingredient concentration and substrate compatibility driving procurement decisions among Saudi Arabian automotive plants and South African mining equipment refurbishers.
- Corrosion Inhibitors:These formulations typically incorporate phosphate esters, amine carboxylates, or azole compounds to interrupt electrochemical degradation on ferrous and non-ferrous substrates. Demand concentrates in Saudi Arabia's offshore oil infrastructure sector, where GSO 1928 hazardous substance restrictions are accelerating the shift from chromate-based systems to trivalent passivation chemistries.
- Coatings:Polyurethane, epoxy, and acrylic resin systems deliver barrier protection and aesthetic finishing across industrial and consumer applications. South Africa's mining equipment refurbishment sector consumes substantial volumes of protective coating formulations, where abrasive blast cleaning pretreatment requirements anchor chemical demand cycles.
- Clearing Agents:Alkaline and acidic degreasing formulations remove oils, soils, and oxide layers prior to conversion coating or plating operations.
- Primers:Adhesion-promoting layers bridge substrate surfaces and topcoats, with silane-based thin-film technologies gaining adoption in UAE automotive plants processing aluminum-intensive vehicle architectures.
Corrosion inhibitors lead on scale; coatings lead on momentum.
Application:
End-use sector specifications dictate bath chemistry parameters, with automotive and aerospace OEMs imposing the most stringent qualification protocols on regional chemical suppliers.
- Automotive:Chassis components, body panels, and powertrain parts require phosphate conversion coatings for paint adhesion and corrosion durability. Saudi Arabian and UAE vehicle manufacturers are expanding zinc phosphate pretreatment capacity, pulling demand for manganese-modified and nickel-accelerated systems.
- Metalworking:General fabrication, machinery production, and component finishing consume cleaning agents and conversion coatings across job shop networks. Egyptian manufacturing investments in the Suez Canal Economic Zone are creating greenfield demand for thin-film pretreatment systems.
- Aerospace:Aircraft structural components and landing gear require chromate-free conversion coatings and specialized anodizing chemistries meeting airworthiness certification.
- Electronics:Connector plating and printed circuit board finishing drive electroplating chemical consumption, with Gulf jewelry manufacturers also sourcing precious metal deposition formulations.
Automotive commands the largest volume footprint; metalworking offers the steepest expansion trajectory.
Technology:
Process technology selection determines capital intensity, effluent treatment requirements, and operator skill thresholds for metal finishing operations across the region.
- Phosphating:Zinc and iron phosphate conversion coatings chemically transform metal surfaces into crystalline layers that enhance paint adhesion and corrosion resistance. Automotive OEMs in Saudi Arabia and the UAE are displacing older iron phosphate systems with zinc phosphate standards for enhanced durability.
- Electroplating:Electrochemical deposition of nickel, chromium, zinc, and precious metals delivers decorative and functional surface properties. This technology dominates volume consumption across the region's jewelry manufacturing clusters and electronics connector industries.
- Anodizing:Electrochemical oxidation builds protective oxide layers on aluminum substrates, with sulfuric acid and hardcoat variants serving architectural and aerospace applications.
- Galvanizing:Hot-dip and electro-galvanizing processes apply zinc coatings for steel corrosion protection in construction and infrastructure applications.
Electroplating maintains the broadest installed base; phosphating is gaining share fastest.
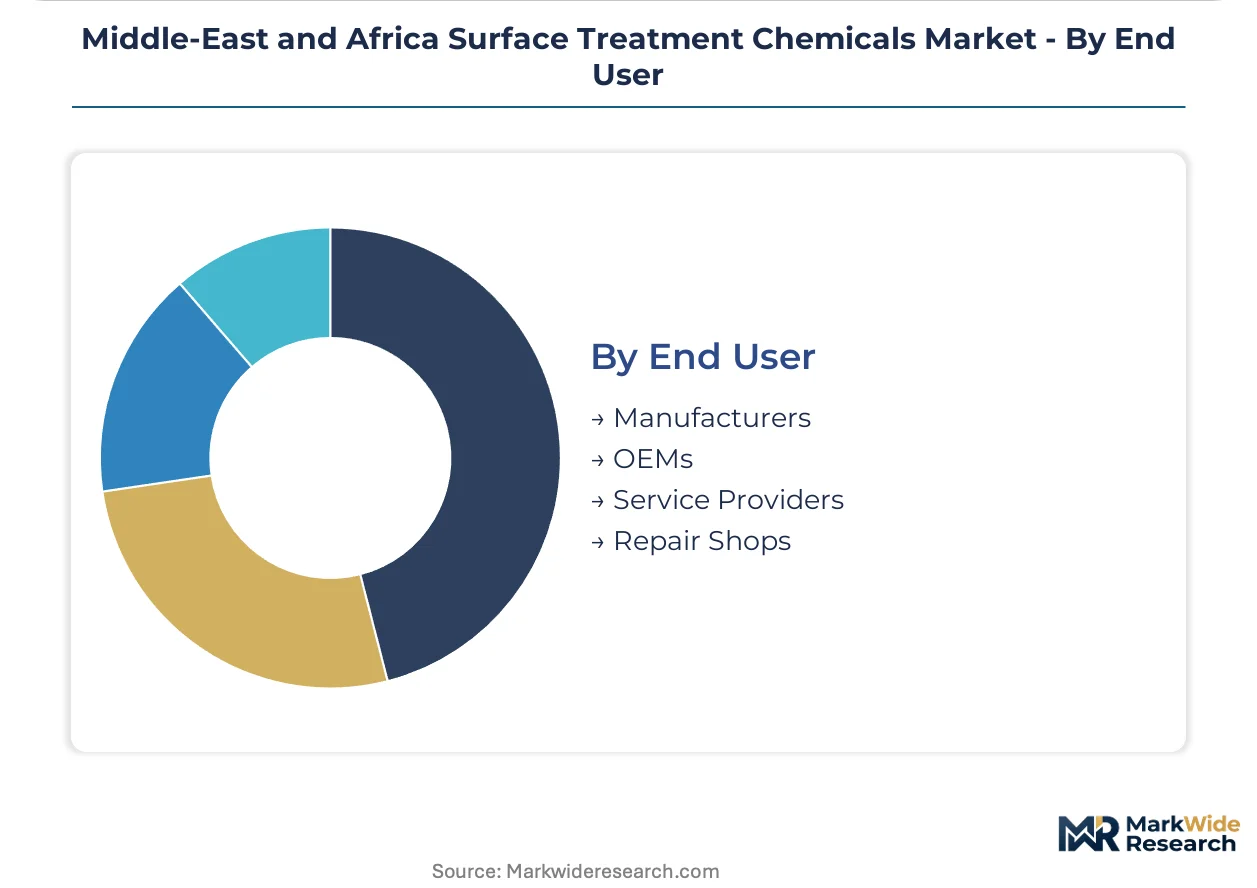
End User:
Customer type shapes purchasing behavior, with OEMs driving formulation standardization and service providers demanding technical support flexibility.
- OEMs:Original equipment manufacturers in automotive, aerospace, and electronics sectors specify qualified chemical systems and audit supplier manufacturing processes. Multi-source procurement mandates are expanding across Gulf automotive tier networks following pandemic-era supply disruptions.
- Service Providers:Independent metal finishing job shops process components for multiple industries, requiring versatile chemistries and responsive technical service. These operators across the UAE and Qatar are reallocating capital toward effluent-neutral process lines to maintain market access under tightening environmental enforcement.
- Manufacturers:Captive surface treatment operations within industrial facilities manage in-house finishing for proprietary components.
- Repair Shops:Maintenance and refurbishment operations consume protective coatings and spot repair chemistries for aftermarket applications.
OEMs dominate value concentration; service providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Eastern Province industrial corridor anchors surface treatment chemical consumption across the Middle-East and Africa, with Jubail's petrochemical complexes and Ras Al-Khair's automotive manufacturing zones driving concentrated demand for phosphate conversion coatings and corrosion inhibitors.
Saudi Arabia
Automotive OEMs in Jubail Industrial City are expanding zinc phosphate pretreatment capacity for chassis corrosion protection. SASO technical regulations mandate chemical composition disclosures for all imported formulations, compressing supplier qualification timelines. Ras Al-Khair's emerging vehicle assembly cluster is pulling demand for thin-film pretreatment systems optimized for aluminum-intensive architectures.
United Arab Emirates
Jebel Ali's metal finishing service providers are reallocating capital toward effluent-neutral process lines under tightening environmental enforcement. Emirates Authority for Standardization and Metrology enforces Gulf Standard GSO 1928 restrictions on hazardous substance content in metal finishing chemicals. Dubai's aerospace maintenance cluster consumes specialized chromate-free conversion coatings for aircraft structural components.
South Africa
Deep-level mining equipment refurbishment operations in Gauteng Province consume substantial abrasive blast cleaning and protective coating volumes. NRCS compulsory specifications shape product registration requirements for imported surface treatment formulations. The Johannesburg-Pretoria industrial corridor anchors regional demand for pretreatment chemicals across mining machinery rebuild centers.
Egypt
New automotive assembly investments in the Suez Canal Economic Zone are creating greenfield demand for thin-film pretreatment systems. The country's national standards body aligns industrial chemical regulations with emerging Gulf Cooperation Council frameworks. Alexandria's port infrastructure supports chemical import logistics for manufacturing operations concentrated in the Delta region.
Qatar
Metal finishing job shops in Doha's industrial area are diversifying procurement sources following pandemic-era supply disruptions. National chemical registration requirements are converging with Gulf unified frameworks and EU REACH hazard classification protocols. Ras Laffan's energy infrastructure maintenance sector consumes corrosion inhibitor formulations for offshore oil and gas assets.
Middle-East and Africa Surface Treatment Chemicals Market Competitive Landscape
Global majors compete with regional champions across formulation technology and regulatory compliance capabilities, creating a tiered structure where integrated chemical conglomerates anchor premium supply contracts while specialized coating houses capture niche applications. Three archetypes dominate: phosphate chemistry specialists with automotive OEM relationships, thin-film pretreatment innovators serving aluminum-intensive vehicle architectures, and heavy metal-free conversion coating developers addressing effluent regulations. Competitive moves concentrate on strategic partnerships with equipment providers and portfolio diversification into water-based, low-temperature systems.
Among Germany-based chemical conglomerates, BASF SE and Henkel AG and Co. KGaA exemplify the integrated formulation supplier archetype, leveraging phosphate ester chemistry portfolios and thin-film pretreatment expertise respectively. SurTec International GmbH occupies a specialist position, representing the heavy metal-free innovation vector through zirconium-based conversion coating development.
| Leading Market Players |
|---|
| SurTec International GmbH |
| Akzo Nobel N.V. |
| BASF SE |
| PPG Industries |
| DuPont |
| Henkel AG and Co. KGaA |
| Chemetall |
| NOF Corporation |
| Element Solutions Inc |
| Others |
Supply & Pricing Matrix
Zinc phosphate system displacement across Saudi Arabian and UAE automotive pretreatment lines simultaneously elevates formulation complexity costs and concentrates supply leverage among integrated phosphate chemistry specialists. This technology transition compresses margin pools for legacy iron phosphate suppliers while rewarding first-movers with trivalent passivation and zirconium-based portfolios.
Pricing Analysis
Phosphate ester and specialty solvent input costs fluctuate with regional hydrocarbon pricing, forcing Gulf formulators to absorb margin volatility or pass through to automotive OEMs via contract escalators. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant trivalent systems from legacy hexavalent formulations and commodity iron phosphate alternatives. Price differentiation hinges on GSO 1928 certification tier and after-sales technical service bundling. Cost compression in standard-tier phosphating is intensifying because South African mining equipment refurbishers prioritize volume procurement over formulation sophistication. Service providers exhibit highest price sensitivity; aerospace OEMs demonstrate lowest.
Supply Chain Analysis
Saudi Arabia's SASO technical regulations and local-content mandates for industrial chemical procurement are reshaping sourcing patterns toward qualified domestic blenders and joint-venture facilities. European and Asian suppliers anchor raw material flows, with phosphate rock concentrates drawing from Morocco, phosphoric acid from China, and specialty amines from Germany. Single-source vulnerability concentrates in zirconium-based conversion coating precursors where qualified alternative suppliers remain limited. Distribution runs through Jebel Ali and Jubail chemical terminals, with last-mile logistics handled by regional distributors holding SASO registration certificates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Automotive OEMs across the Gulf are mandating thin-film pretreatment systems for aluminum-intensive vehicle architectures, elevating specification premiums over commodity alternatives.
For Market Incumbents: Lock in long-term offtake agreements with Ras Al-Khair and Suez Canal Economic Zone automotive plants before qualification timelines compress further. BASF SE and Henkel AG should deepen backward integration into phosphate ester chemistry to defend margin position against feedstock volatility. Certification investment in GSO 1928-aligned trivalent passivation systems represents the critical defensive lever against zirconium-based substitute technologies. For New Entrants and Emerging Players: Enter via Egyptian thin-film pretreatment demand in the Suez Canal Economic Zone, where greenfield automotive assembly investments lack incumbent supplier relationships. Qatar's metal finishing job shops offer secondary penetration potential given pandemic-era supply disruption memories and multi-source procurement mandates. A technical service partnership model with regional equipment providers accelerates market access without SASO registration delays. For Investors and Strategic Acquirers: Roll-up economics work for specialized zirconium-based conversion coating developers because heavy metal-free regulatory tailwinds are consolidating fragmented regional formulators into acquirable targets. The 5-10 year viability window favors platforms with REACH-GCC dual-registration capabilities and automotive OEM qualification track records. The signal to watch is Emirates Authority for Standardization and Metrology enforcement intensity against non-compliant effluent discharges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Ester Chemistry | BASF SE secures captive supply of critical automotive pretreatment raw materials against hydrocarbon-linked volatility. |
| GSO 1928 Certification Investment | Henkel AG accelerates trivalent chromium system registration to maintain UAE market access under tightening hazardous substance enforcement. |
| Joint Venture with Domestic Blenders | SurTec International GmbH satisfies Saudi local-content requirements while preserving formulation IP control. |
| Digital Bath Monitoring Platform Launch | Regional service providers reduce on-site technical service costs for distributed metal finishing operations. |
| Long-term Supply Agreement with Suez Canal Plants | Thin-film pretreatment specialists anchor greenfield Egyptian automotive demand before incumbent qualification. |
Research Methodology
Coverage spans Saudi Arabia, UAE, South Africa, Egypt, and Qatar, with primary inputs from each market's automotive OEM procurement directors, metal finishing service provider plant managers, phosphate ester distribution channel partners, and technical R&D directors at formulation suppliers. Secondary validation drew from SASO registration databases, Gulf Standard GSO 1928 technical specifications, customs and trade flow records, and SEC 10-K filings of listed chemical conglomerates. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Rate-of-change decomposition anchored the analytical framework, with CAGRs derived from segment-level volume trajectories across product type, application technology, and end-user archetype dimensions. The modeling period incorporated automotive production forecasts, mining equipment refurbishment cycles, and regulatory compliance timeline assumptions. Industry-specific inputs included phosphate conversion coating line expansion announcements and REACH-GCC harmonization progress indicators.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time effluent treatment cost data for secondary Gulf cities introduce uncertainty bands around service provider adoption forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Synthetic Gypsum Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market