
 Aerosol Refrigerants Market | 2026-2036
Aerosol Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Refrigerants Market Intelligence
Specialized fluorochemical engineering talent is rotating toward low-global-warming-potential formulation centers as legacy chlorofluorocarbon expertise depreciates under environmental mandates. Honeywell International Inc. leverages its fluorine chemistry heritage to sustain leadership in hydrofluorocarbon alternatives. Daikin Industries, Ltd. anchors Asia-Pacific production networks through captive refrigerant manufacturing and regional distribution infrastructure. Arkema differentiates via proprietary hydrofluoroolefin platforms that target automotive and commercial cooling retrofit demand.
Aerosol refrigerants comprise liquefied gas propellants—typically halogenated alkanes, hydrocarbons, or fluorinated olefins—packaged under pressure in metal canisters for targeted discharge into sealed cooling systems, with formulations specified by vapor pressure curves, purity grades above 99.5 percent, and compatibility with compressor lubricant chemistries. Hydrofluorocarbons still dominate installed base recharge volumes though hydrocarbons represent the fastest-growing product category as flammability standards relax in specific commercial segments. Application demand concentrates in automotive cooling where do-it-yourself recharge culture sustains retail channel throughput, while commercial refrigeration margin pools sit with wholesale distributors serving certified technician networks.
The EPA Significant New Alternatives Policy and the EU F-Gas Regulation together restrict high-GWP aerosol propellant formulations, forcing reformulation investments and reshaping import eligibility across North American and European markets. China's MEE enforces parallel dual carbon goals that tighten domestic production quotas and redirect export volumes. Stakeholders must monitor regulatory divergence between phasedown schedules to anticipate stranded inventory risk and align regional product registrations with divergent compliance timelines.
Market Dynamics
Refrigerant chemistry is pivoting under synchronized regulatory pressure from the EPA Significant New Alternatives Policy and the EU F-Gas Regulation, forcing manufacturers to abandon high-GWP propellant formulations mid-product-lifecycle.
Growth Catalysts
- Building Retrofit Cycles:HVAC contractors are accelerating equipment replacement timelines across aging commercial and residential cooling infrastructure in the United States.
- EPA SNAP Mandates:The agency's phasedown schedule is redirecting formulation investment toward hydrofluoroolefin blends with dramatically lower global warming potential.
- Hydrocarbon Propellants:Flammability standard revisions in select commercial segments are unlocking demand for propane and isobutane-based aerosol formulations.
Market Restraints
- Fluorochemical Feedstock Concentration:Specialty fluorine gas production clusters in China and the United States, creating supply vulnerability during export quota enforcement periods.
- Reformulation Capital Intensity:Transitioning from hydrofluorocarbon to hydrofluoroolefin platforms requires retooling of pressurized packaging lines and purity verification systems.
- Technician Certification Gaps:Hydrocarbon handling protocols demand new safety training modules that wholesale distributors struggle to deploy at sufficient scale.
Strategic Opportunities
- Automotive Aftermarket Channel:Do-it-yourself recharge culture in the United States sustains retail throughput for small-format canister products.
- Commercial Refrigeration Retrofit:Supermarket and cold-chain operators face mandatory equipment upgrades under tightening state-level refrigerant management rules.
- Dual Carbon Alignment:China's MEE production quotas are redirecting export volumes toward markets with compatible environmental compliance timelines.
Industry Challenges
- Formulation Talent Scarcity:Legacy chlorofluorocarbon expertise is depreciating faster than universities and technical institutes can produce low-GWP propellant chemists.
- Stranded Inventory Risk:Divergent phasedown schedules between the EPA SNAP program and EU F-Gas Regulation create misaligned product registration timelines.
- Compressor Lubricant Compatibility:New propellant chemistries require verification against polyolester and polyalkylene glycol oil specifications across multi-brand equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Refrigerants Market |
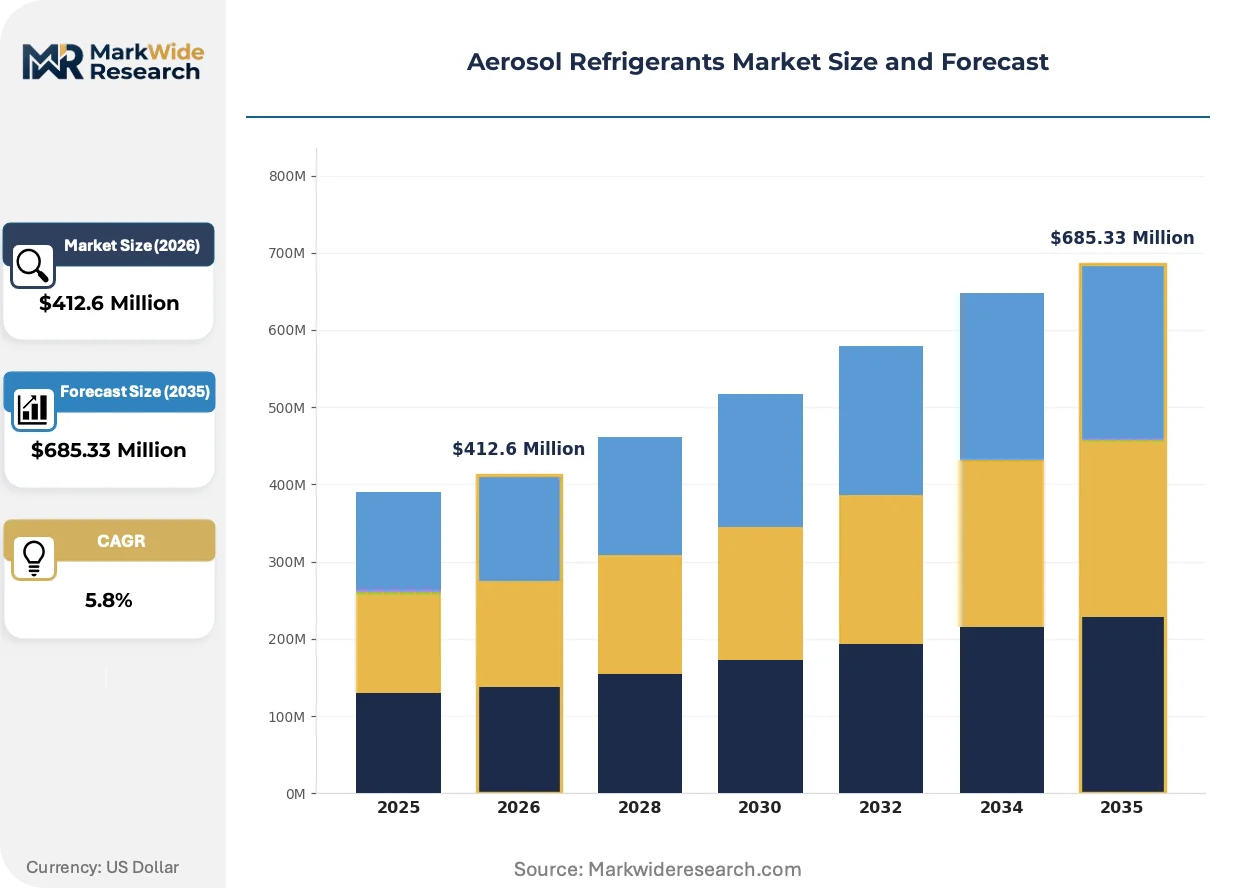
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorofluorocarbons, Hydrofluorocarbons, Hydrocarbons, Others Application: Automotive Cooling, Residential Cooling, Commercial Refrigeration, Industrial Refrigeration End User: Households, Automotive Manufacturers, HVAC Contractors, Refrigeration Installers Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Distributors |
| Companies Covered | Honeywell International Inc., Daikin Industries, Ltd., Solvay, Arkema, Sinochem Lantian Co., Ltd., The Chemours Company, A-Gas International Limited, AGC Inc., Dongyue Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Refrigerants Market Strategic Shifts & Innovations
Pressurized packaging technology is compressing product footprints while regulatory chemistry constraints are fragmenting formulation strategies across jurisdictional boundaries.
Micro-canister dispensing systems are miniaturizing. These sub-8-ounce aluminum containers target residential automotive recharge applications where storage space and handling convenience dominate purchase decisions. Retail channel buyers in the United States are adopting these formats at accelerating velocity. The technology is miniaturizing distribution logistics, enabling direct-to-consumer shipment models that bypass traditional wholesale refrigeration supply chains.
The EU F-Gas Regulation is tightening bulk import quotas for high-global-warming-potential refrigerants while mandating leak detection systems in commercial equipment. European formulators are accelerating hydrofluoroolefin blend registrations to maintain market access. Automotive service chains across Germany and France are retraining technician networks to handle flammability-classified propellants under revised safety protocols.
Certification-driven procurement preferences are displacing price-first buying patterns among commercial refrigeration operators. Third-party environmental performance verification is becoming a gatekeeper criterion for distributor selection in the United States. Large-format retail and foodservice chains now require documented carbon footprint data alongside traditional purity and pressure specifications. This shift is most visible in California and New York state procurement frameworks.
Aerosol Refrigerants Market Segmentation
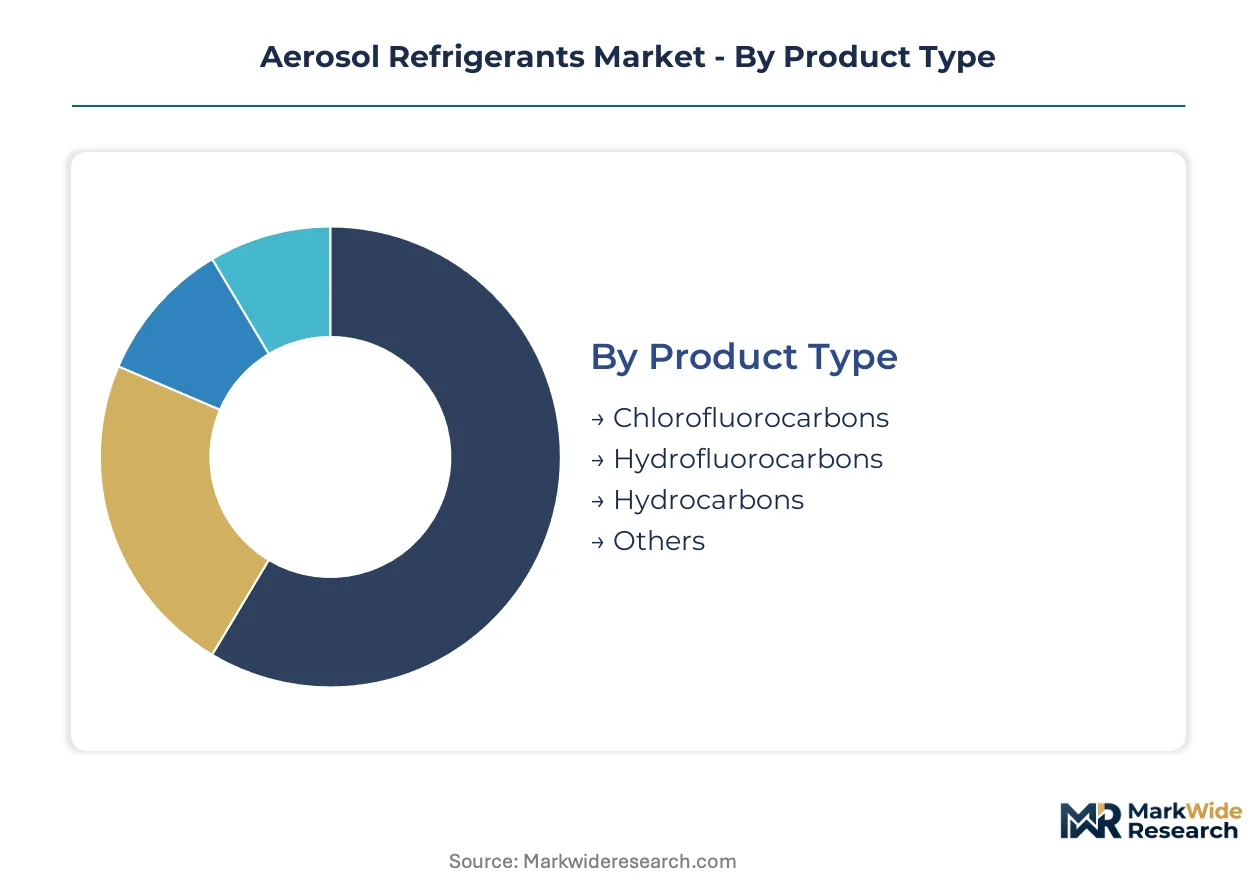
Segmentation in aerosol refrigerants reveals how formulation chemistry, equipment compatibility, and channel economics fragment margin capture across the value chain. Each dimension carries distinct regulatory exposure and capital intensity profiles that reshape competitive positioning.
Product Type:
Hydrofluorocarbon formulations command the largest margin pools through entrenched recharge volumes in legacy cooling systems, though regulatory depreciation is compressing pricing power.
- Hydrofluorocarbons:These halogenated alkane blends dominate current installed base maintenance with vapor pressure curves calibrated to existing compressor specifications. Demand concentrates in United States automotive aftermarket recharge where do-it-yourself culture sustains retail throughput despite EPA SNAP phasedown pressure.
- Hydrocarbons:Propane and isobutane formulations are gaining commercial traction as flammability standards relax in select European commercial segments. Germany and France lead technician retraining investments to handle these A3-classified propellants under revised safety protocols.
- Chlorofluorocarbons:Legacy formulations persist in limited developing market applications where Montreal Protocol phaseout timelines lag advanced economies.
- Others:Hydrofluoroolefin platforms and emerging fluorinated olefin blends occupy pre-commercial registration stages across multiple jurisdictions.
Hydrofluorocarbons hold installed capacity. Hydrocarbons are rotating up the share rankings.
Application:
Volume concentration varies sharply by cooling system scale, with smaller-format equipment enabling aerosol delivery economics that bulk refrigerant logistics cannot match.
- Automotive Cooling:Passenger vehicle air conditioning recharge represents the highest-velocity application, with small-canister formats targeting driveway maintenance culture. United States retail channels move substantial unit volumes through auto parts stores and mass merchants.
- Commercial Refrigeration:Supermarket and cold-chain operators generate premium margin pools through certified technician networks, though leak detection mandates under EU F-Gas Regulation are accelerating equipment replacement over recharge economics.
- Residential Cooling:Window unit and ductless mini-split maintenance drives seasonal demand spikes in warm-climate United States markets.
- Industrial Refrigeration:Large-scale cold storage and process cooling applications favor bulk refrigerant delivery, limiting aerosol penetration to emergency leak repair scenarios.
Automotive Cooling anchors current volume. Commercial Refrigeration is climbing the fastest as retrofit cycles accelerate.
End User:
Procurement authority sits with technically credentialed intermediaries for commercial applications, while residential and automotive segments enable direct consumer purchase.
- HVAC Contractors:These technically certified installers command premium pricing for commercial and residential system recharge services, with EPA Section 608 certification requirements creating credential barriers to market entry.
- Households:Do-it-yourself consumers drive high-volume, low-margin retail transactions through auto parts and home improvement channels.
- Automotive Manufacturers:Factory-fill specifications for new vehicle production favor bulk refrigerant contracts with minimal aerosol format relevance.
- Refrigeration Installers:Commercial foodservice and retail cold-chain specialists face tightening state-level refrigerant management rules in California and New York.
HVAC Contractors concentrate commercial margin. Households dominate unit velocity.
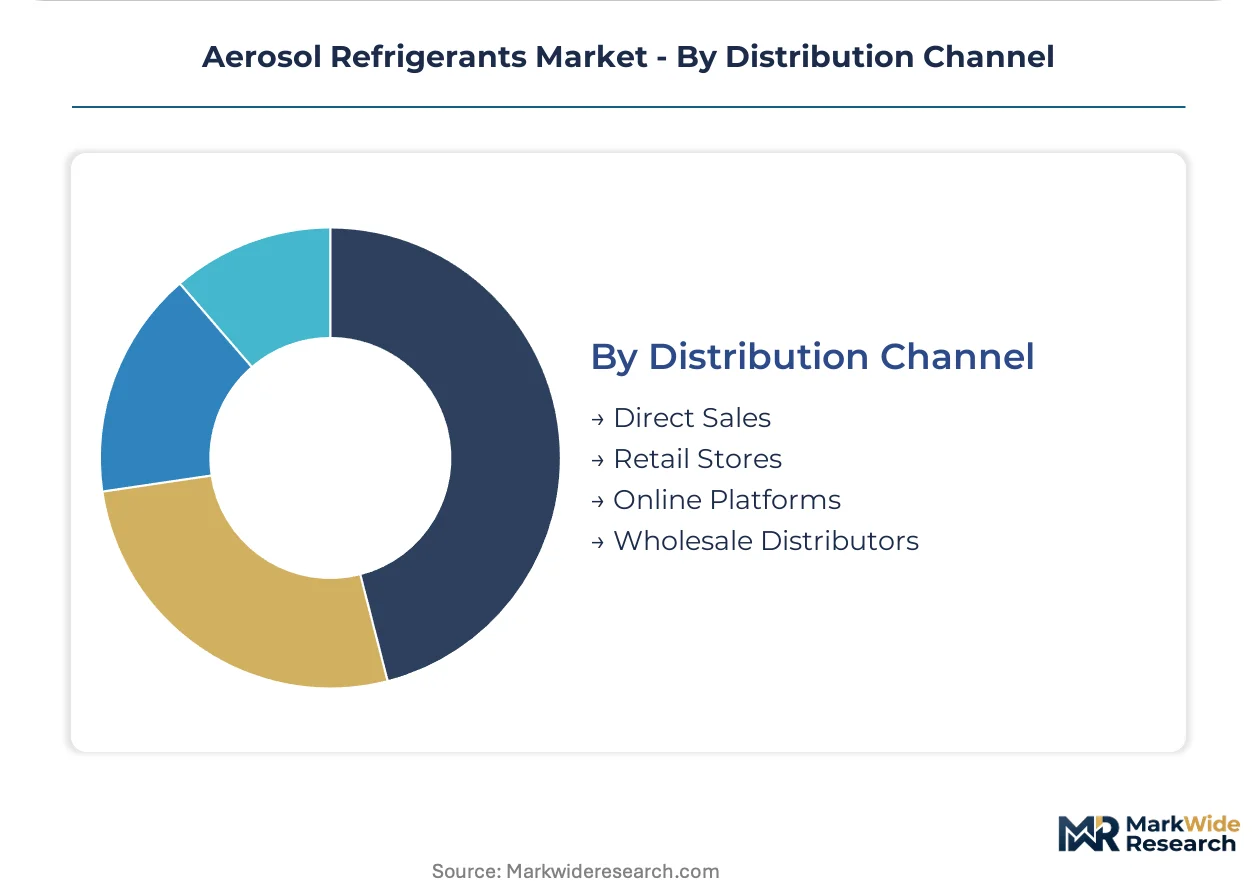
Distribution Channel:
Channel selection determines regulatory compliance burden, with certified technician networks requiring documentation systems that retail formats escape.
- Wholesale Distributors:These intermediaries serving HVAC and refrigeration contractor networks capture margin through technical support services and bulk procurement scale.
- Retail Stores:Auto parts and home improvement channels move high-velocity small-format canisters to consumer self-service applications.
- Online Platforms:Direct-to-consumer shipment models are compressing logistics footprints for micro-canister formats.
- Direct Sales:Manufacturer-to-contractor relationships concentrate in large commercial refrigeration project specifications.
Wholesale Distributors hold contractor relationships. Online Platforms are expanding most quickly in residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA SNAP mandates anchor United States demand as the dominant geography, with regulatory pressure cascading through formulation chemistry decisions across North American supply chains.
United States
Automotive aftermarket recharge volumes and stationary cooling stock turnover sustain aerosol format demand through retail auto parts channels. EPA Section 608 certification requirements create technician credential barriers that concentrate commercial margin with HVAC contractor networks. Texas and Florida markets drive seasonal demand spikes through residential cooling maintenance cycles.
Germany
Commercial refrigeration retrofit demand accelerates under EU F-Gas Regulation leak detection mandates for supermarket and cold-chain operators. KBA safety protocols govern technician retraining investments for flammability-classified hydrocarbon propellants. The Rhine-Ruhr industrial corridor hosts formulation facilities serving pan-European distribution networks.
China
MEE dual carbon goals tighten domestic production quotas and redirect fluorochemical export volumes toward markets with compatible environmental timelines. Yangtze River Delta manufacturing clusters concentrate specialty fluorine gas production capacity. Shanghai-based distributors are expanding regional distribution infrastructure across Southeast Asia.
Japan
METI energy efficiency standards drive equipment replacement timelines in commercial building sectors. Automotive OEM factory-fill specifications favor bulk refrigerant contracts with minimal aerosol penetration. The Kansai region maintains legacy formulation expertise transitioning toward low-GWP propellant platforms.
France
ANSM safety classification revisions enable hydrocarbon propellant adoption in select commercial refrigeration segments. Supermarket operators face mandatory equipment upgrades under tightening national refrigerant management frameworks. The Lyon-Grenoble corridor anchors technician training centers for flammable refrigerant handling protocols.
Aerosol Refrigerants Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Fluorochemical specialists with captive R&D infrastructure command premium positioning in formulation chemistry, while commodity-scale gas processors compete on volume throughput and packaging efficiency. Three archetypes dominate: integrated chemical conglomerates with fluorine heritage, regional packaging specialists with distribution density, and automotive aftermarket brands with retail channel access. Competitive moves concentrate on strategic partnerships for regulatory compliance and capacity expansion for hydrocarbon propellant lines.
Among integrated chemical conglomerates, Honeywell International Inc. and Daikin Industries, Ltd. exemplify technology-forward positioning through fluorine chemistry heritage and captive manufacturing networks. Arkema occupies a specialist tier with proprietary hydrofluoroolefin platform development. These three anchors represent divergent geographic footprints—United States, Japan, and France respectively—reflecting how regulatory proximity shapes competitive strategy in aerosol refrigerant formulation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Daikin Industries, Ltd. |
| Solvay |
| Arkema |
| Sinochem Lantian Co., Ltd. |
| The Chemours Company |
| A-Gas International Limited |
| AGC Inc. |
| Dongyue Group |
| Others |
Cost & Logistics Intelligence
Sixty-day inventory cycles for specialty fluorochemical intermediates expose formulation centers to both feedstock cost spikes and EPA quota enforcement windows, concentrating pricing power with integrated producers while forcing toll-packagers into spot-market vulnerability. This lead-time band compresses margin capture at every supply chain node downstream of fluorine gas production.
Pricing Analysis
United States retail channels command 15-25% premia over European wholesale benchmarks for identical hydrofluorocarbon formulations, reflecting divergent regulatory compliance cost absorption. Contract-based long-term offtake dominates commercial refrigeration procurement, while automotive aftermarket transactions run through spot-adjacent retail formats. Price differentiation separates EPA Section 608-certified contractor grades from uncertified consumer tiers, with brand premiums attaching to Honeywell and Arkema heritage positions. Cost compression in hydrocarbon propellant lines is intensifying because flammability-standard revisions are unlocking competing supply from regional gas processors. Household do-it-yourself buyers exhibit highest price sensitivity, whereas supermarket operators under EU F-Gas retrofit mandates show lowest elasticity due to compliance-driven urgency.
Supply Chain Analysis
China and the United States anchor specialty fluorine gas production, with Yangtze River Delta and Gulf Coast clusters feeding global formulation networks. The supply chain draws from fluorspar mining concentrates, anhydrous hydrogen fluoride, and chlorinated intermediates as critical inputs. Single-source vulnerability concentrates in Chinese export quota enforcement periods, when MEE dual carbon goals redirect domestic production away from international aerosol propellant demand. Distribution runs through wholesale HVAC distributor networks for commercial segments, while retail auto parts channels and direct-to-consumer micro-canister shipment models capture residential and automotive volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerosol refrigerants market rewards players who control scarce low-GWP formulation chemistry capabilities, as universities and technical institutes lag regulatory depreciation timelines for legacy chlorofluorocarbon expertise. This capability gap widens competitive moats for incumbents with captive R&D infrastructure while constraining new entrant scale-up velocity.
For Market Incumbents: Shield margin pools in commercial refrigeration by accelerating hydrofluoroolefin blend registrations ahead of EPA SNAP phasedown deadlines, while capturing stranded inventory risk from competitors with misaligned product timelines. Prioritize backward integration into specialty fluorine gas production to reduce exposure to Chinese export quota volatility under MEE enforcement windows.
For New Entrants and Emerging Players: Technician certification gaps in hydrocarbon handling protocols represent a service-layer gap where incumbents under-serve wholesale distributors struggling to deploy safety training at sufficient scale. Penetrate the United States automotive aftermarket through direct-to-consumer micro-canister shipment models that bypass entrenched wholesale refrigeration supply chains, leveraging online platform economics to compress logistics footprints.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent phasedown schedules between EPA SNAP and EU F-Gas Regulation create recurring product registration windows for formulation specialists with multi-jurisdictional compliance capabilities. Target acquisition profiles center on mid-cap fluorochemical engineers with proprietary hydrofluoroolefin platforms and established automotive OEM relationships. The signal to watch is KBA and ANSM flammability-standard harmonization momentum, which would accelerate hydrocarbon propellant category growth and reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New hydrofluoroolefin production lines in United States Gulf Coast clusters secure EPA SNAP compliance positioning ahead of phasedown deadlines. |
| Backward Integration | Captive fluorspar-to-HF processing reduces exposure to Chinese MEE export quota enforcement and feedstock cost volatility. |
| Long-term Supply Agreement | Fixed-price contracts with supermarket chains under EU F-Gas retrofit mandates lock in commercial refrigeration margin pools. |
| Joint Venture | Regional packaging partnerships with Yangtze River Delta distributors expand Southeast Asia market access under compatible environmental timelines. |
| Green Manufacturing Transition | Low-GWP propellant platform investments align product portfolios with EPA and EU regulatory depreciation trajectories. |
Research Approach
A standing panel of fluorochemical plant managers, HVAC contractor network heads, automotive aftermarket procurement leads, and EPA regulatory affairs specialists provided ongoing calibration against secondary validation sources including customs trade data, ACC refrigerant shipment reports, SEC 10-K chemical segment disclosures, and EU F-Gas Regulation quota tracking databases. This primary stakeholder engagement combined with bottom-up and top-down triangulation across formulation chemistry, packaging format, end-use application, and regional regulatory cluster dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling product type transitions, application penetration curves, and channel shift dynamics. CAGRs were derived from segmented demand build-ups incorporating HVAC retrofit cycle velocity, automotive recharge frequency patterns, and commercial refrigeration equipment replacement timelines under state-level refrigerant management rules.
Underlying assumptions cover regulatory phasedown adherence schedules, flammability standard revision timelines, and feedstock export quota enforcement intensity, with deviation risk concentrated in EPA-EU regulatory divergence and Chinese MEE policy recalibration. Recalibration cycles align with material shifts in EPA SNAP rulemaking, EU F-Gas quota allocations, and MEE dual carbon goal implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market