
 Non-Corrosive Fluxes Market | 2026-2036
Non-Corrosive Fluxes Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Corrosive Fluxes Market Outlook
Market Context
The capital-intensity divergence between integrated flux-chemistry producers and assembly-material distributors is unwinding as OEMs consolidate supplier bases. Henkel AG & Co. KGaA leverages its adhesives and electronics materials platform to bundle flux with underfill and thermal interface products. Indium Corporation specializes in high-purity metal and flux systems for semiconductor packaging, sustaining technical partnerships with advanced substrate manufacturers. Kester anchors North American supply through Illinois Tool Works' industrial distribution network, competing on same-day availability to contract manufacturers.
Technical Definition and Segment Structure
Non-corrosive fluxes are chemical formulations applied to metal surfaces prior to soldering or brazing that clean oxides without leaving acidic residues that degrade electrical continuity; synthetic and water-soluble variants typically activate between 150°C and 350°C and incorporate organic acids or halide-free activator packages. The primary commercial purpose is enabling reliable metallurgical bonds in electronics assembly while eliminating post-joining cleaning steps that consume solvents and labor. Liquid flux dominates electronics high-volume lines where spray or foam application integrates with wave soldering equipment, while paste flux captures margin pools in rework and manual assembly niches where gel viscosity controls placement precision. Bio-based material formulations represent the fastest-growing structural segment as automotive manufacturers impose renewable-content procurement mandates on tier-one electronics suppliers.
Regulatory Framework and Outlook
REACH registration requirements in Europe and RoHS substance restrictions enforced by EU member-state market surveillance authorities shape product formulation roadmaps, forcing halide-free and no-clean chemistry transitions. China's MIIT enforces GB standards for electronic-grade chemicals while SAMR oversees product safety labeling, creating dual compliance obligations for multinationals operating assembly plants in Jiangsu and Zhejiang provinces. Stakeholders must monitor how the EU F-Gas Regulation and evolving state-level chemical disclosure laws in the US reshape raw-material sourcing for synthetic flux bases.
Market Dynamics
REACH compliance deadlines and RoHS directive expansions are forcing simultaneous chemistry reformulation across European supply chains while East Asian electronics clusters absorb the compliance costs through consolidated procurement.
Growth Catalysts
- REACH registration pressure:European ECHA enforcement tightens disclosure requirements for halide-containing formulations, accelerating no-clean flux transitions in German automotive electronics.
- Surface mount density:Miniaturized PCB architectures in Shenzhen assembly plants demand ultra-low residue chemistries that eliminate post-solder cleaning stations.
- Automotive electronics procurement:Tier-one suppliers to BMW and Volkswagen impose renewable-content mandates, pulling bio-based activator formulations into volume production.
Market Restraints
- Specialty resin concentration:Synthetic flux base production clusters in southern China and coastal Japan, exposing buyers to concentrated supply disruption risk.
- RoHS substance friction:EU market surveillance authorities enforce substance restrictions inconsistently across member states, creating compliance cost variance.
- Laser soldering substitution:Selective laser joining systems in aerospace wire harness assembly bypass flux entirely for oxidation-sensitive alloys.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for semiconductor and component assembly create first-mover positioning for halide-free chemistry suppliers in Gujarat and Tamil Nadu.
- EU F-Gas Regulation tailwind:Restrictions on fluorinated greenhouse gases drive solvent-free flux adoption in refrigeration equipment brazing applications.
- Convergence with thermal interface materials:Bundled dispensing systems combining flux with phase-change pads streamline procurement for data center server manufacturers.
Industry Challenges
- Formulation chemistry expertise:Shortage of organic synthesis specialists fluent in both electronics metallurgy and polymer science constrains R&D pipeline velocity.
- Dual certification timelines:Simultaneous GB standard testing in China and UL recognition in North America extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Corrosive Fluxes Market |
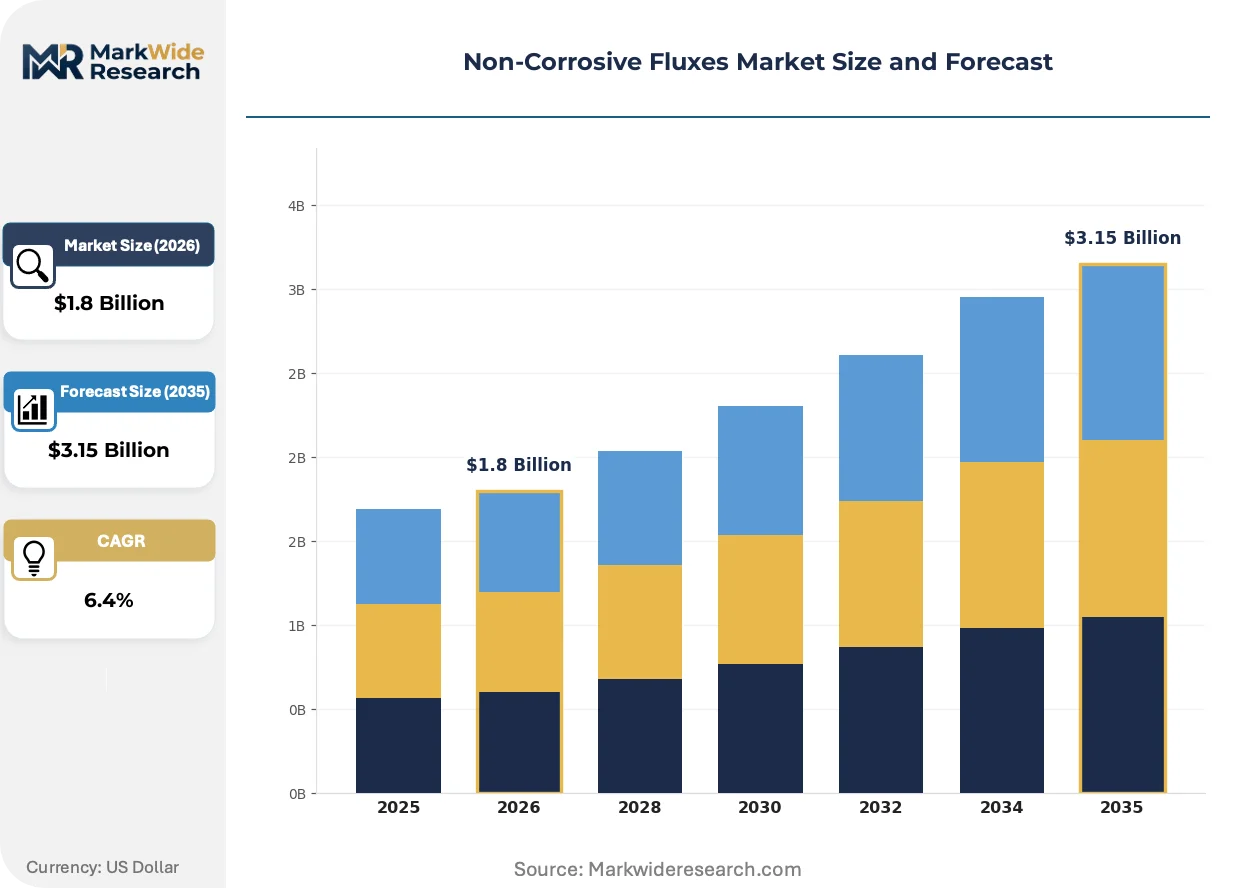
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Flux, Paste Flux, Solid Flux, Gel Flux End User: Electronics Industry, Automotive Manufacturers, Aerospace Sector, Industrial Equipment Application: Soldering, Brazing, Metal Joining, Surface Mount Technology Material: Rosin-based, Water-soluble, Synthetic, Bio-based |
| Companies Covered | Henkel AG & Co. KGaA, Indium Corporation, Kester (Illinois Tool Works Inc.), Alpha Assembly Solutions (MacDermid Alpha), AIM Solder, Nihon Superior Co., Ltd., Solvay Flux GmbH, Lucas-Milhaupt, Inc., The 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Corrosive Fluxes Market Strategic Shifts
Formulation science is diverging along activation temperature and residue chemistry axes as end-use specifications harden, while regulatory disclosure requirements reshape raw-material sourcing transparency.
Low-temperature synthetic fluxes incorporating carboxylic acid activator packages are fragmenting the traditional rosin-based segment. Medical device manufacturers in Switzerland and Germany adopt these formulations to protect heat-sensitive flex circuits during camera module assembly. The technology is fragmenting procurement patterns as OEMs split specifications between legacy high-activation and new low-temperature grades.
EU F-Gas Regulation phase-down schedules are compressing availability of fluorinated solvents used in traditional flux thinning and cleaning operations. Industrial gas suppliers in Belgium and the Netherlands report allocation constraints for HFC-365mfc and HFC-245fa. Electronics subcontractors in Poland and Hungary accelerate water-soluble and no-clean transitions to eliminate solvent dependency.
Consolidated supplier scorecards now weight carbon footprint disclosure alongside technical performance. Automotive electronics buyers in Stuttgart and Wolfsburg require scope-three emissions documentation from flux vendors. Chinese contract manufacturers in Dongguan respond by investing in bio-based feedstock certifications and mass-balance accounting systems.
Non-Corrosive Fluxes Market Segmentation
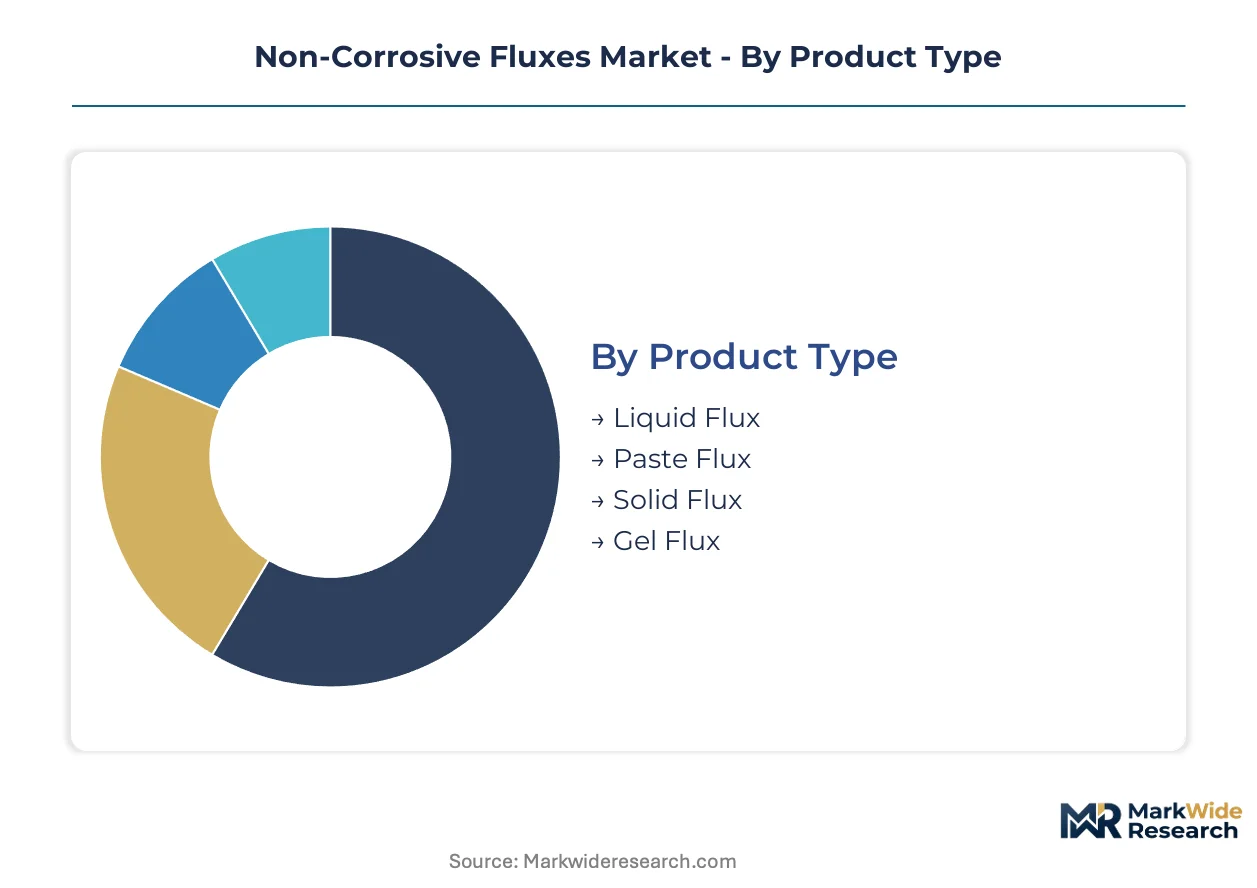
Segmentation in non-corrosive fluxes reveals how formulation chemistry and application method determine procurement patterns across electronics, automotive, and industrial verticals. End-use specifications for residue control, activation temperature, and environmental compliance fragment demand into distinct product-service bundles.
Product Type:
Liquid formulations command the widest margin pools due to integration with high-speed wave soldering lines and automated spray systems in volume electronics assembly.
- Liquid Flux:Low-viscosity formulations enable spray, foam, or wave application in continuous PCB assembly lines. Demand concentrates in Guangdong province surface mount facilities where Henkel and Kester supply integrated dispensing systems. REACH-compliant no-clean variants absorb premium pricing as European automotive electronics procurement tightens residue specifications.
- Paste Flux:Thixotropic gel consistency controls deposition volume in stencil printing and rework operations. Swiss and German medical device manufacturers specify these for heat-sensitive flex circuit assemblies where precise thermal management protects delicate substrates.
- Solid Flux:Bar or wire forms serve manual brazing operations in HVAC and refrigeration equipment manufacturing. EU F-Gas Regulation phase-downs accelerate adoption in Belgian and Dutch industrial gas supply chains.
- Gel Flux:High-viscosity formulations target selective soldering and touch-up applications. Aerospace wire harness assemblers in Poland and Hungary specify gel consistency for controlled placement on oxidation-sensitive alloy terminations.
The dominant share belongs to Liquid Flux, while Paste Flux is closing the gap fastest.
End User:
Volume concentration varies sharply by sector, with automotive procurement now imposing renewable-content mandates that reshape supplier qualification criteria.
- Electronics Industry:Contract manufacturers in Shenzhen and Dongguan drive specification standards for halide-free, no-clean chemistries. Miniaturized PCB architectures demand ultra-low residue formulations that eliminate post-solder cleaning stations entirely.
- Automotive Manufacturers:Tier-one suppliers to BMW and Volkswagen require scope-three emissions documentation and bio-based feedstock certifications. Stuttgart and Wolfsburg procurement teams weight carbon footprint disclosure alongside technical performance in consolidated supplier scorecards.
- Aerospace Sector:Selective laser joining systems in wire harness assembly bypass flux entirely for oxidation-sensitive alloys, constraining addressable market expansion.
- Industrial Equipment:Refrigeration brazing applications absorb water-soluble and synthetic formulations as solvent-free alternatives to fluorinated cleaning operations.
Electronics Industry retains volume leadership, though Automotive Manufacturers demonstrate the steepest specification evolution trajectory.
Application:
Process temperature requirements and metallurgical bond specifications determine formulation selection and create distinct technical moats.
- Soldering:Low-temperature synthetic fluxes with carboxylic acid activator packages protect heat-sensitive components. Medical camera module assemblers in Switzerland and Germany specify these formulations for flex circuit protection.
- Brazing:Higher-activation synthetic and water-soluble chemistries enable copper and brass joint formation in HVAC equipment. F-Gas Regulation compliance pressures accelerate solvent-free adoption.
- Metal Joining:General industrial applications span manual repair through automated production, with residue chemistry determining post-process cleaning requirements.
- Surface Mount Technology:Ultra-low residue no-clean formulations integrate with reflow ovens and wave soldering systems in high-volume Guangdong assembly plants.
Soldering commands the installed base, while Surface Mount Technology absorbs the most advanced formulation development investment.
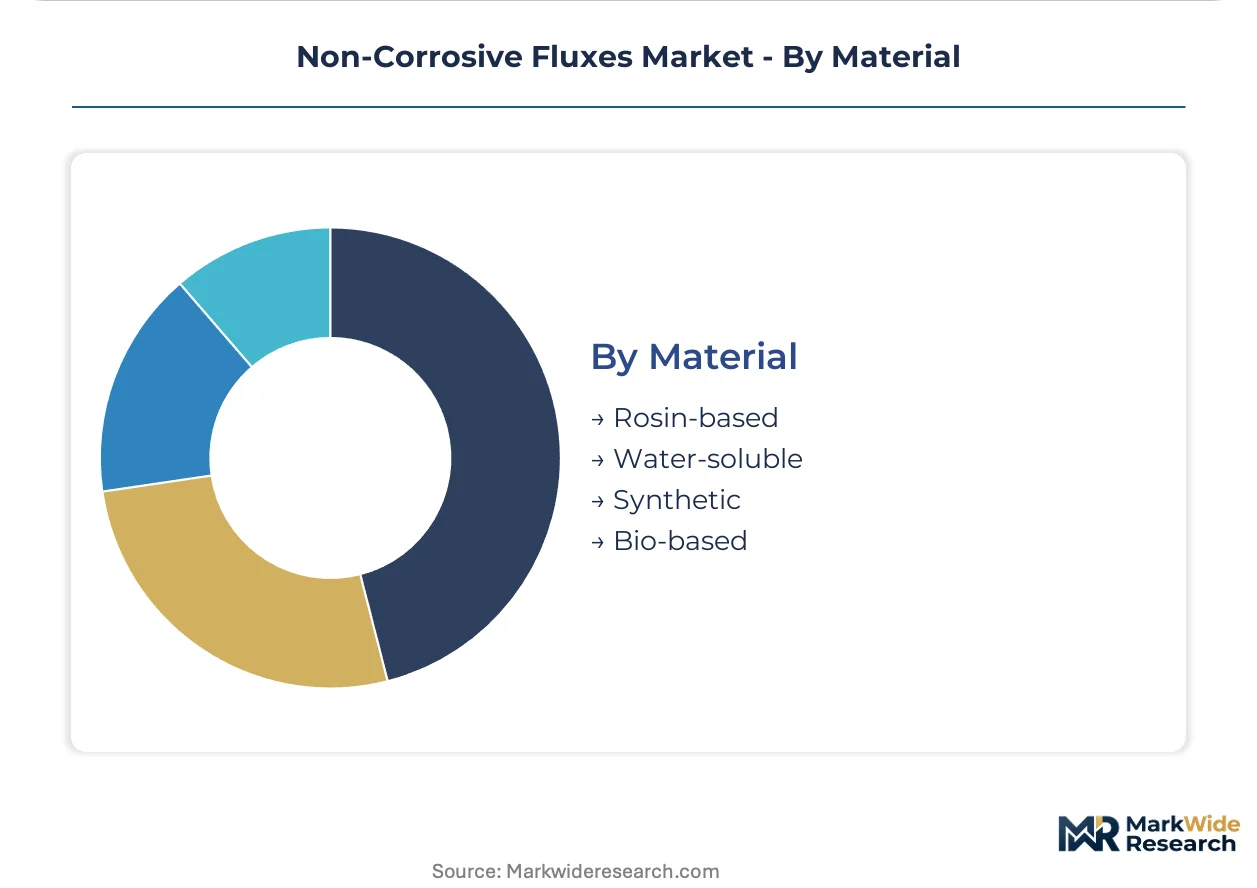
Material:
Feedstock sourcing transparency and renewable-content accounting now influence procurement decisions as automotive mandates cascade through supply chains.
- Rosin-based:Traditional natural resin formulations face displacement as synthetic alternatives offer tighter activation temperature control and consistent supply security.
- Water-soluble:Post-solder cleaning compatibility appeals to aerospace and medical device sectors with stringent ionic contamination limits. Polish and Hungarian subcontractors accelerate transitions to eliminate fluorinated solvent dependency.
- Synthetic:Engineered polymer bases enable precise activation temperature tuning for automated assembly lines. Southern China and coastal Japan production clusters expose buyers to concentrated supply disruption risk.
- Bio-based:Renewable-content formulations derived from plant-derived feedstocks satisfy automotive procurement mandates. Dongguan contract manufacturers invest in mass-balance accounting systems to document scope-three emissions for Stuttgart and Wolfsburg buyers.
Synthetic materials anchor current volume, yet Bio-based formulations are expanding most quickly as regulatory disclosure requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive electronics procurement while Chinese contract manufacturers absorb compliance costs through volume consolidation. This asymmetry reshapes supplier qualification criteria across both regions. Divergent regulatory timelines in Europe and Asia-Pacific create arbitrage opportunities for formulation specialists.
China
Surface mount assembly lines in Guangdong province drive specification standards for halide-free chemistries. MIIT enforces GB standards for electronic-grade chemicals while SAMR oversees product safety labeling. Shenzhen and Dongguan clusters absorb REACH compliance costs through consolidated procurement from integrated flux-chemistry producers.
Germany
Automotive tier-one suppliers to BMW and Volkswagen impose renewable-content mandates and scope-three emissions documentation. ECHA enforcement tightens REACH disclosure requirements for halide-containing formulations. Stuttgart and Wolfsburg procurement teams weight carbon footprint disclosure alongside technical performance in consolidated supplier scorecards.
United States
North American supply chains anchor through Illinois Tool Works' industrial distribution network competing on same-day availability. EPA and state-level chemical disclosure laws reshape raw-material sourcing for synthetic flux bases. Midwest contract manufacturers specify no-clean formulations to eliminate post-solder cleaning stations.
Japan
Advanced substrate manufacturers sustain technical partnerships with high-purity metal and flux system specialists. METI oversees industrial chemical standards while JIS certification requirements fragment procurement patterns. Coastal production clusters for synthetic flux bases expose buyers to concentrated supply disruption risk.
India
PLI scheme subsidies for semiconductor and component assembly create first-mover positioning for halide-free chemistry suppliers. BIS standards for electronic materials run parallel to international certification requirements. Gujarat and Tamil Nadu electronics manufacturing zones attract formulation specialists seeking tariff-advantaged production.
Non-Corrosive Fluxes Market Competitive Environment
Concentration sits with integrated adhesives-and-materials platforms and specialized metal-chemistry producers. The vendor base splits between diversified industrial conglomerates bundling flux with adjacent assembly materials, and focused specialists serving advanced packaging applications. Three archetypes dominate: chemistry-integrated platforms, high-purity metal system specialists, and distribution-anchored regional suppliers. Competitive moves center on supplier base consolidation by OEMs and bundled procurement contracts combining flux with thermal interface materials.
Among Germany-based chemistry-integrated platforms, Henkel AG & Co. KGaA exemplifies the adhesives-and-electronics-materials bundling archetype. Indium Corporation and Kester represent contrasting specialization vectors—high-purity metal systems versus distribution-anchored regional supply. These three occupy positions across the strategic spectrum from integrated platform to focused specialist to logistics-driven availability.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Indium Corporation |
| Kester (Illinois Tool Works Inc.) |
| Alpha Assembly Solutions (MacDermid Alpha) |
| AIM Solder |
| Nihon Superior Co., Ltd. |
| Solvay Flux GmbH |
| Lucas-Milhaupt, Inc. |
| The 3M Company |
| Others |
Value Chain & Pricing Dynamics
Synthetic resin displacement of traditional rosin bases simultaneously relocates production gravity toward southern China and coastal Japan while compressing margin pools for legacy formulation suppliers unable to achieve activation temperature precision.
Pricing Analysis
Configured-to-order pricing for REACH-compliant no-clean formulations commands a 40-60% premium over standard halide-containing grades, with price differentiation anchored in certification tier (ECHA registration status) and volume scale. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement: automotive tier-one suppliers absorb premium tiers for scope-three documentation, while Guangdong contract manufacturers drive cost compression in standard grades through consolidated annual contracts. Price erosion runs through economy-tier rosin-based formulations as bio-based alternatives capture specification share. Electronics OEMs in Shenzhen demonstrate highest price sensitivity, prioritizing per-liter procurement costs; German automotive electronics buyers exhibit lowest sensitivity, weighting technical compliance and carbon accounting above unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for synthetic flux base production, with supply concentration in China, Japan, and South Korea exposing buyers to concentrated disruption risk. Specialty resin production draws from petrochemical feedstocks and bio-derived alcohols, with halide-free activator packages sourcing from Belgian and Dutch industrial gas suppliers. Single-source vulnerability concentrates in advanced polymer synthesis capabilities, where southern China facilities serve multiple competing formulation houses. Distribution runs through integrated adhesives platforms and industrial distribution networks, with same-day availability competing against technical specification depth in procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-corrosive fluxes sit in early-cycle expansion as REACH compliance deadlines and RoHS directive extensions force chemistry transitions across European automotive electronics, creating first-mover advantage windows for halide-free formulation specialists.
For Market Incumbents: Fortify supplier scorecard positioning by securing bio-based feedstock certifications and mass-balance accounting systems before automotive procurement mandates harden. Backward integration into specialty resin production in Jiangsu province reduces exposure to southern China supply concentration. Prioritize ECHA registration maintenance for no-clean portfolios as disclosure requirements tighten. For New Entrants and Emerging Players: Lead with halide-free chemistry qualification for India's PLI-subsidized semiconductor assembly zones in Gujarat and Tamil Nadu, where first-mover positioning remains uncontested. Target medical device contract manufacturers in Switzerland and Germany seeking low-temperature synthetic formulations for flex circuit protection. Anchor go-to-market through technical partnership models with advanced substrate manufacturers rather than volume distribution. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward solvent-free formulation capabilities and water-soluble chemistry pipelines. Long-term viability favors specialists with dual certification competence (GB standards plus UL recognition) and established automotive tier-one relationships. Watch REACH enforcement consistency across EU member states as the inflection signal for compliance-cost variance and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Production | Captive supply of synthetic flux bases insulates margin pools from southern China concentration risk. |
| Dual Certification Investment (GB Standards + UL Recognition) | Parallel qualification compresses product launch cycles for multinationals operating across Chinese and North American assembly plants. |
| Bio-Based Feedstock Certification Program | Mass-balance accounting satisfies Stuttgart and Wolfsburg procurement teams' scope-three documentation requirements. |
| Long-Term Supply Agreement with Guangdong Contract Manufacturers | Consolidated procurement commitments from Shenzhen and Dongguan clusters anchor volume visibility. |
| Joint Venture with Industrial Gas Suppliers | Partnerships with Belgian and Dutch suppliers secure allocation priority for HFC-alternative solvent systems. |
Study Parameters
The analysis maps liquid, paste, solid, and gel flux formulations, each validated through technical directors at formulation houses, procurement leads at automotive tier-one suppliers, plant managers at Guangdong contract manufacturers, and regulatory affairs specialists at ECHA-registered entities. Primary interview findings triangulate against customs and trade data for electronic-grade chemical flows, SEC 10-K disclosures from diversified materials platforms, ACC and Cefic specialty chemicals reports, and GB standard certification databases. Bottom-up volume builds from individual production facility capacities reconcile with top-down market sizing from end-use demand segmentation.
Consistency checks against external benchmarks validate projection outputs across the analysis window. The analytical framework models formulation chemistry, application method, end-use vertical, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from elasticity-adjusted demand curves incorporating REACH compliance cost absorption rates, surface mount technology penetration trajectories, and automotive electronics content-per-vehicle trends. Forecast inputs include synthetic resin price indices and bio-based feedstock availability curves.
Forecasts assume regulatory continuity in EU REACH enforcement, China MIIT GB standard administration, and US EPA chemical disclosure frameworks; material policy shifts would require re-modeling. Specific risk factors include ECHA substance restriction expansions, F-Gas Regulation acceleration, and laser soldering substitution rates in aerospace wire harness applications. Practitioners should keep alternative scenarios live as dual certification timelines and supply concentration events evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Mining Explosives Market
Industrial Chemicals
Fabric Starch Market