
 Calcium Fluoride Market | 2026-2036
Calcium Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Fluoride Market Outlook
The EU Green Deal is realigning procurement standards for calcium fluoride across European optical and chemical supply chains. Solvay leverages its integrated fluorspar-to-derivatives chain to sustain premium-grade output for lithography optics. China Minmetals Corporation anchors regional supply through captive mining assets in Hunan and Jiangxi provinces. Mitsui Mining and Smelting differentiates via ultra-high-purity synthetic crystal growth for semiconductor exposure tools.
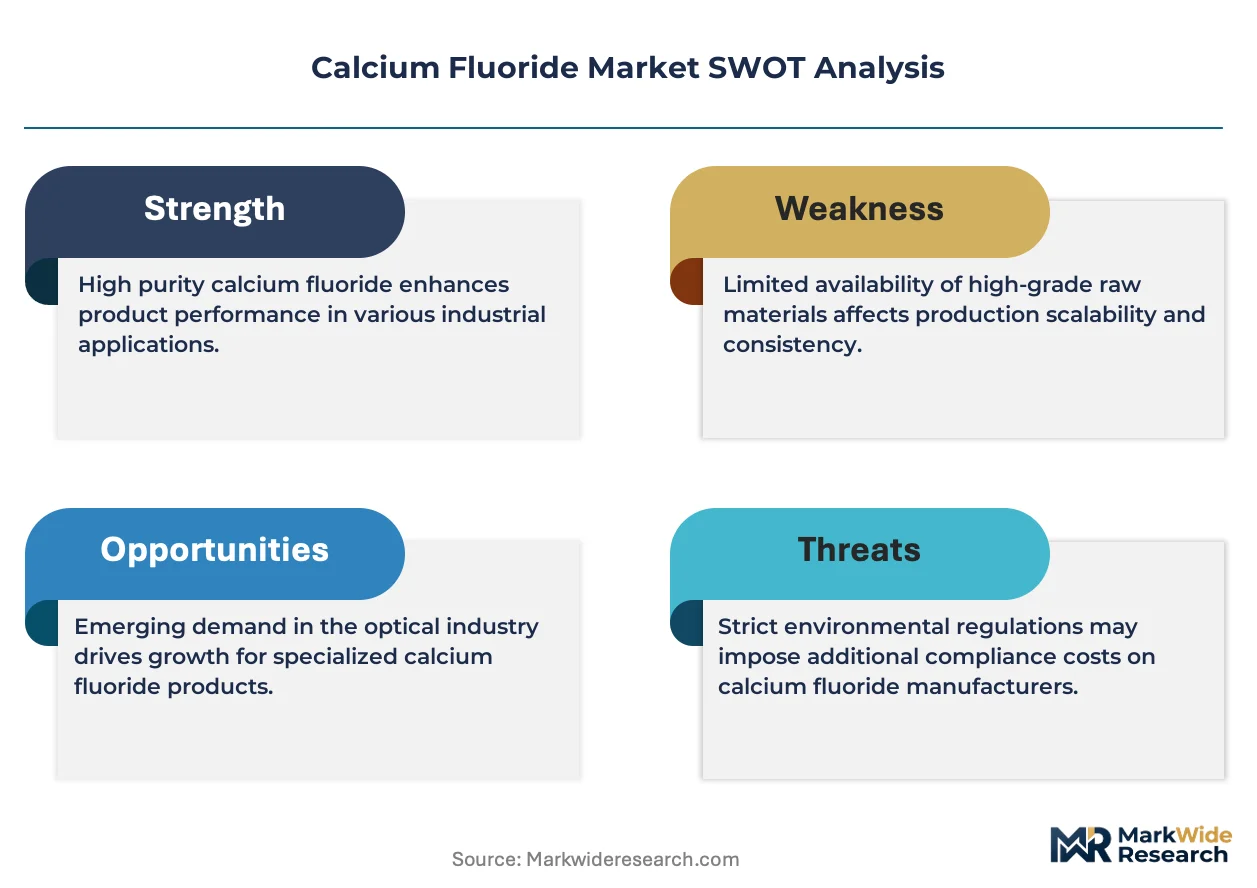
Calcium fluoride (CaF₂) is an inorganic halide mineral with a cubic crystal structure, a Mohs hardness of 4.0, and exceptional ultraviolet transmittance down to 120 nanometers, produced through either acid-grade flotation of natural fluorspar or controlled precipitation of synthetic crystals for optical and metallurgical applications. Anhydrous calcium fluoride leads product type revenue due to its indispensability in hydrogen fluoride cracking and aluminum smelting fluxes, while synthetic calcium fluoride captures expanding margin pools from excimer laser lens fabrication. Optical industry end users command premium pricing for vacuum-ultraviolet-grade material, whereas metallurgical buyers remain volume-sensitive and price-elastic.
The EPA enforces strict fluoride emission limits under the Clean Air Act that elevate compliance costs for U.S.-based acid-grade processors, while REACH registration mandates in Europe restrict heavy metal contaminants in optical-grade supply. China's MEE implements dual carbon goals that tighten energy intensity benchmarks for fluorspar calcination and synthetic crystal furnaces. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate purification investments and site new capacity where compliance costs align with end-use premiums.
Market Dynamics
Deep-ultraviolet lithography expansion is restructuring calcium fluoride procurement, forcing optical-grade suppliers to redirect acid-grade capacity toward synthetic crystal growth while metallurgical buyers absorb residual fluorspar volumes.
Growth Catalysts
- EU Green Deal alignment:REACH compliance mandates are tightening impurity thresholds for optical-grade fluorspar, creating premium-grade demand pull from European lens manufacturers.
- Semiconductor lithography tools:Excimer laser systems for sub-7nm chip fabrication require vacuum-ultraviolet-grade synthetic calcium fluoride with transmittance below 120 nanometers.
- Jiangsu and Hunan concentration:China's fluorochemical clusters dominate upstream acid-grade supply, anchoring regional cost competitiveness for hydrogen fluoride crackers.
Market Restraints
- Acid-grade fluorspar volatility:Metallurgical buyers face input cost swings tied to Chinese mining quota allocations and energy intensity benchmarks under MEE dual carbon goals.
- Optical-grade purification limits:Natural fluorspar carries rare-earth contaminants that synthetic precipitation methods must eliminate, capping substitution of synthetic for natural material.
- EPA emission compliance:U.S.-based processors absorb elevated fixed costs from Clean Air Act fluoride limits, compressing margins on standard-grade output.
Strategic Opportunities
- Underpenetrated semiconductor optics:South Korean and Taiwanese lithography tool builders are expanding synthetic crystal procurement outside established Japanese supply chains.
- Aluminum smelting flux reformulation:Low-carbon smelting technologies are creating demand for high-purity anhydrous calcium fluoride with lower sulfur content.
- Carbon border adjustment mechanism:EU CBAM implementation is incentivizing European buyers to source synthetic material from low-carbon furnace operations rather than calcined natural fluorspar.
Industry Challenges
- Crystal growth technician scarcity:Synthetic optical-grade production requires furnace operators with rare-earth doping expertise, creating recruitment bottlenecks in Hunan and Jiangxi production zones.
- REACH registration timelines:Heavy metal contaminant documentation for optical-grade supply extends certification cycles by 18-24 months, delaying new supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Fluoride Market |
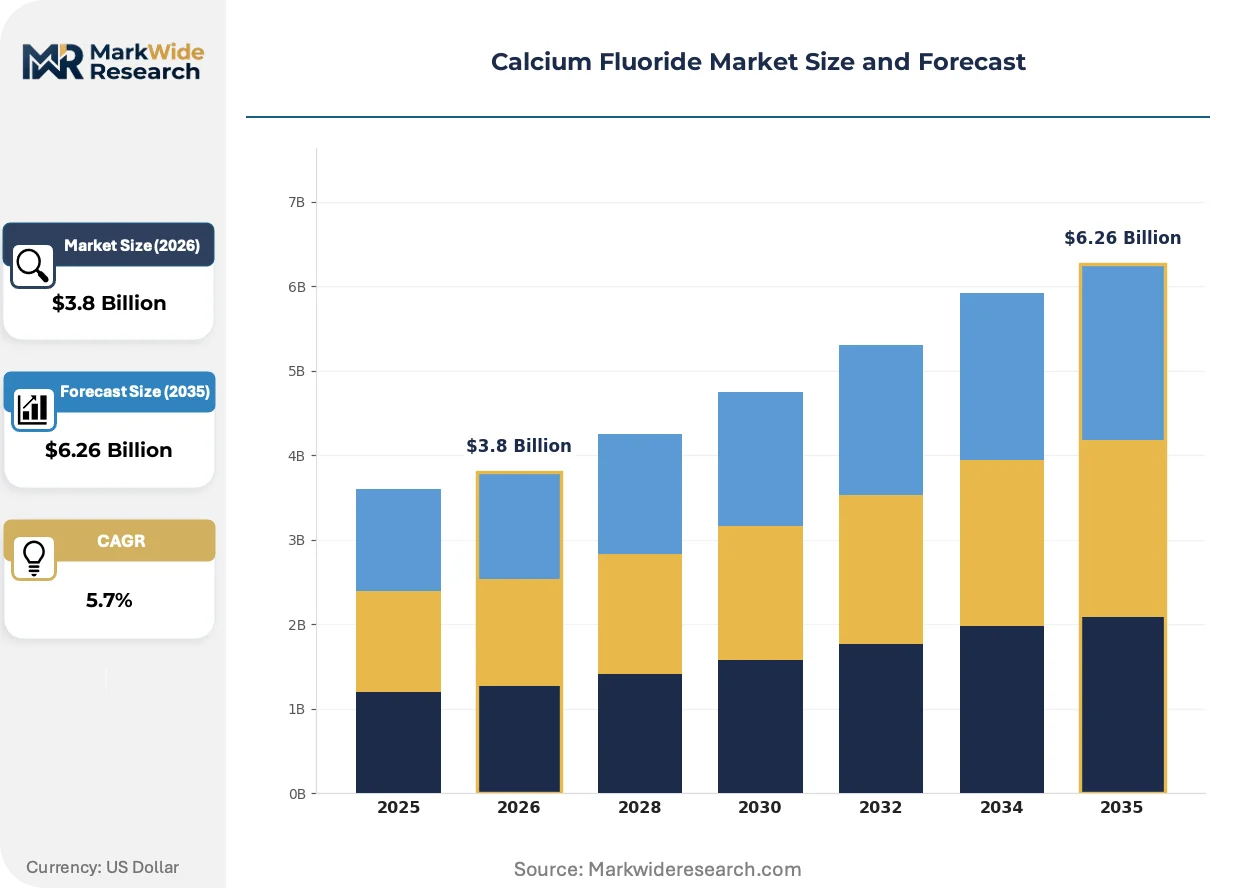
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Calcium Fluoride, Anhydrous Calcium Fluoride, Synthetic Calcium Fluoride, Natural Calcium Fluoride End User: Metallurgical Industry, Optical Industry, Chemical Industry, Pharmaceutical Industry Application: Glass Manufacturing, Welding Rods, Flux for Metal Processing, Fluorine Derivatives Form: Granular, Powder, Crystalline, Micronized |
| Companies Covered | Orbia (Mexichem), China Minmetals Corporation, China Kingho Corporation, Solvay, Mondo Minerals, Fluorsid, Hunan Jinxing Fluorine Chemical, Imerys, Mitsui Mining and Smelting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Fluoride Market Strategic Shifts
Solid-state lithography light sources and carbon-accounting supply chains are restructuring how calcium fluoride grades are specified, priced, and qualified across optical and metallurgical end uses.
Synthetic calcium fluoride precipitation using controlled hydrothermal growth is decentralizing optical-grade supply away from traditional acid-grade fluorspar processors. Semiconductor equipment builders in South Korea and Taiwan are qualifying second-source synthetic crystal suppliers to reduce dependence on Japanese furnace operators. This technology diffusion is compressing regional price premiums and forcing legacy fluorspar miners to defend metallurgical volume through cost rather than optical-grade migration.
REACH registration mandates under ECHA oversight are tightening heavy metal thresholds for optical-grade calcium fluoride entering European lithography supply chains. The regulation now requires batch-level certification for arsenic, lead, and rare-earth contaminants previously managed through supplier self-declaration. German and Dutch optical component manufacturers are responding by consolidating procurement onto integrated fluorspar-to-derivatives suppliers with captive purification assets.
Specification-driven procurement is fragmenting buyer-seller relationships across the calcium fluoride value chain. Large aluminum smelters and hydrogen fluoride crackers are unbundling long-term offtake agreements in favor of spot-indexed contracts tied to Chinese acid-grade export prices. This behavior shift is most visible in European metallurgical procurement, where buyers now maintain dual-source strategies across Mongolian and Mexican fluorspar origins to arbitrage freight and duty differentials.
Calcium Fluoride Market Segmentation
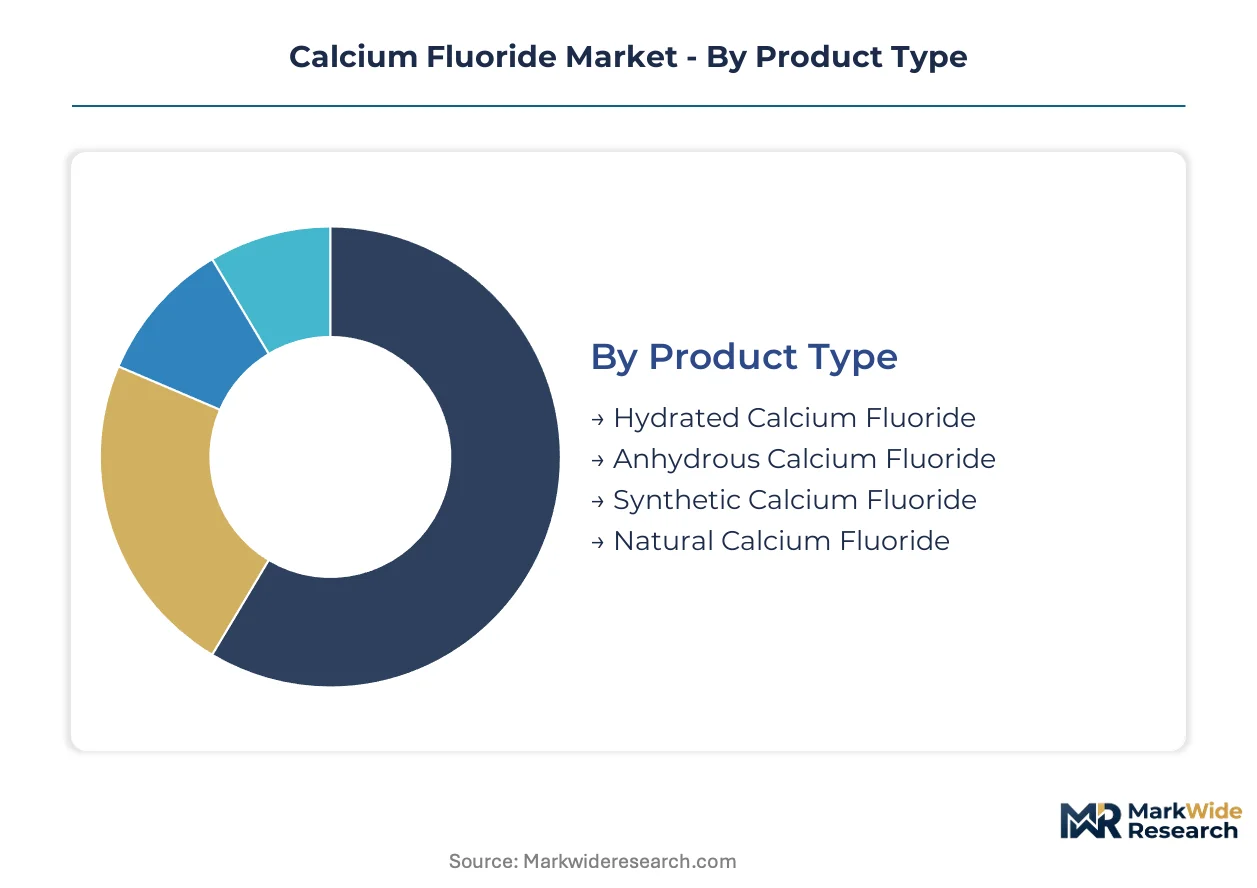
Calcium fluoride procurement splits sharply between metallurgical volume buyers and optical precision customers, with purification intensity and furnace technology determining which segments absorb capital deployment. Specification divergence across end uses forces suppliers to maintain parallel production lines rather than flexible asset reconfiguration.
Product Type:
Capital intensity peaks in synthetic crystal growth, where hydrothermal precipitation demands controlled-atmosphere furnaces and rare-earth doping expertise.
- Anhydrous Calcium Fluoride:Dehydrated acid-grade fluorspar with moisture content below 0.1 percent serves hydrogen fluoride crackers and aluminum smelters requiring sulfur-controlled flux chemistry. Demand concentrates in China's Jiangsu province fluorochemical clusters where MEE dual carbon goals tighten energy intensity benchmarks for calcination furnaces.
- Synthetic Calcium Fluoride:Laboratory-precipitated crystals grown under controlled hydrothermal conditions achieve vacuum-ultraviolet transmittance below 120 nanometers for excimer laser optics. South Korean and Taiwanese lithography tool builders are expanding procurement outside Japanese supply chains, compressing regional price premiums.
- Hydrated Calcium Fluoride:Naturally occurring fluorspar retains crystalline water suitable for lower-purity welding rod coatings and construction glass fluxes.
- Natural Calcium Fluoride:Acid-grade flotation concentrate from Hunan and Jiangxi mining assets feeds metallurgical buyers with volume-sensitive, price-elastic procurement patterns.
Most installed capacity flows through anhydrous calcium fluoride. Expansion is steepest in synthetic calcium fluoride.
End User:
Customer concentration varies by specification tolerance, with optical buyers consolidating procurement onto integrated suppliers while metallurgical purchasers fragment across spot-indexed contracts.
- Optical Industry:German and Dutch lens manufacturers command vacuum-ultraviolet-grade material with batch-level REACH certification for arsenic and lead contaminants. ECHA oversight now mandates documentation previously managed through supplier self-declaration, extending qualification cycles.
- Metallurgical Industry:Aluminum smelters and steelmakers absorb residual fluorspar volumes through dual-source strategies across Mongolian and Mexican origins to arbitrage freight and duty differentials.
- Chemical Industry:Hydrogen fluoride producers in Jiangsu province rely on acid-grade feedstock for fluorocarbon and fluoropolymer precursor synthesis.
- Pharmaceutical Industry:Niche demand for high-purity calcium fluoride in dental formulations and bone graft materials requires GMP-compliant purification.
Optical industry buyers generate the highest margin per ton. Metallurgical industry buyers move the greatest absolute volume.
Application:
Application-driven procurement is fragmenting long-term offtake agreements as buyers unbundle specifications and source each grade independently.
- Flux for Metal Processing:Aluminum smelting consumes anhydrous calcium fluoride as electrolyte additive and dross-reducing agent, with low-carbon smelting technologies creating demand for lower-sulfur variants.
- Fluorine Derivatives:Hydrogen fluoride crackers require acid-grade fluorspar with precise calcium-to-fluoride ratios for refrigerant and pharmaceutical intermediate production.
- Glass Manufacturing:Optical glass foundries in Germany specify synthetic material for ultraviolet-transmissive lens blanks, while construction glassmakers accept natural grades.
- Welding Rods:Hydrated calcium fluoride stabilizes arc characteristics in coated electrodes for shipbuilding and infrastructure fabrication.
Flux applications dominate tonnage shipments. Fluorine derivative applications are gaining share fastest.
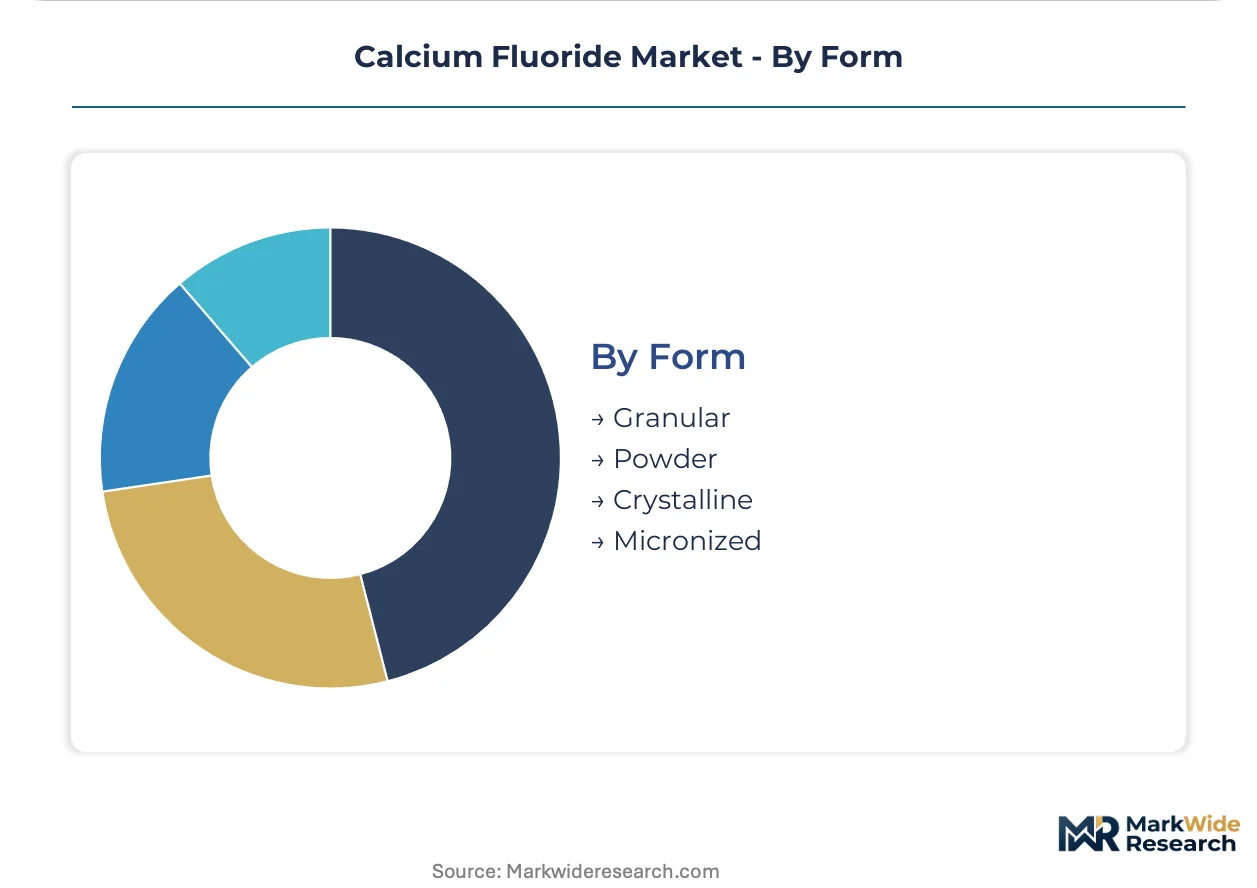
Form:
Physical form selection tracks downstream processing economics, with crystalline and micronized grades commanding purification premiums over bulk granular shipments.
- Crystalline:Single-crystal boules grown via Bridgman-Stockbarger methods supply lithography lens fabricators requiring birefringence control and sub-nanometer surface roughness.
- Micronized:Jet-milled particles below 10 micrometers serve specialty glass batching and pharmaceutical tablet compression where dispersion uniformity matters.
- Granular:Screened acid-grade chunks feed metallurgical furnaces and HF crackers with minimal preprocessing.
- Powder:Ground natural fluorspar fills welding rod coatings and construction sealants where packing density drives formulation economics.
Granular form moves through the most production lines. Crystalline form attracts the steepest capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calcium fluoride industrialization traces to German optical glassworks in Jena during the late nineteenth century, where synthetic crystal growth methods first achieved vacuum-ultraviolet transparency for precision lenses.
China
Jiangsu and Hunan provinces host the world's densest fluorochemical clusters, feeding hydrogen fluoride crackers and aluminum smelters with acid-grade fluorspar. MEE dual carbon goals tighten energy intensity benchmarks for calcination furnaces, forcing capacity consolidation toward larger, more efficient operators. Xinyu and Yichun mining districts in Jiangxi province anchor captive supply chains for integrated fluorspar-to-derivatives producers.
Germany
Optical component manufacturers in Jena and Mainz command premium pricing for REACH-certified vacuum-ultraviolet-grade material. ECHA oversight mandates batch-level documentation for arsenic, lead, and rare-earth contaminants, extending supplier qualification cycles. The country's integrated fluorspar processors leverage captive purification assets to defend lithography optics contracts against Asian synthetic crystal entrants.
United States
Domestic acid-grade processors face elevated fixed costs from EPA Clean Air Act fluoride emission limits, compressing margins on standard-grade output. Metallurgical buyers in the Southeast and Midwest maintain dual-source strategies across Mongolian and Mexican fluorspar origins to arbitrage freight differentials. Limited synthetic crystal growth capacity leaves semiconductor optics procurement dependent on Japanese and European furnace operators.
Japan
Excimer laser lens fabricators in Nagoya and Osaka prefectures pioneered hydrothermal precipitation methods for sub-120-nanometer transmittance crystals. METI industrial standards enforce rigorous purity protocols that Japanese furnace operators leverage to sustain premium positioning in lithography supply chains. South Korean and Taiwanese tool builders are now qualifying second-source suppliers to reduce dependence on these established supply relationships.
South Korea
Semiconductor equipment builders in Suwon and Pyeongtaek are expanding synthetic calcium fluoride procurement outside traditional Japanese supply channels. The country's national industrial regulator supports domestic crystal growth initiatives through targeted R&D programs. This technology diffusion is compressing regional price premiums and forcing legacy supply relationships toward more competitive terms.
Calcium Fluoride Market Competitive Environment
Premium-margin players sit above commodity-margin players across purification intensity and end-use certification tiers. The competitive structure stratifies between integrated fluorspar-to-derivatives chains and specialized synthetic crystal growers, with metallurgical volume handlers occupying a cost-driven middle layer. Three archetypes dominate: captive mining asset holders with downstream integration, precision optics specialists with rare-earth doping expertise, and regional acid-grade traders serving spot-indexed metallurgical demand. Capacity expansion and strategic partnerships represent the dominant competitive moves, as synthetic crystal producers seek furnace scale and acid-grade handlers secure offtake anchors.
Within the integrated mining tier, China Minmetals Corporation and China Kingho Corporation exemplify captive asset strategies through Hunan and Jiangxi province holdings. Solvay occupies a position among European fluorspar-to-derivatives specialists with purification assets aligned to REACH compliance mandates. Mitsui Mining and Smelting anchors the precision optics archetype, representing Japanese furnace operators whose rare-earth doping expertise commands lithography tool builder loyalty.
| Leading Market Players |
|---|
| Orbia (Mexichem) |
| China Minmetals Corporation |
| China Kingho Corporation |
| Solvay |
| Mondo Minerals |
| Fluorsid |
| Hunan Jinxing Fluorine Chemical |
| Imerys |
| Mitsui Mining and Smelting |
| Others |
Value Chain & Pricing Dynamics
Semiconductor lithography tool builders' vacuum-ultraviolet-grade procurement mandates are forcing synthetic crystal suppliers to absorb rare-earth doping costs while metallurgical buyers exploit spot-indexed acid-grade alternatives, compressing margins across the purification intensity spectrum.
Pricing Analysis
Three-tier pricing structure across optical-grade, acid-grade, and metallurgical-grade levels stratifies calcium fluoride procurement by certification intensity and end-use performance. Price differentiation hinges on REACH batch-level contaminant documentation and excimer laser transmittance thresholds below 120 nanometers. Cost compression in acid-grade supply runs through Chinese MEE dual carbon compliance burdens on calcination furnaces. Metallurgical buyers in aluminum smelting exhibit the highest price elasticity, while German lens manufacturers tolerate premium positioning for vacuum-ultraviolet-grade synthetic crystals.
Supply Chain Analysis
Dual-sourcing mandates from European optical component manufacturers and South Korean lithography tool builders are fragmenting procurement across Japanese furnace operators and emerging Chinese synthetic crystal entrants. Supply concentrates in China, Germany, and Japan, with raw material flows drawing from Hunan and Jiangxi fluorspar mining assets, rare-earth dopant precursors, and high-purity hydrofluoric acid feedstocks. Single-source vulnerability persists in Bridgman-Stockbarger crystal growth furnace technology controlled by established Japanese operators. Distribution runs through integrated fluorspar-to-derivatives suppliers with captive purification assets serving REACH-certified European demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium fluoride market represents a late-cycle quality story where specification divergence toward vacuum-ultraviolet-grade synthetic crystals rewards purification capability over volume scale.
For Market Incumbents: Extend furnace capacity in Jiangsu and Hunan provinces to capture dual carbon compliance consolidation while accelerating REACH certification documentation for arsenic and lead batch-level testing. Synthetic crystal entrants from South Korea threaten Japanese furnace operator premiums; backward integration into rare-earth dopant supply secures cost control against raw material volatility. For New Entrants and Emerging Players: Begin with metallurgical-grade acid-grade supply to established hydrogen fluoride crackers in Jiangsu fluorochemical clusters, leveraging MEE energy intensity benchmarks to displace smaller calcination operators. Qualification timelines for optical-grade synthetic crystals exceed 18 months; the penetrable entry point rests on spot-indexed metallurgical contracts with dual-source flexibility. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated fluorspar-to-derivatives operators possessing captive mining assets in Hunan and Jiangxi plus in-house purification infrastructure aligned to REACH mandates. Long-term viability favors ownership structures spanning the full value chain from acid-grade flotation to synthetic crystal precipitation. Watch South Korean and Taiwanese lithography tool builder qualification decisions as the inflection signal for regional pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Dopant Supply | Mitsui Mining and Smelting's captive sourcing insulates synthetic crystal margins against precursor volatility. |
| REACH Batch-Level Certification Investment | Solvay's documentation infrastructure extends supplier qualification cycles by 18-24 months, defending European optical contracts. |
| Dual-Source Qualification Expansion | South Korean lithography tool builders' second-source programs compress regional price premiums for Japanese furnace operators. |
| Low-Carbon Calcination Capacity Consolidation | China Minmetals Corporation's MEE-aligned furnace upgrades in Hunan displace smaller acid-grade processors. |
| Hydrothermal Precipitation Technology Licensing | Technology diffusion to Taiwanese crystal growers fragments synthetic optical-grade supply away from Nagoya and Osaka incumbents. |
Study Parameters
Multiple input streams — primary interviews with furnace operations managers at synthetic crystal producers, procurement leads at aluminum smelters and hydrogen fluoride crackers, and regulatory affairs specialists at ECHA-aligned optical component manufacturers — were reconciled against secondary validation from customs trade data, SEC filings of integrated fluorspar processors, and MEE dual carbon policy disclosures. Bottom-up tonnage estimates by grade tier and end-use application were cross-checked against top-down value projections across the analysis window.
Historical capacity utilization patterns were cross-referenced against expert panel assessments of excimer laser lithography tool deployment schedules. The forecast framework models segmentation across product type (anhydrous, synthetic, hydrated, natural), end user (optical, metallurgical, chemical, pharmaceutical), application (flux, fluorine derivatives, glass, welding), and physical form (crystalline, micronized, granular, powder). CAGRs were derived from supply-demand balance equations incorporating MEE energy intensity benchmarks and REACH registration timeline assumptions.
Several conditions sit outside the modeled scope, including unannounced Chinese mining quota reallocations, sudden EPA emission limit revisions under the Clean Air Act, and breakthrough solid-state lithography light source technologies displacing excimer laser architectures. Forecasts reflect documented assumptions about furnace scale economies and rare-earth technician availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Propylene Oxide Market