
 Oilfield Scale Inhibitors Market | 2026-2036
Oilfield Scale Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Scale Inhibitors Market Analytics
API RP 45 qualification for downhole chemical compatibility is collapsing the supplier base, as only formulators with dedicated HPHT testing infrastructure can secure operator approval. Halliburton Company leverages its integrated well services platform to bundle scale inhibitor delivery with artificial lift packages. Baker Hughes Company sustains R&D intensity in sulfonate-polymer hybrid chemistries for extreme salinity conditions. Dow Inc. anchors its position through backward integration into phosphonate intermediate production, controlling raw material cost volatility.
Oilfield scale inhibitors are specialty chemicals, typically phosphonate, sulfonate, or polyacrylate-based formulations, designed to disrupt crystal nucleation and growth of calcium carbonate, barium sulfate, and strontium sulfate deposits in production tubing and surface equipment at threshold concentrations below stoichiometric levels. Their primary purpose is maintaining well productivity and preventing flow assurance failures in oil and gas extraction systems. Phosphonates dominate current volume demand due to established performance in carbonate scale control, while polyacrylate variants represent the fastest-growing chemistry segment as operators seek improved thermal stability above 150°C in deepwater applications. Liquid delivery mode captures the majority share through continuous injection systems, though emulsion formulations are gaining traction in subsea tiebacks where logistics constraints favor concentrated products.
EPA NPDES discharge permits and OSPAR Harmonised Mandatory Control Scheme govern offshore chemical selection, directly restricting chromate-containing and certain persistent phosphonate formulations in North American and European waters. REACH registration requirements in Europe further elevate compliance costs for importers of active ingredients from non-EU sources. Operators and chemical suppliers must monitor evolving regulatory thresholds for biodegradability and bioaccumulation, as these criteria increasingly determine which formulations qualify for preferred supplier status rather than merely technical performance benchmarks.
Market Dynamics
API RP 45 qualification requirements are compressing the supplier base for high-pressure high-temperature applications, as only formulators with dedicated testing infrastructure can secure operator approval for downhole chemical compatibility in extreme well conditions.
Growth Catalysts
- OSPAR Harmonised Mandatory Control Scheme:Offshore operators in the North Sea must replace persistent phosphonate formulations with biodegradable alternatives, creating sustained demand for compliant chemistry portfolios.
- US shale basins:Continuous injection systems in the Permian and Bakken formations require scale inhibitor programs for carbonate and sulfate deposition control in high-salinity produced water.
- Subsea tieback architectures:Concentrated emulsion formulations reduce logistics burdens for remote deepwater installations where supply vessel frequency is constrained.
Market Restraints
- Phosphonate intermediate supply:Backward integration into phosphonate production requires capital-intensive manufacturing infrastructure that few formulators possess.
- REACH registration costs:European importers of active ingredients from non-EU sources face elevated compliance burdens for biodegradability and bioaccumulation documentation.
- Chromate displacement:EPA NPDES discharge permits prohibit legacy corrosion inhibitor packages, forcing reformulation investments without immediate performance guarantees.
Strategic Opportunities
- Brazil pre-salt fields:ANVISA environmental licensing and Petrobras technical specifications favor suppliers with local blending capacity and biodegradable polymer expertise.
- Polyacrylate-sulfonate hybrids:Thermal stability above 150°C in deepwater Gulf of Mexico wells opens premium positioning for next-generation chemistry platforms.
- Digital chemical monitoring:Integration of real-time scale deposition sensors with automated injection systems creates service-revenue attachment opportunities for qualified formulators.
Industry Challenges
- HPHT certification timelines:API RP 45 testing protocols require 12-18 month validation cycles before operators approve new formulations for downhole deployment.
- Specialized formulation chemists:Scarce expertise in phosphonate-polymer synergy design limits R&D throughput for qualified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Scale Inhibitors Market |
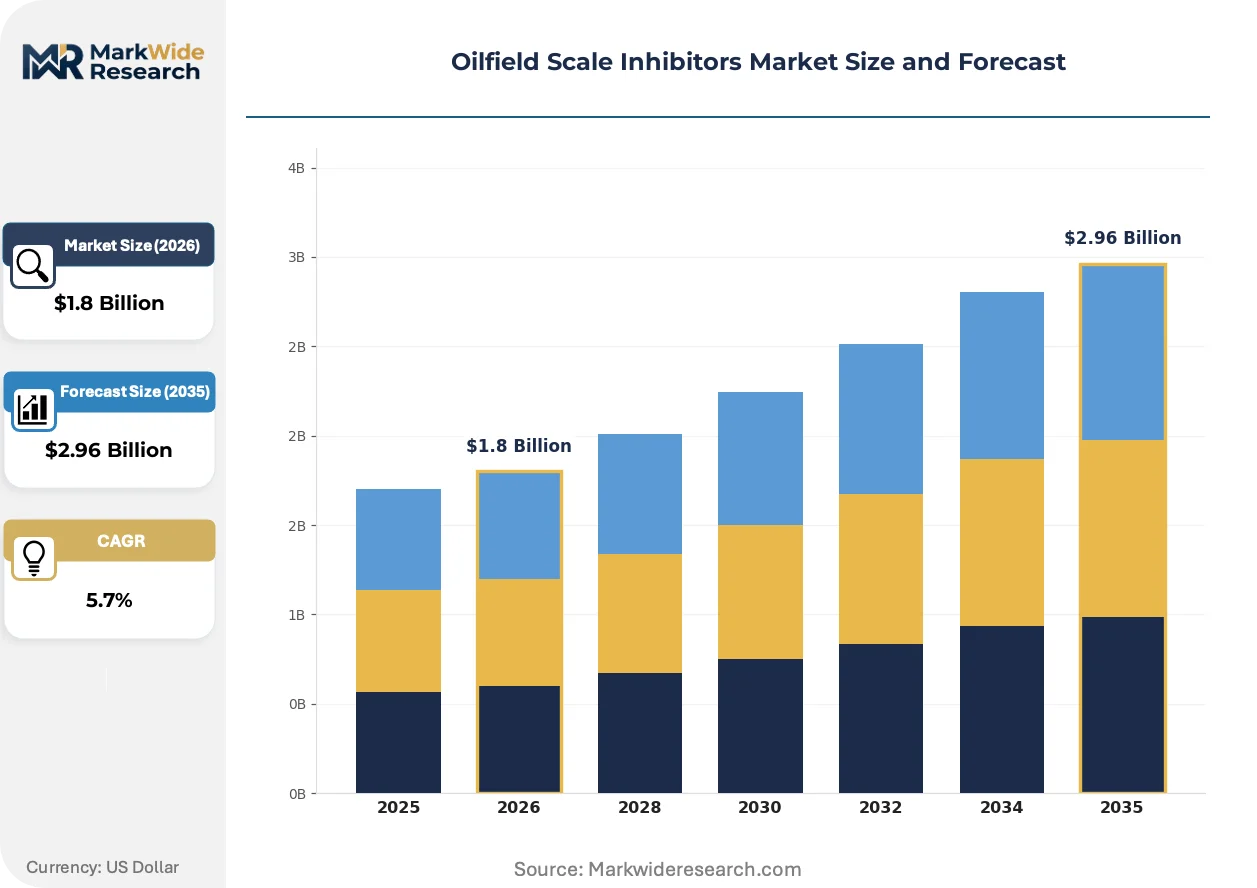
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphonates, Sulfonates, Polyacrylate, Others Application: Oil Production, Gas Production, Water Injection, Fracturing End User: Oil & Gas Operators, Service Companies, Equipment Manufacturers, Research Institutions Delivery Mode: Liquid, Powder, Emulsion, Concentrate |
| Companies Covered | Halliburton Company, Schlumberger Limited, Baker Hughes Company, BASF SE, Dow Inc., Solvay S.A., Kemira Oyj, Ecolab Inc., Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Scale Inhibitors Market Evolving Landscape
Formulation science is converging with digital monitoring systems and regulatory compliance architectures to reshape how scale inhibitors are specified, delivered, and validated in production operations.
Polyacrylate-based chemistry platforms are miniaturizing thermal stability thresholds previously requiring phosphonate backbones, enabling operators in the Gulf of Mexico to deploy single-chemical programs across mixed carbonate-sulfate scaling environments rather than dual-injection systems. Deepwater producers are accelerating adoption of these hybrids for subsea completions where intervention costs dwarf chemical premiums.
REACH registration requirements in Europe are elevating documentation burdens for biodegradability and bioaccumulation testing, forcing non-EU active ingredient suppliers to establish EU-based formulation partnerships or absorb extended approval timelines. North Sea operators now mandate OSPAR-compliant chemistry pre-qualification before contract award, shifting competitive advantage toward suppliers with captive testing laboratories.
Service bundling is displacing standalone chemical supply contracts in US land markets, with operators demanding integrated packages combining scale inhibitor delivery, injection equipment maintenance, and performance guarantees tied to well productivity metrics. This compression of procurement scope favors suppliers with artificial lift and chemical expertise under single accountability structures, most visible in Permian Basin drilling programs.
Oilfield Scale Inhibitors Market Segmentation
Scale inhibitor procurement decisions split across chemistry performance, deployment logistics, and regulatory compliance requirements. Operators match formulation selection to specific scaling risks, well architecture, and discharge permit constraints.
Product Type:
EPA NPDES and OSPAR discharge thresholds favor phosphonate alternatives with demonstrated biodegradability profiles, while thermal stability demands in deepwater applications pull formulation choices toward hybrid architectures.
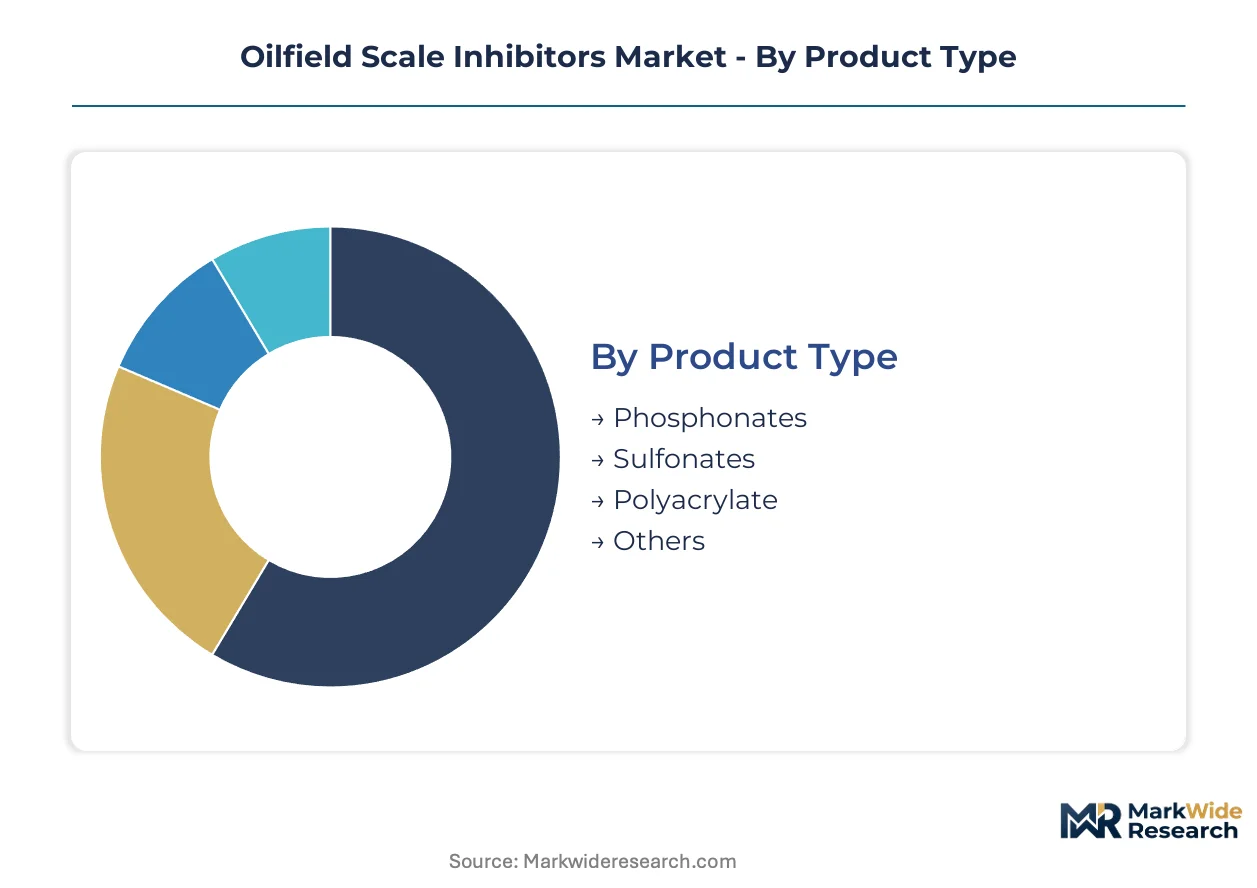
- Phosphonates:Aminophosphonate and phosphonocarboxylate chemistries deliver threshold inhibition at sub-stoichiometric concentrations against calcium carbonate and barium sulfate nucleation. Gulf of Mexico operators rely on these formulations for high-volume carbonate scale control in shelf and deepwater assets, though OSPAR restrictions in the North Sea force substitution with biodegradable variants.
- Polyacrylate:Copolymer architectures with sulfonate functionality achieve thermal stability above 150°C, enabling single-chemical programs in HPHT wells previously requiring dual-injection systems. US shale basins and Brazil pre-salt fields represent concentrated demand for these hybrids as operators seek to simplify logistics and reduce intervention frequency.
- Sulfonates:Sulfonate-polymer blends target extreme salinity conditions where phosphonate solubility limits performance.
- Others:Carboxylate and phosphino-carboxylate alternatives serve niche compatibility requirements with specific completion fluids.
Phosphonates handle the majority of throughput; polyacrylate is climbing the fastest on share as thermal stability thresholds miniaturize.
Application:
Deployment context determines injection strategy, concentration requirements, and compatibility testing protocols.
- Oil Production:Continuous downhole injection maintains tubing integrity and surface facility throughput in primary and secondary recovery operations. Permian Basin operators deploy automated chemical delivery systems tied to real-time scale deposition monitoring, with performance guarantees structured around well productivity maintenance.
- Gas Production:Condensate scaling risks in high-pressure gas wells require specialized phosphonate formulations with low pour points for cold-climate surface facilities. North Sea gas producers prioritize OSPAR-compliant chemistry pre-qualification before contract award.
- Water Injection:Sulfate scale prevention in seawater injection systems protects reservoir injectivity and minimizes souring risks.
- Fracturing:Scale inhibitor incorporation into frac fluid systems prevents proppant pack damage and near-wellbore deposition in shale completions.
Oil production absorbs the largest chemical volumes; gas production is expanding most quickly as deepwater gas developments accelerate.
End User:
Procurement authority and technical specification control vary sharply across buyer categories, shaping contract structures and supplier qualification requirements.
- Oil & Gas Operators:Supermajors and national oil companies set formulation standards, approve supplier lists, and negotiate performance-based contracts with minimum effective dosage guarantees. API RP 45 qualification requirements compress approved supplier bases to formulators with dedicated HPHT testing infrastructure.
- Service Companies:Halliburton and Baker Hughes bundle scale inhibitor supply with artificial lift, pressure pumping, and digital monitoring services, displacing standalone chemical contracts in US land markets.
- Equipment Manufacturers:Subsea production system suppliers specify compatible chemistries for umbilical and injection hardware materials.
- Research Institutions:University and national laboratory partnerships drive pre-competitive formulation development for extreme environment applications.
Oil and gas operators command the largest procurement spend; service companies are gaining share fastest through integrated service bundling.
Delivery Mode:
Logistics constraints and well architecture determine physical form selection, with concentration and stability requirements varying by deployment pathway.
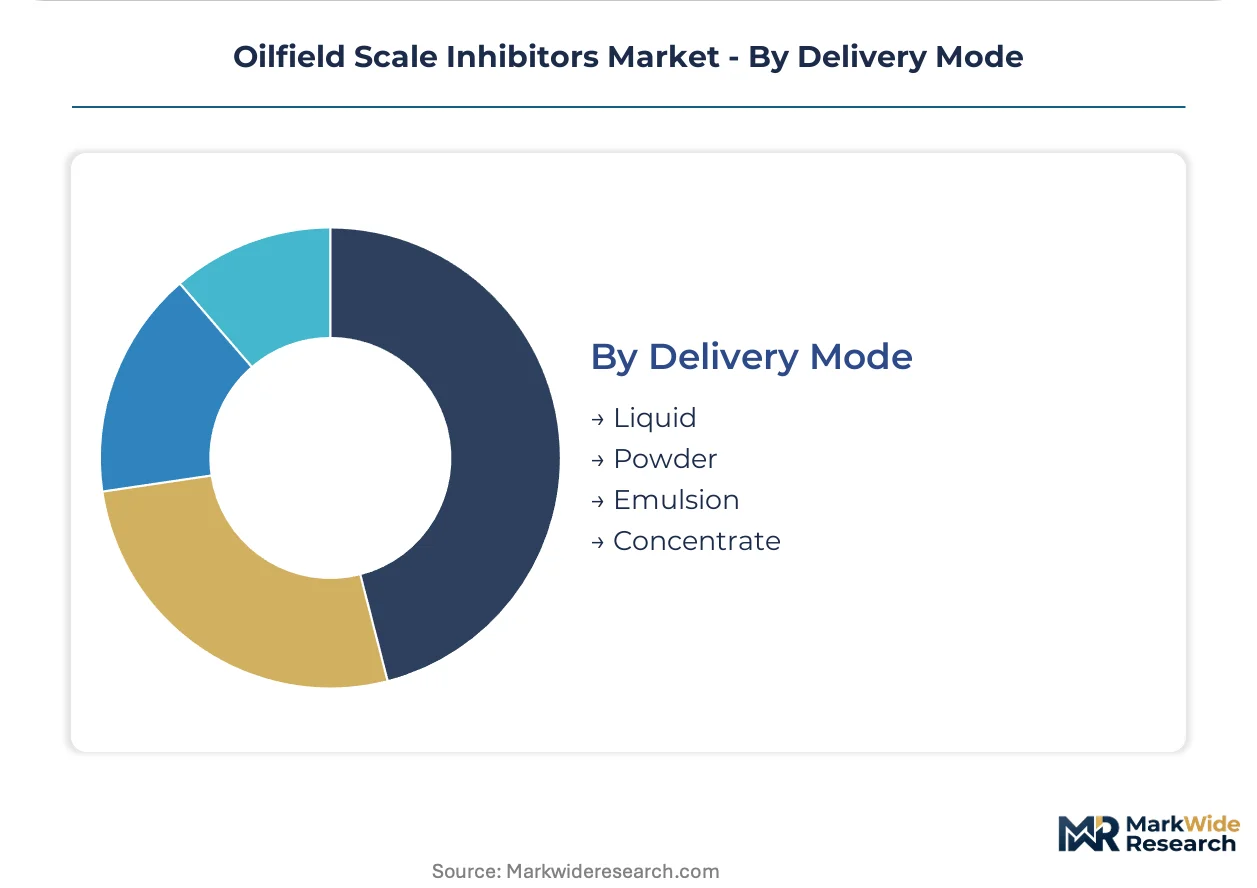
- Liquid:Aqueous solutions dominate continuous injection systems through capillary tubing and surface chemical injection pumps, offering straightforward metering and compatibility with standard field infrastructure. US shale operators favor liquid delivery for automated wellsite chemical programs.
- Emulsion:Concentrated oil-external emulsions reduce supply vessel frequency for remote deepwater tiebacks where deck space and storage capacity are constrained. Gulf of Mexico subsea developments specify emulsion formulations to minimize intervention logistics.
- Powder:Solid granular products serve batch treatment applications and remote locations where liquid transport is uneconomical.
- Concentrate:High-active-content formulations dilute at point of use, reducing transportation costs for high-volume programs.
Liquid delivery handles the majority of volume; emulsion formats are expanding most quickly as subsea tieback architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors North American scale inhibitor demand through its dense network of offshore supply bases and pipeline infrastructure connecting Permian production to Gulf of Mexico deepwater assets.
United States
Permian Basin operators deploy continuous injection systems for carbonate and sulfate scale control in high-salinity produced water environments. EPA NPDES discharge permits restrict chromate-containing formulations, accelerating reformulation investments toward biodegradable phosphonate alternatives. Houston-Galveston chemical blending clusters concentrate supply capacity for Gulf of Mexico offshore programs.
Norway
North Sea offshore installations require OSPAR-compliant chemistry pre-qualification before contract award, favoring suppliers with captive biodegradability testing laboratories. The country's national petroleum regulator enforces Harmonised Mandatory Control Scheme thresholds for bioaccumulation and persistence. Stavanger-based service company headquarters coordinate subsea chemical logistics for remote tieback architectures.
Brazil
Pre-salt field developments generate demand for thermal-stable polyacrylate-sulfonate hybrids above 150°C in deepwater completions. ANVISA environmental licensing procedures favor suppliers with local blending capacity and biodegradable polymer expertise. Rio de Janeiro petrochemical complexes anchor formulation manufacturing for Petrobras technical specifications.
Saudi Arabia
High-pressure high-temperature gas well completions require specialized phosphonate formulations with extreme salinity tolerance. The country's national oil company mandates supplier qualification through dedicated testing infrastructure for downhole chemical compatibility. Eastern Province industrial cities concentrate production chemical manufacturing and regional distribution.
United Kingdom
North Sea gas producers prioritize REACH-registered scale inhibitor portfolios with documented biodegradability profiles for offshore discharge compliance. The Health and Safety Executive governs chemical handling protocols on platform installations. Aberdeen supply chain clusters coordinate logistics for remote subsea developments where intervention costs drive concentrated emulsion formulation demand.
Oilfield Scale Inhibitors Market Competitive Landscape
Listed leaders compete with private specialists across qualification infrastructure, where API RP 45 certification requirements compress the approved supplier base to formulators with dedicated HPHT testing capabilities. The market structure concentrates around integrated service providers, diversified chemical conglomerates, and regional blending specialists. Three archetypes dominate: artificial lift bundlers, backward-integrated phosphonate producers, and subsea logistics optimizers. Competitive intensity centers on M&A-driven service integration and captive testing laboratory expansion.
Within the integrated service tier, Halliburton Company and Baker Hughes Company exemplify the bundling archetype, anchoring positions through combined chemical delivery and well intervention accountability structures. Dow Inc. occupies a position representing backward-integrated phosphonate intermediate production, controlling raw material cost exposure through in-house manufacturing. These three entities illustrate the competitive spectrum from service bundling to upstream chemical integration.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| Baker Hughes Company |
| BASF SE |
| Dow Inc. |
| Solvay S.A. |
| Kemira Oyj |
| Ecolab Inc. |
| Clariant AG |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Gulf of Mexico operators and Houston-Galveston chemical blenders lock in phosphonate supply access while providing 12-18 month price visibility against raw material volatility. These structures tie volume commitments to API RP 45 certification status, embedding qualification timelines into procurement economics.
Pricing Analysis
Certification level (API RP 45-qualified versus standard-grade) creates the primary spread between premium and economy tiers in this market. Performance-based contracts with minimum effective dosage guarantees dominate the pricing model, differentiating on thermal stability thresholds and biodegradability documentation. Cost compression in standard phosphonate formulations is intensifying because REACH registration burdens are elevating compliance overhead for non-EU suppliers. National oil companies exhibit the least price sensitivity due to intervention cost exposure in deepwater assets, while independent shale operators in the Permian Basin show highest sensitivity to unit chemical costs.
Supply Chain Analysis
Phosphonate intermediate production concentrates in the United States, Germany, and China, with backward-integrated formulators controlling captive supply. Formulation manufacturing draws from phosphonic acid, acrylate monomers, and sulfonate precursors as primary inputs. Single-source vulnerability persists for HPHT testing infrastructure, where only a limited supplier base possesses dedicated qualification capabilities. Distribution runs through Houston-Galveston and Rotterdam chemical clusters for offshore supply bases, with emulsion formulations requiring specialized blending assets near deepwater ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scale inhibitor demand sits in early-cycle expansion as subsea tieback architectures proliferate and OSPAR-compliant chemistry pre-qualification becomes mandatory for North Sea contract access.
For Market Incumbents: Consolidate testing infrastructure advantages by expanding captive HPHT laboratory capacity in Stavanger and Rio de Janeiro to capture Petrobras and Equinor qualification workflows. Defend against polyacrylate hybrid substitution threats by accelerating phosphonate-polymer synergy R&D programs. Prioritize backward integration into phosphonate intermediate production to neutralize raw material cost volatility from Chinese supply fluctuations. For New Entrants and Emerging Players: Differentiate on biodegradable polymer expertise targeting ANVISA environmental licensing requirements in Brazil pre-salt fields. White-space opportunities concentrate in digital chemical monitoring integration, where real-time scale deposition sensors create service-revenue attachment openings. Target subsea logistics optimization for remote Gulf of Mexico tiebacks as the most penetrable segment, leveraging concentrated emulsion formulations to reduce supply vessel frequency burdens. For Investors and Strategic Acquirers: Regional blending specialists with OSPAR-compliant chemistry portfolios and local manufacturing licenses represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance infrastructure rather than commodity chemical production, favoring targets with captive biodegradability testing capabilities. Watch for ANVISA licensing timeline acceleration as the signal indicating Brazil pre-salt field development inflection.| Strategic Initiative | Industry Significance |
|---|---|
| HPHT Testing Infrastructure Expansion | API RP 45 qualification requirements compress approved supplier bases to formulators with dedicated capabilities. |
| Backward Integration into Phosphonate Intermediates | In-house phosphonic acid production neutralizes raw material cost exposure from Chinese supply volatility. |
| Biodegradable Polymer R&D Partnerships | OSPAR and EPA NPDES discharge restrictions mandate formulation shifts toward compliant chemistry portfolios. |
| Digital Chemical Monitoring Integration | Real-time scale deposition sensors create automated injection system service-revenue attachment opportunities. |
| Local Blending Capacity in Brazil | ANVISA environmental licensing favors suppliers with Rio de Janeiro petrochemical complex manufacturing presence. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with chemical formulation directors, offshore production engineers, procurement leads at national oil companies, and HPHT testing laboratory managers; and secondary validation through customs trade data, OSPAR discharge permit filings, SEC 10-K chemical segment disclosures, and API certification registries. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against operator chemical spend disclosures anchored the market sizing framework.
Across the projection horizon, the analytical framework modeled chemistry type, application deployment, end-user procurement authority, and delivery mode logistics as core segmentation dimensions. CAGRs were derived from operator capital program disclosures and chemical treatment intensity benchmarks per well type. Forecast inputs incorporated subsea tieback architecture proliferation rates and regulatory compliance timeline shifts in the North Sea and Gulf of Mexico.
Forecasts assume regulatory continuity in OSPAR Harmonised Mandatory Control Scheme and EPA NPDES discharge permit regimes; material policy shifts would require re-modeling. Specific risks include accelerated biodegradability threshold tightening, phosphonate intermediate supply disruptions, and HPHT certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Regenerative Thermal Oxidizer Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
North America Quicklime Market