
 Gas Sweetening Chemicals Market | 2026-2036
Gas Sweetening Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Sweetening Chemicals Market Foresight
Asset-light leasing models for amine regeneration units are tilting competitive dynamics toward operators who avoid heavy balance-sheet commitments. BASF SE leverages its integrated amine production network to sustain margin control across multiple geographies. Dow Chemical Company anchors its position through captive supply of specialty amine formulations for high-H2S gas streams. Huntsman Corporation differentiates via deep specialization in methyl-diethanolamine blends for selective sulfur removal.
Gas sweetening chemicals are formulated absorbents, predominantly alkanolamine compounds such as monoethanolamine, diethanolamine, and methyldiethanolamine, engineered to remove hydrogen sulfide and carbon dioxide from sour gas streams through reversible acid-base reactions at 40-60°C contact temperatures. Their primary industrial purpose is to meet pipeline sulfur specifications and prevent downstream catalyst poisoning in hydrocarbon processing plants. Primary amines command the largest share of product type demand due to their aggressive H2S binding kinetics, though tertiary amines are gaining ground in selective CO2 removal applications where lower corrosion rates extend equipment life. Amine gas treating dominates technology deployment because decades of operational data reduce engineering risk for facility operators, while membrane separation occupies a growing niche in offshore platforms where footprint constraints override energy efficiency considerations.
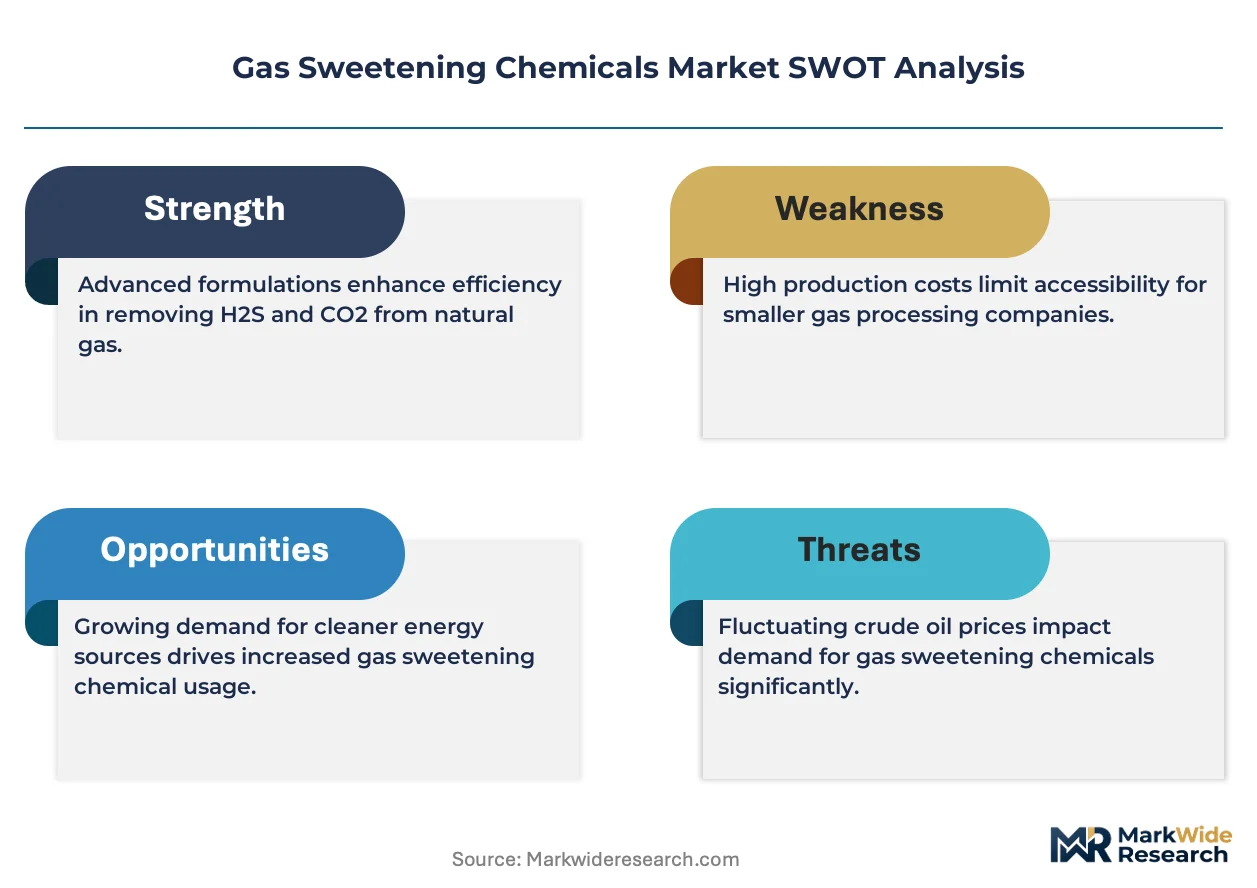
The US EPA enforces sulfur emissions limits under the Clean Air Act that mandate sub-ppm outlet concentrations from gas treatment facilities, while the EU F-Gas Regulation constrains fluorinated solvent alternatives that might otherwise compete with amine systems. China's MEE implements GB standards for sour gas processing that require domestic operators to match international discharge thresholds. Stakeholders must monitor how regulatory tightening in major gas-producing jurisdictions affects chemical consumption intensity per unit of treated gas volume.
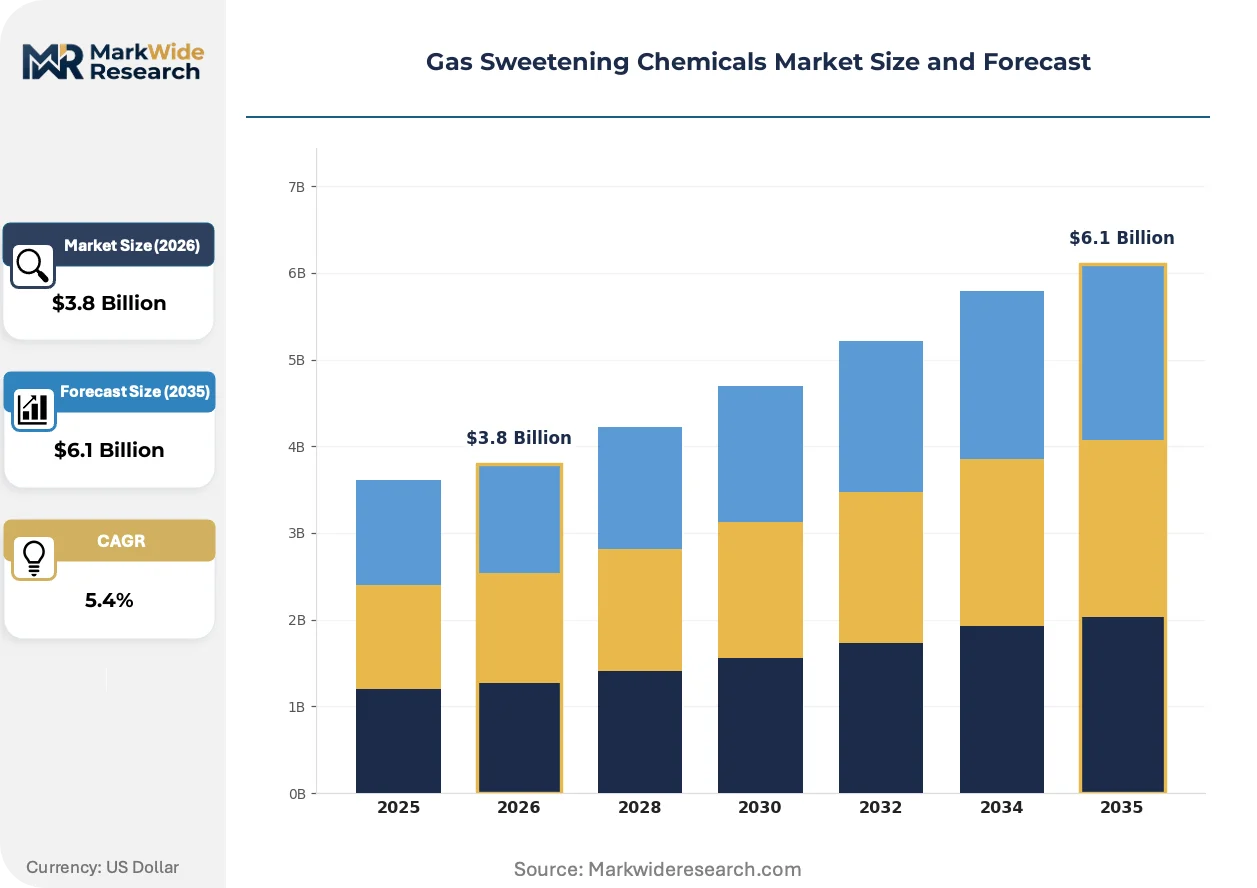
Market Dynamics
Asset-light leasing models for amine regeneration units are compressing capital deployment cycles and tilting procurement power toward operators who avoid heavy balance-sheet commitments. This structural shift favors chemical suppliers capable of delivering integrated service bundles rather than standalone product volumes.
Growth Catalysts
- EPA sulfur tightening:The US EPA's Clean Air Act amendments mandate sub-ppm outlet concentrations from gas treatment facilities, forcing processing plant upgrades and chemical consumption intensity increases.
- Permian Basin souring:Shale gas sulfur content runs high in West Texas and New Mexico clusters, creating concentrated demand for high-capacity amine systems among midstream operators.
- Membrane-amine hybridization:Offshore platform engineers deploy membrane pre-treatment upstream of amine units to reduce footprint and energy load in space-constrained environments.
Market Restraints
- Ethylene oxide feedstock volatility:Alkanolamine production depends on ethylene oxide availability, whose pricing swings with petrochemical cycle troughs compress blender margins unpredictably.
- MEA corrosion penalties:Primary amine systems require continuous inhibitor dosing and metallurgical upgrades to manage stress-corrosion cracking, adding lifecycle cost burdens.
- Fluorinated solvent substitution limits:The EU F-Gas Regulation constrains fluorinated solvent alternatives that might otherwise compete with amine systems in selective removal applications.
Strategic Opportunities
- China shale sulfur surge:The Sichuan Basin's high-sulfur tight gas reserves require treatment intensity matching US Permian specifications, opening volume expansion for formulated amine suppliers.
- Regenerable ionic liquids:Ionic liquid absorbents with lower vapor pressure and thermal degradation rates are hybridizing with conventional amine infrastructure in pilot installations.
- Carbon capture co-processing:Post-combustion carbon capture retrofits at power stations create dual-purpose chemical demand for selective CO2 removal alongside trace H2S polishing.
Industry Challenges
- Amine chemist scarcity:Formulation expertise for selective H2S/CO2 separation has concentrated among retiring specialists, constraining R&D pipeline velocity for next-generation blends.
- Legacy unit retrofit complexity:Brownfield amine absorber modifications require staged tie-ins that extend commissioning timelines and disrupt continuous gas processing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Sweetening Chemicals Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Amines, Secondary Amines, Tertiary Amines, Organic Solvents Application: Natural Gas Processing, Oil Refining, Petrochemicals, Biogas Treatment End User: Oil & Gas, Chemical Manufacturing, Power Generation, Waste Management Technology: Amine Gas Treating, Membrane Separation, Pressure Swing Adsorption, Cryogenic Distillation |
| Companies Covered | Huntsman Corporation, BASF SE, Dow Chemical Company, China Petroleum & Chemical Corporation, SABIC, INEOS Group Holdings S.A., Air Products and Chemicals, Inc., Arkema Group, Chevron Phillips Chemical Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Sweetening Chemicals Market Shifts & Advancements
Operational data analytics and modular system architectures are compressing engineering risk and enabling predictive chemical management in remote gas processing facilities. These capabilities are reshaping how operators specify and procure sweetening chemistry.
Hybrid amine formulations combining methyldiethanolamine with piperazine activators are hybridizing selective H2S removal with accelerated mass transfer kinetics. Midstream operators in the Gulf Coast corridor adopt these blends to process high-CO2 associated gas without multiple absorption stages. The technology is compressing absorber column height requirements and reducing reboiler duty by fifteen to twenty percent versus conventional MEA systems.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbons is eliminating fluorinated solvent competition in selective gas treatment applications. Industrial consequence flows through to amine system designers who face reduced substitution pressure in EU-licensed offshore platforms. North Sea operators respond by extending amine unit depreciation schedules and deferring membrane pilot investments previously contemplated as F-gas alternatives.
Leasing arrangements for regeneration skids and reclaiming units are displacing capital purchase models among independent gas processors. Mid-tier operators in the Appalachian Basin and Oklahoma SCOOP/STACK plays favor operating-expense treatment of chemical handling infrastructure. This shift concentrates procurement influence with service-integrated suppliers capable of remote monitoring and predictive chemical replenishment.
Gas Sweetening Chemicals Market Segmentation
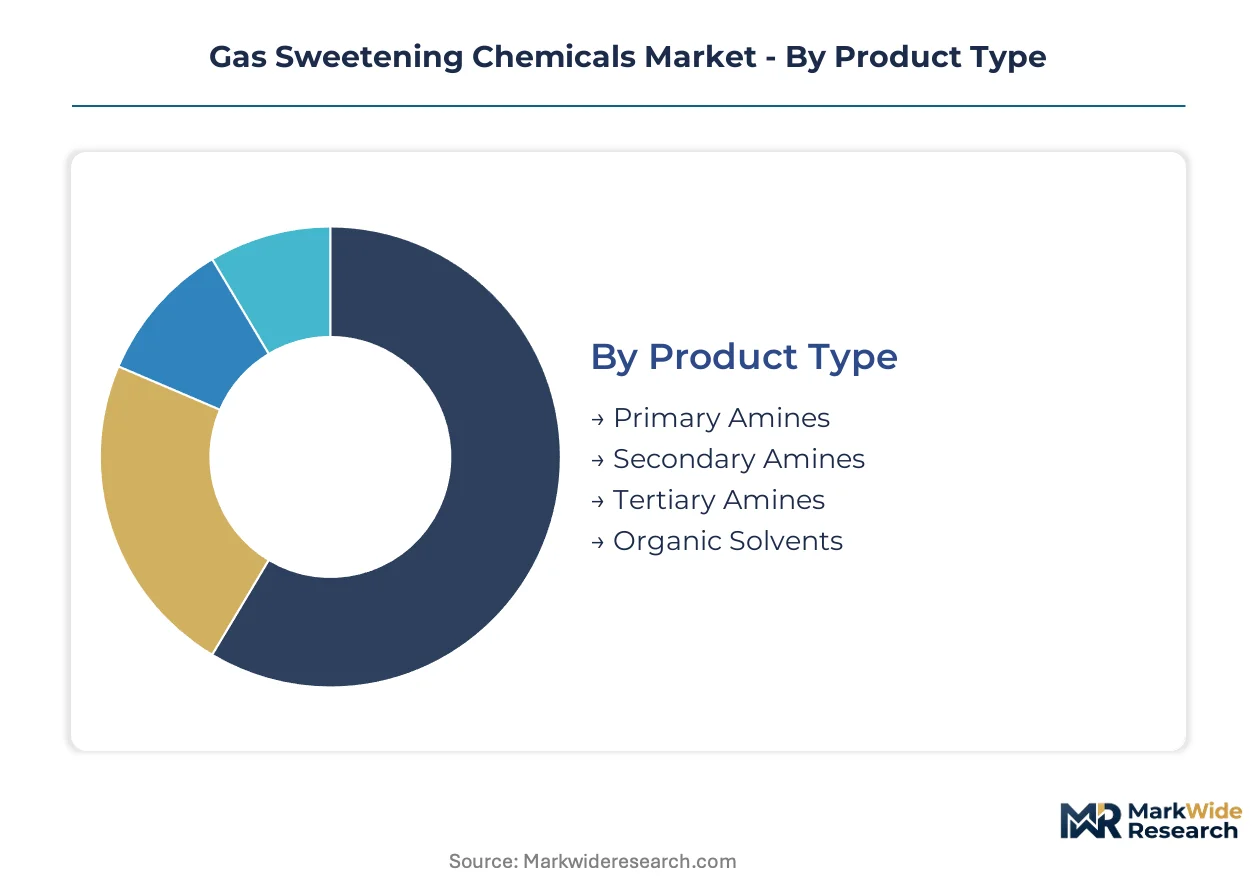
Segmentation in gas sweetening chemicals reveals how formulation chemistry, treatment intensity, and facility scale intersect to determine procurement patterns. Suppliers must align product portfolios with the sulfur loading profiles and capital constraints that vary across upstream, midstream, and downstream operators.
Product Type:
Mature commodity chemistries dominate volume flows while specialty blends capture margin expansion in high-severity applications.
- Primary Amines:Monoethanolamine and diethanolamine formulations deliver aggressive H2S binding kinetics through rapid acid-base reactions at 40-60°C contact temperatures. Demand concentrates in Permian Basin midstream facilities processing high-sulfur shale gas where EPA-mandated sub-ppm outlet specifications require maximum removal efficiency. Corrosion inhibitor dosing and metallurgical upgrades add lifecycle cost burdens that operators accept for guaranteed compliance.
- Tertiary Amines:Methyldiethanolamine blends enable selective H2S removal in CO2-rich gas streams through sterically hindered reaction pathways that suppress carbonate formation. Gulf Coast operators processing associated gas from high-CO2 formations adopt these formulations to reduce reboiler duty and absorber column height versus conventional systems.
- Secondary Amines:Diisopropanolamine occupies niche applications in refinery fuel gas treaters requiring intermediate reactivity.
- Organic Solvents:Sulfolane and proprietary physical solvents serve high-acid-gas-concentration streams where chemical absorption economics deteriorate.
Primary amines retain volume leadership; tertiary amines hold the steepest expansion curve.
Application:
Application segmentation tracks sulfur content gradients across hydrocarbon value chains from wellhead to finished product.
- Natural Gas Processing:Pipeline specification enforcement and LNG liquefaction pretreatment drive formulation demand in gathering systems and processing plants. West Texas and New Mexico clusters generate concentrated procurement for high-capacity amine systems as sour gas reserves deepen.
- Oil Refining:Catalytic cracker and hydrotreater off-gas treatment requires selective H2S polishing to protect downstream sulfur recovery units. Complex refineries on the US Gulf Coast blend multiple amine types across integrated processing trains.
- Petrochemicals:Steam cracker feedstock pretreatment and syngas conditioning in methanol and ammonia plants utilize formulated absorbents for trace contaminant control.
- Biogas Treatment:Anaerobic digester output upgrading to pipeline quality or vehicle fuel specifications employs amine scrubbing alongside membrane and PSA alternatives.
Natural gas processing commands the largest share of chemical consumption; biogas treatment is expanding most quickly as renewable natural gas subsidies mature.
End User:
End user categories reflect capital intensity differentials between integrated majors and independent operators.
- Oil & Gas:Upstream producers and midstream gatherers specify sweetening chemistry based on reservoir sulfur signatures and pipeline tariff structures. Independent processors in Oklahoma's SCOOP/STACK plays favor leasing arrangements for regeneration infrastructure over capital purchase.
- Chemical Manufacturing:Ammonia, methanol, and hydrogen producers require ultra-low sulfur feedstocks to protect synthesis catalysts, driving demand for high-purity amine systems with reclamation capabilities.
- Power Generation:Natural gas-fired plants with post-combustion carbon capture retrofits create dual-purpose chemical demand for selective CO2 removal alongside trace H2S polishing.
- Waste Management:Landfill gas and wastewater treatment biogas upgrading facilities represent emerging volume as renewable fuel incentives expand.
Oil and gas retains procurement dominance; waste management is gaining share fastest on biogas infrastructure buildout.
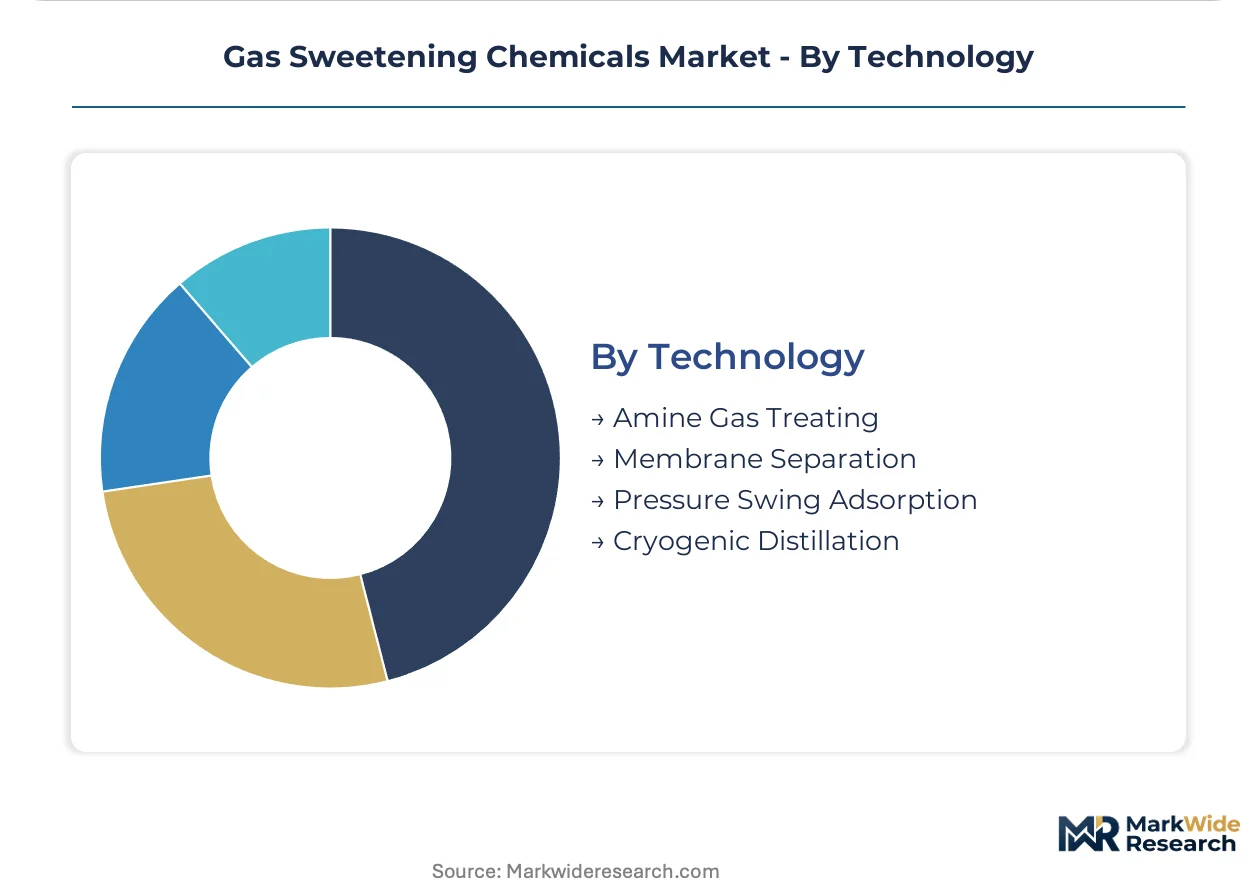
Technology:
Technology segmentation captures the tradeoff between operational certainty and energy efficiency in gas treatment design.
- Amine Gas Treating:Decades of operational data reduce engineering risk for facility operators, sustaining dominance despite higher energy intensity versus alternatives. BASF SE and Dow Chemical Company anchor supply positions through integrated production networks and captive specialty formulations.
- Membrane Separation:Polymeric and inorganic membranes occupy growing niches in offshore platforms where footprint constraints override energy efficiency considerations, often deployed as pre-treatment upstream of amine units.
- Pressure Swing Adsorption:Molecular sieve systems serve small-scale biogas upgrading and hydrogen purification where amine infrastructure scale is uneconomical.
- Cryogenic Distillation:Low-temperature separation remains limited to high-nitrogen or helium-rich gas streams where multiple component recovery justifies capital intensity.
Amine gas treating retains volume leadership; membrane separation holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented gas sweetening chemical producers in Germany and the United States supply formulated amine blends to sour gas processing facilities across multiple continents, while import-dependent markets in Asia-Pacific and the Middle East rely on these shipments for refinery and LNG pretreatment operations.
United States
EPA sulfur tightening under the Clean Air Act mandates sub-ppm outlet concentrations from gas treatment facilities, forcing processing plant upgrades throughout the Permian Basin and Gulf Coast clusters where shale gas sulfur content runs high and midstream operators deploy high-capacity amine systems.
China
The Sichuan Basin's high-sulfur tight gas reserves require treatment intensity matching international specifications, with MEE implementing GB standards for sour gas processing that require domestic operators to match discharge thresholds prevalent in developed markets.
Germany
EU F-Gas Regulation constraints on fluorinated solvent alternatives protect amine system market share, while industrial chemical producers in the Rhine-Ruhr corridor formulate specialty blends for export to sour gas processing facilities across Europe and beyond.
Saudi Arabia
High-H2S associated gas from Ghawar and other mega-fields drives demand for selective removal formulations, with domestic petrochemical integration projects requiring ultra-low sulfur feedstocks to protect synthesis catalysts in ammonia and methanol trains.
Canada
Alberta oil sands operations and British Columbia shale gas developments generate concentrated demand for gas sweetening chemistry, with provincial environmental regulations enforcing sulfur recovery standards that mirror EPA thresholds south of the border.
Gas Sweetening Chemicals Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated chemical majors with captive ethylene oxide feedstock positions and specialized amine formulation capabilities. Three strategic archetypes dominate: integrated petrochemical conglomerates with backward control into ethylene oxide, specialty chemical houses focused on selective removal formulations, and regional state-owned enterprises serving captive domestic demand. Competitive moves concentrate on capacity expansion in high-sulfur gas provinces and technology licensing arrangements for hybrid amine-membrane systems.
Among integrated chemical majors, BASF SE and Dow Chemical Company anchor the premium formulation tier through integrated production networks spanning multiple geographies, while Huntsman Corporation occupies a specialist position in methyl-diethanolamine blends for selective sulfur removal applications. These three represent contrasting strategic postures: scale-driven vertical integration, captive specialty supply, and deep product specialization respectively.
| Leading Market Players |
|---|
| Huntsman Corporation |
| BASF SE |
| Dow Chemical Company |
| China Petroleum & Chemical Corporation |
| SABIC |
| INEOS Group Holdings S.A. |
| Air Products and Chemicals, Inc. |
| Arkema Group |
| Chevron Phillips Chemical Company LLC |
| Others |
Supply & Pricing Matrix
Ethylene oxide feedstock volatility determines both pricing tier spreads and supply chain shape in gas sweetening chemicals, compressing blender margins during petrochemical cycle troughs while forcing procurement concentration among integrated producers with captive supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on formulation purity and EPA compliance certification. Price differentiation stems from volume scale and vertical integration depth, with integrated majors capturing margin premiums during ethylene oxide shortages. Cost compression in standard-grade MEA formulations is intensifying because shale gas processors prioritize total lifecycle cost over unit chemistry spend. Independent midstream operators in the Permian Basin exhibit highest price sensitivity, while integrated chemical manufacturing end-users demonstrate lowest sensitivity due to catalyst protection requirements.
Supply Chain Analysis
BASF SE and Dow Chemical Company hold captive ethylene oxide capacity across Germany, the United States, and China, anchoring global formulation supply. Alkanolamine production draws from ethylene oxide, ammonia, and methanol feedstocks, with single-source vulnerability concentrated in Gulf Coast ethylene cracker complexes. Tariff exposure on specialty amine imports into China and the EU threatens regional supply continuity. Distribution runs through integrated chemical distributors and direct mill-to-plant pipelines for high-volume midstream operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas sweetening chemicals are approaching a platform-economics inflection as leasing models for regeneration infrastructure create service-integrated supplier ecosystems that lock in chemical offtake through predictive replenishment systems.
For Market Incumbents: Insulate margin positions by deepening backward integration into ethylene oxide and expanding reclaiming service footprints in the Permian Basin and Sichuan Basin. Membrane-amine hybridization threatens standalone amine volumes; counter by embedding IoT-enabled chemical management platforms that extend contractual switching costs. Prioritize certification investment for China GB standards compliance ahead of domestic competitor scale-up. For New Entrants and Emerging Players: Establish a beachhead in biogas upgrading applications where renewable natural gas subsidies create price-tolerant demand and incumbent chemical majors lack dedicated service infrastructure. Target landfill gas and wastewater treatment facilities in North America and Europe with modular, skid-mounted amine systems leased on opex terms. Lead with carbon-negative positioning aligned with EU Green Deal procurement preferences. For Investors and Strategic Acquirers: EPA sulfur tightening under Clean Air Act amendments reshapes the acquisition landscape toward formulated amine suppliers with proven sub-ppm removal capabilities and established midstream operator relationships. Long-term viability favors service-integrated chemical platforms over standalone commodity blenders. Watch for inflection signals in Sichuan Basin development timelines and China MEE enforcement intensity on GB standard adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates margin compression during petrochemical cycle troughs. |
| Leasing Model Expansion for Regeneration Units | Asset-light structures concentrate procurement influence with service-integrated suppliers. |
| Hybrid Amine-Piperazine Formulation Launch | MDEA-activated blends reduce reboiler duty for Gulf Coast high-CO2 associated gas processors. |
| China GB Standards Certification Investment | MEE enforcement on Sichuan Basin sour gas processing creates compliant-supplier preference. |
| Biogas Upgrading Service Platform Buildout | Renewable natural gas subsidies in North America and Europe open price-tolerant volume segments. |
Research Methodology
Cross-validation between plant manager interviews at Permian Basin processing facilities and Dow Chemical Company SEC 10-K disclosures anchors the qualitative findings. Primary fieldwork engaged procurement leads at midstream gatherers, technical R&D directors at formulated amine suppliers, and distribution channel partners across North America, Europe, and Asia-Pacific. Secondary validation drew from US EPA enforcement data, China MEE GB standard filings, EU ECHA REACH registrations, and ACC industry statistics. Bottom-up chemical consumption estimates triangulate against top-down market sizing from trade flow analysis.
Calibration against historical capacity utilization rates and patent filing trajectories shapes the projection framework across the analysis window. Segmentation dimensions modeled include amine type tier, end-use industry cluster, treatment technology configuration, and regional regulatory stringency. CAGRs derive from elasticity-adjusted demand curves incorporating shale gas sulfur content trends and carbon capture retrofit penetration. Forecast inputs incorporate ethylene oxide price cycle assumptions and membrane separation technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in natural gas benchmark pricing or ethylene cracker operating rates would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and sour gas reserve depletion patterns. Quarterly review of EPA consent decree filings, China shale production statistics, and EU F-Gas Regulation phase-down progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Barbituric Acid Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Europe Biguanide Market
Chemicals
Diphosphate Market
Chemicals
Flooring Chemicals Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
De-Icing Agents Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
Lime Sulfur Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Non PVC Plasticizers Market
Chemicals
South America Construction Chemicals Market