
 China Amines Market | 2026-2036
China Amines Market Size, Share, and Industry Trends Forecast 2026-2036
China Amines Market Outlook
The divergence between pharmaceutical-grade and industrial-grade amine specifications is hardening in China's procurement channels. BASF SE leverages its integrated Ludwigshafen-to-Nanjing technology corridor to sustain high-purity methylamine output for regulated applications. Shandong IRO Amine Industry Co., Ltd. anchors domestic supply of commodity butylamine through captive ammonia sourcing across its Shandong facilities. Huntsman Corporation differentiates via specialized ethylamine formulations serving epoxy curing agents in the Pearl River Delta.
Amines are nitrogen-containing organic compounds derived from ammonia by replacement of one or more hydrogen atoms with alkyl or aryl groups, typically manufactured through catalytic hydrogenation of alcohols or nitriles with hydrogen over metal catalysts at elevated pressures. These compounds function as essential intermediates in agrochemical synthesis, pharmaceutical active ingredient production, polyurethane foam generation, and surfactant formulation. Methylamine dominates volume flows into agricultural pesticide manufacturing, where margin pools remain thin but offtake scales reliably. Ethylamine segments serving pharmaceutical applications command premium pricing due to stringent purity thresholds and CDSCO-aligned documentation requirements. Butylamine applications in plastics and rubber accelerators represent a maturing demand pocket with slower expansion trajectories.
China's Ministry of Ecology and Environment enforces GB 31571 emission standards for chemical enterprises, compelling amine producers to deploy vapor recovery and wastewater treatment upgrades that elevate capital intensity. The MIIT oversees industrial chemical capacity approvals under national dual carbon targets, restricting new coal-to-chemical amine projects in water-stressed provinces. GB standards for food-contact amines and pharmaceutical-grade specifications from NMPA create layered compliance thresholds that filter market access. Stakeholders must monitor how provincial carbon intensity quotas and Yangtze River basin environmental enforcement reshape cost structures for integrated versus merchant producers.
Market Dynamics
China's dual carbon targets are restructuring amine production economics, forcing coal-to-chemical operators toward natural gas feedstock conversion while tightening emission permits across the Yangtze River basin.
Growth Catalysts
- GB 31571 Enforcement:The Ministry of Ecology and Environment's emission standards are accelerating vapor recovery system deployment, creating compliant capacity scarcity that rewards early upgraders in Jiangsu and Zhejiang.
- Pharmaceutical Formulator Expansion:Shanghai-based CDMOs are scaling high-purity ethylamine offtake for active pharmaceutical ingredient synthesis, pulling specialty grade premiums above commodity methylamine benchmarks.
- Agrochemical Cluster Integration:Yangtze River Delta pesticide manufacturers are consolidating procurement through long-term supply agreements with captive ammonia producers, locking in volume commitments.
Market Restraints
- Coal-to-Chemical Feedstock Lock-In:Legacy producers in Shanxi and Inner Mongolia face stranded asset risk as MIIT restricts new coal-based capacity approvals under carbon intensity quotas.
- Natural Gas Price Volatility:Import-dependent LNG pricing swings compress margins for gas-based hydrogenation routes, disadvantaging coastal producers versus integrated coal-chemical inland complexes.
- High-Purity Import Dependency:Pharmaceutical-grade specifications aligned with NMPA and CDSCO documentation requirements still rely on BASF Ludwigshafen-to-Nanjing corridor supply for critical purity thresholds.
Strategic Opportunities
- Guangdong Epoxy Curing Agent Demand:Pearl River Delta electronics manufacturers are expanding ethylamine consumption for printed circuit board laminates, creating geographic diversification beyond agrochemical concentration.
- Biogenic Amine Pathways:Fermentation-derived amine technologies are approaching pilot scale, offering carbon-accounting advantages for exporters facing EU CBAM scope 3 disclosure requirements.
- Food-Contact Certification Gap:GB standards for food-grade amines remain underpenetrated, with only three domestic producers holding full NMPA registration for packaging applications.
Industry Challenges
- Catalyst Specialist Scarcity:Hydrogenation process engineers with experience in continuous-flow methylamine synthesis command premium compensation, constraining brownfield expansion timelines.
- Wastewater Treatment Capex Burden:Zero-liquid-discharge mandates in water-stressed provinces require membrane bioreactor and evaporation crystallization investments exceeding RMB 80 million per facility.
- Dual-Carbon Compliance Documentation:Provincial carbon intensity audits demand granular scope 1 and 2 data collection systems that legacy ERP infrastructure cannot support without middleware overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Amines Market |
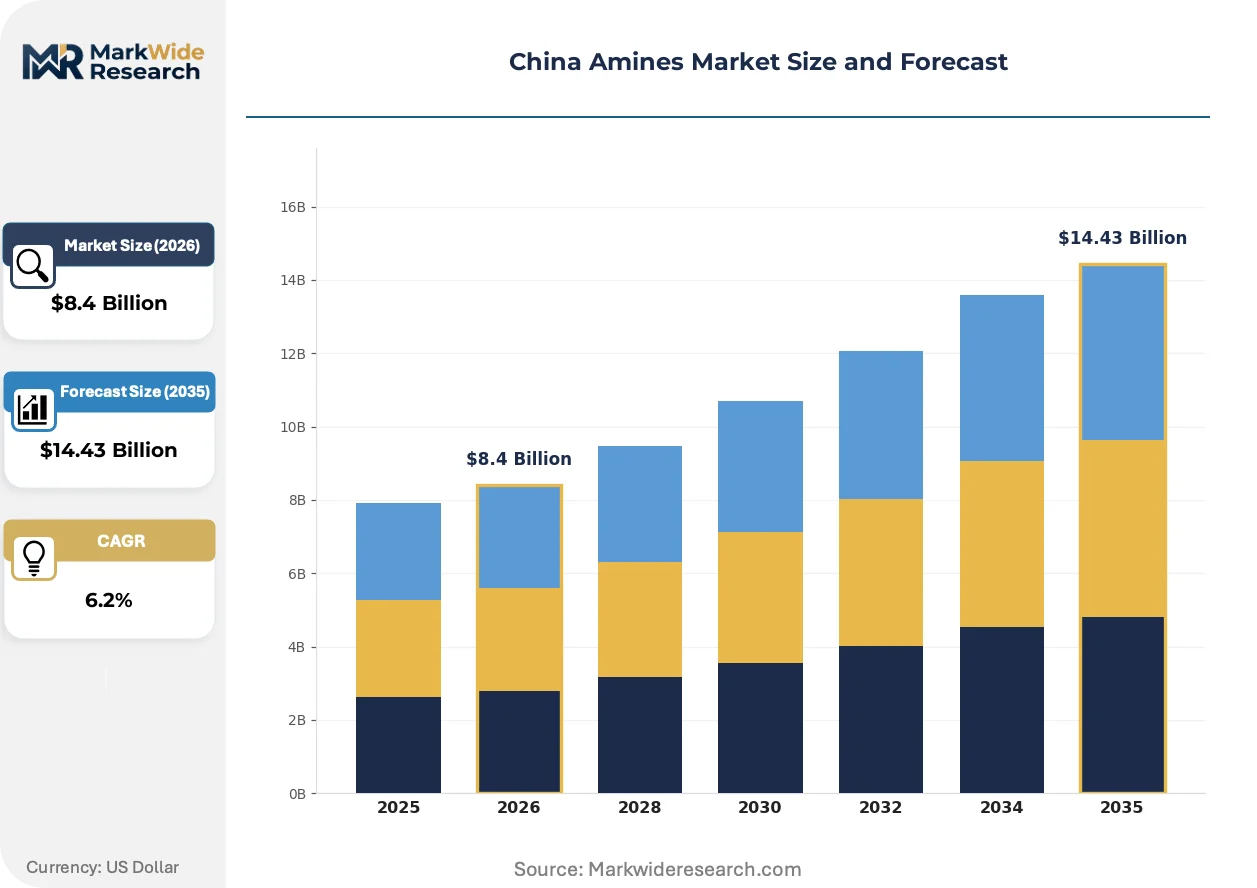
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylamine, Ethylamine, Propylamine, Butylamine Application: Agriculture, Pharmaceuticals, Plastics, Personal Care End User: Chemical Industry, Agriculture Sector, Consumer Goods, Food Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | BASF SE, Evonik Industries AG, Eastman Chemical Company, Shandong IRO Amine Industry Co., Ltd., INEOS, Akzo Nobel NV, Huntsman Corporation, Henan Prosper Chemicals Co Ltd, Quzhou New Refrigeration Material Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Amines Market Strategic Shifts
Continuous-flow hydrogenation reactor designs are displacing batch operations across Chinese amine plants, compressing cycle times while enabling tighter purity control for regulated applications.
Membrane separation technology for amine-water distillation is expanding into Jiangsu and Shandong facilities, replacing energy-intensive conventional columns. Pharmaceutical formulators in Taizhou and Taixing are specifying membrane-refined feedstock for genotoxic impurity compliance. This shift is compressing the cost gap between commodity and high-purity grades, forcing batch operators toward specialty product mix reconfiguration.
GB standards for carbon emission accounting in chemical manufacturing are tightening documentation requirements for scope 1 and 2 disclosures. The MIIT's provincial allocation system now ties production permits to verified emission intensity baselines, elevating compliance overhead for merchant producers. Shandong-based integrated operators with captive power and ammonia synthesis are capturing permit advantages versus standalone hydrogenation facilities.
Long-term supply contracting is displacing spot market transactions among Yangtze River Delta agrochemical manufacturers. Formulators in Nantong and Changzhou are locking in eighteen to twenty-four month methylamine commitments to secure volume against carbon-constrained capacity expansions. This pattern is most visible in herbicide intermediate procurement, where just-in-time inventory models are proving incompatible with emission-permit volatility.
China Amines Market Segmentation
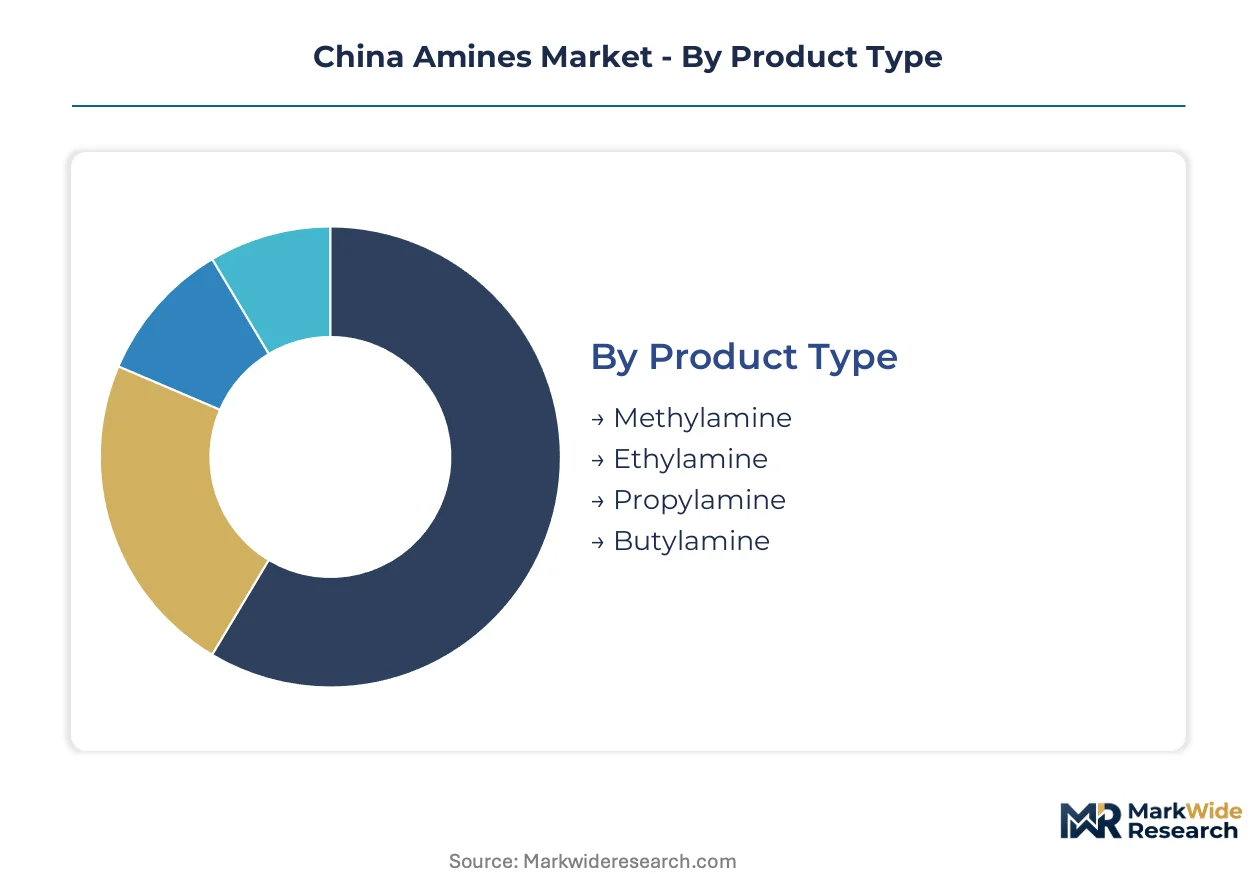
Segmentation in China's amines market reveals how regulatory pressure and end-use purity requirements split procurement channels. Divergent compliance thresholds across GB standards and NMPA specifications force buyers into distinct sourcing strategies that reshape competitive positioning.
Product Type:
Standalone commodity amines serve bulk industrial applications through established hydrogenation routes, while high-purity derivatives embed into regulated pharmaceutical and electronics supply chains with stringent documentation requirements.
- Methylamine:Primary aliphatic amine manufactured via catalytic hydrogenation of methanol with ammonia over silica-alumina catalysts at elevated pressure. Yangtze River Delta agrochemical manufacturers in Nantong and Changzhou consolidate procurement through long-term supply agreements, locking volume commitments against carbon-constrained capacity expansions.
- Ethylamine:Two-carbon chain amine requiring tighter distillation control for genotoxic impurity compliance. Shanghai-based CDMOs are scaling offtake for active pharmaceutical ingredient synthesis, pulling specialty grade premiums above commodity benchmarks as NMPA documentation requirements harden.
- Propylamine:Intermediate chain length amine serving surfactant and corrosion inhibitor applications with moderate purity specifications.
- Butylamine:Longer-chain derivative anchoring rubber accelerator and plastics additive demand through Shandong integrated production complexes with captive ammonia sourcing.
Methylamine leads volumes today; ethylamine is gaining share fastest.
Application:
Cost tier stratification separates thin-margin bulk chemical consumption from premium-priced regulated applications where certification overhead elevates procurement budgets.
- Agriculture:Dominant demand pocket absorbing methylamine volumes for herbicide and pesticide intermediate synthesis. Yangtze River Delta formulators in Jiangsu consolidate procurement through eighteen to twenty-four month supply commitments, abandoning just-in-time models incompatible with emission-permit volatility.
- Pharmaceuticals:High-purity ethylamine and specialty derivatives for active ingredient production. CDSCO-aligned documentation requirements and NMPA registration thresholds sustain import dependency for critical purity grades through the Ludwigshafen-to-Nanjing technology corridor.
- Plastics:Butylamine consumption for rubber accelerators and polymer stabilizers, representing maturing demand with slower expansion trajectories.
- Personal Care:Surfactant and emulsifier applications requiring food-contact GB compliance, with only three domestic producers holding full NMPA registration for packaging-grade specifications.
Agriculture anchors volume concentration; pharmaceuticals command the steepest margin premiums.
End User:
Customer type fragmentation tracks capital intensity divergence between integrated chemical complexes and specification-sensitive downstream formulators.
- Chemical Industry:Merchant hydrogenation operators and integrated ammonia-amine producers supplying intermediate feedstocks. Shandong-based operators with captive power and synthesis capacity capture permit advantages versus standalone facilities under MIIT carbon intensity quotas.
- Agriculture Sector:Pesticide and herbicide manufacturers in the Yangtze River Delta chemical cluster, where procurement consolidation through long-term agreements is displacing spot market transactions.
- Consumer Goods:Personal care and household product formulators requiring GB-compliant amine derivatives for surfactant applications.
- Food Industry:Packaging and processing applications demanding food-contact certification, an underpenetrated segment with registration barriers filtering domestic supply.
Chemical Industry procurement dominates tonnage; Food Industry specifications remain the least contested entry point.
Distribution Channel:
Supply concentration in coastal chemical clusters shapes logistics economics, favoring direct procurement for bulk volumes while fragmented inland demand sustains intermediary layers.
- Direct Sales:Long-term supply agreements between integrated producers and Yangtze River Delta agrochemical manufacturers, locking eighteen to twenty-four month methylamine commitments against carbon-constrained capacity.
- Distributors:Regional chemical traders bridging merchant hydrogenation facilities to smaller plastics and personal care formulators lacking volume scale for direct contracting.
- Online Retail:Digital platforms serving laboratory-scale and specialty grade procurement for research institutions and pilot-scale pharmaceutical developers.
- Wholesale:Bulk aggregation points for commodity methylamine moving into inland agriculture provinces, though emission-permit volatility is compressing spot market liquidity.
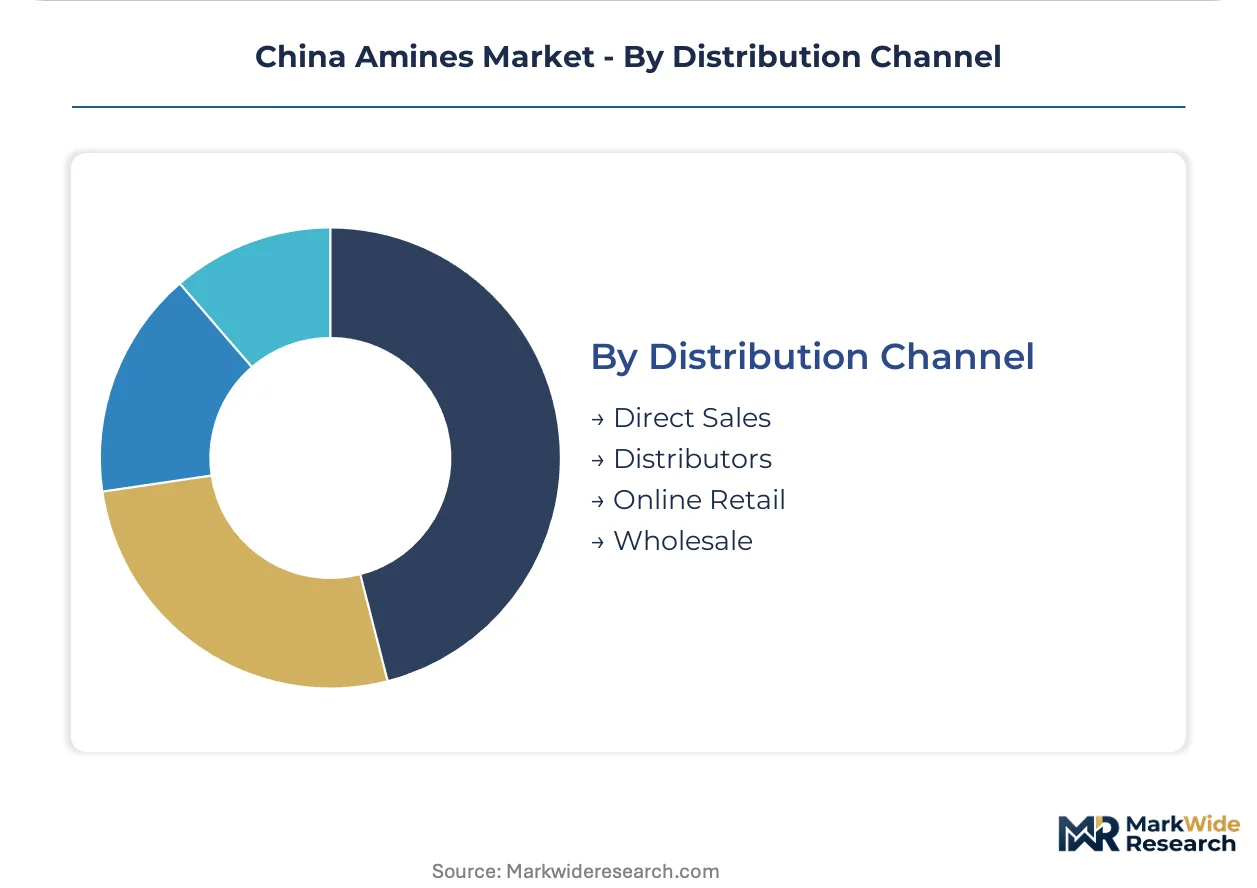
Direct Sales channels handle the largest contracted volumes; Distributor networks retain relevance for geographic coverage beyond core chemical clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters in the Yangtze River Delta anchor China's amine production capacity. Provincial carbon intensity quotas and GB emission standards reshape facility economics across coastal and inland chemical belts.
Yangtze River Delta
Shanghai-based CDMOs scale high-purity ethylamine offtake for pharmaceutical synthesis. MEE enforces GB 31571 emission standards that accelerate vapor recovery deployment across Jiangsu and Zhejiang facilities. Nantong and Changzhou pesticide manufacturers consolidate procurement through eighteen to twenty-four month supply commitments.
Shandong Peninsula
Integrated ammonia-amine producers leverage captive feedstock sourcing for butylamine output. MIIT carbon intensity quotas reward operators with in-house power and synthesis capacity versus standalone hydrogenation facilities. Qingdao and Zibo chemical complexes capture permit advantages under provincial dual-carbon auditing systems.
Pearl River Delta
Electronics manufacturers in Guangdong expand ethylamine consumption for printed circuit board laminates and epoxy curing agents. SAMR oversees industrial chemical registration requirements that filter market access for specialty formulations. Shenzhen and Dongguan industrial parks anchor demand diversification beyond agrochemical concentration.
Beijing-Tianjin-Hebei
Research institutions and pilot-scale developers drive laboratory-grade amine procurement for pharmaceutical R&D. NMPA pharmaceutical-grade specifications sustain import dependency for critical purity thresholds in regulated applications. Tianjin port infrastructure supports BASF Ludwigshafen-to-Nanjing corridor logistics for high-purity methylamine derivatives.
Sichuan-Chongqing
Western chemical producers explore natural gas feedstock conversion as MIIT restricts new coal-based capacity approvals. Provincial environmental bureaus enforce zero-liquid-discharge mandates in water-stressed upstream regions. Chongqing chemical parks test membrane separation technologies for amine-water distillation efficiency gains.
China Amines Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across China's amine procurement channels. The market structure splits between integrated ammonia-amine operators with captive feedstock and merchant hydrogenation facilities dependent on spot ammonia sourcing. Three archetypes dominate: multinational technology licensors with purity-certified import corridors, provincial integrated chemical complexes with carbon-permit advantages, and regional distributors bridging fragmented inland demand. Competitive moves center on long-term supply contracting displacement of spot transactions and emission-compliant capacity upgrades ahead of MIIT permit renewal cycles.
Among multinational technology providers, BASF SE and Evonik Industries AG occupy positions exemplifying import-dependent high-purity supply. Within domestic integrated production, Shandong IRO Amine Industry Co., Ltd. represents the provincial chemical complex archetype with captive ammonia sourcing. These named entities anchor commentary on how technology licensing fees and carbon-permit scarcity reshape margin capture across the value chain.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Eastman Chemical Company |
| Shandong IRO Amine Industry Co., Ltd. |
| INEOS |
| Akzo Nobel NV |
| Huntsman Corporation |
| Henan Prosper Chemicals Co Ltd |
| Quzhou New Refrigeration Material Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical formulators in Shanghai and Jiangsu are tightening purity specifications for ethylamine derivatives, compelling suppliers to deploy membrane separation and continuous-flow hydrogenation technologies that compress margins on commodity grades while sustaining premiums for certified batches. This demand-side quality escalation fragments procurement channels into specification-tethered supply relationships with divergent pricing power.
Pricing Analysis
Long-term offtake contracting dominates methylamine procurement, with eighteen to twenty-four month agreements displacing spot transactions among Yangtze River Delta agrochemical manufacturers. Price differentiation hinges on NMPA certification tier and captive ammonia integration, with integrated Shandong operators capturing margin advantages versus merchant hydrogenation facilities. Cost compression in commodity methylamine runs through emission-permit scarcity and natural gas feedstock volatility, while pharmaceutical-grade ethylamine sustains pricing resilience. Agriculture sector buyers exhibit highest price sensitivity; pharmaceutical CDMOs prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Nantong and Changzhou pesticide manufacturers mandate qualification of at least two methylamine suppliers per procurement contract, fragmenting volume concentration. Supply concentrates in China, with BASF's Ludwigshafen-to-Nanjing corridor anchoring high-purity import dependency. Feedstock draws from captive ammonia synthesis, merchant methanol, and natural gas hydrogenation routes. Single-source vulnerability persists for pharmaceutical-grade catalysts and specialized hydrogenation engineering talent. Distribution runs through direct sales for bulk volumes, with regional distributors bridging fragmented inland personal care and plastics demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with CDSCO-aligned documentation requirements and NMPA pharmaceutical-grade specifications pulling procurement toward certified supply relationships that reward early compliance investment.
For Market Incumbents: Deepen captive ammonia integration across Shandong facilities to defend margin position against natural gas price volatility and MIIT carbon intensity quota enforcement. Prioritize membrane separation capacity upgrades ahead of GB 31571 permit renewal cycles to capture compliant capacity scarcity premiums. Lock eighteen to twenty-four month supply commitments with Yangtze River Delta agrochemical formulators before brownfield expansion timelines extend. For New Entrants and Emerging Players: GB standards for food-contact amines in China open a window for NMPA registration investment, with only three domestic producers currently holding full certification for packaging applications. Target personal care surfactant procurement channels in fragmented inland provinces where distributor networks retain relevance. Pursue pilot-scale fermentation-derived amine partnerships with EU-facing exporters confronting CBAM scope 3 disclosure requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated ammonia-amine operators in Shandong and Jiangsu with verified emission intensity baselines and captive power infrastructure. Long-term viability over a five-to-ten year window favors assets with backward control over hydrogenation feedstock and documented compliance with provincial dual-carbon auditing systems. Watch provincial carbon intensity quota allocation announcements as the critical inflection signal for permit-advantaged capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ammonia | Shandong-based operators with in-house synthesis capture MIIT permit advantages versus merchant facilities. |
| Membrane Separation Technology Deployment | Jiangsu pharmaceutical formulators specify membrane-refined feedstock for genotoxic impurity compliance. |
| NMPA Food-Contact Certification Investment | Only three domestic producers hold full registration for packaging-grade amine specifications. |
| Long-term Supply Agreement Lock-in | Nantong and Changzhou herbicide manufacturers abandon just-in-time models for emission-permit security. |
| Biogenic Amine Pathway Pilot Development | Fermentation-derived technologies offer carbon-accounting advantages for EU CBAM-facing exporters. |
Study Parameters
Coverage spans China's Yangtze River Delta, Shandong Peninsula, Pearl River Delta, and Sichuan-Chongqing chemical belts, with primary inputs from each. The analysis combines interviews with plant managers at integrated ammonia-amine facilities, procurement leads at agrochemical formulators, distribution channel partners in inland provinces, and technical R&D directors specializing in hydrogenation catalysts. Secondary validation draws from MIIT capacity approval filings, MEE emission compliance disclosures, NMPA registration databases, and provincial carbon intensity audit reports. Bottom-up volume modeling and top-down value reconciliation ensure cross-verified outputs.
Granularity extends to methylamine, ethylamine, propylamine, and butylamine product tiers; agriculture, pharmaceutical, plastics, and personal care applications; and direct sales versus distributor channel splits across the projection horizon. CAGRs derive from segmented demand elasticity modeling against carbon-constrained supply expansion timelines. Key inputs include provincial dual-carbon quota allocation trajectories, GB standard implementation schedules, and pharmaceutical formulator CDMO expansion pipelines.
Revisions become necessary when MIIT restricts coal-to-chemical capacity approvals beyond current provincial quotas, when MEE tightens GB 31571 enforcement thresholds, or when EU CBAM scope 3 disclosure requirements accelerate biogenic amine substitution. Deviation in any of these regulatory triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Allyl Alcohol Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Detergent Alcohols Market
Chemicals
Menadione Market
Chemicals
Copper Oxychloride Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Sodium Methoxide Market
Chemicals
RDX and HMX Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Cyclopentylamine Market
Chemicals
Paint Stripper Market
Chemicals
Pyrogallol Market
Chemicals
Potassium Alum Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Fungicide Active Ingredients Market