
 Europe Tertiary Amines Market | 2026-2036
Europe Tertiary Amines Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tertiary Amines Market Insights
Personal care formulators and pharmaceutical intermediaries is bifurcating demand between commodity surfactant buyers and specialty catalyst purchasers. BASF SE leverages its Ludwigshafen integrated site to sustain captive dimethyl amine supply for downstream quaternary production. Eastman Chemical Company anchors its European position through specialized corrosion inhibitor grades serving North Sea oilfield chemical distributors. Arkema SA differentiates via focused R&D on low-VOC amine architectures for waterborne coatings.
Tertiary amines are nitrogen-bearing organic compounds with three alkyl substituents bonded to a central nitrogen atom, typically manufactured through reductive amination or alkylation of primary/secondary amines using methanol or ethanol feedstocks over metal oxide catalysts at elevated pressure. These compounds function primarily as chemical intermediates for quaternary ammonium salts, polyurethane catalysts, and pH-responsive surfactant systems. Dimethyl amine derivatives dominate volume flows into agricultural chemical formulations where glyphosate adjuvant demand remains structurally entrenched. Surfactant applications represent the fastest-expanding margin pool as personal care brands reformulate around sulfate-free cleansing systems requiring amphoteric co-surfactants. Trimethyl amine grades in corrosion inhibitor applications command premium pricing tied to offshore platform maintenance cycles in the Norwegian Continental Shelf.
REACH registration requirements enforced by ECHA mandate comprehensive toxicity dossiers for all imported and manufactured tertiary amine volumes above one tonne annually, elevating compliance costs for non-integrated distributors. The EU Green Deal's chemical sustainability targets and F-Gas Regulation phase-down schedules are indirectly redirecting investment toward amine-based absorption systems for carbon capture and industrial refrigeration. Germany's Federal Environment Agency and France's ANSES coordinate divergent hazard classification protocols that fragment product approval timelines across contiguous markets. Stakeholders must monitor the evolving interface between CBAM carbon border adjustments and upstream ammonia feedstock sourcing from North African producers.
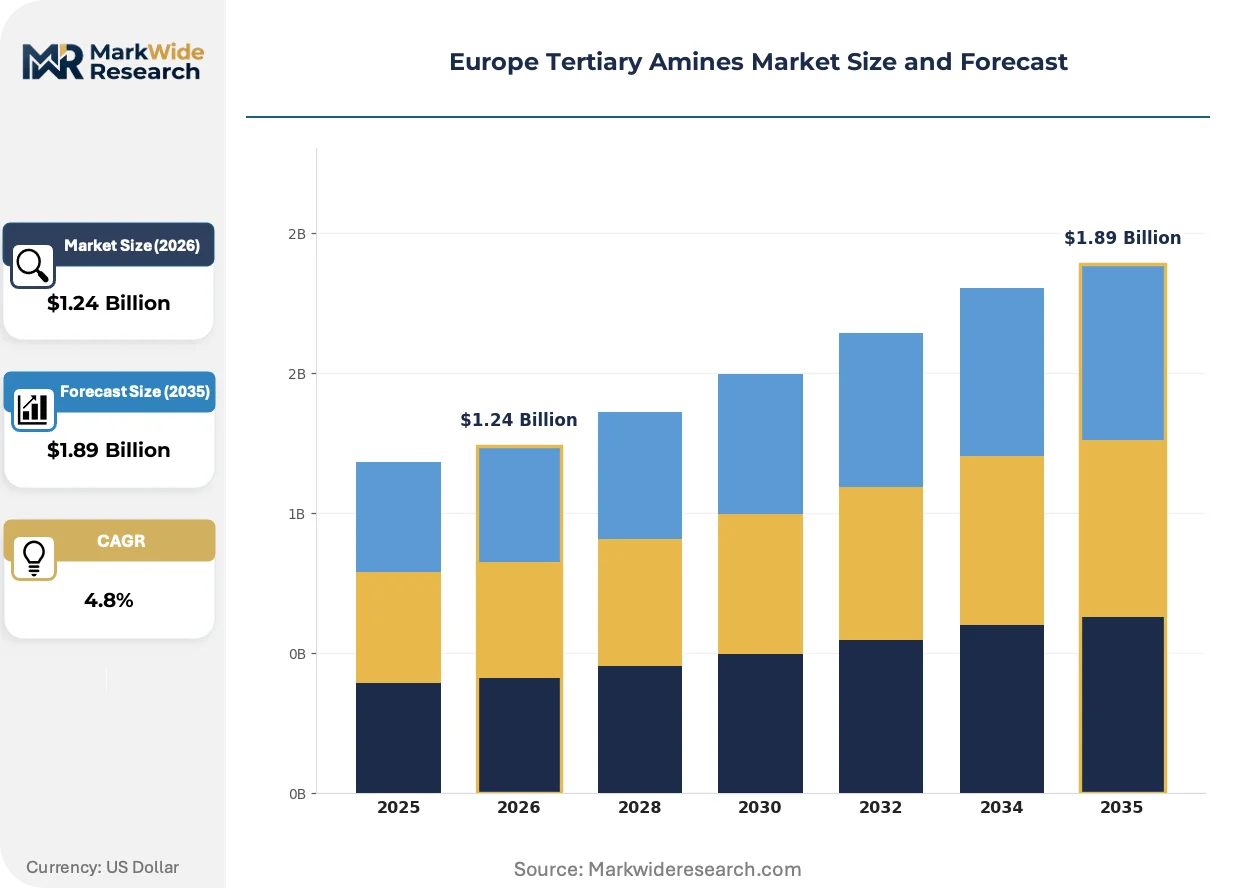
Market Dynamics
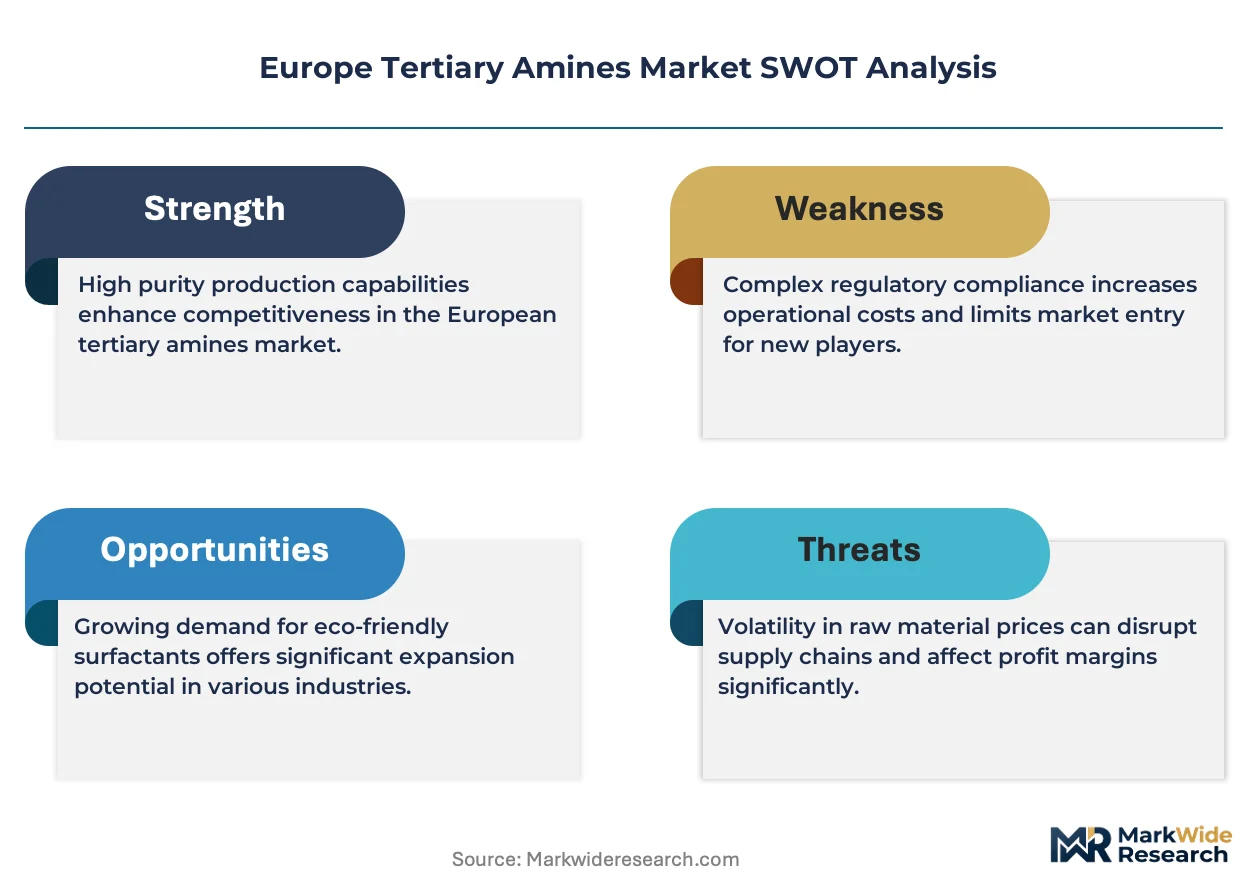
REACH compliance costs and the EU Green Deal's chemical sustainability mandates are redirecting formulation strategies toward bio-based feedstocks across the Rhine-Ruhr chemical corridor.
Growth Catalysts
- Water treatment expansion:Germany and France are expanding procurement of quaternary ammonium precursors for municipal and industrial water treatment facilities.
- Carbon capture absorption systems:The EU F-Gas Regulation phase-down schedules are redirecting investment toward amine-based absorption systems for industrial refrigeration and carbon capture applications.
- Sulfate-free personal care reformulation:Personal care brands across the region are reformulating cleansing systems requiring amphoteric co-surfactants derived from tertiary amine intermediates.
Market Restraints
- Feedstock cost volatility:Ammonia feedstock sourcing from North African producers faces carbon border adjustment exposure under CBAM implementation.
- Regulatory fragmentation:Germany's Federal Environment Agency and France's ANSES coordinate divergent hazard classification protocols that fragment product approval timelines.
- REACH compliance burden:ECHA mandates comprehensive toxicity dossiers for all volumes above one tonne annually, elevating costs for non-integrated distributors.
Strategic Opportunities
- Norwegian offshore platform maintenance:Trimethyl amine grades in corrosion inhibitor applications command premium pricing tied to maintenance cycles in the Norwegian Continental Shelf.
- Bio-based feedstock transition:The EU Green Deal's chemical sustainability targets create white space for renewable methanol and ethanol feedstock integration.
- Integrated surfactant production:Germany's Rhine-Ruhr chemical corridor offers captive dimethyl amine supply advantages for downstream quaternary production.
Industry Challenges
- Technical talent scarcity:Formulation chemistry expertise for low-VOC amine architectures remains concentrated among legacy surfactant producers.
- Legacy equipment retrofit costs:Waterborne coatings manufacturers face capital intensity in transitioning from solvent-based to amine-catalyzed systems.
- Cross-border certification delays:Divergent national implementations of REACH create timeline friction for multi-country product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tertiary Amines Market |
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimethyl Amines, Trimethyl Amines, Ethyl Dimethyl Amines, Other Amines End Use Industry: Pharmaceuticals, Agricultural Chemicals, Personal Care Products, Textile Industry Application: Solvents, Catalysts, Surfactants, Corrosion Inhibitors Form: Liquid, Solid, Powder, Concentrate |
| Companies Covered | BASF SE, Eastman Chemical Company, Arkema SA, Kao Corporation, Solvay SA, Dow Chemical, AkzoNobel, Clariant, Nouryon, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tertiary Amines Market Trends and Innovations
Formulation chemistry across Europe is pivoting toward low-emission architectures as regulatory pressure compounds end-user sustainability requirements.
Continuous flow reactor technology for reductive amination is miniaturizing production footprints while maintaining throughput. Specialty chemical producers in the Netherlands and Belgium are adopting these systems to reduce solvent waste and energy intensity. The technology is miniaturizing capital requirements for mid-scale quaternary ammonium salt manufacturers, compressing the traditional scale advantages of integrated petrochemical sites.
The EU F-Gas Regulation and its phase-down schedules are forcing refrigerant gas formulators toward amine-based absorption alternatives. Industrial refrigeration OEMs are redesigning system architectures to accommodate ammonia-amine working pairs. Cold chain logistics operators in Germany and Poland are piloting these retrofits ahead of 2030 phase-down deadlines.
Personal care procurement departments are consolidating supplier panels around REACH-registered tertiary amine sources with verified bio-based content claims. Indie beauty brands are bypassing traditional chemical distributors to contract directly with Ludwigshafen and Antwerp-based producers. This concentration is most visible in German and French sulfate-free shampoo and body wash launches.
Europe Tertiary Amines Market Segmentation
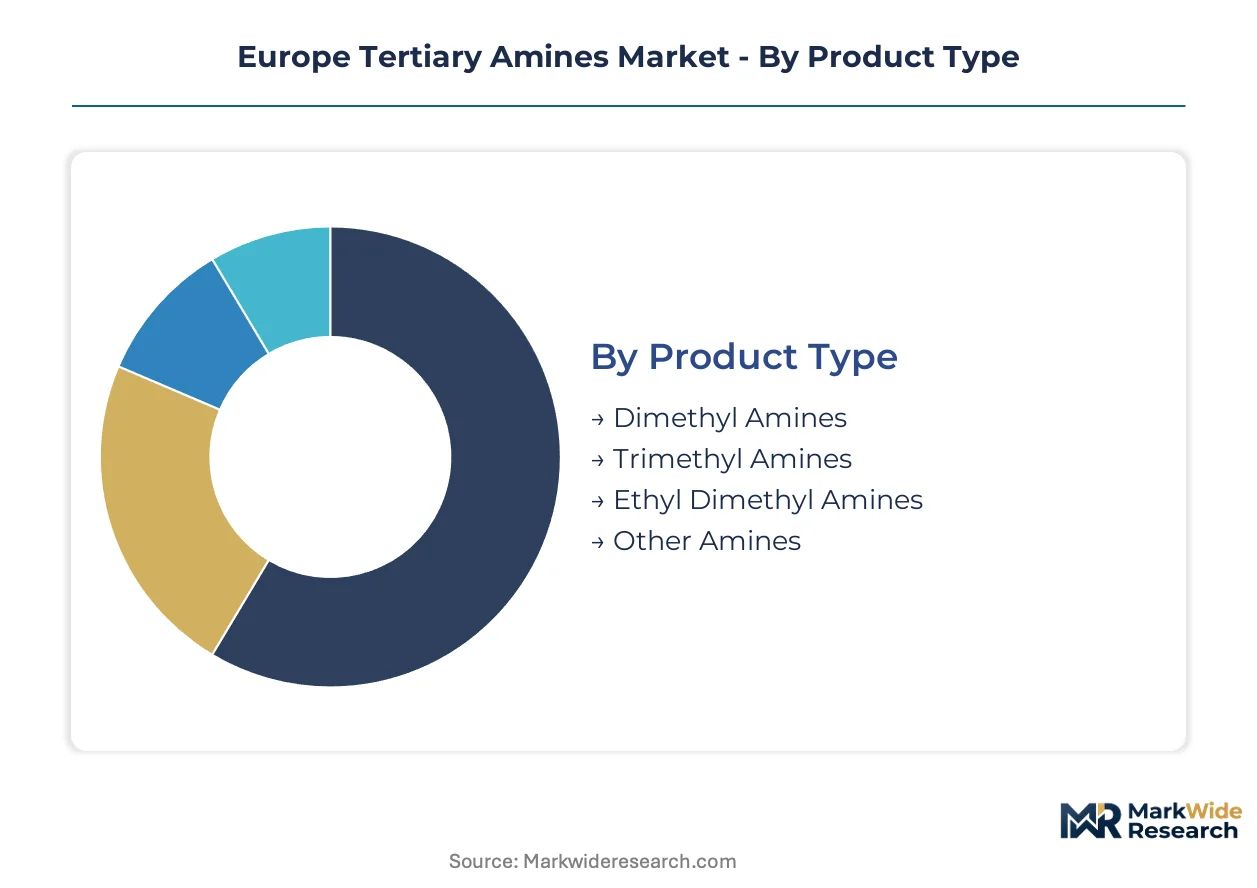
Segmentation in the Europe Tertiary Amines Market reveals how substitution pressures from bio-based alternatives and regulatory constraints reshape competitive priorities across product grades and end-use applications. Understanding these fault lines allows suppliers to align capacity investments with the most defensible demand pockets.
Product Type:
Substitution pressure from renewable feedstock alternatives weighs most heavily on commodity-grade amines with established petrochemical supply chains, while specialty derivatives retain structural insulation.
- Dimethyl Amines:These methyl-substituted intermediates serve as the primary feedstock for quaternary ammonium salt production in German water treatment facilities. Demand concentrates in the Rhine-Ruhr corridor where BASF's Ludwigshafen complex maintains captive supply for downstream surfactant manufacturers facing REACH registration deadlines.
- Trimethyl Amines:Volatile low-molecular-weight compounds command premium pricing in Norwegian offshore corrosion inhibitor formulations. Norwegian Continental Shelf maintenance cycles drive procurement timing, with North Sea oilfield chemical distributors stocking ahead of platform turnaround schedules.
- Ethyl Dimethyl Amines:Hybrid alkyl structures find niche application in agricultural adjuvant systems for glyphosate formulations across France's cereal-growing regions.
- Other Amines:Longer-chain and cyclic tertiary amines address specialized pharmaceutical intermediate requirements in Swiss and Belgian custom synthesis operations.
Dimethyl amines retain volume leadership across European production statistics; trimethyl amines hold the steepest expansion curve tied to offshore energy maintenance intensity.
End Use Industry:
Customer procurement sophistication varies sharply, with pharmaceutical buyers demanding batch-level traceability while agricultural formulators prioritize delivered cost above certification depth.
- Pharmaceuticals:High-purity grades for active pharmaceutical ingredient synthesis require EMA-compliant manufacturing records and dedicated production lines. Swissmedic-registered facilities in Basel and Swiss border regions anchor regional supply for contract development organizations.
- Agricultural Chemicals:Glyphosate adjuvant demand from French and German crop protection distributors consumes bulk dimethyl amine volumes. ANSES hazard classification protocols delay new product introductions, entrenching incumbent supplier relationships.
- Personal Care Products:Sulfate-free shampoo and body wash reformulations in Germany and France drive amphoteric co-surfactant procurement. Indie beauty brands now contract directly with Antwerp and Ludwigshafen producers, bypassing traditional chemical distributors.
- Textile Industry:Fabric softener quaternary precursors face demand erosion as EU Green Deal targets accelerate bio-based surfactant substitution in Scandinavian markets.
Agricultural chemicals consume the greatest raw material tonnage; personal care applications are gaining share fastest amid formulation chemistry transitions.
Application:
Performance requirements stratify sharply between commodity solvent functions and precision catalyst roles where specification tolerance tightens.
- Solvents:Polar aprotic dissolution media for pharmaceutical and agrochemical synthesis face regulatory scrutiny under ECHA SVHC candidate list reviews. German chemical processors are qualifying lower-toxicity alternatives ahead of potential restriction proposals.
- Catalysts:Polyurethane foam production relies on tertiary amine gel and blow catalysts with precise kinetic profiles. Automotive seating and insulation manufacturers in Czech and Polish industrial zones specify amine grades by reaction time windows.
- Surfactants:Quaternary ammonium salt precursors for personal care and household cleaning command margin premiums tied to bio-based content verification. REACH-registered sources with mass balance certification capture procurement panel consolidation.
- Corrosion Inhibitors:Film-forming amine derivatives protect North Sea infrastructure against CO2 and H2S degradation. Norwegian platform operators specify trimethyl amine grades by salt spray test performance in North Atlantic conditions.
Surfactant applications lead value generation; corrosion inhibitors deliver the highest unit margins despite smaller absolute volumes.
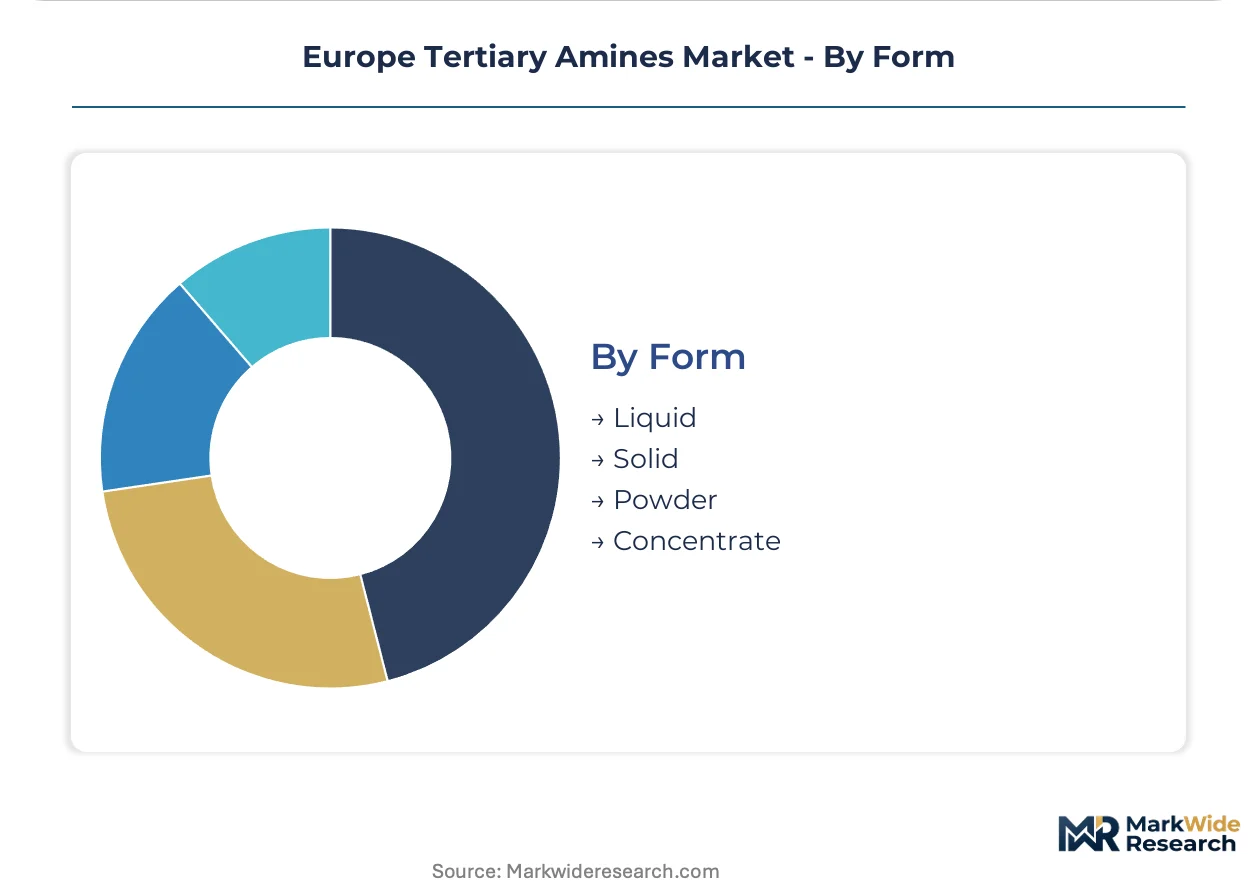
Form:
Physical state selection determines logistics economics and formulation compatibility, with liquid dominance challenged by powder advantages in concentrated detergent systems.
- Liquid:Standard bulk delivery format for integrated chemical processors with dedicated amine handling infrastructure. Rhine barge and pipeline networks from Rotterdam to Ludwigshafen minimize liquid transfer costs for high-volume consumers.
- Solid:Flaked or prilled grades reduce transportation costs for inland agricultural chemical blenders in Eastern European markets lacking liquid terminal access.
- Powder:Micronized particles enable rapid dissolution in powder detergent manufacturing. Polish and Hungarian household cleaning producers specify powder amines for sulfate-free laundry formulations.
- Concentrate:High-active-content solutions reduce water shipping weight for distant personal care contract manufacturers. French indie beauty brands source concentrates to minimize inventory holding costs.
Liquid forms dominate tonnage movements; concentrate formats are expanding most quickly as brands optimize supply chain carbon intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam-to-Ludwigshafen barge corridors anchor intra-European tertiary amine flows, with German chemical processors exporting quaternary ammonium precursors to French water treatment distributors and Norwegian offshore chemical suppliers.
Germany
Rhine-Ruhr integrated chemical sites consume captive dimethyl amine volumes for downstream surfactant production. ECHA REACH registration deadlines compress procurement timelines for non-integrated distributors. BASF's Ludwigshafen complex sustains backward integration into ammonia feedstocks, insulating margin structures from CBAM exposure on North African imports.
France
ANSES hazard classification protocols delay new agricultural adjuvant introductions, entrenching incumbent supplier relationships in glyphosate formulation channels. The EU Green Deal's chemical sustainability targets accelerate bio-based surfactant substitution in fabric softener applications. Paris Basin water treatment authorities expand quaternary ammonium procurement for municipal disinfection systems.
Netherlands
Antwerp-Rotterdam chemical terminals handle bulk liquid amine transshipments to German and French processors. Continuous flow reactor adoption miniaturizes production footprints for mid-scale quaternary manufacturers. Dutch specialty chemical producers reduce solvent waste through reductive amination technology upgrades.
Norway
North Sea platform maintenance cycles drive trimethyl amine demand for corrosion inhibitor formulations. Norwegian Continental Shelf operators specify amine grades by salt spray performance in North Atlantic conditions. Statoil-anchored supply chains concentrate procurement timing around scheduled turnaround windows.
Belgium
Antwerp-based surfactant producers serve French indie beauty brands with REACH-registered, bio-based certified amine supplies. F-Gas Regulation phase-down schedules redirect industrial refrigeration OEMs toward amine-based absorption system retrofits. Belgian custom synthesis operations source longer-chain tertiary amines for pharmaceutical intermediate production.
Europe Tertiary Amines Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with captive ammonia-to-amine supply chains, creating tiered competition between Rhine-Ruhr anchored producers and specialized corrosion inhibitor formulators. Three archetypes dominate: integrated chemical majors with backward feedstock control, specialty surfactant houses with formulation chemistry expertise, and offshore-focused chemical distributors with Norwegian market access. Competitive moves concentrate on REACH registration portfolio expansion and bio-based feedstock certification rather than capacity addition.
Among integrated chemical majors, BASF SE exemplifies the captive supply archetype through its Ludwigshafen complex positioning. Eastman Chemical Company occupies a specialty-grade position serving North Sea oilfield chemical channels. Arkema SA represents the R&D-focused tier with low-VOC amine architecture development. These three anchors illustrate how geographic integration, application specialization, and technical differentiation stratify competitive positioning across European procurement panels.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Arkema SA |
| Kao Corporation |
| Solvay SA |
| Dow Chemical |
| AkzoNobel |
| Clariant |
| Nouryon |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Rhine-Ruhr integrated producers and French water treatment distributors lock in both supply access and price visibility, insulating buyers from ammonia feedstock volatility while exposing non-integrated distributors to CBAM-adjusted spot market swings. These arrangements concentrate procurement power among Ludwigshafen-anchored suppliers with backward integration into North African ammonia sourcing.
Pricing Analysis
Current-generation continuous flow reactor outputs command margin premiums over legacy batch-processed grades, while next-generation bio-based feedstock amines remain supply-constrained and price-elevated. Three-tier pricing structure across REACH-registered premium, standard commodity, and unregistered economy levels stratifies by certification depth and traceability documentation. Cost compression in standard commodity dimethyl amine grades is intensifying because agricultural chemical blenders prioritize delivered cost above regulatory compliance investment. Agricultural formulators exhibit the highest price sensitivity, while Norwegian offshore platform operators purchasing corrosion inhibitor grades demonstrate minimal elasticity tied to salt spray performance specifications.
Supply Chain Analysis
Port congestion at Rotterdam-Antwerp terminals elevates inbound logistics costs for methanol feedstock arriving from Middle Eastern producers, compressing margins for Belgian and Dutch mid-scale manufacturers lacking pipeline access. Supply concentration centers on Germany, the Netherlands, and Belgium, with German integrated sites consuming captive ammonia while Benelux processors draw from transshipment terminals. The supply chain rests on methanol, ethanol, and ammonia feedstocks, with metal oxide catalyst supply anchored to German and Belgian specialty chemical distributors. Single-source vulnerability in North African ammonia imports creates exposure to carbon border adjustment implementation. Distribution runs through Rhine barge networks and Antwerp-Rotterdam liquid terminals to downstream surfactant and water treatment processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as REACH registration databases function as interoperability infrastructure, locking formulators into approved supplier panels and creating switching costs that favor incumbent integrated producers with comprehensive dossier portfolios.
For Market Incumbents: Fortify market position by accelerating bio-based feedstock certification to capture EU Green Deal procurement preferences, and deepen backward integration into ammonia sourcing to neutralize CBAM exposure on North African imports. The priority lever rests on defending against specialty surfactant houses with formulation chemistry expertise by expanding REACH-registered product portfolios ahead of competitor dossier submissions. For New Entrants and Emerging Players: Differentiate on continuous flow reactor technology to serve mid-scale quaternary ammonium salt manufacturers seeking miniaturized production footprints with reduced solvent waste. Target Polish and Hungarian powder detergent producers lacking liquid terminal access, where solid and concentrate format supply gaps create penetrable white space. The optimal go-to-market angle involves direct contracting with indie beauty brands bypassing traditional chemical distributors, mirroring the procurement pattern established in German and French sulfate-free personal care launches. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chemical majors with captive feedstock control and comprehensive REACH registration portfolios. Long-term viability over the next decade hinges on regulatory compliance depth rather than capacity scale, positioning backward-integrated Rhine-Ruhr assets as durable value anchors. Acquisition targets should prioritize specialty surfactant houses with formulation chemistry expertise and verified bio-based content claims. The signal to watch is ECHA restriction proposal timelines for solvent-grade amines under SVHC candidate list review, which would accelerate substitution demand toward compliant specialty grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Feedstock | Insulates margin structures from CBAM exposure on North African imports under EU carbon border adjustments. |
| REACH Registration Portfolio Expansion | Creates switching costs that lock personal care formulators into approved supplier panels ahead of competitor dossiers. |
| Bio-based Feedstock Certification | Captures procurement panel consolidation around verified mass balance claims under EU Green Deal mandates. |
| Continuous Flow Reactor Adoption | Reduces solvent waste and energy intensity for Dutch and Belgian mid-scale quaternary manufacturers. |
| Direct-to-Brand Distribution Model | Bypasses traditional chemical distributors to serve French and German indie beauty brands with concentrate formats. |
Research Methodology
A spread of perspectives from plant managers at integrated chemical sites, procurement leads at downstream surfactant manufacturers, distribution channel partners in the Rhine-Ruhr corridor, and technical R&D directors specializing in low-VOC amine architectures converged on the working assumptions. These primary insights combined with secondary validation from ECHA registration databases, Cefic industry statistics, customs and trade flow data, and SEC filings from disclosed chemical producers. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic indicators to establish analytical coherence.
Segmentation dimensions modeled include product type tier, end-use industry vertical, physical form factor, and regional production hub concentration across the analysis window. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory inflection points and feedstock cost trajectories. Industry-specific forecast inputs incorporated REACH registration deadline impacts on procurement timing and F-Gas Regulation phase-down schedules driving amine-based absorption system adoption.
Decision-makers should treat outputs as directional under stable regulatory implementation timelines and contained feedstock cost volatility; material deviation in CBAM enforcement intensity or North African supply disruption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Trichlorosilane Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Global Thiophene Market
Chemicals
Global Organobromine Market
Chemicals
Global Bleaching Agents Market
Chemicals
North America Tartaric Acid Market
Chemicals
Wood Preservation Chemicals Market
Chemicals
Egypt Acidulants Market
Chemicals
HATU Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
United States Construction Chemicals Market
Chemicals
Superplasticizer Market
Chemicals
Detergent Alcohols Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
China Amines Market
Chemicals
Pyrimidine Market