
 Biobased Degreaser Market | 2026-2036
Biobased Degreaser Market Size, Share, and Industry Trends Forecast 2026-2036
Biobased Degreaser Market Outlook
The capital-intensity divergence between fermentation-derived surfactant producers and conventional blenders is rotating competitive advantage toward upstream bio-refinery operators. BASF SE leverages its integrated biotechnology platform to secure feedstock cost stability across European manufacturing sites. Ecolab Inc. sustains service-led distribution density in North American food processing plants. Soy Technologies LLC anchors its position through proprietary soy methyl ester chemistry developed for military specification cleaning.
Biobased degreasers are formulated cleaning agents derived from renewable feedstocks such as vegetable oils, corn-derived alcohols, or microbial surfactants, typically exhibiting flash points above 60°C and biodegradable profiles exceeding 60% in OECD 301 tests, designed to dissolve hydrocarbon soils without chlorinated or aromatic petroleum fractions. Aqueous formulations dominate unit volume in food processing sanitation where rinse-water discharge regulations restrict solvent content, while solvent-based variants command premium positioning in aerospace maintenance applications requiring rapid evaporation and non-corrosive residue profiles. Metal degreasing as an application category generates the densest margin pool due to precision manufacturing tolerances and contract-specified performance validation protocols.
The EPA regulates volatile organic compound emissions under 40 CFR 59, while the EU REACH framework restricts hazardous substance authorization in industrial cleaners, and the USDA BioPreferred program establishes federal procurement preference thresholds that directly shape North American demand validation. Stakeholders must monitor regulatory divergence between California's Safer Consumer Products regulations and emerging state-level biobased procurement mandates to anticipate formulation reformulation cycles and certification investment requirements.
Market Dynamics
Fermentation-derived surfactant production is concentrating capital flows toward integrated bio-refinery operators, compressing margins for conventional blenders dependent on commodity oleochemical feedstocks. EPA VOC enforcement under 40 CFR 59 and EU REACH authorization restrictions are forcing simultaneous reformulation across multiple regulatory jurisdictions.
Growth Catalysts
- REACH Authorization Restrictions:The EU framework's sunset clause for hazardous substance use in industrial cleaners mandates biobased substitution in German metal fabrication and precision engineering clusters.
- Soy Methyl Ester Chemistry:Military specification cleaning requirements for non-flammable, low-toxicity degreasers in aerospace maintenance facilities are validating plant-derived solvent performance under MIL-PRF-680 Type II protocols.
- Food Processing Sanitation:Rinse-water discharge regulations in USDA-inspected facilities restrict petroleum solvent content, creating captive demand for aqueous biobased formulations with OECD 301 biodegradability certification.
Market Restraints
- Feedstock Cost Volatility:Soybean oil and corn-derived alcohol prices fluctuate with agricultural commodity cycles, exposing formulation costs to weather-driven supply shocks in Midwestern US growing regions.
- Performance Validation Burden:Metal degreasing contracts require ISO 4406 cleanliness code certification and surface energy testing, extending qualification timelines for biobased alternatives against established petroleum benchmarks.
- Flash Point Limitations:Aqueous formulations with elevated water content fail to meet aerospace rapid-evaporation requirements, capping addressable share in maintenance-repair-operations segments.
Strategic Opportunities
- USDA BioPreferred Federal Procurement:The program's mandatory federal purchasing thresholds create validated demand anchors for certified biobased content in defense and civilian agency maintenance operations.
- California Safer Consumer Products:The state's regulatory divergence from federal standards is generating first-mover advantage for formulators with pre-approved Design for Environment alternatives.
- Microbial Surfactant Platforms:Convergence of synthetic biology with continuous fermentation is enabling rhamnolipid and sophorolipid production at cost parity with petrochemical surfactants.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Industrial microbiology and downstream processing expertise concentrates in pharmaceutical and food biotechnology sectors, constraining scale-up velocity for dedicated degreaser surfactant production.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA Safer Choice, EU Ecolabel, and USDA BioPreferred verification requires 18-24 month documentation cycles before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobased Degreaser Market |
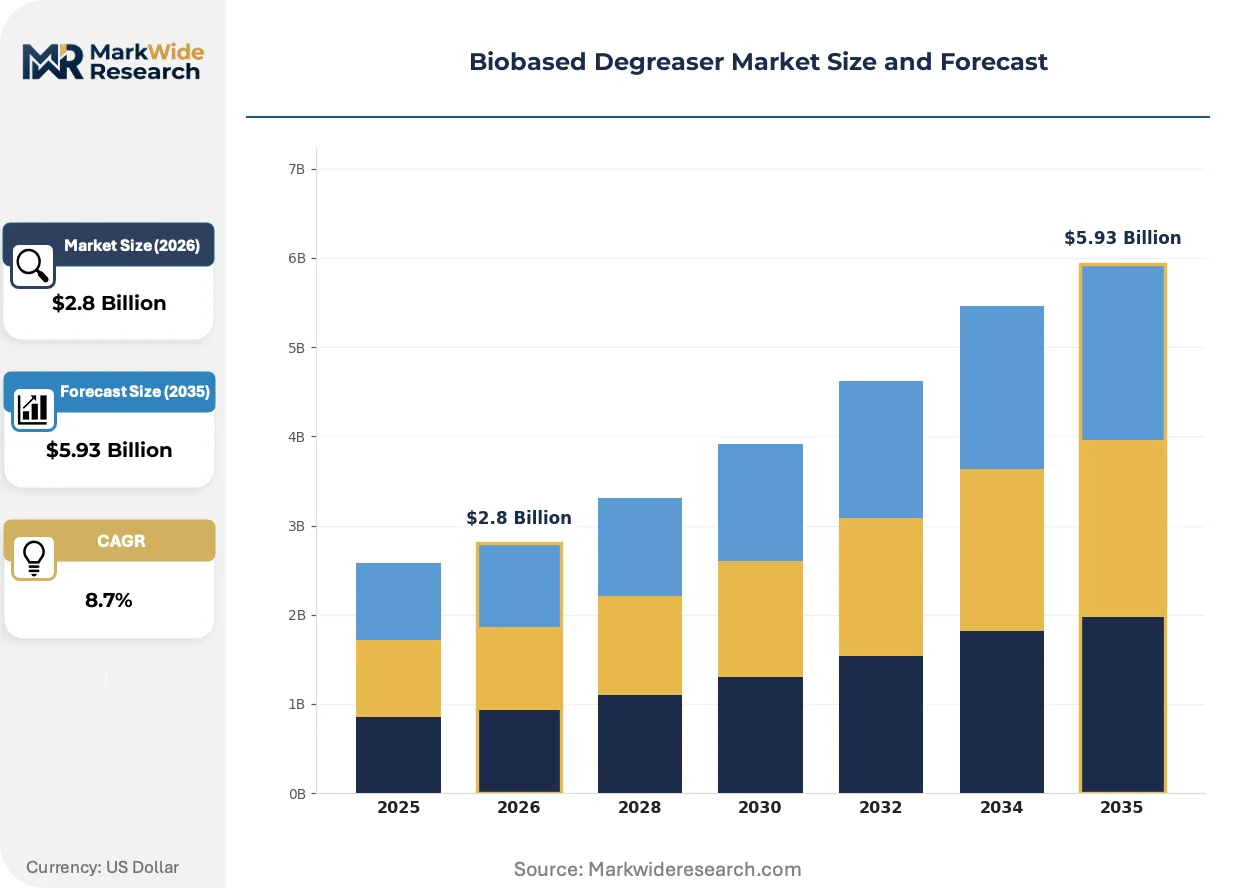
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous, Solvent-Based, Emulsifiable, Biodegradable End User: Manufacturing, Automotive, Food Processing, Aerospace Application: Surface Cleaning, Metal Degreasing, Equipment Maintenance, Oil Removal Packaging Type: Bottles, Drums, Bulk Containers, Spray Cans |
| Companies Covered | BASF SE, Ecolab Inc., Henkel AG & Co. KGaA, Dow Chemical Company, Carroll Company, Soy Technologies LLC, Renewable Lubricants Inc., Huntsman Corporation, Cortec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobased Degreaser Market Strategic Shifts
Formulation chemistry is actively bifurcating between aqueous systems optimized for food processing discharge compliance and high-performance solvent blends engineered for aerospace maintenance specifications. This technical divergence is reshaping R&D allocation and manufacturing asset configuration across the supplier base.
Rhamnolipid biosurfactant production is bifurcating the surfactant supply structure. Pseudomonas aeruginosa fermentation platforms achieve 90% purity grades suitable for precision metal cleaning. German automotive suppliers are qualifying these materials for transmission component degreasing. The technology is bifurcating competitive advantage toward integrated fermentation operators with captive glycerol feedstock access.
EPA enforcement discretion under 40 CFR 59 is tightening volatile organic compound limits for consumer and industrial degreaser categories. The regulatory pressure is accelerating reformulation investments among private-label blenders dependent on mineral spirits and aromatic solvents. Aqueous biobased alternatives with flash points above 60°C are capturing shelf space in retail automotive channels previously dominated by petroleum products.
Contract cleaning service providers are unbundling chemical supply from labor provision in food processing sanitation agreements. Facilities managers are assuming direct procurement responsibility for biobased degreaser formulations while outsourcing application labor to specialized service firms. This disaggregation is most visible in Midwestern US meat and dairy processing clusters where USDA inspection frequency creates demand for validated, traceable cleaning chemistry.
Biobased Degreaser Market Segmentation
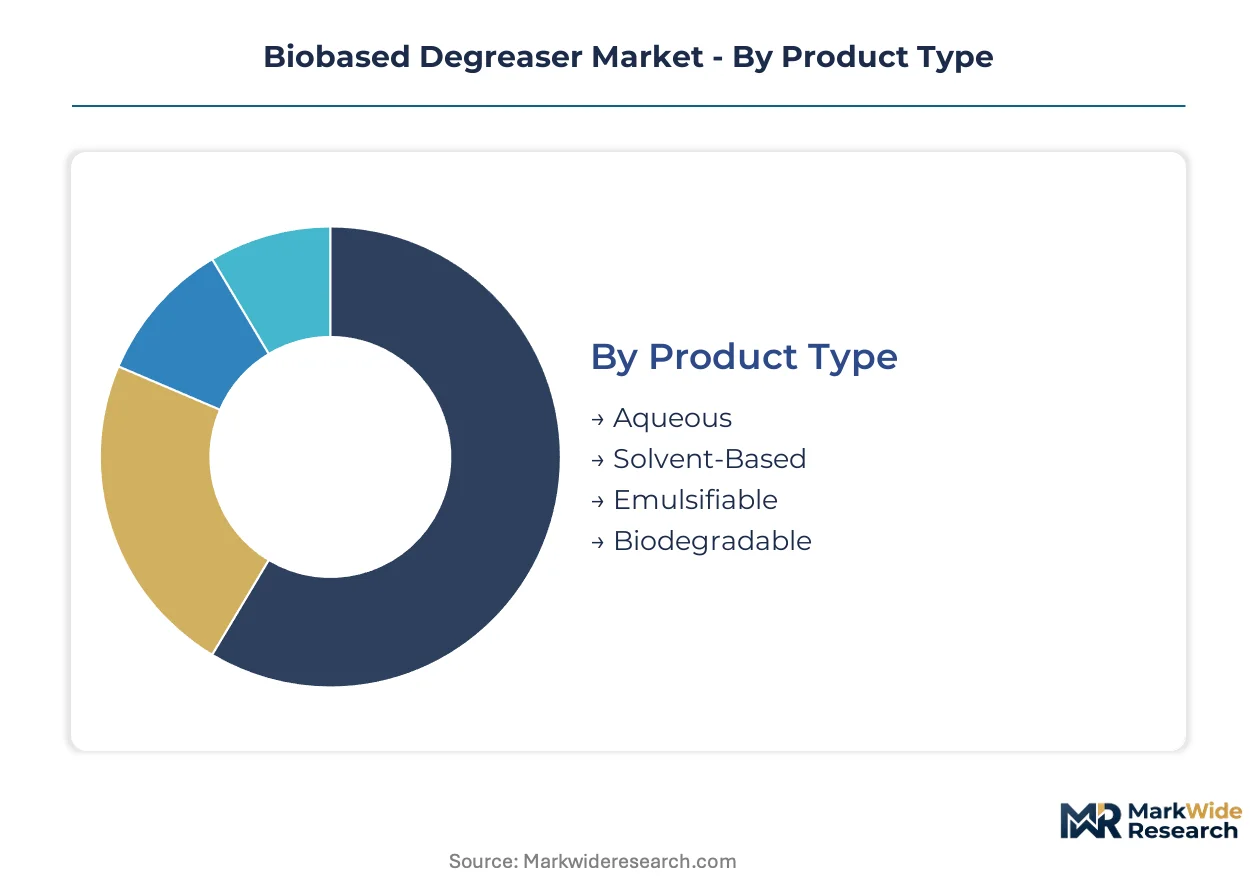
Biobased degreaser segmentation reveals how formulation chemistry, end-use performance requirements, and regulatory compliance intersect to create distinct competitive arenas. Each dimension carries different margin structures and certification burdens that reshape supplier positioning.
Product Type:
Aqueous formulations face the most intense substitution pressure from conventional petroleum cleaners in price-sensitive automotive channels, while solvent-based variants defend premium positioning through military specification performance.
- Aqueous:Water-based systems incorporate vegetable oil-derived surfactants and corn-based alcohols, achieving OECD 301 biodegradability certification above 60%. Food processing plants in Germany specify these formulations to meet rinse-water discharge regulations under EU REACH frameworks.
- Solvent-Based:Plant-derived esters and terpenes deliver flash points above 60°C with rapid evaporation profiles. Aerospace maintenance facilities in the United States validate these materials under MIL-PRF-680 Type II protocols for non-flammable cleaning operations.
- Emulsifiable:Concentrates designed for dilution with water reduce transport costs and storage footprint.
- Biodegradable:Formulations engineered for maximum environmental compatibility through microbial surfactant platforms.
Aqueous products anchor the volume base while solvent-based variants gain share at the steepest rate.
End User:
Cost tier differentiation separates contract-specified industrial applications from maintenance-repair-operations procurement with shorter qualification cycles.
- Manufacturing:Precision metal fabrication and electronics assembly demand ISO 4406 cleanliness code validation. German automotive transmission suppliers specify rhamnolipid-based formulations for component degreasing with surface energy testing protocols.
- Automotive:Workshop channels previously dominated by mineral spirits are converting to biobased alternatives as EPA 40 CFR 59 VOC limits tighten retail shelf requirements.
- Food Processing:USDA-inspected meat and dairy facilities mandate traceable cleaning chemistry with validated residue profiles.
- Aerospace:Military and commercial aviation maintenance requires non-corrosive residue and rapid evaporation under strict safety specifications.
Manufacturing commands the densest margin pool while automotive channels expand most quickly through regulatory displacement of petroleum products.
Application:
Volume concentration in metal degreasing reflects precision manufacturing tolerance requirements that extend qualification timelines for biobased alternatives.
- Surface Cleaning:General industrial and commercial maintenance applications with moderate soil loads and less stringent performance validation.
- Metal Degreasing:Critical for precision engineering where surface cleanliness directly impacts downstream coating adhesion and component function.
- Equipment Maintenance:Preventive and corrective maintenance operations across industrial asset bases with diverse substrate compatibility requirements.
- Oil Removal:Heavy hydrocarbon soil dissolution for manufacturing equipment and fleet vehicle cleaning with high soil loading capacity specifications.
Metal degreasing captures premium pricing while equipment maintenance applications climb the fastest through service contract unbundling trends.
Packaging Type:
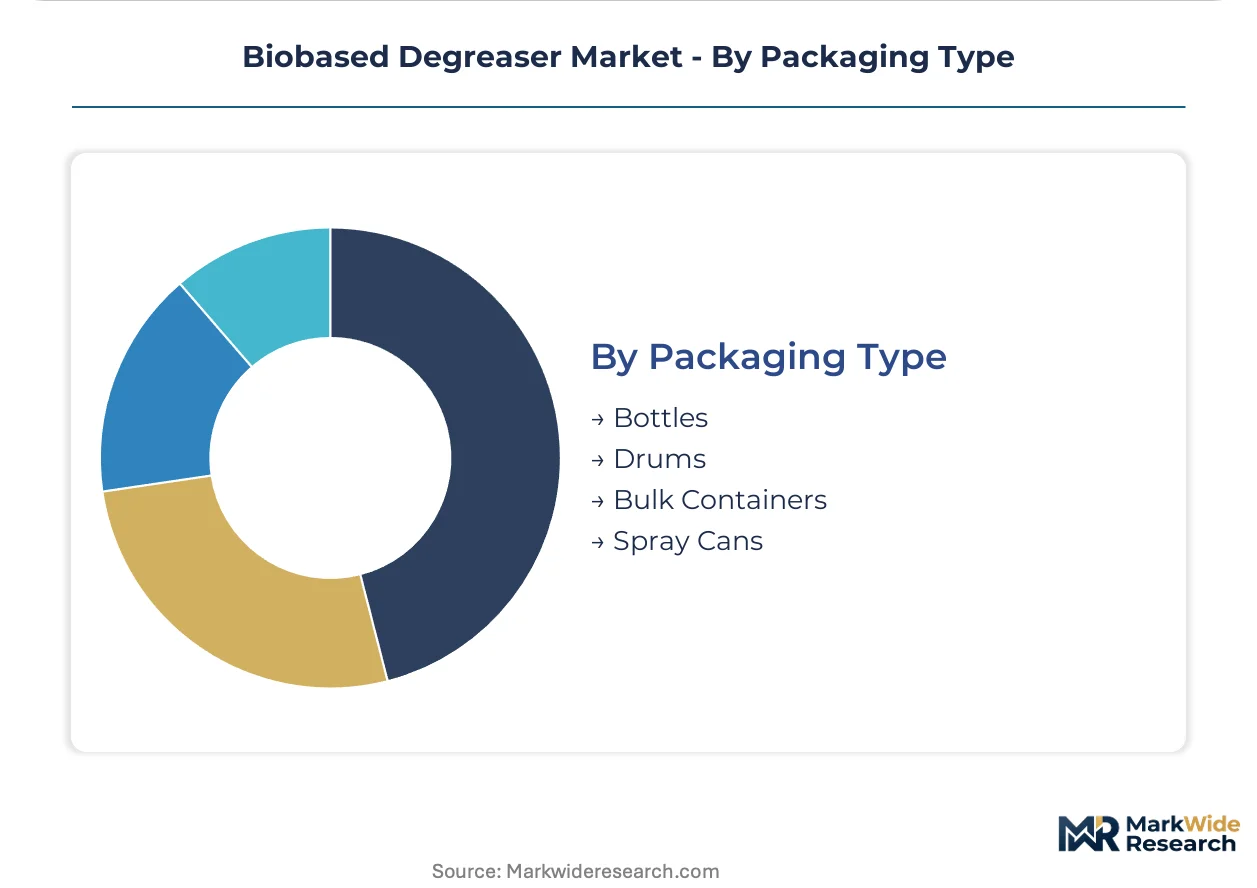
Supply chain configuration determines packaging economics, with bulk formats dominating high-volume manufacturing procurement and retail formats serving fragmented automotive channels.
- Bottles:Consumer and light commercial applications in automotive retail and small workshop settings.
- Drums:Mid-volume industrial procurement for manufacturing facilities with established chemical handling infrastructure.
- Bulk Containers:Tanker and tote deliveries for food processing plants with continuous sanitation operations and direct feed system integration.
- Spray Cans:Aerosol and pump-spray formats for precision application in aerospace maintenance and spot cleaning operations.
Drums and bulk containers anchor industrial volume while spray can formats expand most quickly through aerospace maintenance specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision engineering clusters while cost-sensitive automotive workshops in the United States compress margins through high-volume procurement contracts.
United States
Defense maintenance operations and aerospace facilities in California and Texas drive specification-grade demand. EPA 40 CFR 59 enforcement tightens volatile organic compound limits for industrial cleaners. Wichita, Kansas and Seattle, Washington aerospace clusters validate plant-derived solvents under MIL-PRF-680 Type II protocols for non-flammable cleaning.
Germany
Automotive transmission suppliers and metal fabrication workshops require ISO 4406 cleanliness certification for component degreasing. EU REACH authorization restrictions mandate biobased substitution through sunset clauses for hazardous substances. Stuttgart and Munich precision engineering clusters specify rhamnolipid-based formulations with surface energy testing protocols.
China
Electronics assembly plants and semiconductor fabrication facilities demand residue-free cleaning for downstream coating adhesion. The country's national environmental regulator tightens discharge standards for industrial wastewater containing petroleum solvents. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang provinces qualify aqueous biobased formulations for circuit board cleaning operations.
Japan
Automotive OEMs and precision machinery manufacturers prioritize low-toxicity chemistry for worker safety compliance. METI industrial standards encourage renewable feedstock adoption in process chemicals. Nagoya automotive suppliers and Osaka metalworking districts specify soy-derived esters for transmission component degreasing with biodegradability certification.
India
Food processing plants and dairy cooperatives seek traceable cleaning chemistry for USDA-equivalent export compliance. BIS standards for industrial cleaners incorporate biodegradability thresholds aligned with OECD 301 protocols. Maharashtra and Gujarat dairy clusters adopt aqueous biobased formulations to meet European export sanitation requirements.
Biobased Degreaser Market Competitive Environment
Concentration sits with integrated chemical conglomerates possessing captive biotechnology platforms and fermentation capacity. The market structure tiers between multinational formulators with regulatory certification infrastructure and specialized blenders serving contract-specified industrial niches. Three archetypes dominate: upstream bio-refinery operators controlling feedstock costs, service-integrated distributors owning food processing plant relationships, and military-specification specialists validating performance under aerospace protocols. Dominant competitive moves include backward integration into oleochemical feedstock production and geographic expansion through regional formulation licensing.
Within the integrated chemical tier, BASF SE and Dow Chemical Company exemplify multinational operators with biotechnology platforms spanning European and North American manufacturing. Ecolab Inc. occupies a position among service-integrated distributors with dense presence in food processing sanitation contracts. Soy Technologies LLC anchors the military-specification specialist archetype through proprietary chemistry developed for aerospace maintenance validation.
| Leading Market Players |
|---|
| BASF SE |
| Ecolab Inc. |
| Henkel AG & Co. KGaA |
| Dow Chemical Company |
| Carroll Company |
| Soy Technologies LLC |
| Renewable Lubricants Inc. |
| Huntsman Corporation |
| Cortec Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German automotive transmission suppliers and integrated bio-refinery operators lock in rapeseed methyl ester supply visibility while insulating formulation costs from Rotterdam vegetable oil price swings. These agreements concentrate pricing power with upstream operators possessing captive fermentation capacity.
Pricing Analysis
Configured-to-order pricing for MIL-PRF-680 Type II certified solvent blends commands spreads above standard aqueous formulations due to aerospace validation protocols and surface energy testing documentation. Three-tier pricing structure across premium, standard, and economy levels separates military-specification solvent blends from ISO 4406 certified metal degreasing concentrates and commodity automotive workshop cleaners. Cost compression in standard-grade aqueous products is intensifying because Midwestern US soybean oil feedstock volatility exposes blenders without backward integration. Automotive workshop channels exhibit highest price sensitivity due to high-volume procurement contracts, while aerospace maintenance facilities accept premium positioning for validated non-flammable chemistry.
Supply Chain Analysis
Strait of Malacca transit underwrites palm kernel oil and coconut-derived feedstock flows to Southeast Asian surfactant production hubs, creating logistics vulnerability for European formulators dependent on Asian oleochemical imports. Supply concentrates in Germany, the United States, and Malaysia for fermentation-derived surfactants, rapeseed methyl esters, and palm-derived alcohols respectively. Raw material dependencies rest on soybean oil, corn-derived alcohols, and microbial glycerol feedstocks. Single-source vulnerability concentrates in Pseudomonas aeruginosa strain banks for rhamnolipid production. Distribution runs through service-integrated chemical distributors in food processing sanitation and direct mill supply agreements in precision metal fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where formulation supply contracts bundled with ISO 4406 cleanliness validation and surface energy testing protocols expand faster than standalone chemical sales. The recurring-revenue layer from performance certification and technical service outpaces product margin growth.
For Market Incumbents: Consolidate backward integration into oleochemical feedstock production to neutralize soybean oil price volatility exposure from Midwestern US growing regions. Deepen capacity presence in Stuttgart and Munich precision engineering clusters where REACH authorization sunset clauses are accelerating biobased substitution timelines. Lock in exclusive service contracts with USDA-inspected meat and dairy facilities before contract unbundling trends mature. For New Entrants and Emerging Players: Anchor in Yangtze River Delta electronics assembly plants where China's national environmental regulator is tightening petroleum solvent discharge standards for circuit board cleaning operations. Target aqueous biobased formulations for semiconductor fabrication facilities seeking residue-free chemistry for downstream coating adhesion. Pursue direct procurement relationships with facilities managers assuming chemical supply responsibility from unbundled sanitation service contracts. For Investors and Strategic Acquirers: Capital is best deployed toward integrated fermentation operators with captive glycerol feedstock access and established rhamnolipid purity grades above 90%. Long-term viability hinges on synthetic biology convergence enabling sophorolipid production at cost parity with petrochemical surfactants. Watch for EPA enforcement discretion tightening under 40 CFR 59 as the inflection indicator accelerating petroleum degreaser displacement in retail automotive channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstock | Captive rapeseed and soybean oil supply insulates BASF from Rotterdam price volatility. |
| USDA BioPreferred Certification Investment | Federal procurement thresholds validate demand anchors for defense maintenance operations. |
| Fermentation Capacity Expansion | Rhamnolipid scale-up captures German automotive transmission supplier qualification timelines. |
| Service Contract Unbundling Response | Direct procurement relationships with facilities managers bypass traditional distributor channels. |
| California Safer Consumer Products Pre-Approval | Design for Environment alternatives secure first-mover advantage in state-level regulatory divergence. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA 40 CFR 59 enforcement records, EU REACH authorization sunset clause documentation, USDA BioPreferred procurement databases, and OECD 301 biodegradability certification registries. Plant managers at German metal fabrication facilities, procurement leads at North American food processing OEMs, distribution channel partners in Midwestern dairy clusters, and technical R&D directors at integrated bio-refinery operators provided operational validation. Bottom-up formulation demand modeling triangulates against top-down industrial cleaner consumption estimates.
Segmentation dimensions modeled span aqueous versus solvent-based formulation chemistry, manufacturing versus automotive versus food processing versus aerospace end-use verticals, metal degreasing versus surface cleaning versus equipment maintenance application categories, and drums versus bulk containers versus spray can packaging formats. CAGRs derive from regression analysis of historical substitution rates and regulatory enforcement intensity across the projection horizon. Feedstock cost curves for soybean oil and corn-derived alcohols inform formulation pricing elasticity assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA VOC enforcement and EU REACH authorization restriction timelines; material deviation in regulatory stringency would warrant model refresh. Practitioners should keep alternative scenarios live as agricultural commodity price volatility and bioprocess engineering talent scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Dynamite Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Defatting Systems Market