
 Extended Text Labels Market | 2026-2036
Extended Text Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Extended Text Labels Market Analysis
Capital-intensity divergence between flexographic press operators and digital print entrants is rotating competitive dynamics across the Extended Text Labels landscape. Avery Dennison Corporation leverages its polymer science capabilities to sustain premium positions in pharmaceutical-grade polyester constructions. Schreiner Group GmbH & Co. KG anchors European demand through specialized booklet-label systems for clinical trial materials. CCL Industries Inc. competes via geographic breadth, operating dedicated extended-text facilities across multiple North American and European production zones.
Extended text labels are pressure-sensitive or adhesive-backed constructions incorporating fold-out panels, booklet layers, or extended-content formats that expand printable surface area beyond standard label dimensions, typically achieving 3-to-10-fold information density increases through multi-ply lamination or concertina folding. These constructions serve regulatory compliance, multilingual instruction, and traceability requirements in packaging environments where primary container space remains constrained. Polyester substrates dominate pharmaceutical applications due to chemical resistance and dimensional stability under autoclave and cold-chain conditions, while vinyl alternatives lead in durable goods labeling where outdoor exposure and mechanical abrasion dominate. Digital print technology captures the fastest expansion trajectory, displacing conventional gravure for short-run serialized pharmaceutical batches where variable data and regional language customization reduce economic order quantities.
FDA's 21 CFR Part 211 labeling regulations and the EU Falsified Medicines Directive enforce traceability standards that directly expand extended text label penetration in pharmaceutical primary packaging. REACH compliance across European supply chains restricts adhesive chemistries, pushing converters toward solvent-free acrylic systems that meet both bonding performance and substance authorization thresholds. Stakeholders must monitor evolving serialization mandates in emerging pharmaceutical manufacturing jurisdictions and assess digital press investments against flexographic infrastructure already amortized across high-volume food and beverage contracts.
Market Dynamics
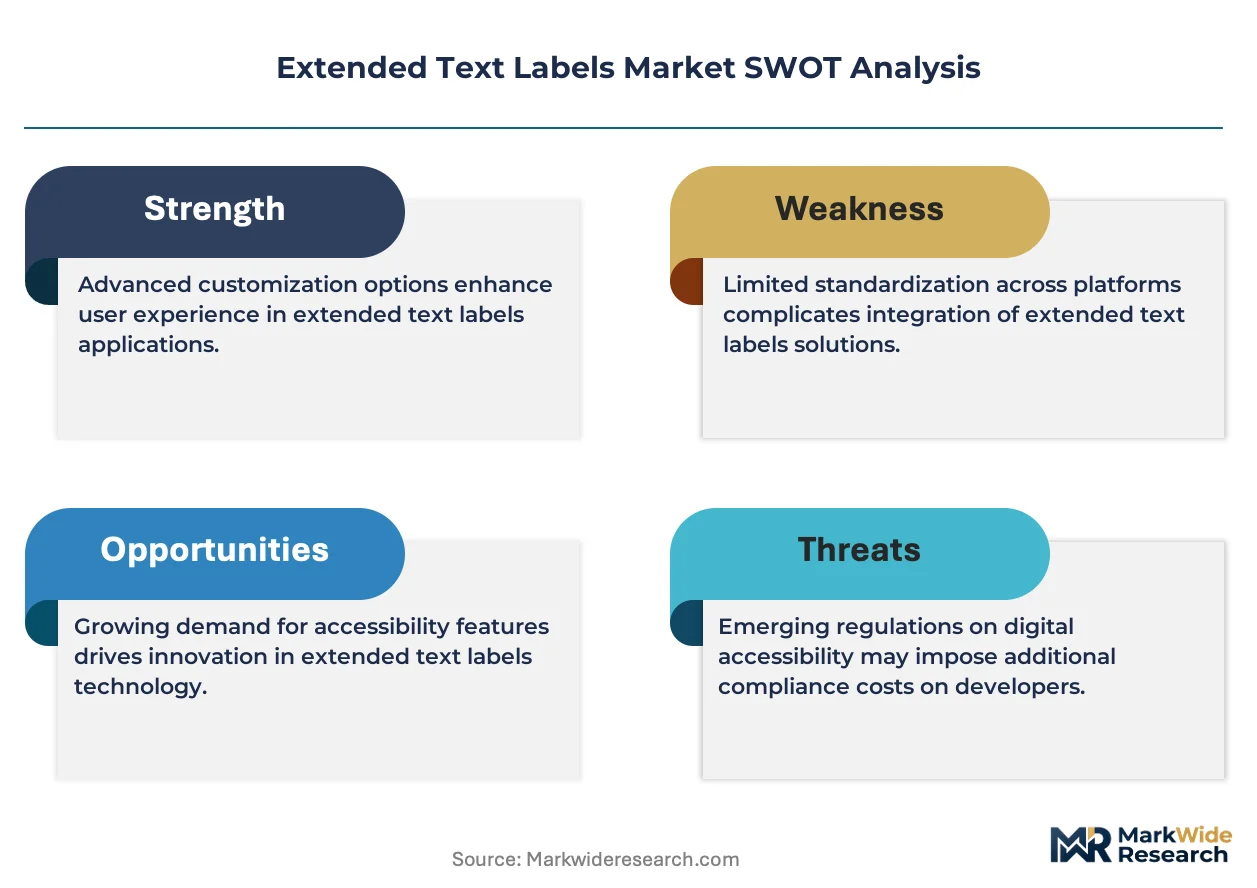
Pharmaceutical serialization mandates across multiple jurisdictions are forcing converters to retool production lines for variable-data booklet labels, compressing batch economics and favoring digital press investments over amortized flexographic infrastructure.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization requirements for pharmaceutical packaging mandate multi-page labels with unique identifiers, expanding demand for fold-out constructions in primary drug containers.
- Digital inkjet adoption:Pharmaceutical contract manufacturers now specify digital presses for short-run clinical trial materials, enabling region-specific language customization without plate-change costs.
- Frankfurt-Darmstadt corridor concentration:Germany's dense cluster of contract packaging organizations serving EU-wide distribution networks generates concentrated procurement of polyester booklet-label systems.
Market Restraints
- Raw material concentration:Specialty polyester film supply concentrates among a limited set of polymer science specialists, exposing converters to input cost volatility and allocation constraints.
- REACH substance authorization:Solvent-based adhesive chemistries face progressive restriction across European supply chains, forcing reformulation investments that extend qualification timelines.
- Flexographic lock-in:High-volume food and beverage contracts amortize conventional press infrastructure, creating sunk-cost resistance to digital migration despite pharmaceutical demand pull.
Strategic Opportunities
- Clinical trial logistics expansion:Decentralized trial models require patient-specific dosing instructions in 20+ languages, opening demand for ultra-complex booklet labels with integrated temperature indicators.
- Brazil ANVISA serialization alignment:Emerging pharmaceutical manufacturing jurisdictions are adopting traceability frameworks modeled on EU standards, creating regulatory tailwinds for export-ready label converters.
- RFID-inlay convergence:Combining extended-text constructions with passive RFID tags enables item-level authentication without separate label application, streamlining high-value pharmaceutical packaging lines.
Industry Challenges
- Variable-data workflow integration:Pharmaceutical manufacturers require seamless data handoff from enterprise serialization systems to print production, demanding costly MES-press connectivity investments.
- Multi-substrate certification timelines:Each new polyester construction requires separate stability testing under ICH guidelines, extending qualification cycles before commercial deployment.
- Specialized operator scarcity:Digital press operation combines conventional print mechanics with IT infrastructure management, creating skill gaps that constrain capacity expansion at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extended Text Labels Market |
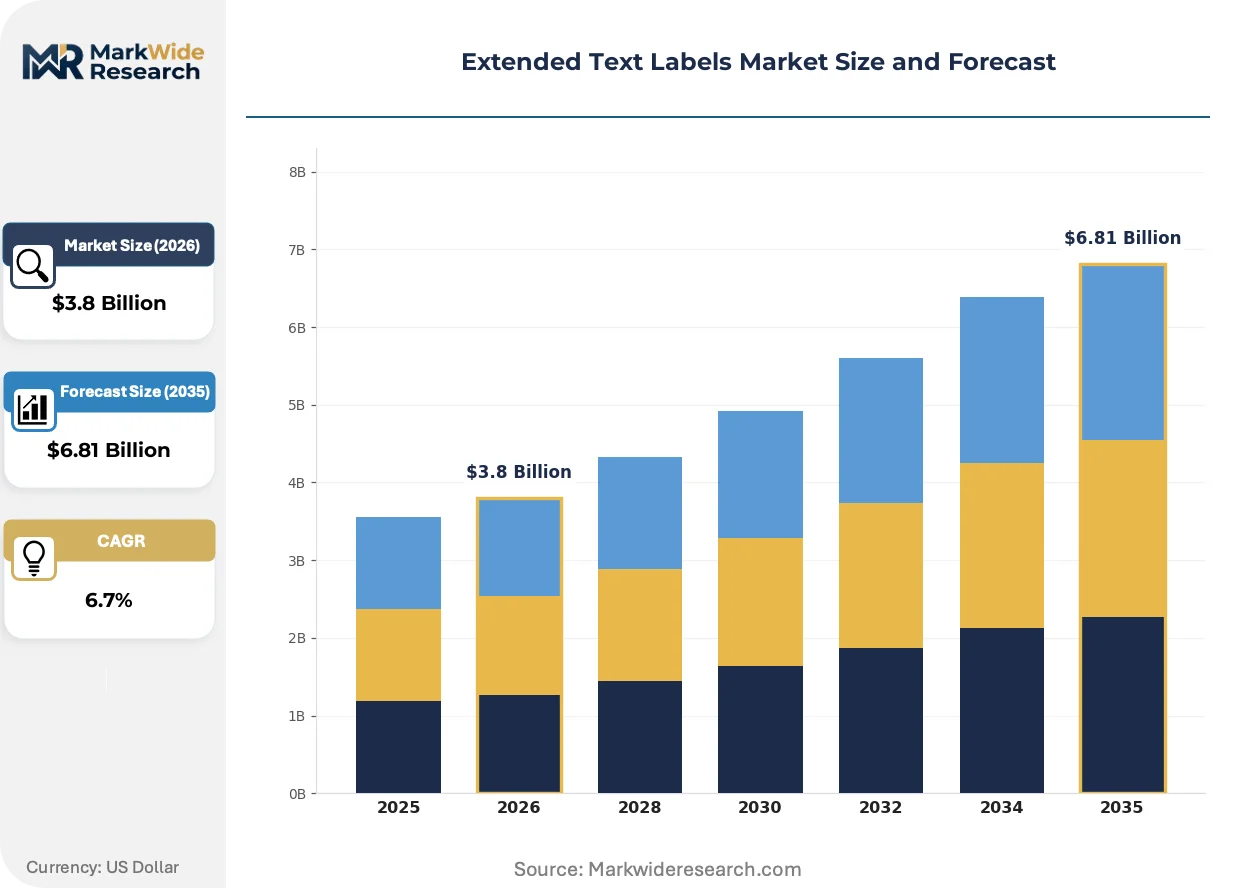
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Paper, Vinyl, Polyester, Polypropylene Adhesive Type: Permanent, Removable, Repositionable, Pressure-Sensitive Print Technology: Digital, Flexographic, Gravure, Offset End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics |
| Companies Covered | Avery Dennison Corporation, Multi-Color Corporation, Coveris Holdings S.A., Schreiner Group GmbH & Co. KG, Denny Bros Ltd., Faubel & Co. Nachf. GmbH, JH Bertrand Inc., CCL Industries Inc., Resource Label Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extended Text Labels Market Emerging Trajectories
Extended text label production is bifurcating between high-throughput flexographic operations serving commoditized segments and digitally enabled systems capturing pharmaceutical serialization work, with substrate chemistry and data-integration capabilities becoming primary differentiation vectors.
Water-based UV-LED inkjet systems are supplanting solvent gravure for pharmaceutical booklet labels, enabling pharmaceutical contract packagers to reduce minimum order quantities from 50,000 to 5,000 units while maintaining regulatory-grade print durability, which compresses inventory carrying costs and accelerates regional language customization cycles.
REACH substance authorization protocols are restricting adhesive chemistries across European pharmaceutical supply chains, forcing converters toward solvent-free acrylic systems that meet both bonding performance thresholds and ECHA substance authorization requirements, with German and Swiss packaging facilities experiencing the most acute reformulation pressure.
Buyer procurement patterns are fragmenting as pharmaceutical manufacturers unbundle label supply from primary packaging contracts, with Merck KGaA and Roche Diagnostics establishing direct relationships with specialized booklet-label converters in the Rhine-Main region to secure serialization-ready capacity outside traditional packaging vendor hierarchies.
Extended Text Labels Market Segmentation
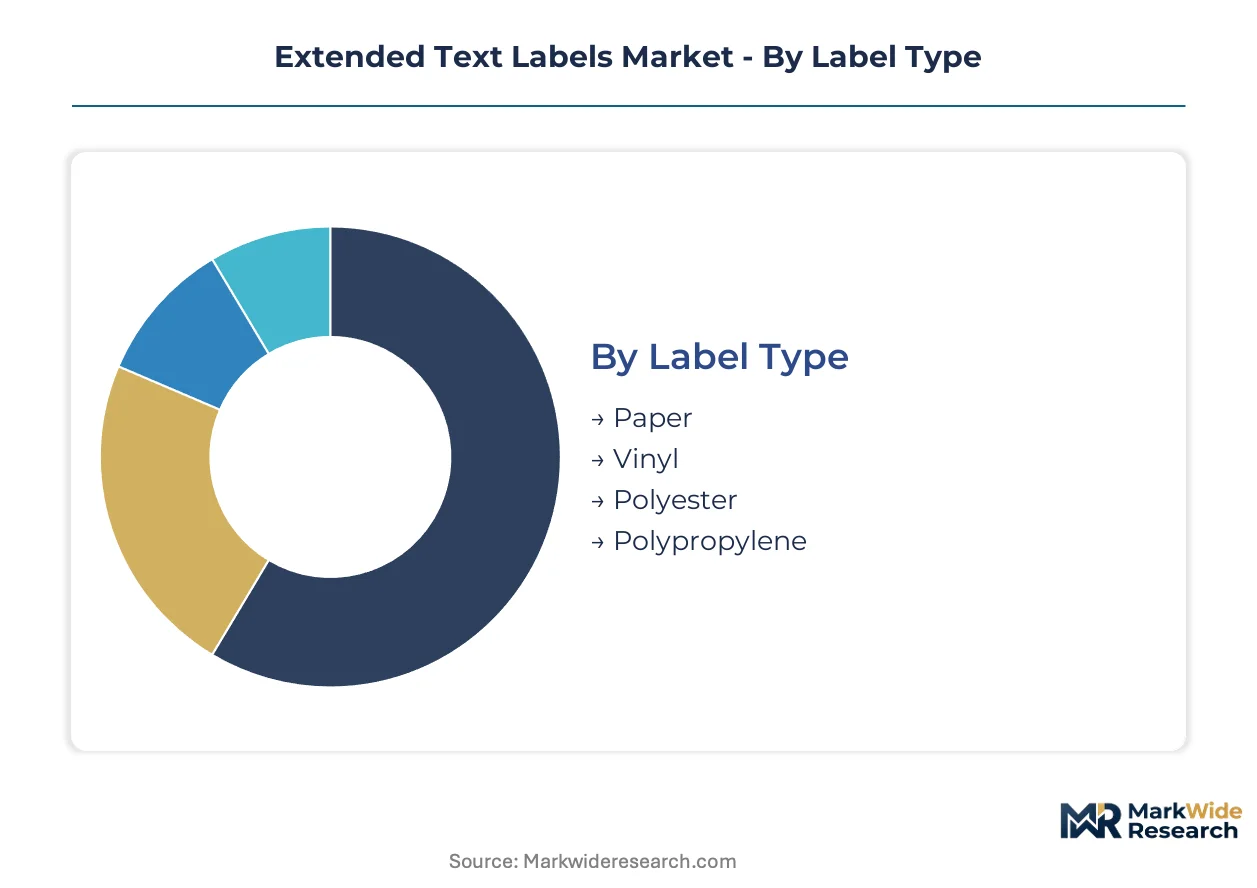
Extended text labels serve divergent performance requirements across pharmaceutical serialization, food safety compliance, and industrial durability applications. Substrate chemistry, adhesive formulation, and print technology choices cascade through total cost of ownership and regulatory qualification timelines.
Label Type:
Premium margin pools concentrate in synthetic substrates where dimensional stability and chemical resistance command price premiums over commodity paper constructions.
- Polyester:Biaxially oriented polyethylene terephthalate constructions deliver autoclave resistance and cold-chain dimensional stability required for pharmaceutical primary packaging. Demand concentrates in Germany's Frankfurt-Darmstadt pharmaceutical manufacturing corridor, where EMA serialization mandates under the Falsified Medicines Directive force adoption of multi-ply booklet systems capable of withstanding gamma sterilization cycles.
- Vinyl:Polyvinyl chloride formulations provide outdoor UV resistance and mechanical abrasion tolerance for durable goods labeling. Procurement clusters in North American automotive and power equipment sectors where NHTSA durability standards and extended warranty tracking requirements drive specification of 7-year exterior-grade constructions.
- Paper:Coated and uncoated cellulose substrates serve cost-sensitive food and beverage applications where moisture exposure remains limited and single-use disposability dominates lifecycle economics.
- Polypropylene:Oriented polypropylene films balance chemical resistance with lower density than polyester, finding uptake in cosmetic and personal care segments where squeezable container compliance and label conformability outweigh extreme temperature performance requirements.
The dominant share belongs to polyester, while polypropylene is closing the gap fastest.
Adhesive Type:
Application permanence requirements and surface energy characteristics of target substrates determine adhesive selection economics.
- Permanent:Solvent-free acrylic systems dominate pharmaceutical applications where ECHA REACH substance authorization restricts legacy solvent chemistries, with German and Swiss packaging facilities experiencing acute reformulation pressure to maintain EU market access.
- Pressure-Sensitive:Self-adhesive constructions combining face stock, adhesive layer, and release liner into single-application systems capture the majority of extended text label volume, enabling high-speed automated application on rotary bottle labeling equipment without heat or moisture activation.
- Removable:Low-tack acrylic formulations permit clean removal from glass and high-density polyethylene containers, serving retail promotional labels and temporary pricing applications in European grocery and mass merchandise channels.
- Repositionable:Microsphere adhesive technologies allow initial placement adjustment before permanent bonding, finding use in electronics labeling where precise alignment of extended-content fold-out panels on small device surfaces reduces application error rates.
Permanent adhesives hold the largest installed base, though pressure-sensitive configurations are expanding most quickly.
Print Technology:
Run length economics and variable-data capability requirements are rotating competitive positioning across converter capital investments.
- Digital:UV-LED inkjet systems enable pharmaceutical contract manufacturers to reduce minimum order quantities from 50,000 to 5,000 units while maintaining regulatory-grade print durability, compressing inventory carrying costs and accelerating regional language customization cycles for clinical trial materials.
- Flexographic:Central impression drum presses deliver unit cost advantages at volumes above 100,000 units, with amortized infrastructure across high-volume food and beverage contracts creating sunk-cost resistance to digital migration despite pharmaceutical demand pull.
- Gravure:Cylinder-based intaglio printing retains position in ultra-high-volume liquor and tobacco applications where image consistency and metallic ink effects justify cylinder engraving costs across multi-million-unit annual commitments.
- Offset:Lithographic sheetfed systems serve commercial and promotional extended text applications where paper-based substrates and lower production speeds align with quality-sensitive marketing collateral requirements.
Flexographic equipment still processes the greatest label volume, yet digital adoption is climbing the fastest.
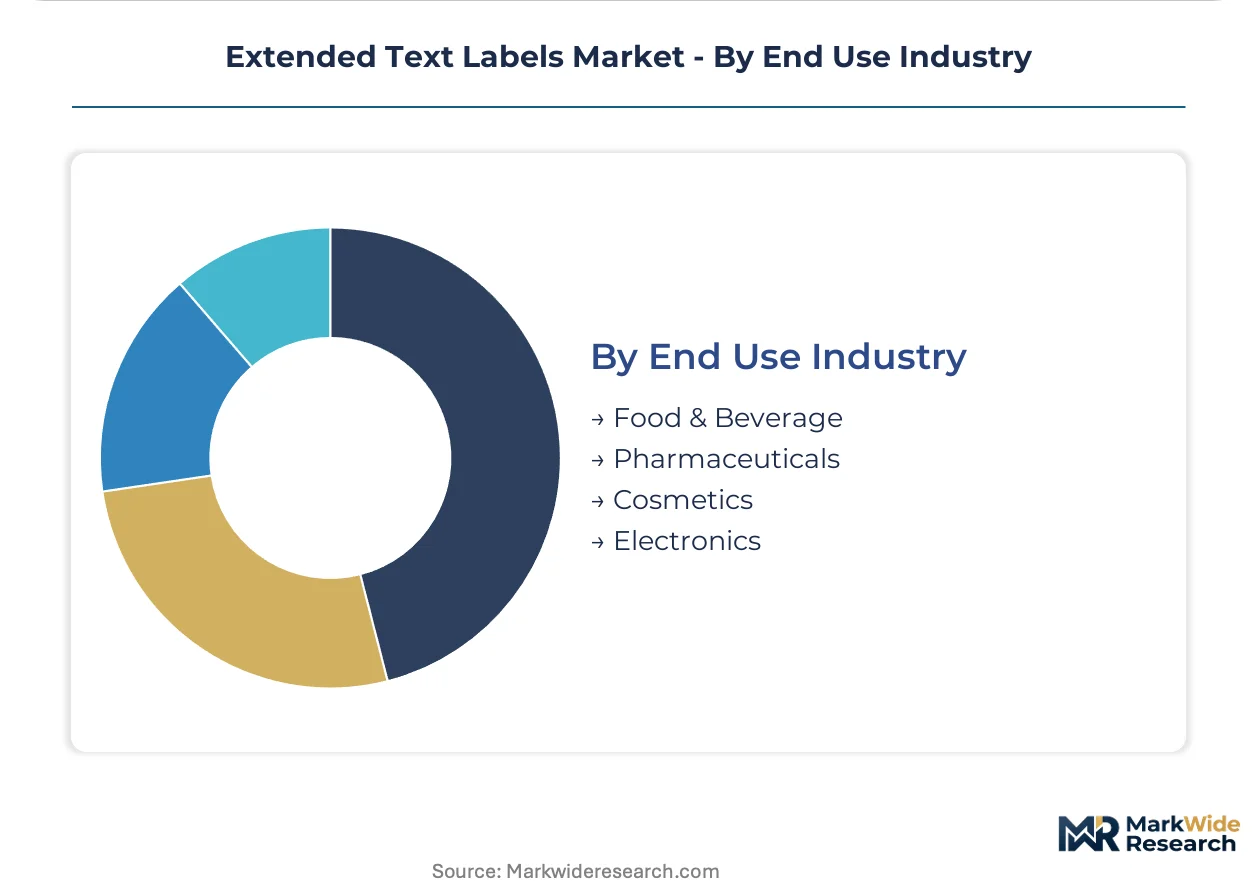
End Use Industry:
Regulatory compliance intensity and product liability exposure create divergent customer willingness-to-pay across vertical applications.
- Pharmaceuticals:FDA 21 CFR Part 211 labeling regulations and EU Falsified Medicines Directive serialization mandates directly expand extended text label penetration in primary drug packaging, with multi-page booklet constructions required for patient information leaflets, dosage instructions, and unique identifier integration.
- Food & Beverage:FSSAI nutritional disclosure requirements in India and FDA Food Safety Modernization Act traceability provisions in the United States drive multilingual ingredient labeling on constrained container surfaces, particularly for export-oriented processed food manufacturers.
- Cosmetics:EU Regulation (EC) No 1223/2009 ingredient disclosure rules and emerging microplastic labeling requirements force brand owners to expand printable surface area on primary packaging without container redesign.
- Electronics:WEEE directive compliance markings, safety certifications, and multilingual warranty terms concentrate demand in East Asian manufacturing hubs serving EU and North American distribution.
Pharmaceuticals commands the dominant value share, while cosmetics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in pharmaceutical-grade polyester constructions concentrates in Germany's Rhine-Main corridor, while cost-sensitive paper-based alternatives dominate procurement patterns in India and Southeast Asian export manufacturing hubs.
United States
FDA 21 CFR Part 211 labeling regulations and the Food Safety Modernization Act traceability provisions drive pharmaceutical and food sector demand for serialized booklet labels. The FDA enforces unique device identification requirements that expand multi-page label penetration in medical device packaging. Greater Boston's biotech cluster and New Jersey's pharmaceutical corridor generate concentrated procurement of autoclave-resistant polyester constructions.
Germany
The EMA serialization mandates under the EU Falsified Medicines Directive force pharmaceutical contract manufacturers to adopt multi-ply booklet systems with integrated traceability codes. ECHA REACH substance authorization restricts solvent-based adhesive chemistries, accelerating converter migration to solvent-free acrylic systems. The Frankfurt-Darmstadt corridor hosts dense clusters of packaging organizations serving EU-wide distribution networks.
Switzerland
Swissmedic pharmaceutical regulations align with EU serialization standards, creating demand for booklet labels capable of withstanding gamma sterilization and cold-chain distribution. The country's precision manufacturing base supports high-value pharmaceutical primary packaging. Basel's pharmaceutical research cluster drives specialized procurement of clinical trial materials with patient-specific dosing instructions.
India
CDSCO pharmaceutical serialization requirements and FSSAI nutritional disclosure rules expand extended text label adoption in export-oriented generic drug manufacturing and processed food sectors. The PLI scheme for pharmaceuticals incentivizes domestic packaging capability investments. Maharashtra's Mumbai-Pune pharmaceutical belt and Gujarat's Ahmedabad-Vadodara corridor concentrate contract manufacturing demand.
China
NMPA traceability mandates for pharmaceutical packaging and GB standards for food safety labeling accelerate multi-page label penetration in domestic and export manufacturing. SAMR enforcement of labeling compliance intensifies across consumer goods sectors. The Yangtze River Delta pharmaceutical manufacturing zone around Shanghai generates concentrated demand for serialization-ready constructions.
Extended Text Labels Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the extended text labels landscape, with polymer science specialists commanding premium positions in pharmaceutical-grade substrates while scale-driven converters capture commoditized food and beverage volume. The market structure tilts toward consolidation at the premium tier and fragmentation in mid-market segments. Three archetypes dominate: integrated material science conglomerates with captive polymer supply, specialized booklet-label converters with clinical trial expertise, and regional flexographic operators serving high-volume standardized applications. M&A activity concentrates on digital press capability acquisition, while strategic partnerships between converters and pharmaceutical contract manufacturers bypass traditional packaging vendor hierarchies.
Within the integrated material science tier, Avery Dennison Corporation exemplifies polymer-to-label vertical control, while Schreiner Group GmbH & Co. KG occupies a specialized position in European pharmaceutical booklet systems. CCL Industries Inc. represents geographic breadth strategies with dedicated extended-text facilities across multiple production zones. These three anchors illustrate divergent competitive vectors: material science depth, clinical specialization, and geographic scale.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Multi-Color Corporation |
| Coveris Holdings S.A. |
| Schreiner Group GmbH & Co. KG |
| Denny Bros Ltd. |
| Faubel & Co. Nachf. GmbH |
| JH Bertrand Inc. |
| CCL Industries Inc. |
| Resource Label Group LLC |
| Others |
Supply Flow & Price Mechanics
Ninety-day polyester film lead times from German polymer specialists compress converter inventory buffers and amplify pricing leverage for pharmaceutical-grade substrate holders. This temporal constraint binds procurement flexibility to EMA serialization mandates, concentrating margin capture among integrated material science conglomerates while forcing mid-tier converters into longer-term contract commitments.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical booklet labels from standard food-grade constructions. Contract-based long-term offtake dominates, with price differentiation driven by certification grade (FDA 21 CFR Part 211 vs. FSSAI tiers) and volume scale. Pricing pressure stems from digital press commoditization in short-run segments, while pharmaceutical buyers exhibit lowest price sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Inbound logistics costs through Rotterdam-Antwerp container corridors constrain just-in-time delivery for Asian polyester film imports. Supply concentrates in Germany, China, and South Korea for specialty substrates; adhesive chemistries draw from Swiss and Dutch formulation specialists. Single-source vulnerability persists in gamma-stabilized polyester grades. Distribution runs through pharmaceutical contract packaging organizations and food-grade converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical contract manufacturers as direct procurement relationships with specialized booklet-label converters bypass traditional packaging vendor hierarchies. This consolidation among downstream buyers fragments legacy supply arrangements.
For Market Incumbents: Consolidate polymer science capabilities through backward integration into specialty polyester film production to defend against digital print entrants eroding premium positions. Lock in serialization-ready capacity via exclusive supply agreements with Rhine-Main corridor contract packaging organizations facing EMA mandate deadlines.
For New Entrants and Emerging Players: Lead with water-based UV-LED inkjet systems targeting clinical trial logistics where patient-specific dosing instructions in 20+ languages create ultra-complex demand beyond incumbent flexographic capacity. Penetrate Brazil ANVISA serialization alignment programs as regulatory tailwinds favor export-ready digital converters.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because pharmaceutical serialization mandates across emerging jurisdictions create durable demand for traceability-integrated label systems. Target acquisition profiles center on digital press operators with validated MES connectivity. Watch FDA unique device identification expansion into medical device packaging as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Press Capability Acquisition | Enables short-run pharmaceutical serialization work with variable-data integration beyond flexographic constraints. |
| Solvent-Free Adhesive Reformulation | Secures ECHA REACH compliance for European pharmaceutical supply chain continuity. |
| RFID-Inlay Convergence Development | Combines extended-text constructions with passive authentication for streamlined high-value packaging lines. |
| Clinical Trial Logistics Specialization | Captures decentralized trial demand for multi-language patient-specific dosing instruction labels. |
| Rhine-Main Corridor Capacity Expansion | Positions near Frankfurt-Darmstadt pharmaceutical manufacturing cluster serving EU-wide distribution networks. |
Methodological Framework
A standing panel of pharmaceutical packaging procurement managers, flexographic press operators, digital print integration specialists, and EMA regulatory affairs consultants provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with converter operations directors and pharmaceutical contract manufacturing executives, validated against secondary sources including FDA 21 CFR guidance documents, EMA serialization implementation reports, ECHA substance authorization databases, and customs trade data for polyester film imports. Bottom-up capacity assessments triangulated with top-down demand modeling from pharmaceutical serialization mandate timelines.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across label substrate chemistry, adhesive formulation permanence, print technology configuration, and end-use regulatory intensity. CAGRs derived from regression analysis of historical pharmaceutical packaging expenditure against mandated serialization rollout schedules, with ICH stability testing timelines and digital press adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside EMA serialization enforcement continuity or REACH substance authorization stability would require recalibration. Forecasts reflect documented assumptions regarding pharmaceutical contract packaging concentration patterns and digital press technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Direct Thermal Labels Market
Labels
North America Self-Adhesive Labels Market
Labels
Industrial Label Printers Market
Labels
Healthcare and Laboratory Labels Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Freezer Label Market
Labels
Europe Self Adhesives Label Market
Labels
Wet Glue Labels Market
Labels
Global Tamper Evident Labels Market
Labels
Domed Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Warning Labels and Stickers Market
Labels
Direct Thermal Linerless Labels Market
Labels
Holographic Labels Market
Labels
Polyester Labels Market
Labels
Die Cut Labels Market