
 Direct Thermal Linerless Labels Market | 2026-2036
Direct Thermal Linerless Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Thermal Linerless Labels Market Outlook
Food services is pivoting toward direct thermal linerless formats as quick-service chains and meal-kit distributors seek to cut liner disposal costs. Avery Dennison Corporation anchors its position through specialized adhesive coatings that perform across variable temperature environments. UPM Raflatac leverages its pulp-to-label integration to control substrate quality and supply continuity. Zebra Technologies competes by bundling linerless media with its thermal printer installed base, tightening hardware-software-substrate linkages.
Direct thermal linerless labels are pressure-sensitive adhesive constructions manufactured without a silicone release liner, relying instead on specialized coatings that prevent adhesive-to-adhesive contact during roll unwind; they typically employ hot-melt or acrylic adhesives on facestocks ranging from thermal paper to polypropylene, with print sensitivity calibrated for 200–300 dpi thermal printheads. The primary commercial purpose is to eliminate liner waste while maintaining scan-readability in high-speed retail, logistics, and food packaging environments. Synthetic facestocks lead on durability metrics in shipping and inventory management, though paper grades retain volume dominance in retail pricing due to cost positioning. Digital printing technology is capturing share among custom design workflows where shorter runs and variable data justify toner-based or inkjet integration over flexographic plate costs.
FDA food-contact substance notifications govern adhesive migration limits for linerless labels applied to prepared foods in the United States, while the EU F-Gas Regulation and REACH constrain silicone alternative chemistries used in release coatings. ECHA's ongoing substance evaluations for cyclic siloxanes are pressuring manufacturers to validate silicone-free release systems or document safe-use profiles. Stakeholders must monitor how evolving extended producer responsibility frameworks for packaging waste alter total cost calculations against conventional lined labels.
Market Dynamics
E-commerce logistics providers are expanding linerless label procurement to reduce liner waste in high-volume shipping operations, while the EU Green Deal and single-use plastics directives accelerate demand for adhesive substrates that eliminate silicone release liners.
Growth Catalysts
- EU Green Deal:Packaging waste directives mandate reduction of single-use plastics, pushing food distributors toward silicone-free label constructions.
- Hot-melt adhesive formulations:Improved low-temperature performance enables linerless deployment in cold-chain logistics previously served by lined alternatives.
- German packaging automation:Concentrated investment in automated applicators creates pull for roll-fed linerless media compatible with high-speed lines.
Market Restraints
- Silicone price volatility:Release coating alternatives remain cost-sensitive to petrochemical feedstock swings, compressing margins on silicone-free formulations.
- Facestock supply concentration:Thermal paper substrate production clusters in Nordic pulp regions, exposing converters to freight cost spikes and currency risk.
- Adhesive migration limits:FDA food-contact substance notifications impose testing burdens that extend qualification timelines for prepared-food applications.
Strategic Opportunities
- Meal-kit distribution:Direct-to-consumer food boxes require variable-data labeling with minimal waste, favoring linerless roll formats.
- Digital printing convergence:Toner-based and inkjet systems enable shorter runs with variable data, expanding addressable market for custom linerless workflows.
- Extended producer responsibility frameworks:Packaging waste regulations in Germany and France create compliance-driven preference for liner elimination.
Industry Challenges
- Thermal printhead compatibility:Linerless coatings require recalibration of 200–300 dpi printheads, demanding field service expertise scarce among maintenance technicians.
- REACH substance evaluations:ECHA's ongoing cyclic siloxane assessments force documentation of safe-use profiles for silicone-free release systems.
- Legacy applicator retrofitting:Existing shipping lines designed for lined labels require mechanical modification to handle linerless unwind characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Thermal Linerless Labels Market |
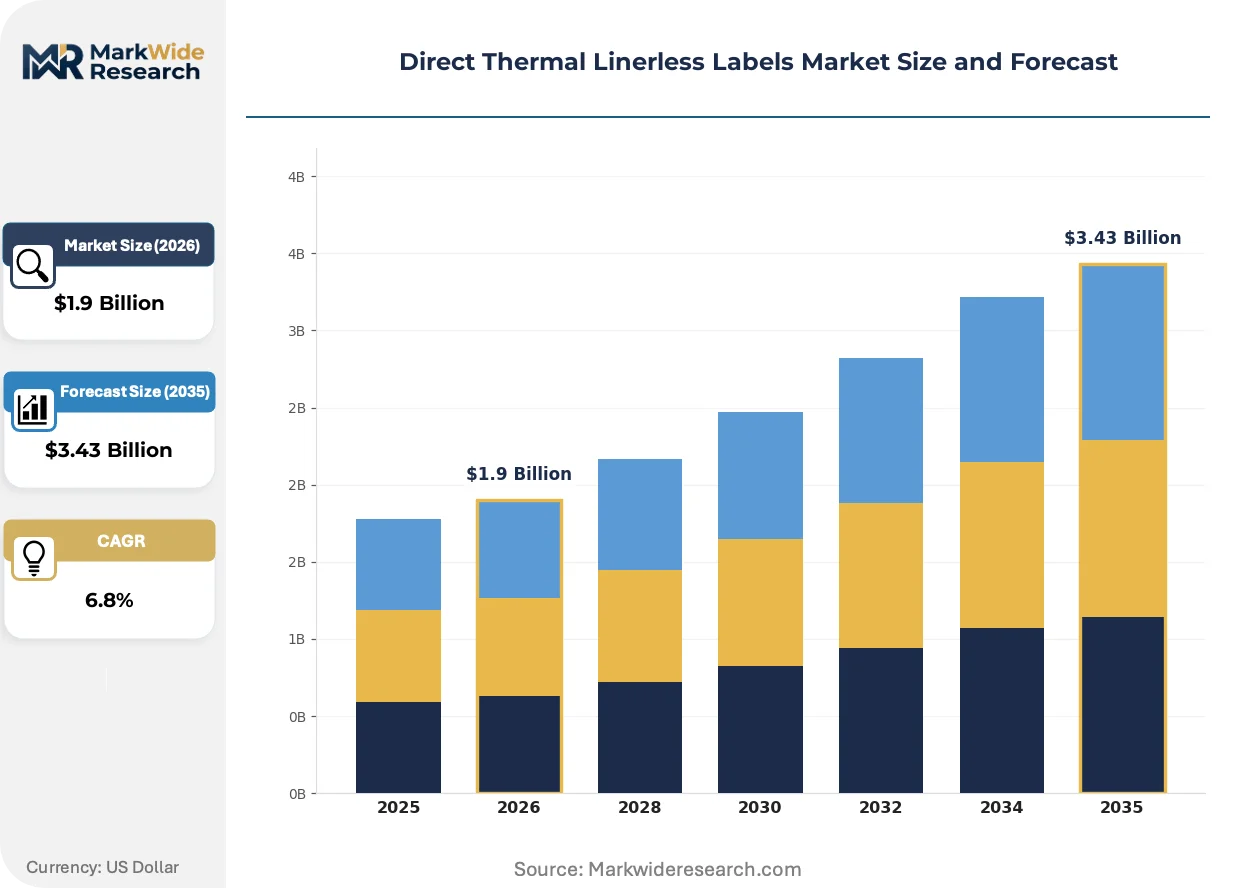
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Paper, Compliance Labels, Custom Designs Application: Retail Pricing, Shipping, Product Labeling, Inventory Management Technology: Digital Printing, Flexographic, Screen Printing, Thermal Transfer End User: Manufacturers, Retailers, Logistics Providers, Food Services |
| Companies Covered | RR Donnelley, UPM Raflatac, Avery Dennison Corporation, Seiko Instruments, 3M, Zebra Technologies, Honeywell International, BIXOLON, SATO Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Thermal Linerless Labels Market Strategic Shifts
Silicone-free release coatings are reshaping substrate engineering as regulatory pressure intensifies, while digital printing workflows compress run-length economics and food logistics automation drives format standardization.
Water-based release coatings are absorbing the functional role of silicone in linerless constructions, preventing adhesive-to-adhesive contact during roll unwind without petrochemical release liners. Cold-chain distributors in Northern Europe are adopting these formulations fastest, driven by sustainability procurement mandates. The technology is absorbing market share from conventional silicone-coated alternatives in temperature-controlled logistics.
REACH constraints on cyclic siloxanes are forcing reformulation of release coating chemistries across EU manufacturing. Industrial consequence includes extended validation timelines for new adhesive-substrate combinations. Food-contact applications face the tightest compliance windows, with converters pre-qualifying silicone-free alternatives ahead of anticipated substance restrictions.
Variable-data printing is compressing order quantities as brand owners demand shorter runs with SKU-level customization. Traditional flexographic plate costs are being displaced by toner-based and inkjet integration in quick-service restaurant and meal-kit channels. Germany and the Netherlands show the fastest adoption, where centralized distribution centers consolidate labeling operations for multi-brand portfolios.
Direct Thermal Linerless Labels Market Segmentation
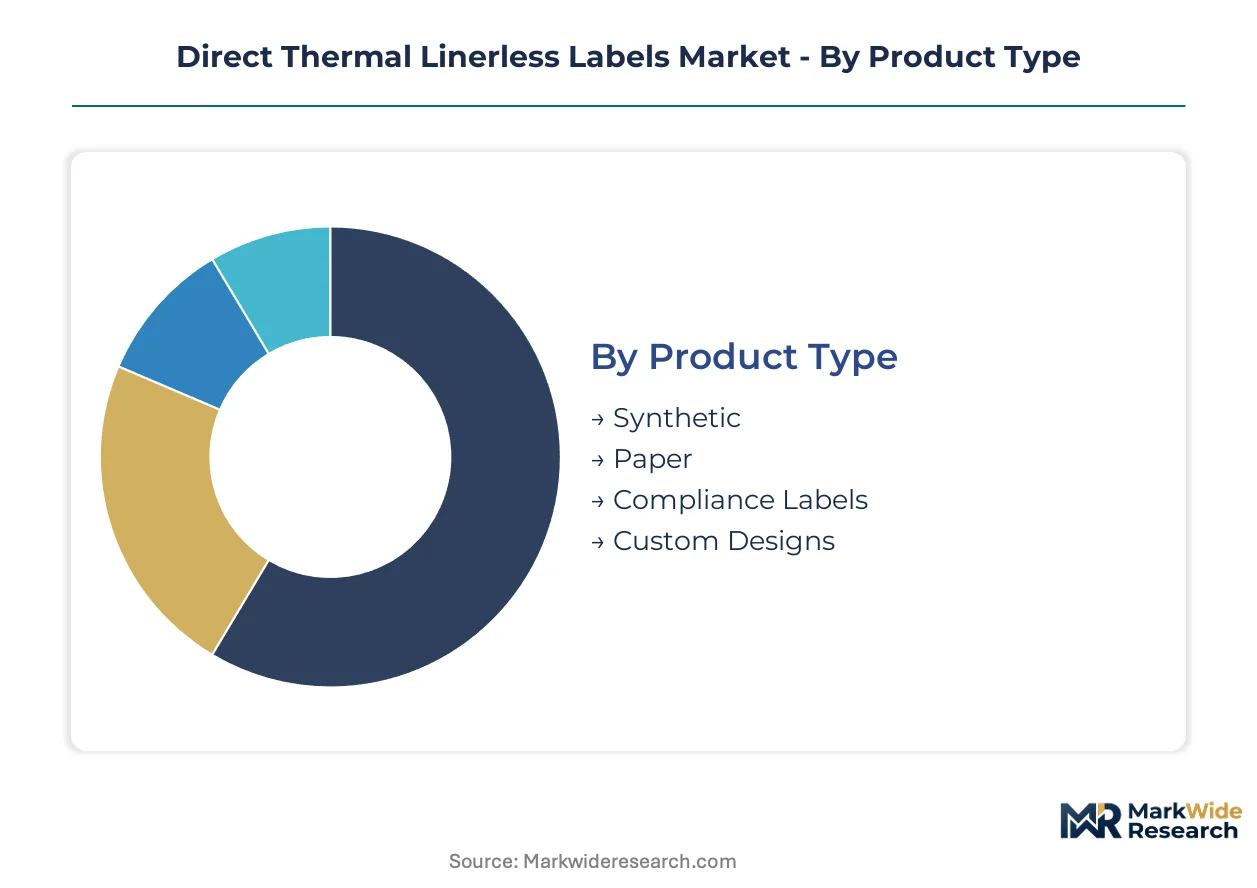
Direct thermal linerless labels serve divergent performance requirements across temperature extremes, regulatory environments, and print speed demands. Segmentation reveals how substrate chemistry, application workflow, and end-user infrastructure dictate purchasing criteria and supplier positioning.
Product Type:
Thermal sensitivity and facestock durability define the specification hierarchy, with material science investments clustering where environmental stress exceeds paper tolerance.
- Synthetic:Polypropylene and polyethylene facestocks withstand moisture, abrasion, and sub-zero temperatures without delamination. Cold-chain logistics operators in Germany and the Netherlands specify synthetic grades for pharmaceutical and fresh-produce distribution where condensation compromises paper integrity.
- Paper:Thermal paper dominates unit economics in retail pricing applications where shelf-life exposure remains minimal. Quick-service restaurant chains deploy paper linerless rolls for receipt and order-label functions where cost-per-impression drives procurement decisions.
- Compliance Labels:Pre-printed regulatory markings for hazardous materials, nutritional facts, and serialization requirements.
- Custom Designs:Brand-owner specifications with color fields, security features, or variable-data zones.
Synthetic leads on scale in logistics channels; paper leads on momentum in food-service automation.
Application:
Workflow velocity and label permanence requirements segment demand by operational environment rather than industry vertical.
- Shipping:High-speed applicators in e-commerce fulfillment centers demand linerless rolls with precise unwind tension and adhesive tack calibrated for corrugated, polybag, and reusable tote surfaces. German parcel networks are retrofitting lines for linerless compatibility to meet EU packaging waste directives.
- Retail Pricing:Short-dwell applications with minimal adhesive exposure prioritize facestock print contrast over durability. Supermarket chains in France are consolidating shelf-label operations to linerless formats to eliminate liner collection and disposal labor.
- Product Labeling:Primary package identification with brand graphics and regulatory text.
- Inventory Management:Internal tracking labels for warehouse location, asset, and work-in-process identification.
Shipping commands the largest volume position; retail pricing is climbing the fastest as self-checkout expansion accelerates format conversion.
Technology:
Capital equipment utilization and run-length economics determine print technology selection, with digital systems capturing share in variable-data workflows.
- Digital Printing:Toner-based and inkjet systems enable lot-size-one production with SKU-level customization without plate costs. Meal-kit distributors in the United Kingdom rely on digital linerless for recipe-specific ingredient labels with variable allergen warnings.
- Flexographic:Rotogravure-quality graphics at scale remain cost-advantaged for long-run brand labels with static designs.
- Screen Printing:Heavy ink deposits for industrial durability and outdoor exposure applications.
- Thermal Transfer:Ribbon-based systems for legacy compatibility in existing printer fleets.
Flexographic retains the widest installed base; digital is gaining share fastest in food logistics and personalized commerce.
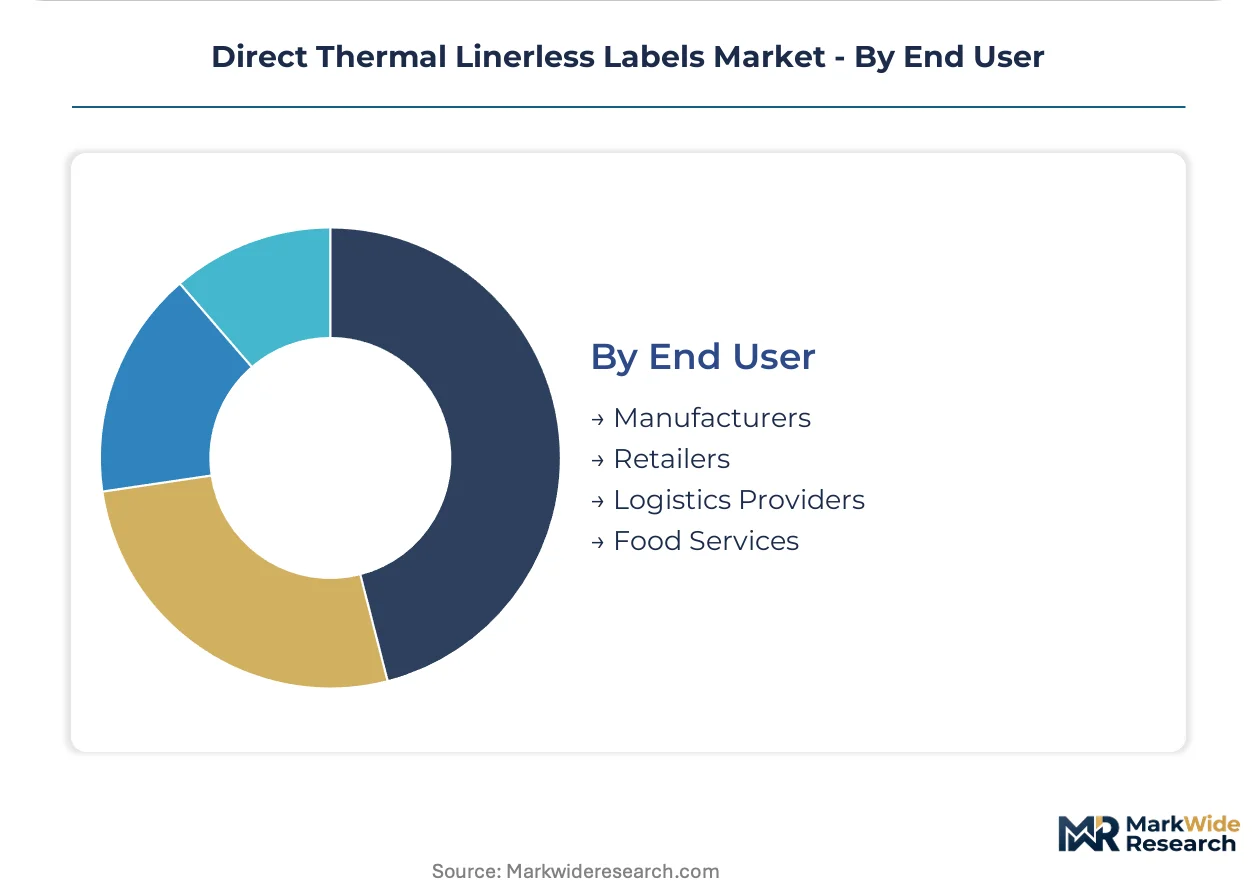
End User:
Procurement sophistication and sustainability mandate intensity differentiate customer segments, with logistics providers leading linerless specification authority.
- Logistics Providers:Parcel networks and third-party fulfillment operators specify linerless media to reduce waste tonnage and streamline sortation line maintenance. DHL and Hermes operations in Germany have mandated linerless conversion for new equipment procurement.
- Food Services:Quick-service chains and meal-kit platforms prioritize liner elimination to reduce back-of-house disposal burden and align with corporate sustainability commitments. Pret A Manger and similar chains are piloting linerless for grab-and-go labeling.
- Manufacturers:Industrial goods producers with integrated packaging lines.
- Retailers:Omnichannel operators managing shelf-edge and fulfillment label requirements.
Logistics providers lead on contract value concentration; food services is expanding most quickly as sustainability procurement policies harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping linerless label production geography as converters migrate toward jurisdictions with clearer silicone-free coating approval pathways and lower extended producer responsibility compliance costs.
Germany
Parcel networks DHL and Hermes mandate linerless formats for new equipment procurement to satisfy EU packaging waste directives. The country's national packaging regulator enforces strict extended producer responsibility frameworks that penalize liner waste tonnage. The Rhine-Ruhr industrial corridor hosts concentrated adhesive coating R&D as BASF and Henkel pilot water-based release systems.
United States
FDA food-contact substance notifications for adhesive migration limits drive qualification investment from meal-kit distributors and quick-service chains. The EPA maintains oversight of volatile organic compound emissions from coating operations. Chicago and Dallas-Fort Worth distribution centers are retrofitting applicator lines for linerless compatibility to reduce waste disposal labor costs.
United Kingdom
Variable-data digital printing adoption concentrates among centralized meal-kit fulfillment operations serving multi-brand portfolios. The Environment Agency implements packaging waste regulations that accelerate liner elimination incentives. The Midlands logistics hub around Birmingham is converting legacy thermal transfer installations to direct thermal linerless for grocery e-commerce.
Netherlands
Cold-chain distributors adopt silicone-free water-based release coatings fastest among Northern European markets. The Dutch national environmental regulator enforces EU Green Deal packaging waste reduction targets through producer accountability schemes. The Rotterdam-Antwerp port cluster anchors linerless substrate import and conversion for re-export across continental distribution networks.
France
Supermarket chains consolidate shelf-label operations to linerless formats to eliminate liner collection labor at self-checkout expansion sites. ANSM and environmental regulators coordinate on food-contact adhesive safety assessments. The Île-de-France logistics basin around Paris is standardizing linerless roll specifications across omnichannel retail fulfillment centers.
Direct Thermal Linerless Labels Market Competitive Environment
Capacity expansion dominates the current landscape as substrate manufacturers invest in silicone-free coating lines ahead of anticipated REACH substance restrictions. The vendor base organizes into three tiers: integrated pulp-to-label conglomerates controlling thermal paper supply, specialized adhesive coaters with proprietary release formulations, and hardware bundlers leveraging thermal printer installed bases. Strategic archetypes include backward-integrated substrate controllers, coating technology licensors, and print-system ecosystem builders. M&A activity concentrates on adhesive coating assets, while geographic expansion targets German and French packaging automation clusters.
Among North American diversified manufacturers, 3M and Avery Dennison Corporation exemplify the coating-technology archetype through specialized adhesive portfolios. UPM Raflatac anchors the integrated substrate controller position with captive pulp sourcing. Zebra Technologies occupies the hardware-bundler tier, tightening media-printer linkages through linerless roll specifications calibrated to its thermal printhead installed base.
| Leading Market Players |
|---|
| RR Donnelley |
| UPM Raflatac |
| Avery Dennison Corporation |
| Seiko Instruments |
| 3M |
| Zebra Technologies |
| Honeywell International |
| BIXOLON |
| SATO Holdings |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging waste mandates gate qualified supply for converters serving German and French parcel networks, while simultaneously creating premium-tier pricing access for silicone-free coating specialists with validated REACH documentation.
Pricing Analysis
Distributor margin layers compress pricing transparency as converters serving quick-service restaurant chains negotiate direct-to-OEM volume discounts against spot-market paper substrate purchases. Pricing stratifies across premium silicone-free formulations, standard hot-melt constructions, and economy-grade thermal paper tiers, with certification-grade differentiation commanding measurable spreads. Cost compression in economy paper grades is intensifying because Nordic pulp freight spikes and currency volatility squeeze converter margins. Quick-service restaurant procurement teams demonstrate highest price sensitivity due to cost-per-impression metrics, while pharmaceutical cold-chain distributors show lowest sensitivity given compliance-driven specification authority.
Supply Chain Analysis
Workforce availability constraints in Finnish and Swedish pulp mill regions tether thermal paper substrate supply to seasonal labor pool fluctuations and union negotiation cycles. Manufacturing concentrates in Germany, Finland, and the Netherlands, where coating line operators and adhesive chemists anchor regional conversion capacity. Raw material flows draw from Nordic softwood pulp, petrochemical-derived acrylic adhesives, and water-based release coating polymers. Single-source vulnerability runs through concentrated silicone-free coating chemistry suppliers facing ECHA substance evaluation timelines. Distribution runs through Rotterdam-Antwerp port clusters for continental re-export and direct mill-to-converter relationships for high-volume German parcel network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal packaging waste directives and REACH substance evaluations compound demand acceleration for qualified silicone-free alternatives.
For Market Incumbents: Deploy coating-technology licensing as a defensive lever to capture revenue from converters lacking in-house silicone-free formulation capabilities. Incumbents should accelerate backward integration into water-based release polymer supply to offset petrochemical feedstock volatility threatening margin stability. The emergence of digital-native label converters with variable-data capabilities poses substitution risk to volume-based flexographic incumbents. For New Entrants and Emerging Players: Capture white-space opportunity in meal-kit distribution channels where variable-data linerless requirements outpace incumbent converter digital printing capacity. New entrants should prioritize UK and Netherlands centralized fulfillment operations serving multi-brand portfolios, where sustainability procurement policies create rapid specification windows. A direct digital-printing service model bypasses capital-intensive coating line investments while building customer relationships ahead of potential coating asset acquisition. For Investors and Strategic Acquirers: Roll-up economics work for specialized adhesive coaters with proprietary silicone-free formulations because regulatory qualification timelines create moats against rapid commoditization. Long-term viability centers on five-to-ten-year regulatory compliance windows where ECHA substance restrictions progressively eliminate conventional silicone alternatives. The signal to watch is German parcel network linerless conversion rate acceleration as DHL and Hermes equipment procurement mandates create demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Free Coating Scale-Up | ECHA cyclic siloxane evaluations force validated alternative production capacity ahead of restrictions. |
| Digital Print System Integration | Toner-based and inkjet workflows capture meal-kit variable-data demand from legacy flexographic converters. |
| German Automation Cluster Expansion | Rhine-Ruhr adhesive R&D concentration aligns with DHL and Hermes linerless equipment mandates. |
| Water-Based Release Polymer Backward Integration | Captive supply of coating raw materials insulates margins from petrochemical price volatility. |
| Extended Producer Responsibility Compliance Services | Packaging waste accounting expertise creates converter stickiness in France and Germany regulatory environments. |
Study Parameters
Bottom-up food-service and logistics modeling reconciled against top-down adhesive substrate production tracking forms the analytical core of this study. Primary interviews with quick-service restaurant procurement directors, parcel network operations managers, adhesive coating R&D leads, and label converter plant managers combined with secondary validation from EU packaging waste directive filings, ECHA substance evaluation databases, and Nordic pulp industry trade statistics. Top-down supply-side verification draws from customs records of thermal paper substrate trade flows and coating line capacity announcements.
Historical trendline analysis of linerless label adoption rates in German parcel networks and UK meal-kit channels established baseline penetration curves extended across the projection horizon. Segmentation dimensions modeled include facestock material tier, application workflow velocity, print technology deployment, and end-user procurement sophistication. CAGRs derive from slope analysis of adoption curve inflection points calibrated against regulatory milestone timing. Industry-specific forecast inputs incorporate EU Green Deal implementation schedules and FDA food-contact substance notification approval timelines.
REACH substance restriction acceleration, FDA qualification timeline extension, and Nordic pulp supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory implementation pacing and substrate technology substitution elasticity. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Direct Thermal Labels Market
Labels
Barcode Label Market
Labels
Laser Markable Labels Market
Labels
Water Dissolvable Labels Market
Labels
Global Cryogenic Label Market
Labels
Fiber Optic Labels Market
Labels
Laser Printable Wristbands Market
Labels
Domed Labels Market
Labels
Metallic Labels Market
Labels
Syringe Labels Market
Labels
Pin Feed Labels Market
Labels
Glue Applied Automotive Labels Market
Labels
Ripeness Indicator Labels Market
Labels
Global Industrial Labels Market
Labels
Sustainable Labels Market
Labels
Wash Off Labels Market