
 Booklet Labels Market | 2026-2036
Booklet Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Booklet Labels Market Outlook
Label distribution through pharmaceutical contract packagers is fragmenting as serialization deadlines force brand owners to split orders across certified converters. CCL Industries Inc. leverages vertical integration across substrate production and finishing to capture high-compliance orders. Avery Dennison Corporation anchors North American supply with specialized adhesive portfolios for cold-chain pharmaceuticals. Schreiner Group differentiates through precision die-cutting capabilities serving European medical device labeling.
Booklet labels are multi-layer, fold-out adhesive constructions that expand printable surface area beyond standard label dimensions, typically manufactured through rotary die-cutting, precision folding, and lamination processes to accommodate dense regulatory text, multilingual instructions, or promotional content in constrained packaging footprints. Pressure-sensitive formats dominate pharmaceutical applications where removability and resealability protect dosage information across repeated openings, while digital print technology captures fastest growth as brand owners reduce minimum order quantities and accelerate SKU proliferation for regionalized packaging. Thermal transfer substrates sustain share in industrial and logistics segments requiring barcode durability against abrasion and chemical exposure.
FDA serialization requirements under the Drug Supply Chain Security Act mandate track-and-trace compatibility that shapes label substrate selection and print verification standards across US pharmaceutical packaging. EMA's Falsified Medicines Directive and evolving EU Medical Device Regulation impose equivalent compliance burdens on European converters, favoring suppliers with certified quality management systems. Stakeholders must monitor regulatory divergence between FDA and EMA traceability timelines to align capital investments in verification infrastructure with enforcement calendars.
Market Dynamics
Pharmaceutical serialization mandates are compressing converter certification timelines and fragmenting order flows across certified supply networks, forcing brand owners to split procurement across multiple qualified suppliers rather than consolidating with single vendors.
Growth Catalysts
- Drug Supply Chain Security Act:FDA track-and-trace requirements mandate multi-layer labels with embedded verification features, expanding substrate specifications for US pharmaceutical packaging.
- Biologics cold-chain expansion:Temperature-sensitive therapeutics require resealable booklet constructions that preserve dosage integrity across repeated freezer access cycles.
- Germany's pharmaceutical corridor:Concentrated packaging demand in Baden-Württemberg and Bavaria sustains specialized converter capacity for high-compliance European orders.
Market Restraints
- Specialized adhesive volatility:Acrylic and silicone pressure-sensitive formulations face input cost swings from petrochemical feedstock markets, compressing converter margins on fixed-price contracts.
- Rotary die-cutting equipment concentration:Precision finishing machinery suppliers cluster in Southern Germany and Northern Italy, creating geographic supply risk for converters outside these zones.
- Digital print speed limitations:Inkjet web speeds lag flexographic throughput by 40-60% for long-run pharmaceutical orders, constraining SKU proliferation economics.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO alignment with WHO prequalification standards creates demand for serialization-ready booklet labels among generic drug manufacturers targeting regulated markets.
- Combination product labeling:Drug-device convergence under EU MDR Article 117 requires integrated instructions-for-use constructions spanning pharmaceutical and medical device regulatory frameworks.
- Direct-to-pharmacy distribution:Hospital and retail pharmacy consolidation in France and the UK is compressing channel layers, opening converter-direct relationships bypassing traditional wholesale label procurement.
Industry Challenges
- Serialization verification engineering:Converters lack sufficient optical character recognition and machine vision talent to validate 2D Data Matrix codes at production line speeds.
- Multi-site quality system synchronization:Brand owners demand identical audit protocols across converter networks, forcing mid-cap suppliers to replicate ISO 15378 documentation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Booklet Labels Market |
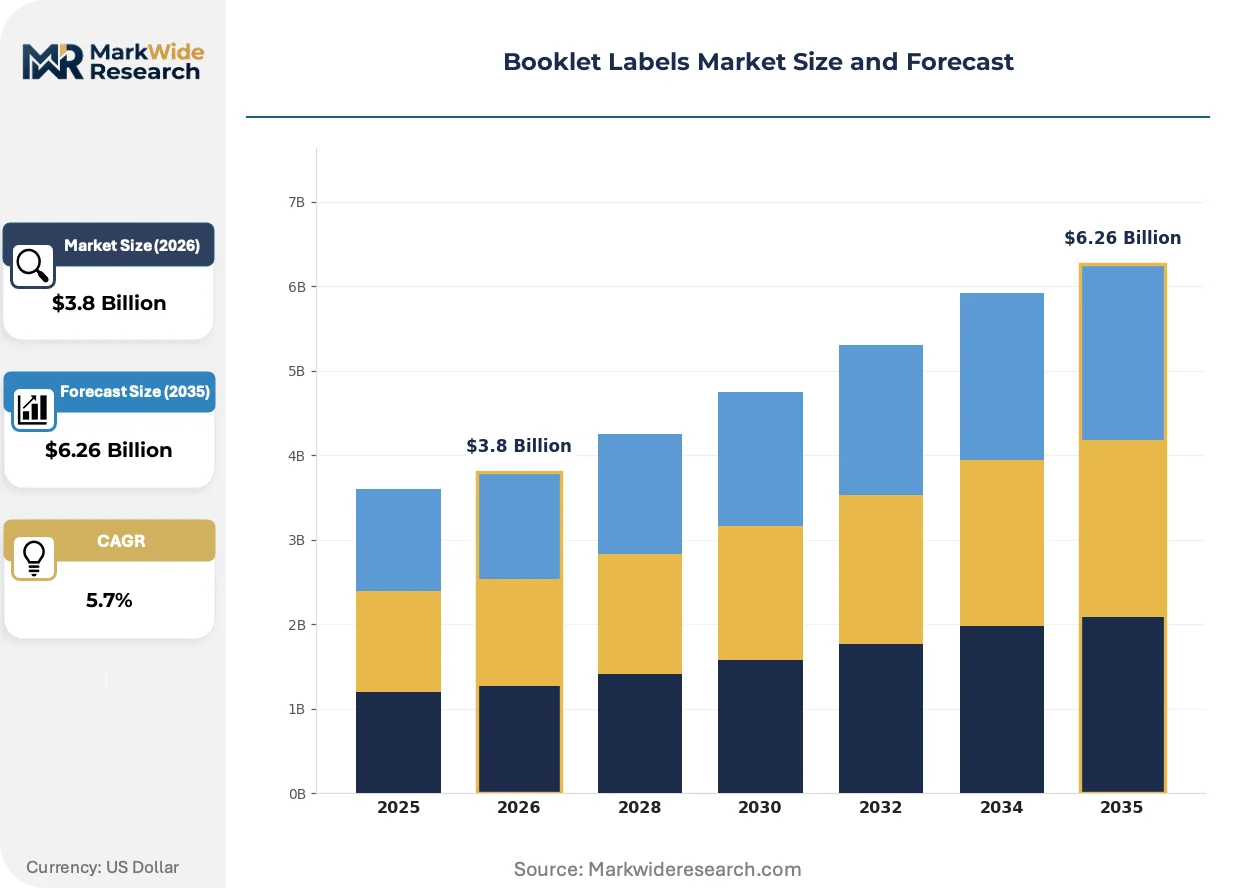
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive, Thermal Transfer, Direct Thermal, In-mold Material: Paper, Vinyl, Polyester, Polypropylene Application: Food & Beverage, Pharmaceuticals, Retail, Consumer Goods Print Technology: Flexographic, Digital, Lithographic, Screen Printing |
| Companies Covered | CCL Industries Inc., Multi-Color Corporation, Avery Dennison Corporation, Schreiner Group, Consolidated Label Company, Denny Bros Ltd., Resource Label Group, LLC, Faubel & Co. Nachfolger GmbH, JH Bertrand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Booklet Labels Market Strategic Shifts
Digital production workflows are compressing minimum order quantities and accelerating regional SKU proliferation, while regulatory divergence between FDA and EMA timelines is fragmenting converter certification requirements across Atlantic supply chains.
HP Indigo and Xeikon electrophotographic presses are digitizing pharmaceutical label production by enabling economical runs below 5,000 units. Regional brand managers at mid-cap drug manufacturers are adopting these systems for clinical trial packaging and market-specific language variants. This technology is digitizing order economics previously dominated by flexographic setup costs, enabling just-in-time inventory models that reduce obsolescence risk for short-lifecycle therapies.
EMA's Falsified Medicines Directive Delegated Regulation mandates unique identifier verification across all prescription medicines, with enforcement timelines staggered by product category. European converters must upgrade thermal transfer and laser marking capabilities to meet authentication standards. Small-molecule generics manufacturers in Italy and Spain face compressed compliance windows, driving accelerated capital deployment into verification infrastructure ahead of 2025 deadlines.
Hospital procurement consortia in France and the Netherlands are consolidating label specifications across therapeutic categories, displacing brand-specific constructions with standardized multi-page formats. This concentration forces converters to absorb design costs across larger contract volumes while sacrificing premium pricing for customized constructions. Generic injectable suppliers face the steepest margin compression as GPOs impose uniform labeling requirements across competing products.
Booklet Labels Market Segmentation
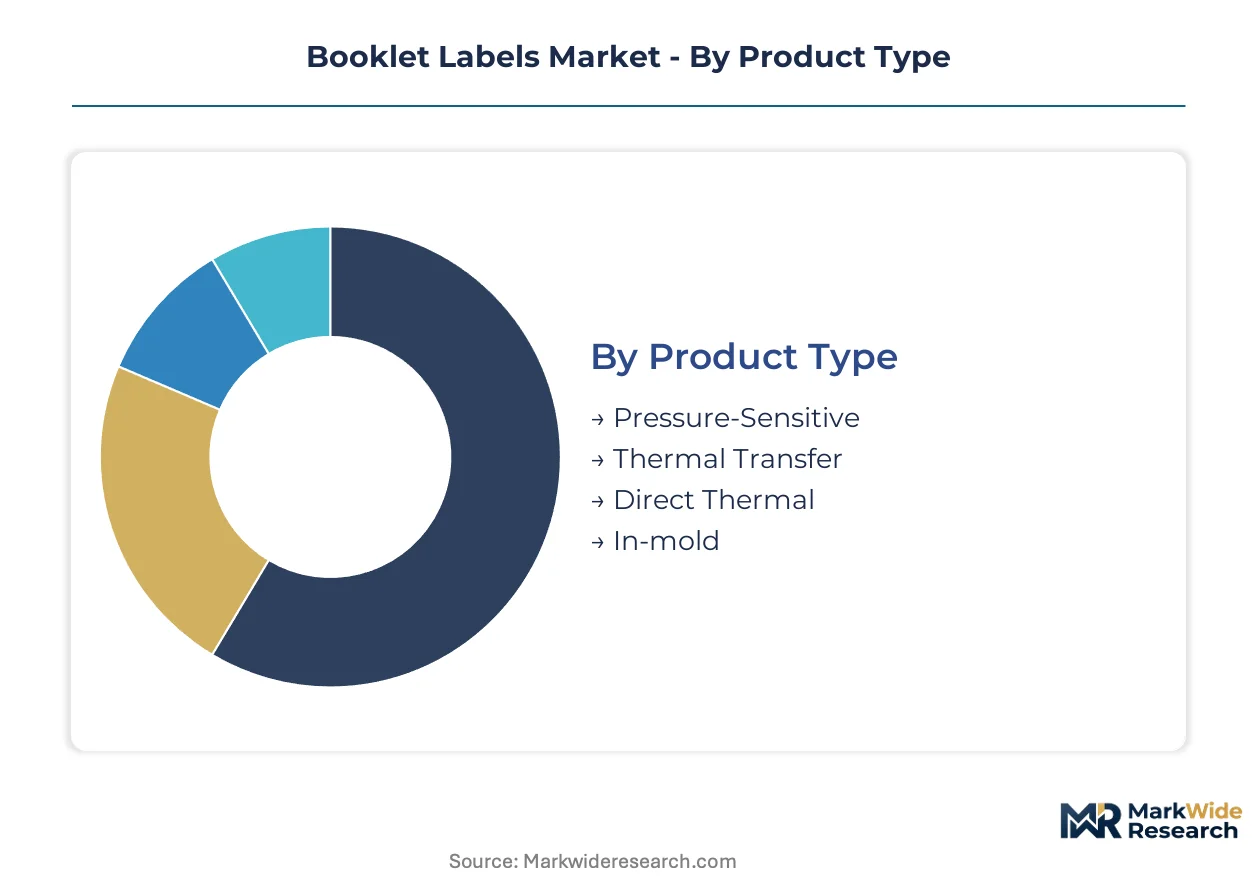
Booklet label procurement splits across substrate durability requirements and regulatory compliance tiers. Converter specialization concentrates in high-serialization segments where certification barriers filter supply capacity.
Product Type:
After-sales service intensity varies sharply across adhesive technologies, with resealable constructions demanding field support for dispenser calibration and failure analysis.
- Pressure-Sensitive:Acrylic or silicone adhesive layers enable clean removal and reapplication across repeated pharmaceutical package openings. Pharmaceutical contract packagers in Germany's Baden-Württemberg corridor specify these formats for biologics cold-chain compliance.
- Thermal Transfer:Wax-resin or resin ribbons transfer ink onto synthetic substrates for barcode durability against chemical exposure and abrasion. Industrial logistics operators in France specify these for warehouse track-and-trace reliability.
- Direct Thermal:Heat-sensitive coatings darken without ribbon consumption, suicing short-lifecycle retail promotions with limited environmental exposure.
- In-mold:Labels fuse with injection-molded containers during forming, serving durable consumer goods where decoration permanence outweighs resealability needs.
By volume, Pressure-Sensitive leads. By growth pace, Thermal Transfer is ahead.
Material:
Cost tier stratification separates commodity paper from performance synthetics, with converter margin profiles diverging across material handling complexity.
- Paper:Cellulosic substrates dominate food and beverage applications where moisture barriers and cost minimization outweigh durability demands. Italian wine exporters specify these for regulatory back-label compliance.
- Polyester:PET films deliver dimensional stability and chemical resistance for pharmaceutical serialization where substrate integrity protects embedded verification codes. Spanish generic manufacturers favor these for EMA Falsified Medicines Directive alignment.
- Vinyl:PVC constructions flex around curved container geometries in personal care segments.
- Polypropylene:Biaxially oriented PP balances moisture resistance with tear strength for refrigerated retail goods.
Polyester commands premium pricing. Polypropylene expands most quickly in emerging market exports.
Application:
Customer type fragmentation distinguishes regulated pharmaceutical procurement from specification-flexible retail segments, with certification requirements filtering converter participation.
- Pharmaceuticals:Multi-page constructions accommodate dense regulatory text, dosage instructions, and serialization codes within constrained primary packaging. FDA Drug Supply Chain Security Act mandates are compressing converter certification timelines across US generic manufacturers.
- Food & Beverage:Nutritional disclosure and multilingual ingredient listings drive fold-out formats for export-oriented processors. German organic food exporters specify these for EU multilingual labeling compliance.
- Retail:Promotional booklet labels attach to shelf-edge displays and product samples.
- Consumer Goods:Extended content supports warranty registration and loyalty program enrollment for electronics and appliances.
Pharmaceuticals absorb the highest certification overhead. Food & Beverage offers the broadest addressable base.
Print Technology:
Supply concentration in Southern Germany and Northern Italy for precision finishing equipment shapes regional technology adoption patterns.
- Digital:Electrophotographic and inkjet systems enable economical runs below 5,000 units, compressing minimum order quantities for clinical trial packaging and regional SKU proliferation. Mid-cap drug manufacturers in the Netherlands adopt these for just-in-time inventory models.
- Flexographic:Rotary letterpress analog systems sustain cost efficiency for long-run pharmaceutical orders where inkjet web speeds lag by 40-60%.
- Lithographic:Offset platforms serve high-volume consumer goods with premium graphic reproduction.
- Screen Printing:Thick ink deposits deliver opacity and durability for industrial safety labels and outdoor applications.
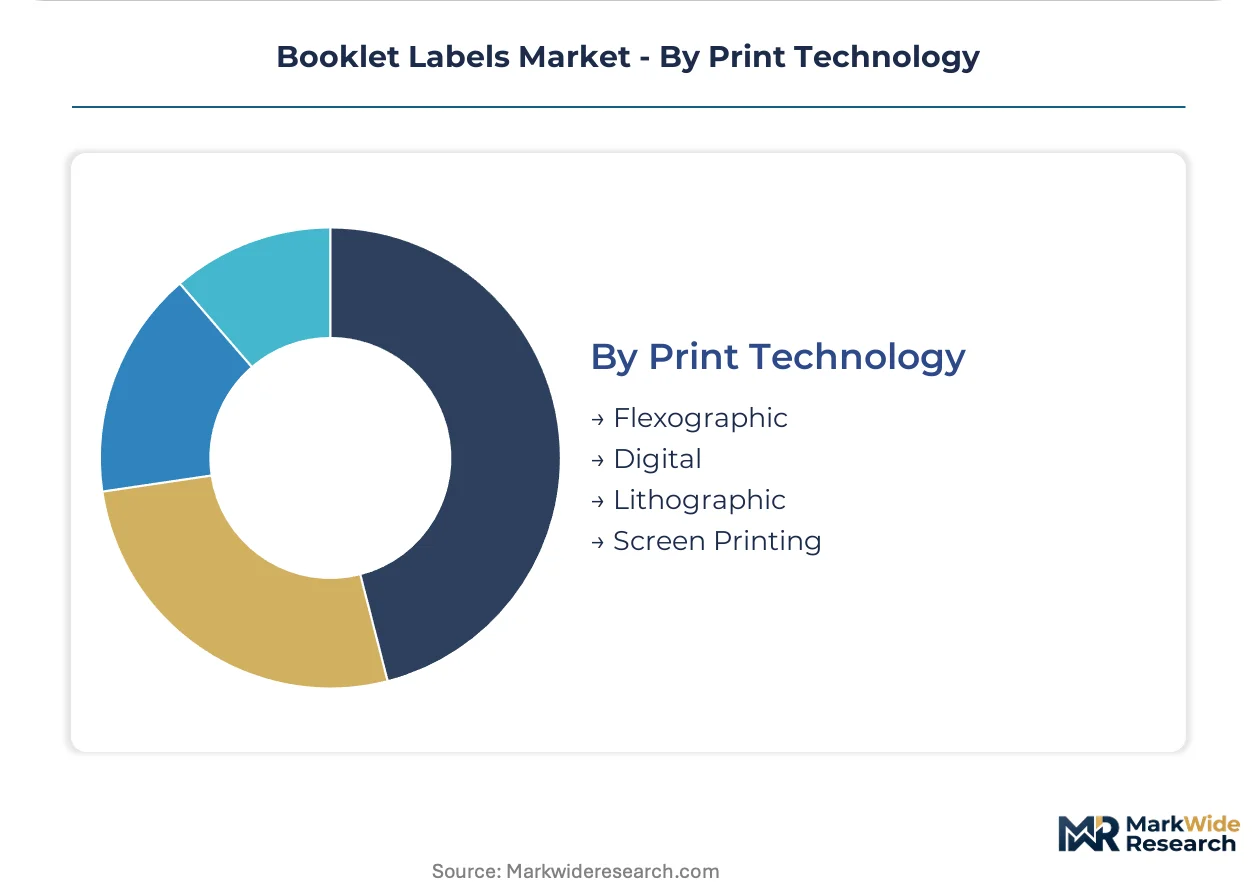
Flexographic retains volume leadership. Digital gains share fastest in serialization-ready short runs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in pharmaceutical packaging logistics, connecting converter clusters in Southern Germany to distribution hubs across the continent.
United States
FDA Drug Supply Chain Security Act enforcement is compressing converter certification timelines for generic drug manufacturers. Serialization-ready label demand concentrates around New Jersey's pharmaceutical packaging corridor and Puerto Rico's tax-advantaged manufacturing zone. Cold-chain biologics expansion is driving resealable construction specifications across Massachusetts and North Carolina clusters.
Germany
EMA Falsified Medicines Directive compliance deadlines are accelerating capital deployment into verification infrastructure. Baden-Württemberg's precision engineering ecosystem hosts specialized rotary die-cutting equipment suppliers serving European medical device labeling. Bavaria's pharmaceutical packaging corridor sustains concentrated demand for high-compliance multi-page constructions.
India
CDSCO alignment with WHO prequalification standards is creating export-oriented demand for serialization-ready booklet labels among generic drug manufacturers. Gujarat's pharmaceutical formulation belt and Hyderabad's vaccine production cluster are driving substrate specification upgrades. Government production-linked incentive schemes are expanding domestic converter capacity for regulated market exports.
France
Hospital procurement consortia consolidation is displacing brand-specific label constructions with standardized multi-page formats across Île-de-France and Auvergne-Rhône-Alpes. ANSM pharmacovigilance requirements are expanding printable surface area mandates for dense regulatory text. Direct-to-pharmacy distribution channel compression is opening converter-direct relationships bypassing traditional wholesale procurement layers.
Italy
Small-molecule generics manufacturers in Lombardy and Emilia-Romagna face compressed EMA compliance windows ahead of 2025 enforcement deadlines. Wine export regulatory back-label requirements are sustaining paper-based booklet demand among Veneto and Piedmont processors. Northern Italy's precision finishing machinery suppliers are creating geographic supply risk concentration for converters outside these zones.
Booklet Labels Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated substrate producers and specialized precision finishers, with mid-cap converters facing certification barriers that filter participation in high-serialization segments. Three archetypes dominate: integrated material-to-label suppliers controlling substrate production and finishing, precision die-cutting specialists serving medical device applications, and regional contract packagers leveraging geographic proximity to pharmaceutical clusters. Competitive moves center on backward integration into adhesive formulation and strategic partnerships with digital press manufacturers to compress minimum order quantities.
Among North American integrated suppliers, CCL Industries Inc. and Avery Dennison Corporation exemplify the material-to-label archetype, with the former representing vertical control across substrate production and the latter anchoring specialized adhesive portfolios for cold-chain applications. Schreiner Group occupies a position within the European precision specialist tier. These three entities collectively illustrate how geographic certification density and substrate control differentiate competitive positioning across Atlantic supply chains.
| Leading Market Players |
|---|
| CCL Industries Inc. |
| Multi-Color Corporation |
| Avery Dennison Corporation |
| Schreiner Group |
| Consolidated Label Company |
| Denny Bros Ltd. |
| Resource Label Group, LLC |
| Faubel & Co. Nachfolger GmbH |
| JH Bertrand Inc. |
| Others |
Value Chain & Pricing Dynamics
Rotary die-cutting equipment suppliers cluster in Southern Germany and Northern Italy, anchoring margin pools with precision finishing converters serving pharmaceutical serialization mandates. Acrylic and silicone adhesive formulations face petrochemical feedstock volatility, compressing converter margins on fixed-price contracts with brand owners.
Pricing Analysis
Volume-discount tiering separates ISO 15378-certified converters from uncertified competitors, with pharmaceutical contract packagers commanding standard-tier rates for serialization-ready orders. Price differentiation rests on certification grade and cold-chain adhesive performance, with resealable biologics constructions capturing premium positioning. Cost compression in the standard tier intensifies as hospital procurement consortia impose uniform specifications across competing generic injectables. Food and beverage processors exhibit highest price sensitivity, while biologics manufacturers prioritize adhesive reliability over unit economics.
Supply Chain Analysis
Export-control regimes on precision laser marking and optical verification equipment limit flows from Germany and Japan to emerging-market converters, constraining verification infrastructure deployment. Supply concentrates in Germany, Italy, and the United States for rotary die-cutting and folding machinery. Raw material dependencies span petrochemical-derived adhesives, biaxially oriented polypropylene films, and thermal transfer ribbons. Single-source vulnerability runs through Southern German equipment suppliers for pharmaceutical-grade finishing lines. Distribution runs through pharmaceutical contract packagers in Baden-Württemberg and Bavaria, with direct-to-pharmacy channels emerging in France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters lacking optical character recognition engineering talent face exclusion from high-serialization segments, creating a capability moat for certified suppliers with machine vision infrastructure.
For Market Incumbents: Build certification moats through ISO 15378 multi-site quality system synchronization, replicating audit protocols across converter networks to defend against mid-cap suppliers capturing fragmented pharmaceutical orders. Prioritize backward integration into adhesive formulation to buffer petrochemical feedstock volatility. Anchor capacity in Germany's pharmaceutical corridor to maintain proximity to EMA compliance deadlines. For New Entrants and Emerging Players: India's CDSCO-aligned export belt offers underpenetrated demand for serialization-ready booklet labels among generic drug manufacturers targeting WHO prequalification. Target Gujarat's formulation cluster and Hyderabad's vaccine production hub with digital press partnerships enabling sub-5,000-unit clinical trial runs. Partner with regional contract packagers to bypass established converter-direct relationships in regulated markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision die-cutting specialists lacking pharmaceutical certification infrastructure. Five-to-ten year viability favors converters with verified cold-chain adhesive portfolios and digital production workflows compressing minimum order quantities. Watch EMA-FDA regulatory divergence timelines as inflection indicators for verification infrastructure deployment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | ISO 15378 multi-site synchronization opens EMA-compliant pharmaceutical orders for mid-cap converters. |
| Digital Press Partnership | HP Indigo and Xeikon alliances enable economical sub-5,000-unit runs for clinical trial packaging. |
| Adhesive Formulation Backward Integration | In-house acrylic and silicone production buffers petrochemical feedstock cost volatility. |
| Cold-Chain Construction Development | Resealable biologics formats capture premium pricing from Massachusetts and North Carolina clusters. |
| Direct-to-Pharmacy Channel Development | Converter-direct relationships in France bypass wholesale procurement layers compressed by hospital consolidation. |
Study Parameters
The analysis maps pressure-sensitive, thermal transfer, direct thermal, and in-mold constructions, each validated through converter operations managers, pharmaceutical contract packaging procurement leads, brand owner regulatory affairs directors, and precision finishing equipment suppliers. Primary interviews with these stakeholders combined with secondary validation from FDA Drug Supply Chain Security Act filings, EMA Falsified Medicines Directive delegated regulations, CDSCO export guidance documents, and customs trade data. Bottom-up volume estimates triangulated against top-down market sizing across substrate, adhesive, and print technology tiers.
Assumptions held pharmaceutical serialization enforcement timelines and petrochemical feedstock pricing patterns within observed ranges across the analysis window. Segmentation dimensions modeled include adhesive technology, substrate material durability tier, application regulatory cluster, and print production format. CAGRs derived from segment-level volume trajectories weighted by certification overhead and SKU proliferation rates. Industry-specific inputs incorporated thermal transfer ribbon consumption patterns and digital press adoption curves among mid-cap drug manufacturers.
The forecast holds incumbent behavior within observed patterns; aggressive certification investments by uncertified converters would shift outcomes toward price compression in the standard tier. Material shifts in EMA-FDA regulatory divergence timelines or petrochemical feedstock volatility spikes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Sustainable Labels Market
Labels
Non-Adhesive Tags Market
Labels
Global QR Code Labels Market
Labels
Tags Market
Labels
Global Sensormatic Labels Market
Labels
Ripeness Indicator Labels Market
Labels
GCC Labeling Market
Labels
Pre-Gummed Labels Market
Labels
Self-Adhesive Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Sheeted Labels Market
Labels
North America Self-Adhesive Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Indicative Seals Market
Labels
Laser Markable Labels Market
Labels
Shipping Label Market