
 Warning Labels and Stickers Market | 2026-2036
Warning Labels and Stickers Market Size, Share, and Industry Trends Forecast 2026-2036
Warning Labels and Stickers Market Analysis
The gap between premium and commodity tiers is expanding in concrete terms. Avery Dennison Corporation leverages its materials science portfolio to dominate high-performance adhesive segments with thermal stability specifications. Brady Corporation anchors its position through specialized industrial safety labels that sustain compliance-driven replacement cycles in hazardous environments. 3M competes across both tiers, extending its geographic reach through channel control in North American and Asian industrial corridors.
Warning labels and stickers comprise printed or digitally rendered substrates—polypropylene, polyester, paper, or PVC—engineered with pressure-sensitive adhesives or mechanical fasteners to convey hazard classification, handling instructions, or regulatory certification. Their primary industrial purpose centers on OSHA-mandated hazard communication, GHS chemical classification, and supply-chain traceability through barcode or RFID integration. Adhesive labels lead volume consumption due to universal applicability across manufacturing and logistics, while vinyl stickers capture margin pools in outdoor automotive and heavy equipment applications where UV resistance and substrate flexibility command pricing premiums. Medical use represents the fastest-growing application segment as FDA Unique Device Identification and EU MDR serialization requirements multiply label complexity per unit.
OSHA hazard communication standards, FDA Unique Device Identification rules, and EU MDR labeling requirements collectively shape product specifications, testing protocols, and market access conditions across the industry's major demand centers. REACH substance restrictions and California Proposition 65 disclosure mandates further constrain material selection and ink chemistry for suppliers serving cross-border end users. Stakeholders must monitor evolving serialization granularity requirements and substrate sustainability certifications as procurement criteria harden in pharmaceutical and food-contact applications.
Market Dynamics
Serialization mandates from FDA and EU MDR are compressing label replacement cycles while forcing substrate upgrades for thermal transfer and laser-marking compatibility across pharmaceutical and medical device supply chains.
Growth Catalysts
- EU MDR serialization:Medical device manufacturers in Germany and France must deploy unit-level traceability labels, expanding demand for polyester and polyimide substrates with 10-year archival durability.
- GHS chemical classification:OSHA-mandated hazard communication drives replacement demand in US chemical manufacturing, with pictogram-heavy labels requiring fade-resistant inks and synthetic facestocks.
- Thermal transfer ribbons:Automotive OEMs in Stuttgart and Wolfsburg specify resin-enhanced ribbon formulations for under-hood applications where engine bay temperatures exceed 150°C.
Market Restraints
- Petrochemical volatility:Polypropylene and polyester resin prices fluctuate with crude oil benchmarks, squeezing margin on commodity-grade pressure-sensitive labels.
- Adhesive supply concentration:Acrylic and rubber-based adhesive production clusters in Germany and the US, creating geographic vulnerability for Asian label converters.
- Silicone release liner shortage:Glassine and PET liner availability constrains high-speed die-cutting throughput for pharmaceutical serialization contracts.
Strategic Opportunities
- India pharmaceutical exports:CDSCO serialization requirements for export-bound generics create demand for tamper-evident labels with integrated holographic features.
- RFID-NFC convergence:Medical device manufacturers combine passive RFID inlays with printed antennas for real-time supply chain visibility beyond barcode scanning.
- E-commerce hazardous goods:Amazon and third-party logistics providers require lithium battery warning labels meeting IATA and DOT specifications for air and ground transport.
Industry Challenges
- Color management for GHS:Precise Pantone matching for red diamond pictograms demands spectrophotometer calibration and ink formulation expertise that converters struggle to staff.
- Legacy ERP integration:Pharmaceutical label orders must flow into SAP and Oracle systems with batch-level traceability, requiring middleware development that extends implementation timelines.
Report Scope
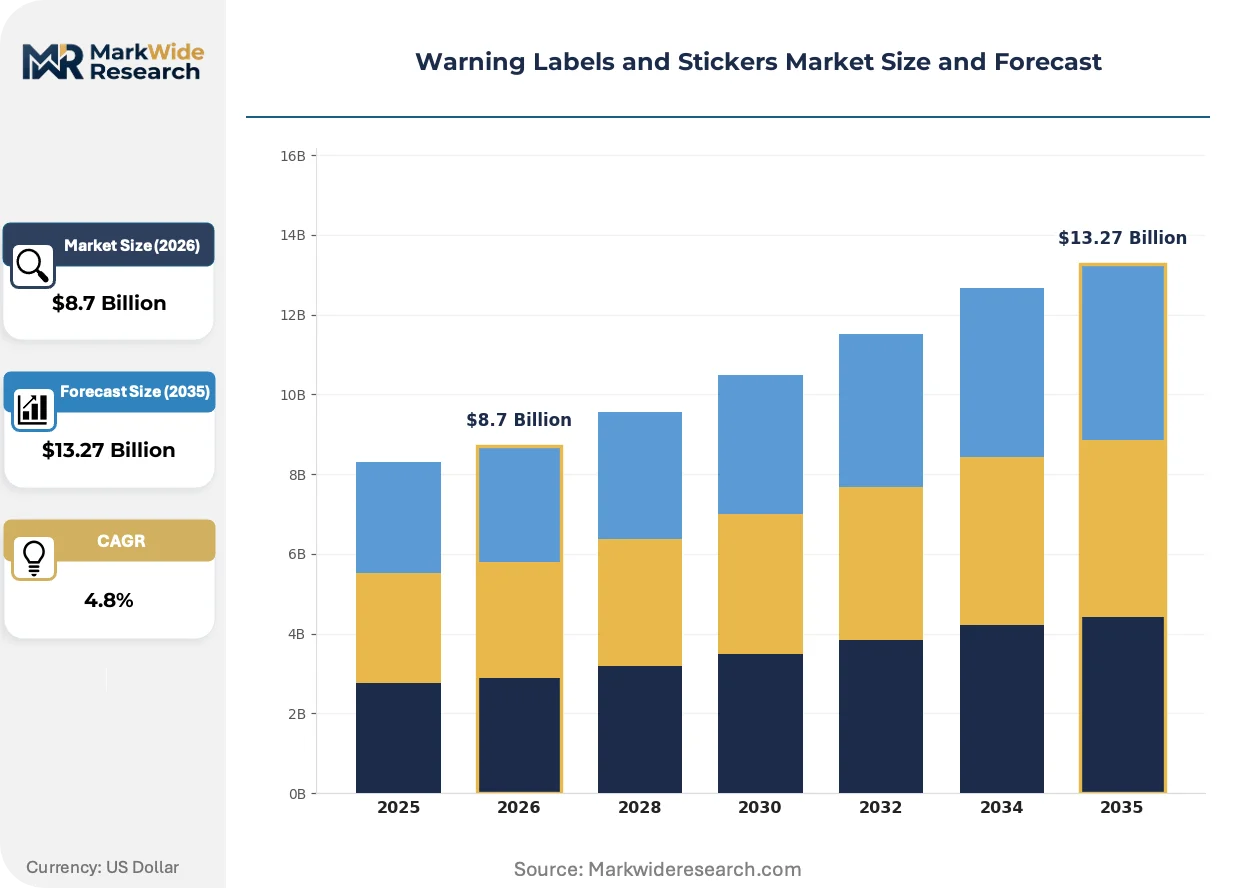
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warning Labels and Stickers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Labels, Vinyl Stickers, Paper Labels, Safety Tags Material: Polypropylene, Polyester, Paper, PVC Application: Industrial Use, Household Use, Automotive Use, Medical Use End User: Manufacturers, Retailers, Hospitals, Transportation |
| Companies Covered | Avery Dennison Corporation, 3M, Brady Corporation, CCL Industries, MaverickLabel.Com, Inc., Multi-Color Corporation, Advanced Labels, Edwards Label, Mercian Labels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warning Labels and Stickers Market Emerging Trajectories
Digital printing and smart labeling technologies are collapsing minimum order quantities while embedding authentication features directly into substrate layers, reshaping how converters compete on speed versus scale.
Laser-markable polyimide films are integrating into orthopedic implant packaging where FDA Unique Device Identification requires permanent, solvent-resistant marking that survives sterilization cycles. Device manufacturers in Warsaw and Minneapolis specify these substrates for knee and hip replacement kits. The technology is integrating permanent marking capability that eliminates ribbon inventory and reduces label SKU complexity for contract manufacturers.
EU MDR Article 10 and Annex I labeling requirements mandate that device labels remain legible throughout the stated lifetime, driving adoption of UV-cured screen printing over thermal transfer in cardiovascular and neurological device packaging. German notified bodies enforce accelerated aging tests per ISO 11607. Sterile barrier manufacturers in Tuttlingen and Freiburg im Breisgau now specify 100% inspection for print contrast and barcode grade.
Automotive OEMs now bundle label specification authority with tier-one electronics suppliers rather than sourcing directly, compressing the buying center and privileging converters with IATF 16949 certification and VDA 6.3 process audits. This procurement consolidation favors specialists in Ingolstadt and Munich with captive design-for-manufacturing capabilities. The shift is most visible in electric vehicle battery warning labels requiring flame-retardant polycarbonate substrates and Chinese GB/T compliance for export models.
Warning Labels and Stickers Market Segmentation
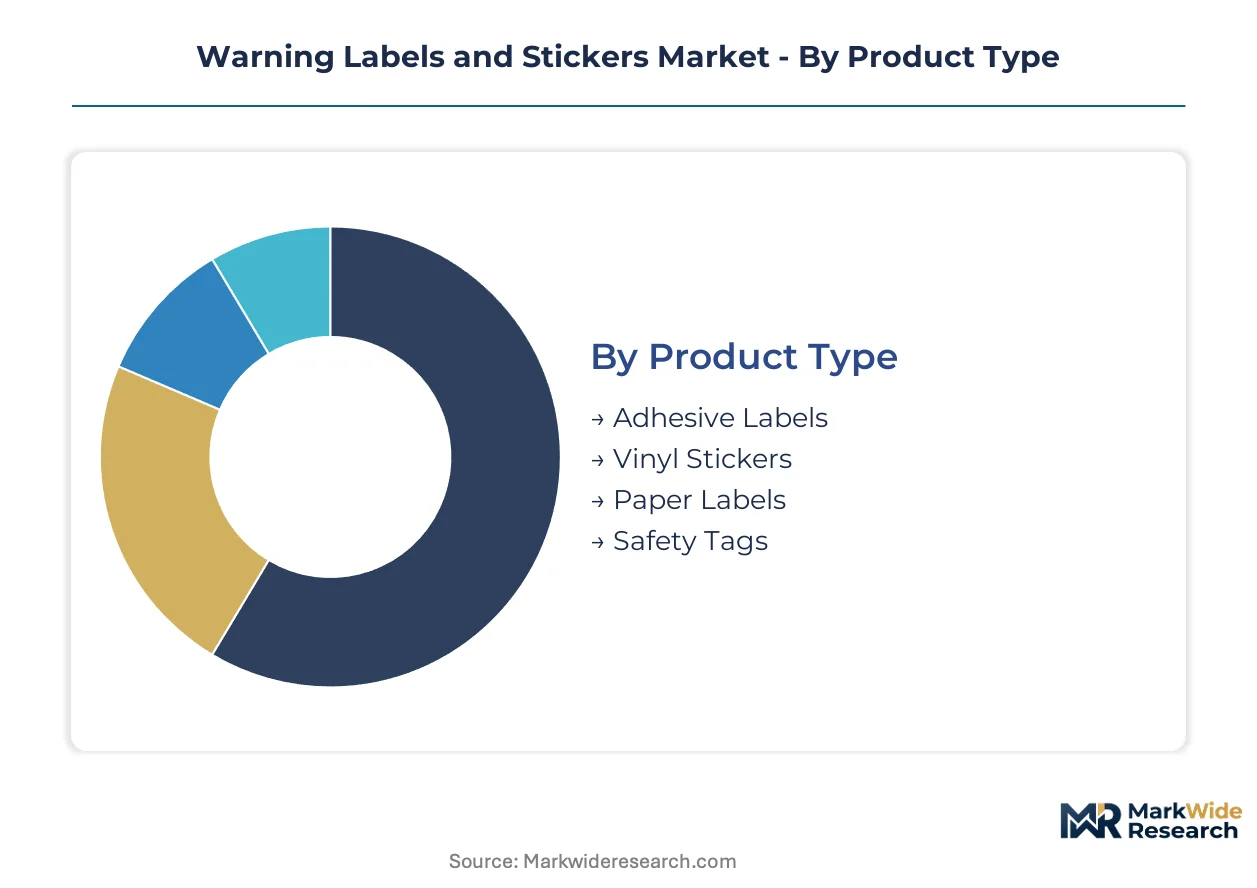
Warning labels and stickers fragment across four dimensions that determine specification depth, regulatory burden, and margin capture. Product type and material selection drive unit economics, while application and end-user concentration shape procurement authority and replacement cadence.
Product Type:
Standalone adhesive formats dominate high-volume manufacturing lines, while embedded safety tags integrate into asset-tracking systems requiring serialization compliance.
- Adhesive Labels:Pressure-sensitive constructions using acrylic or rubber-based adhesives bond to corrugated, metal, and plastic substrates across chemical manufacturing and logistics operations. German automotive OEMs in Stuttgart specify thermal-transfer-compatible facestocks for under-hood applications where engine bay temperatures exceed 150°C, driving resin-enhanced ribbon procurement.
- Vinyl Stickers:Calendered or cast PVC films with UV-stabilized inks sustain outdoor exposure in heavy equipment and fleet vehicle applications. Marine and construction equipment manufacturers in Hamburg and Rotterdam prioritize vinyl for salt spray resistance and substrate flexibility on curved surfaces.
- Paper Labels:Direct thermal and thermal transfer grades serve short-lifecycle consumer goods and shipping documentation where cost minimization outweighs durability requirements.
- Safety Tags:Cardstock or synthetic constructions with metal grommets attach to valves, scaffolding, and lockout points in OSHA-regulated industrial environments.
Adhesive labels lead volumes today; vinyl stickers are gaining share fastest.
Material:
Substrate selection locks in performance tier and regulatory compliance path, with synthetic films commanding premium positioning over cellulosic alternatives.
- Polypropylene:Biaxially oriented films deliver moisture resistance and dimensional stability at mid-tier price points, capturing food contact and chemical drum labeling in US and European manufacturing corridors.
- Polyester:PET films with archival-grade adhesives satisfy FDA Unique Device Identification and EU MDR durability mandates for pharmaceutical and medical device serialization. Warsaw and Minneapolis orthopedic implant manufacturers specify laser-markable polyimide variants for sterilization-survivable permanent marking.
- Paper:Uncoated and coated wood pulp grades dominate e-commerce shipping labels and retail price marking where single-use economics prevail.
- PVC:Rigid and flexible vinyl formulations serve flame-retardant electric vehicle battery warning labels requiring Chinese GB/T compliance for export-bound production.
Polypropylene anchors volume consumption; polyester climbs the fastest on medical serialization demand.
Application:
Use-case severity determines adhesive specification, print durability requirements, and inspection protocols across industrial, consumer, and regulated environments.
- Industrial Use:GHS chemical classification labels with fade-resistant inks and synthetic facestocks sustain OSHA-mandated hazard communication in US chemical manufacturing, with pictogram-heavy formats driving replacement cycles.
- Medical Use:Unit-level traceability labels with 10-year archival durability meet EU MDR Article 10 legibility requirements through stated device lifetime. German notified bodies enforce accelerated aging tests per ISO 11607, compelling UV-cured screen printing adoption over thermal transfer in Tuttlingen and Freiburg im Breisgau sterile barrier operations.
- Automotive Use:IATF 16949-certified converters supply tier-one electronics suppliers with flame-retardant polycarbonate substrates for electric vehicle battery warnings, with procurement authority consolidating at Ingolstadt and Munich design-for-manufacturing specialists.
- Household Use:Appliance safety markings and consumer product warnings on paper and film substrates face less stringent durability requirements but must satisfy California Proposition 65 disclosure mandates for cross-border commerce.
Industrial use holds the largest installed base; medical use shows the steepest expansion trajectory.
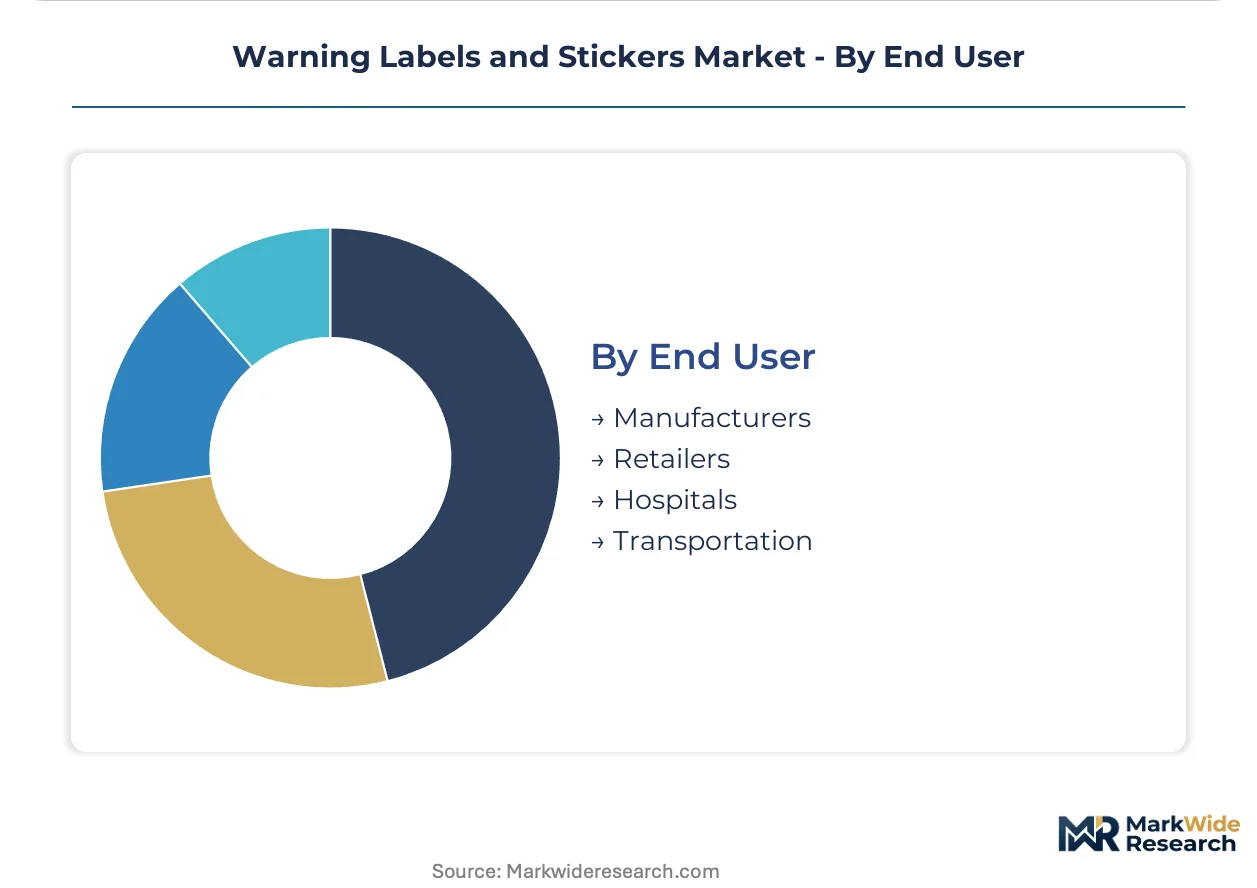
End User:
Procurement sophistication varies sharply, with regulated manufacturers driving specification complexity while retail and logistics prioritize unit cost and availability.
- Manufacturers:Chemical, pharmaceutical, and automotive producers embed label specifications into supplier quality agreements, requiring batch-level traceability and SAP or Oracle ERP integration that extends implementation timelines.
- Hospitals:Sterile processing departments and supply chain operations demand FDA UDI-compliant labels with integrated RFID-NFC convergence for real-time inventory visibility beyond barcode scanning.
- Transportation:Third-party logistics providers and air cargo operators require lithium battery warning labels meeting IATA and DOT specifications for hazardous goods movement through Amazon and e-commerce distribution networks.
- Retailers:Private label and shelf-edge applications emphasize price competitiveness and rapid turnaround on short-run digital print orders.
Manufacturers command the deepest specification authority; hospitals are expanding procurement fastest on traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive chemists and print engineers concentrate in German industrial corridors, anchoring premium-grade safety label specification authority for automotive and pharmaceutical exporters.
United States
OSHA hazard communication enforcement drives GHS pictogram label replacement cycles across chemical manufacturing clusters in Texas and Louisiana. FDA Unique Device Identification rules mandate polyester substrates with 10-year archival durability for orthopedic implant packaging in Minneapolis and Warsaw medical device corridors.
Germany
EU MDR Article 10 serialization requirements compress replacement cycles for medical device manufacturers in Tuttlingen and Freiburg im Breisgau. Stuttgart and Wolfsburg automotive OEMs specify thermal-transfer-compatible facestocks for under-hood applications exceeding 150°C, driving resin-enhanced ribbon procurement from specialized converters.
China
Electric vehicle battery warning labels requiring GB/T compliance and flame-retardant polycarbonate substrates concentrate production in Yangtze River Delta manufacturing zones. NMPA serialization mandates for pharmaceutical exports tighten substrate specifications for domestic converters serving international generics manufacturers.
India
CDSCO serialization requirements for export-bound pharmaceuticals create demand for tamper-evident labels with holographic authentication features in Gujarat and Maharashtra pharmaceutical corridors. Mumbai and Ahmedabad contract manufacturers upgrade thermal transfer infrastructure to meet EU and US traceability standards.
Japan
METI industrial safety standards and PMDA device labeling rules sustain premium substrate demand for chemical and medical applications in Osaka and Nagoya manufacturing belts. Kansai-region converters specialize in polyimide films for sterilization-survivable permanent marking in orthopedic implant packaging.
Warning Labels and Stickers Market Vendor Landscape
Top-tier vendors anchor premium-performance segments, while mid-scale converters compete on regional certification and turnaround velocity. The vendor base stratifies across three tiers: multinational materials science conglomerates with captive adhesive development, specialized industrial safety label fabricators with hazardous-environment expertise, and regional digital print shops serving short-run compliance orders. Consolidation pressure intensifies as pharmaceutical serialization contracts demand ERP integration capabilities that smaller converters cannot staff. Capacity expansion and strategic partnerships represent the dominant competitive moves, with tier-one players securing IATF 16949 certification to access automotive procurement consolidation.
Among North American-based materials specialists, Avery Dennison Corporation occupies a position exemplifying premium-tier adhesive science integration, while 3M represents diversified industrial conglomerate participation across both commodity and performance segments. Brady Corporation anchors the specialized industrial safety archetype, with its positioning reflecting deep compliance-driven replacement cycle capture in OSHA-regulated environments. These three entities collectively illustrate how competitive positioning stratifies between materials science depth, regulatory specialization breadth, and channel control geography.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M |
| Brady Corporation |
| CCL Industries |
| MaverickLabel.Com, Inc. |
| Multi-Color Corporation |
| Advanced Labels |
| Edwards Label |
| Mercian Labels |
| Others |
Supply Flow & Price Mechanics
Specialized adhesive chemists and print engineers concentrated in German industrial corridors create labor-cost differentials that widen spreads between premium-certified and commodity-grade label tiers.
Pricing Analysis
Bundled design-for-manufacturing services separate premium converters from unbundled commodity suppliers competing on per-unit transactional pricing. Three-tier pricing structure across premium, standard, and economy levels hinges on certification grade and volume scale, with IATF 16949-certified specialists capturing margin premiums from Stuttgart automotive OEMs. Price erosion runs through commodity polypropylene labels as Asian converters expand thermal transfer capacity. Chemical manufacturers in US Gulf Coast clusters exhibit highest price sensitivity, while orthopedic implant packers in Minneapolis and Warsaw prioritize archival durability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical serialization returns create secondary demand channels for label verification and reprinting services. Raw material supply draws from Germany, the United States, and China for acrylic adhesives, polyester films, and silicone release liners respectively. Petrochemical volatility in polypropylene and polyester resin feeds margin compression across commodity-grade pressure-sensitive constructions. Distribution runs through specialized industrial distributors in North American and European manufacturing corridors, with direct OEM relationships consolidating procurement authority at tier-one automotive electronics suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through substrate upgrades for EU MDR serialization compliance, where premium-grade polyester and polyimide films command pricing premiums over commodity alternatives.
For Market Incumbents: Acquire laser-markable polyimide film production capabilities to capture orthopedic implant packaging demand from Warsaw and Minneapolis device manufacturers. Deepen backward integration into resin-enhanced thermal transfer ribbon formulations for automotive under-hood applications exceeding 150°C. Consolidate ERP integration expertise to defend pharmaceutical serialization contracts against mid-scale converters lacking SAP or Oracle middleware development capacity. For New Entrants and Emerging Players: Enter via CDSCO-compliant tamper-evident label production for Gujarat and Maharashtra pharmaceutical exporters serving EU and US generics markets. Target e-commerce hazardous goods logistics as the most penetrable segment, where Amazon and third-party providers require lithium battery warning labels meeting IATA and DOT specifications. Pursue digital print infrastructure for short-run compliance orders with rapid turnaround velocity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional converters lacking IATF 16949 certification or EU MDR serialization infrastructure. Long-term viability favors specialists with captive materials science capabilities and design-for-manufacturing relationships with German automotive OEMs. Monitor silicone release liner availability and glassine substrate pricing as early signals of capacity constraints affecting high-speed die-cutting throughput.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Captive acrylic and rubber-based formulation secures supply continuity for pharmaceutical serialization contracts. |
| ERP Middleware Development | SAP and Oracle integration capabilities extend implementation timelines but lock in manufacturer quality agreements. |
| Laser-Markable Substrate Capacity Addition | Polyimide film production captures orthopedic implant demand from FDA UDI-compliant Warsaw and Minneapolis corridors. |
| RFID-NFC Convergence Investment | Passive inlay integration with printed antennas enables real-time supply chain visibility beyond barcode scanning. |
| IATF 16949 Certification Pursuit | Automotive quality certification accesses procurement consolidation at Ingolstadt and Munich tier-one electronics suppliers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with label converters, adhesive chemists, pharmaceutical packaging engineers, and automotive tier-one procurement leads with secondary validation from FDA UDI guidance documents, EU MDR technical specifications, OSHA hazard communication standards, and customs trade data for pressure-sensitive materials. Bottom-up demand modeling across substrate types, adhesive chemistries, and end-use applications triangulated against top-down market sizing from industry association reports and SEC filings of listed materials specialists.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning product type, material substrate, application severity, and end-user procurement sophistication. CAGRs derived from trend extrapolation of serialization mandate adoption curves, thermal transfer infrastructure deployment rates, and automotive OEM specification authority consolidation patterns. Industry-specific forecast inputs incorporated EU MDR Article 10 implementation timelines and CDSCO export compliance deadlines for Indian pharmaceutical manufacturers.
The model holds under stable petrochemical feedstock pricing and continued regulatory enforcement of serialization mandates; deviation in crude oil volatility or delayed MDR compliance deadlines would shift replacement cycle assumptions. Practitioners should monitor silicone release liner supply availability and German notified body inspection protocol changes for early signals of substrate cost or certification timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Ripeness Indicator Labels Market
Labels
Repositionable Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Foil Labels Market
Labels
BOPP Labels Market
Labels
Wet Glue Labeling Machines Market
Labels
Holographic Labels Market
Labels
GCC Labels and Release Liners Market
Labels
Pressure Sensitive Labels Market
Labels
Shipping Label Market
Labels
Barcode Label Printer Market
Labels
Sustainable Labels Market
Labels
Pre-Gummed Labels Market
Labels
Global QR Code Labels Market
Labels
HAZMAT Labels Market