
 Freezer Label Market | 2026-2036
Freezer Label Market Size, Share, and Industry Trends Forecast 2026-2036
Freezer Label Market Foresight
The capital-intensity divergence between integrated film producers and narrow converters is rotating competitive dynamics across the freezer label supply base. Avery Dennison Corporation leverages captive adhesive polymerization to sustain margin control across extreme-temperature grades. CCL Industries Inc. anchors its position through multi-continent slitting and distribution infrastructure that dominates pharmaceutical cold-chain accounts. UPM Raflatac competes on renewable substrate certification, differentiating its offering for European food processors facing Scope 3 disclosure requirements.
Freezer labels are pressure-sensitive identification substrates engineered with specialized adhesives formulated to maintain tack integrity at temperatures reaching minus eighty degrees Celsius, typically constructed from coated papers or polymer films with acrylic or rubber-based adhesive systems designed for cryogenic and deep-freeze commercial environments. Synthetic labels lead volume contribution due to their dimensional stability under thermal cycling, while direct thermal technology captures expanding share in food processing plants seeking to eliminate ribbon inventory and simplify operational workflows. Pharmaceutical preservation applications command premium positioning as lot-level traceability mandates tighten across regulated cold chains.
The FDA enforces strict label legibility standards for pharmaceutical products stored under controlled temperatures, compelling converters to validate print durability across freeze-thaw cycles. REACH and the EU F-Gas Regulation jointly shape material selection and cold-storage infrastructure design, restricting certain adhesive chemistries while accelerating energy-efficient freezer deployment that demands compatible identification systems. Stakeholders must monitor evolving pharmacopeial traceability requirements and substrate recyclability mandates to align R&D pipelines with compliance trajectories.
Market Dynamics
The EU F-Gas Regulation is tightening cold-storage energy standards, forcing operators to upgrade freezer infrastructure and procure identification materials that withstand intensified thermal cycling. This regulatory pressure is compressing replacement cycles and elevating specification requirements across pharmaceutical and food processing supply chains.
Growth Catalysts
- Pharmaceutical Cold-Chain Expansion:Lot-level traceability mandates from the FDA and EMA are compelling vaccine distributors to deploy cryogenic-grade labels capable of maintaining legibility through minus eighty-degree Celsius storage and repeated freeze-thaw cycles.
- REACH Compliance:Restrictions on certain adhesive chemistries are accelerating R&D investment in acrylic systems that satisfy both adhesion performance and substance disclosure requirements for European food processors.
- Direct Thermal Adoption:Food processing plants are eliminating thermal transfer ribbons to simplify workflows, driving label demand for coated synthetic facestocks engineered for high-speed direct thermal printing in refrigerated environments.
Market Restraints
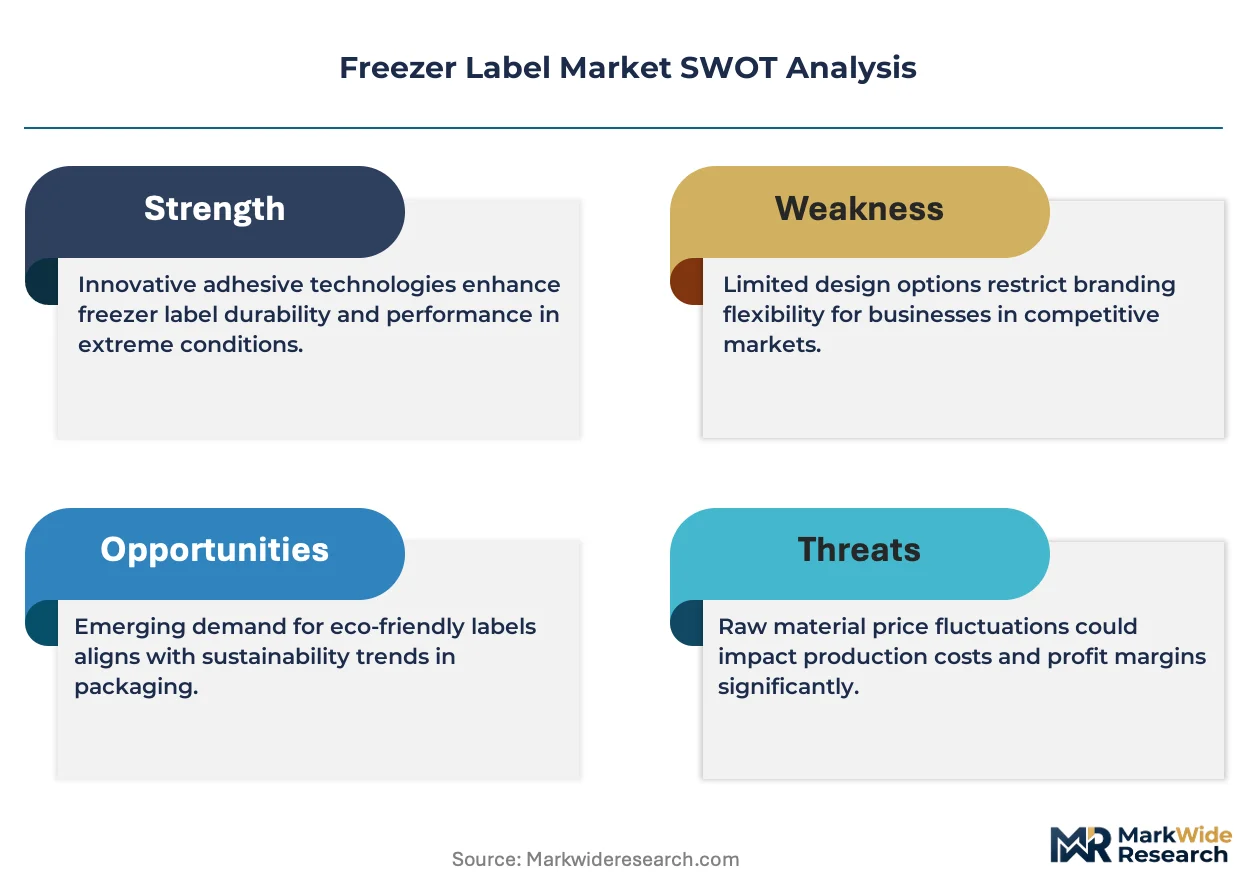
- Petrochemical Input Volatility:Acrylic adhesive polymerization depends on propylene and acrylic acid derivatives, exposing converters to margin compression when energy markets fluctuate.
- Specialized Substrate Concentration:Coated paper and film production for extreme-temperature grades clusters among integrated European and North American mills, creating geographic supply risk for Asia-Pacific converters.
- Silicone Release Liner Cost Structure:Glassine and PET liner substrates represent a fixed cost burden that narrow converters cannot backward integrate, limiting pricing flexibility in competitive tenders.
Strategic Opportunities
- Cell and Gene Therapy Logistics:Cryogenic preservation requirements for CAR-T therapies and mRNA platforms are creating demand for labels validated to liquid nitrogen temperatures, a specification tier with limited qualified suppliers.
- Renewable Substrate Certification:The EU Green Deal and CSRD disclosure requirements are positioning FSC-certified and bio-based film alternatives as premium offerings for Scope 3-conscious pharmaceutical distributors.
- Digital Print Integration:Hybrid inkjet and toner systems are enabling short-run customization for clinical trial materials, opening service revenue streams beyond commodity roll stock.
Industry Challenges
- Adhesion Chemistry Expertise Gap:Formulating pressure-sensitive adhesives for polar cryogenic environments requires polymer science capabilities that legacy label converters lack, forcing reliance on external adhesive suppliers.
- Multi-Jurisdiction Validation Timelines:Pharmaceutical customers require simultaneous FDA, EMA, and WHO-PQS certification for cold-chain labels, extending qualification cycles and freezing working capital.
- Legacy Print Infrastructure Compatibility:Direct thermal synthetic labels demand recalibrated printhead settings and modified platen rollers, creating implementation friction in established food processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezer Label Market |
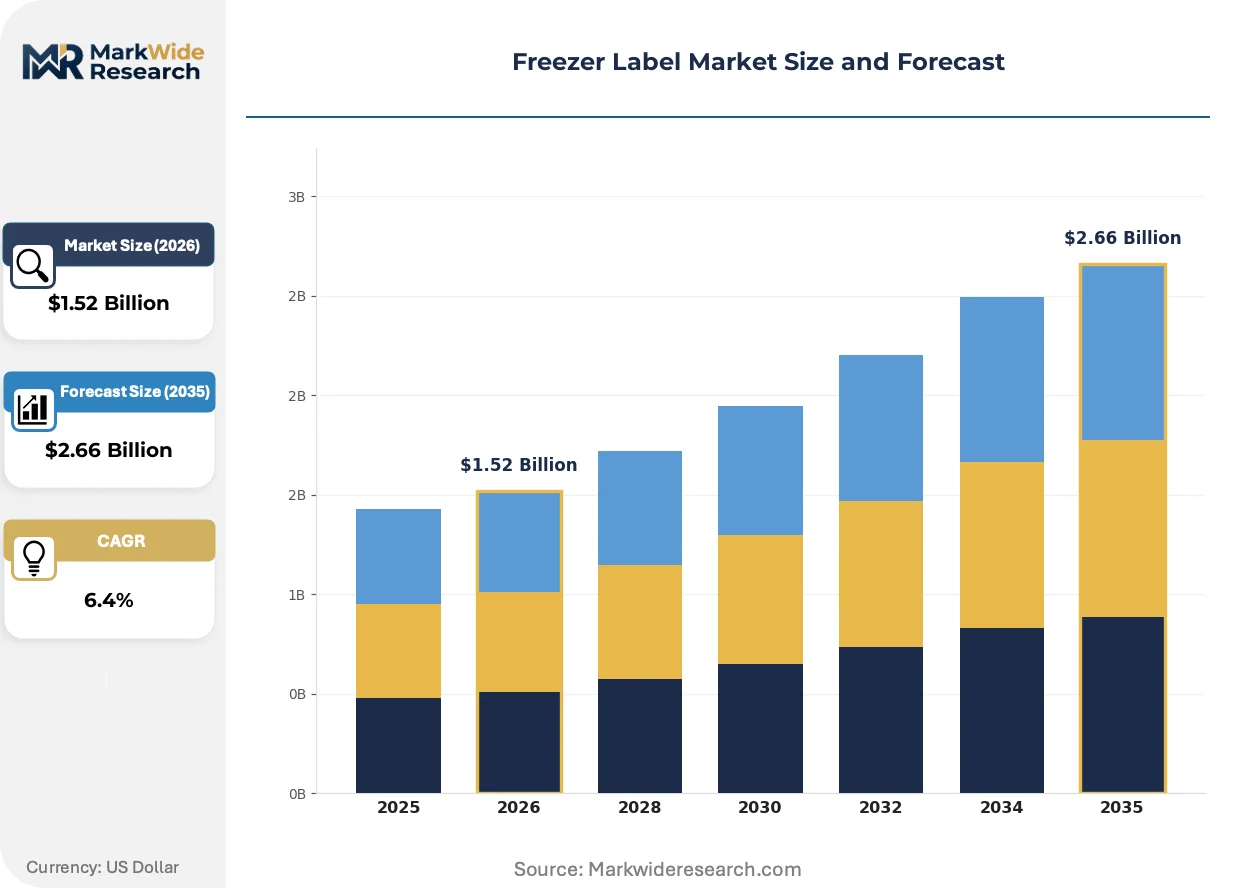
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $2.66 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Labels, Synthetic Labels, Polyester Labels, Polypropylene Labels, Vinyl Labels Technology: Thermal Transfer, Direct Thermal, Inkjet, Laser, Flexographic Application: Pharmaceutical Preservation, Food Packaging, Chemical Storage, Laboratory Sample Identification, Biotechnological Research End User: Hospitals, Food Processing Plants, Research Laboratories, Biotechnology Firms, Chemical Manufacturers |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., 3M Company, Brady Corporation, UPM Raflatac, LINTEC Corporation, Multi-Color Corporation, SATO Holdings Corporation, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezer Label Market Shifts & Advancements
Material science advances and regulatory disclosure requirements are converging to reshape specification standards across freezer label procurement. Three developments are compressing legacy product lifecycles and opening competitive differentiation paths.
Direct thermal synthetic facestocks are fragmenting the traditional thermal transfer installed base. Food processors operating multi-temperature distribution centers are adopting these materials to eliminate ribbon inventory management and reduce line changeover downtime. The technology is fragmenting converter revenue pools by shifting value from ribbon supplies toward specialized coating formulations.
The EU F-Gas Regulation is mandating energy-efficiency upgrades for commercial refrigeration equipment, which alters thermal cycling profiles and demands label adhesives validated against revised temperature excursion protocols. Pharmaceutical third-party logistics providers in Germany and the Netherlands are responding by tightening incoming material specifications and requiring converters to submit expanded stability documentation.
Clinical trial sponsors are consolidating label procurement under centralized vendor management programs, displacing site-level purchasing autonomy. Contract research organizations are capturing preferred supplier status through integrated kitting and distribution services. This concentration is most visible in the Boston-Cambridge and Basel pharmaceutical clusters, where sponsor procurement functions have established dedicated cold-chain packaging categories.
Freezer Label Market Segmentation
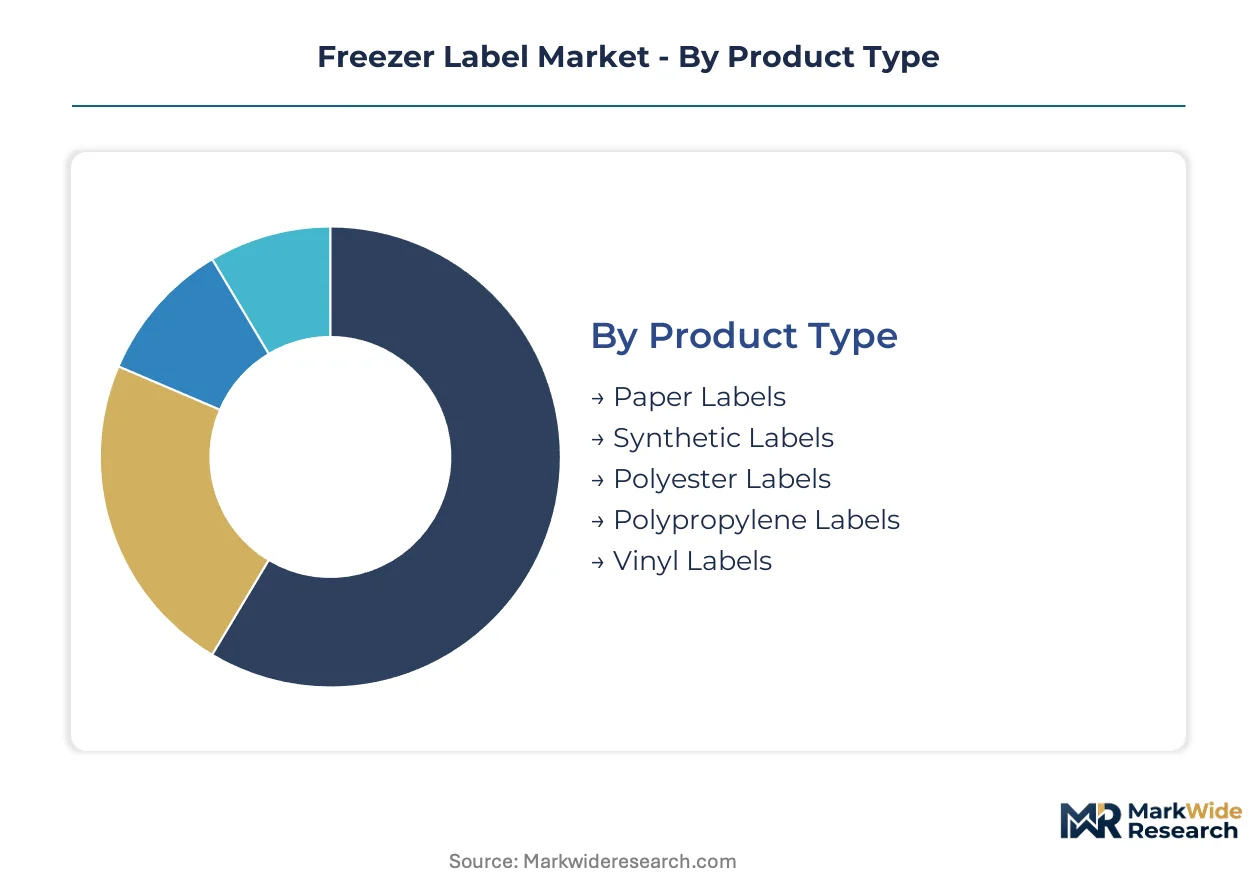
Freezer label procurement patterns diverge sharply across substrate chemistry, print technology, and end-use compliance requirements. Pharmaceutical cold-chain operators prioritize validated synthetic constructions, while food processors optimize for operational simplicity in high-volume environments.
Product Type:
Domestic consumption of coated paper grades concentrates in North American food processing corridors, whereas synthetic and polymer film exports flow predominantly to European pharmaceutical distribution hubs serving EMA-regulated cold chains.
- Paper Labels:Coated facestocks with moisture-resistant barriers serve cost-sensitive food retail applications. Demand clusters in Midwest US meatpacking facilities where short shelf-life cycles limit durability requirements.
- Synthetic Labels:Polymer constructions maintain dimensional stability through repeated freeze-thaw excursions. German pharmaceutical third-party logistics providers specify these grades for minus eighty-degree Celsius vaccine storage under EU F-Gas Regulation compliance mandates.
- Polyester Labels:High-tensile films resist brittleness in cryogenic liquid nitrogen environments. CAR-T therapy logistics operators in Massachusetts and Basel require validated polyester constructions for cell preservation tracking.
- Polypropylene Labels:Flexible olefin films conform to curved vial surfaces. Japanese biobank operators favor polypropylene for genomic sample libraries requiring decades-long archival stability.
- Vinyl Labels:Plasticized constructions tolerate moderate cold-chain excursions in chemical drum identification. Industrial solvent manufacturers in Texas and Louisiana deploy vinyl for warehouse inventory under OSHA hazard communication rules.
Paper labels command the established base. The steepest expansion runs through synthetic labels.
Technology:
Print method selection directly determines ribbon inventory economics, printhead replacement frequency, and regulatory traceability compliance across pharmaceutical and food processing installations.
- Thermal Transfer:Wax-resin and resin ribbons deliver archival print durability for pharmaceutical lot codes. EMA serialization mandates in the Netherlands and Ireland sustain thermal transfer demand despite higher operational costs.
- Direct Thermal:Chemically coated synthetic facestocks eliminate ribbon procurement and changeover downtime. US poultry processors in Georgia and Arkansas are eliminating thermal transfer infrastructure to streamline refrigerated packaging lines.
- Inkjet:Piezoelectric and thermal inkjet systems enable variable data printing for clinical trial materials. Contract research organizations in the Boston-Cambridge corridor adopt inkjet for short-run protocol amendments.
- Laser:Toner-based systems produce permanent marks resistant to solvent exposure. Chemical manufacturers in Germany's Rhine-Ruhr industrial zone specify laser-printed labels for flammable material handling under REACH substance disclosure requirements.
- Flexographic:Rotary letterpress methods support high-volume pre-printed roll stock for commodity food packaging. Midwest dairy cooperatives procure flexographic labels in million-unit quantities for milk carton dating.
Thermal transfer retains the pharmaceutical certification base. Direct thermal is climbing the fastest through food processing automation upgrades.
Application:
Regulatory stringency and temperature excursion profiles fragment specification requirements across pharmaceutical preservation, food safety, and industrial chemical tracking use cases.
- Pharmaceutical Preservation:Cryogenic-grade adhesives validated to minus eighty degrees Celsius maintain tack integrity for mRNA vaccine vials. FDA lot-level traceability mandates compel distributors to procure stability-documented constructions.
- Food Packaging:Direct thermal synthetic facestocks withstand refrigerated distribution center thermal cycling. USDA-inspected poultry plants in the southeastern US specify these grades to eliminate ribbon inventory management.
- Chemical Storage:Solvent-resistant adhesives prevent delamination from drum surfaces in sub-zero warehouse environments. OSHA hazard communication standards require GHS pictogram legibility across temperature extremes.
- Laboratory Sample Identification:Barcode-readable constructions support automated biobank retrieval systems. Research institutions in Switzerland and Singapore specify cryogenic-validated labels for long-term specimen archiving.
- Biotechnological Research:RNase-free and DNA-free certified substrates prevent nucleic acid contamination. Cell therapy developers in California and Maryland require validated cleanroom-compatible label constructions.
Pharmaceutical preservation anchors premium pricing tiers. Food packaging is gaining share fastest through operational simplification demands.
End User:
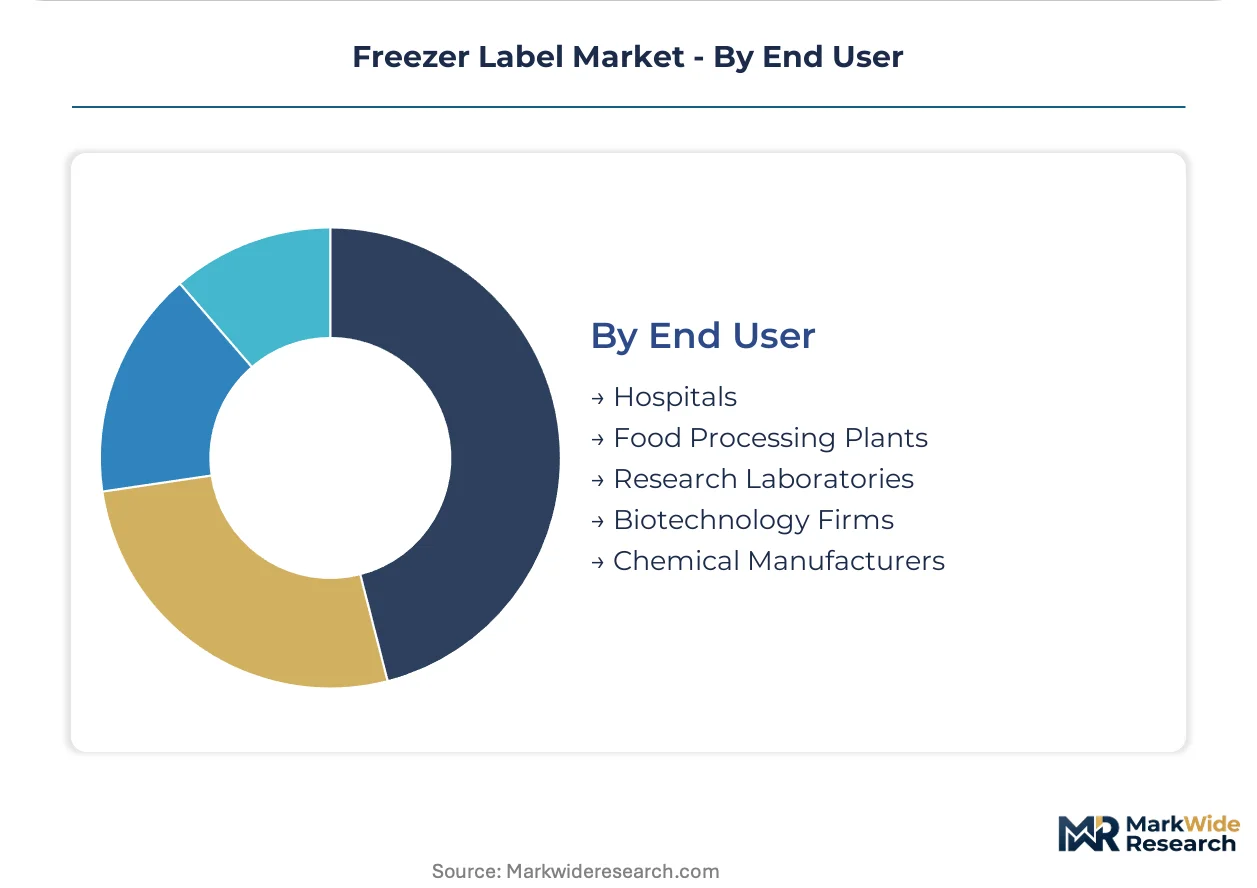
Procurement centralization patterns vary across institutional healthcare, industrial food processing, and research laboratory environments with distinct validation timelines and specification authority.
- Hospitals:Pharmacy and blood bank departments require FDA-compliant labels for controlled-temperature medication storage. Health system consolidation in the US is centralizing purchasing under regional supply chain officers.
- Food Processing Plants:Multi-temperature distribution centers demand synthetic direct thermal grades for operational efficiency. German meatpacking facilities under EU F-Gas Regulation pressure are upgrading identification systems alongside refrigeration infrastructure.
- Research Laboratories:Academic and government biobanks specify cryogenic-validated constructions for decades-long sample retention. NIH-funded institutions require stability documentation spanning liquid nitrogen exposure protocols.
- Biotechnology Firms:Clinical-stage companies procure short-run customized labels for investigational product distribution. Sponsor procurement functions in Basel and Boston are consolidating vendors under preferred supplier programs.
- Chemical Manufacturers:Industrial drum labeling requires solvent-resistant adhesives and abrasion-resistant print. Texas petrochemical complexes specify grades validated under OSHA hazard communication and EPA environmental release reporting.
Food processing plants command volume concentration. Biotechnology firms are expanding most quickly through cell and gene therapy pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of synthetic freezer label substrates concentrate in German and US integrated mills, while pharmaceutical cold-chain operators in Switzerland and Japan import specialized cryogenic-grade constructions. This trade pattern reflects adhesive chemistry expertise clustering in North American and European polymer science corridors.
United States
FDA lot-level traceability mandates and mRNA vaccine distribution networks drive synthetic label procurement. The EPA oversees chemical substance reporting for adhesive formulations used in pharmaceutical packaging. Massachusetts biotechnology clusters around Boston-Cambridge require cryogenic-validated labels for cell therapy logistics.
Germany
Centralized pharmaceutical distribution networks and EU F-Gas Regulation compliance pressure upgrade identification system specifications. EMA serialization requirements tighten stability documentation demands for cold-chain materials. The Rhine-Ruhr industrial zone anchors converter capacity serving EMA-regulated logistics providers.
Switzerland
Swissmedic pharmacovigilance standards and decades-long biobank archival requirements sustain premium substrate demand. REACH substance disclosure rules shape adhesive selection for food processing exports. Basel pharmaceutical procurement functions consolidate vendor programs for clinical trial materials.
Japan
PMDA cold-chain validation protocols and genomic sample library expansion propel cryogenic label adoption. METI industrial standards guide synthetic film specifications for automated retrieval systems. Tokyo-Yokohama biobank operators specify polypropylene constructions for long-term nucleic acid preservation.
India
CDSCO pharmaceutical export compliance and domestic vaccine distribution scale pressure-sensitive adhesive demand. FSSAI food safety labeling requirements extend to refrigerated supply chains. Maharashtra pharmaceutical manufacturing corridors near Mumbai and Pune upgrade cold-storage identification infrastructure.
Freezer Label Market Competitive Landscape
Concentration sits with integrated film producers controlling captive adhesive polymerization and multi-continent distribution infrastructure. The supply base stratifies across three archetypes: integrated polymer producers with backward adhesive control, narrow converters dependent on external substrate supply, and specialized pharmaceutical certification specialists. Competitive moves center on renewable substrate certification acquisition and cryogenic validation documentation expansion for cell therapy logistics.
Within the integrated producer tier, Avery Dennison Corporation and CCL Industries Inc. exemplify scale-driven positioning through polymer science capabilities and slitting infrastructure. UPM Raflatac occupies a position representing renewable certification differentiation for European food processors facing Scope 3 disclosure requirements.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| 3M Company |
| Brady Corporation |
| UPM Raflatac |
| LINTEC Corporation |
| Multi-Color Corporation |
| SATO Holdings Corporation |
| Zebra Technologies |
| Others |
Supply & Pricing Matrix
FDA lot-level traceability mandates gate both converter qualification and price differentiation simultaneously, forcing pharmaceutical buyers to pay premiums for stability-documented constructions while food processors optimize for operational cost. This regulatory bifurcation concentrates pricing power among integrated adhesive producers serving validated cold-chain segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across synthetic substrate tiers. Price differentiation rests on cryogenic certification grade and volume scale, with pharmaceutical third-party logistics providers showing least sensitivity due to regulatory compliance requirements. Cost compression in food-grade paper labels is intensifying because poultry processors are consolidating procurement under regional supply chain officers. Narrow converters dependent on external adhesive supply face the steepest margin pressure.
Supply Chain Analysis
Container availability constraints on transatlantic lanes from Rotterdam to Charleston elevate inbound logistics costs for European converters sourcing acrylic acid derivatives. Adhesive polymerization draws from propylene feedstocks concentrated in Texas, Louisiana, and the Rhine-Ruhr industrial zone. Single-source vulnerability sits with glassine and PET release liner production clustering among integrated North American and European mills. Distribution runs through multi-continent slitting infrastructure controlled by integrated producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freezer label procurement is approaching a platform-economics inflection as clinical trial sponsors consolidate vendor management programs and demand interoperable stability documentation across FDA, EMA, and WHO-PQS certification regimes.
For Market Incumbents: Consolidate cryogenic validation documentation capabilities through captive adhesive polymerization expansion in Germany and Massachusetts biotechnology corridors. Defend against narrow converters by tightening preferred supplier status with Boston-Cambridge and Basel sponsor procurement functions. Prioritize backward integration into silicone release liner production to escape fixed cost burdens. For New Entrants and Emerging Players: WHO-PQS certification fast-track programs open white-space entry into Indian and Southeast Asian vaccine distribution networks. Target Maharashtra pharmaceutical manufacturing corridors near Mumbai where CDSCO export compliance pressure is upgrading cold-storage identification infrastructure. Pursue digital print integration for clinical trial short-run customization as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized adhesive polymerization assets and dormant pharmaceutical certification relationships. Five-to-ten year viability hinges on cell and gene therapy logistics scale-up. Monitor CAR-T therapy pipeline advancement through NIH-funded institutions as the signal indicating cryogenic-grade label demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Validation Documentation Expansion | FDA and EMA stability requirements tighten qualification barriers for mRNA vaccine distributors. |
| Renewable Substrate Certification Acquisition | FSC-certified film alternatives capture premium positioning under EU Green Deal Scope 3 disclosure mandates. |
| Direct Thermal Synthetic Capacity Buildout | US poultry processors in Georgia and Arkansas eliminate ribbon inventory through coated facestock adoption. |
| Backward Integration into Adhesive Polymerization | Captive propylene derivative supply insulates margin control from petrochemical input volatility. |
| Digital Print Platform Integration | Hybrid inkjet systems enable short-run clinical trial customization for Boston-Cambridge contract research organizations. |
Research Methodology
A spread of perspectives from adhesive R&D directors, pharmaceutical cold-chain procurement managers, food processing plant engineers, and converter operations heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA guidance documents, EMA serialization directives, EU F-Gas Regulation implementation reports, and customs trade data for acrylic acid derivative flows. Bottom-up volume estimates triangulated against top-down pharmaceutical cold-chain infrastructure investment tracking.
Segmentation dimensions modeled span substrate chemistry, print technology, application compliance tier, and end-user procurement centralization patterns across the projection horizon. CAGRs derived from installed base replacement cycles, regulatory mandate implementation timelines, and cell therapy logistics pipeline advancement. Industry-specific forecast inputs incorporated WHO-PQS qualification velocity and EU Green Deal renewable certification adoption curves.
Underlying assumptions cover stable FDA and EMA traceability mandate enforcement, with deviation risk concentrated in REACH substance disclosure expansion and propylene derivative supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Sleeve Label Market
Labels
Barcode Label Market
Labels
Ethical Label Market
Labels
Sustainable Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Global Cryogenic Label Market
Labels
Foil Labels Market
Labels
Screen Print Label Market
Labels
Safety Labels Market
Labels
Print Label Market
Labels
Variable Data Printing Labels Market
Labels
Multi-Part Labels Market
Labels
Inspection and Inventory Labels Market
Labels
Global Security Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Holographic Labels Market