
 Polyester Labels Market | 2026-2036
Polyester Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Labels Market Analytics
Buyer concentration in the food and beverage sector is decoupling as craft producers and private-label manufacturers fragment demand away from multinational CPG giants. Avery Dennison Corporation leverages its global adhesive technology portfolio to serve both ends of this split. CCL Industries Inc. anchors its position through backward integration into film extrusion and coating operations. SATO Holdings Corporation specializes in RFID-enabled polyester label systems for track-and-trace applications.
Polyester labels are synthetic film-based identification substrates manufactured from polyethylene terephthalate, typically coated with acrylic or silicone adhesives and engineered to withstand temperatures from minus forty to one hundred fifty degrees Celsius, moisture exposure, and chemical abrasion in industrial environments. Pressure-sensitive labels dominate volume due to their compatibility with high-speed dispensers across pharmaceutical and electronics assembly lines, while thermal transfer labels capture expanding share in barcode and variable-data printing where permanence and smudge resistance are critical. Roll labels align with automated applicator infrastructure in cosmetics and electronics manufacturing, whereas sheet formats retain relevance in short-run branding and proofing workflows.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR traceability mandates compel pharmaceutical converters toward certified, tamper-evident polyester label constructions. REACH restrictions on adhesive chemistries and California Proposition 65 disclosure rules shape material selection and supplier qualification protocols across the value chain. Stakeholders must monitor evolving extended producer responsibility frameworks and adhesive substance restrictions to preempt compliance-driven reformulation costs.
Market Dynamics
Pharmaceutical serialization mandates across the European Union and the United States are forcing label converters to reengineer production lines for tamper-evident, track-and-ready polyester constructions at unprecedented speed.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Pharmaceutical manufacturers in the United States must deploy serialized labels on unit-level packaging, driving certified polyester substrate demand through 2035.
- Food and beverage automation:German and American craft producers are installing high-speed applicator lines that specify roll-format pressure-sensitive labels for throughput consistency.
- RFID integration:Track-and-trace systems in electronics assembly are absorbing polyester labels with embedded antennas for real-time inventory visibility.
Market Restraints
- Petroleum-based resin volatility:Polyethylene terephthalate feedstock costs fluctuate with crude oil benchmarks, compressing converter margins during energy price spikes.
- Adhesive chemistry restrictions:REACH substance limitations and California Proposition 65 disclosure rules are disqualifying legacy acrylic formulations from European and American pharmaceutical contracts.
- Paper label substitution:Short-run branding workflows in cosmetics and proofing applications are reverting to paper substrates where moisture resistance is non-critical.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO serialization requirements for export-bound generics are creating demand for FDA-compliant polyester label suppliers with local coating capabilities.
- EU Green Deal alignment:Extended producer responsibility frameworks in Germany and France are rewarding converters offering recyclable or bio-based polyester film alternatives.
- Thermal transfer-inkjet convergence:Hybrid printing systems combining thermal transfer durability with inkjet variable-data flexibility are opening electronics and logistics segments.
Industry Challenges
- Specialized coating technician scarcity:Silicone and adhesive formulation expertise is concentrated among aging workforces in Germany and Japan, slowing new facility ramp-ups.
- Multi-certification timelines:Pharmaceutical converters must synchronize FDA, EMA, and ISO 15378 audits, extending qualification cycles for new polyester label constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Labels Market |
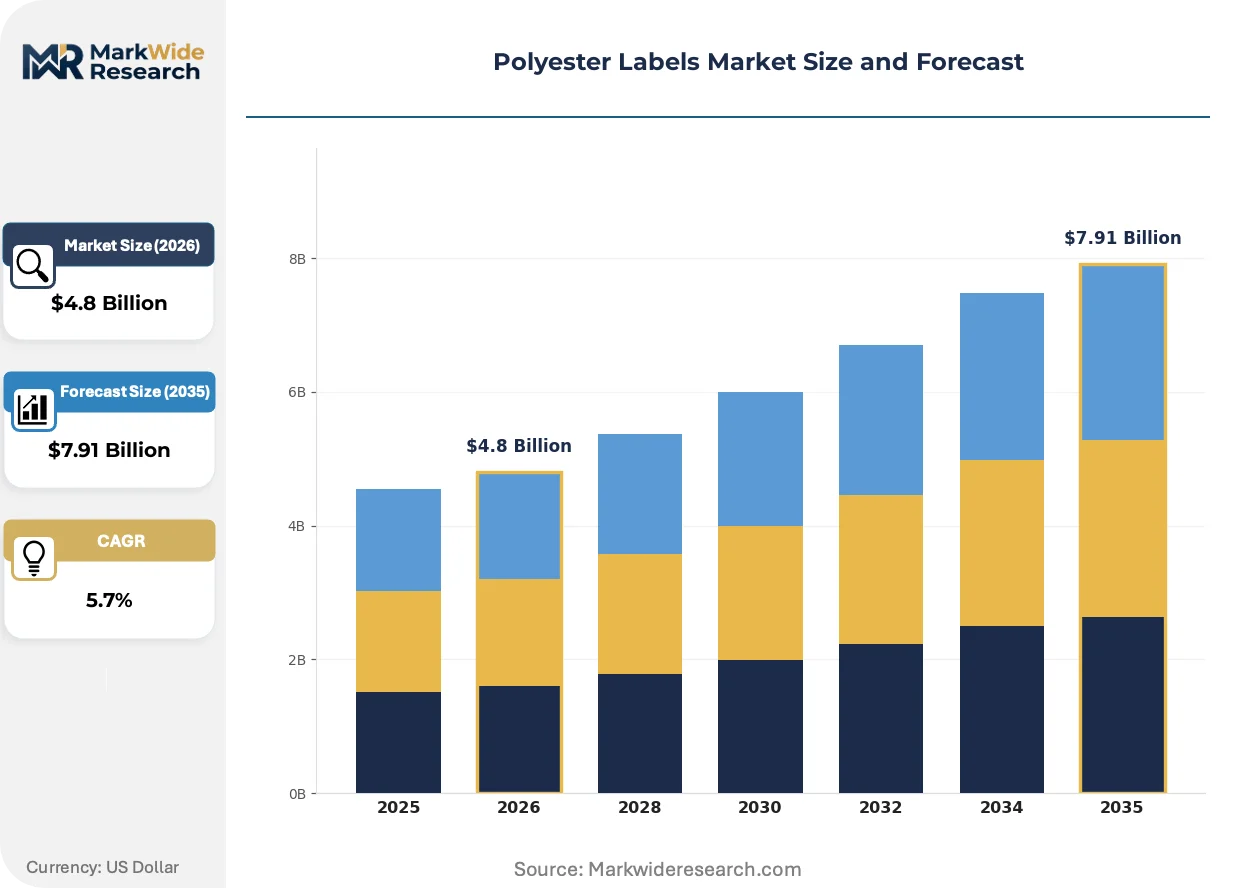
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Heat-Shrink Labels, Thermal Transfer Labels, Bopp Labels End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Label Format: Sheet Labels, Roll Labels, Custom Shape Labels, Waterproof Labels Application: Branding, Product Identification, Barcoding, Shipping Labels |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., Lintec Corporation, Tesa SE, Brady Corporation, UPM-Kymmene Oyj, SATO Holdings Corporation, DuraMark Technologies Inc., Constantia Flexibles Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Labels Market Evolving Landscape
Digital printing integration and sustainable material science are converging to redefine polyester label specifications across pharmaceutical, electronics, and food packaging verticals.
Direct-to-object inkjet systems are absorbing polyester label volumes in short-run electronics and cosmetics applications. Contract manufacturers in South Korea and Germany are retrofitting lines for on-demand printing that eliminates pre-printed inventory. This technology is absorbing demand from traditional thermal transfer workflows by enabling lot-size-one economics without plate costs.
REACH substance restrictions are compelling adhesive reformulation across European pharmaceutical supply chains. ECHA candidate list updates are phasing out specific isocyanate-based curing agents, forcing converters to validate alternative chemistries under compressed timelines. German label producers are accelerating partnerships with film coaters to secure compliant adhesive supply ahead of 2025 restriction deadlines.
Private-label fragmentation is compressing procurement cycles in North American food and beverage. Brand owners are unbundling master label contracts into SKU-specific agreements with regional converters, displacing long-term sole-source arrangements. This pattern is most visible in craft brewing and specialty coffee segments, where packaging refresh frequencies have doubled since 2020.
Polyester Labels Market Segmentation
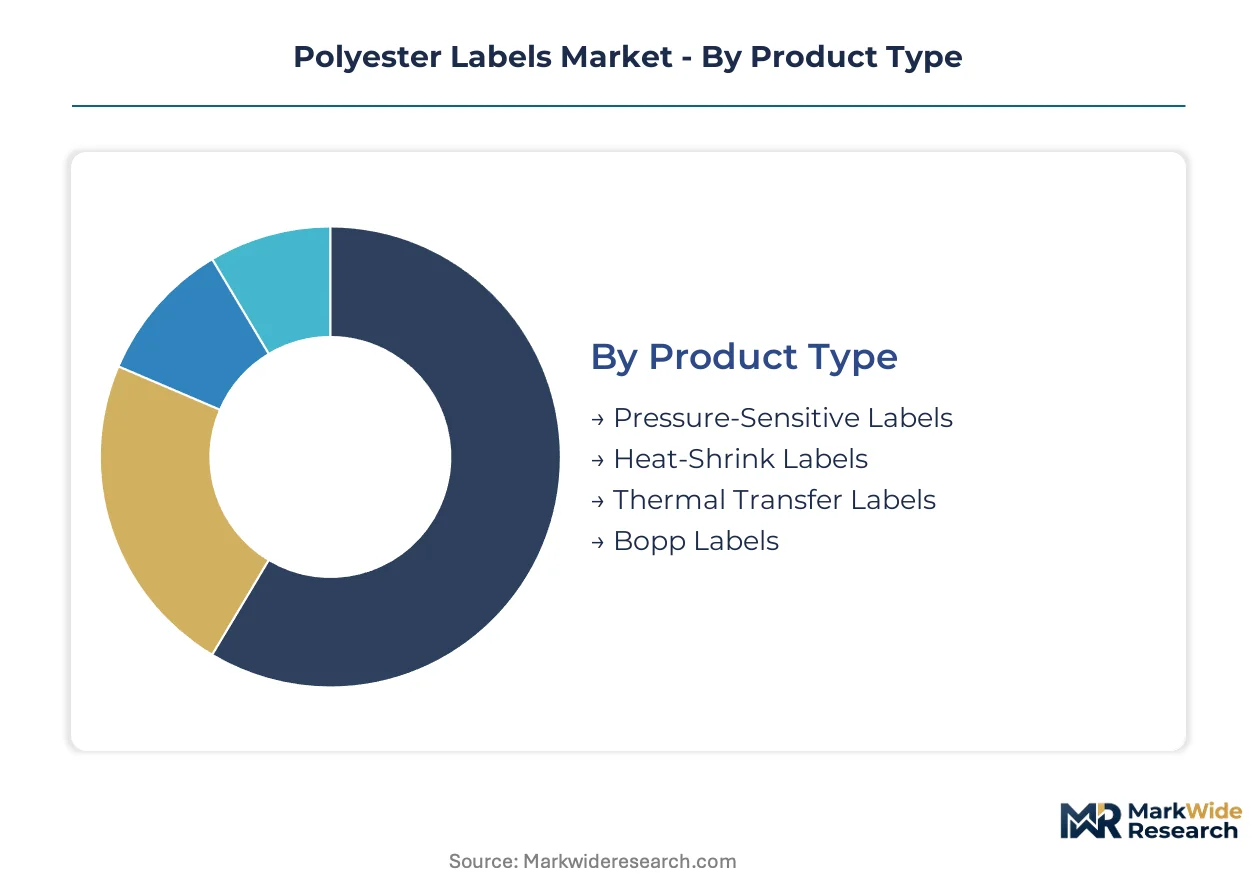
Polyester label procurement splits across four independent dimensions: adhesion mechanism, end-use environment, physical format, and functional purpose. Each axis carries distinct certification requirements and margin profiles that reshape converter specialization strategies.
Product Type:
Converters select adhesion technologies based on line speed, substrate compatibility, and permanence requirements in target applications.
- Pressure-Sensitive Labels:Acrylic or silicone-coated films that adhere instantly upon contact without heat activation. Pharmaceutical assembly lines in Germany and the United States specify these for high-speed dispensers handling serialized unit-dose packaging under FDA and EU MDR mandates.
- Thermal Transfer Labels:Receptive topcoats engineered for ribbon-based printing that produces smudge-resistant, chemically stable barcodes. Electronics manufacturers in South Korea and contract packagers in Germany are absorbing volumes for variable-data track-and-trace applications requiring archival durability.
- Heat-Shrink Labels:Oriented polyester films that conform to container contours when exposed to controlled heat. Beverage bottlers specify these for full-body decoration on contoured packaging where traditional adhesive labels fail.
- BOPP Labels:Biaxially oriented polypropylene alternatives offering cost positioning below PET films. Private-label food producers specify these where moisture resistance requirements are moderate and price sensitivity dominates.
Pressure-sensitive constructions lead on scale; thermal transfer formats lead on momentum.
End Use Industry:
Regulatory intensity and automation maturity vary sharply across verticals, fragmenting converter qualification requirements.
- Food & Beverage:Roll-format pressure-sensitive labels dominate automated bottling and canning lines. Craft brewers in Germany and specialty coffee roasters in the United States are unbundling master contracts into SKU-specific regional agreements.
- Pharmaceuticals:Tamper-evident, serialized polyester constructions mandated by FDA DSCSA and EU MDR traceability rules. CDSCO export requirements for Indian generics are extending demand for FDA-compliant coating capabilities.
- Cosmetics:Short-run branding workflows favor sheet formats for proofing flexibility. Direct-to-object inkjet systems in South Korea are absorbing volumes from traditional pre-printed label inventories.
- Electronics:RFID-enabled polyester labels with embedded antennas for real-time inventory visibility. Contract manufacturers specify these for assembly-line track-and-trace in high-mix production environments.
Pharmaceutical applications command premium pricing tiers; food and beverage delivers volume concentration.
Label Format:
Format selection locks converters into specific equipment ecosystems and order-size economics.
- Roll Labels:Continuous-web configurations compatible with automated applicators and high-speed dispensers. German and American food producers specify these for throughput consistency in craft-scale operations.
- Sheet Labels:Die-cut configurations delivered in flat stacks for manual or semi-automated application. Cosmetics proofing workflows and short-run branding retain this format where flexibility outweighs speed.
- Custom Shape Labels:Irregular die-cuts engineered for distinctive shelf presence. Premium spirits and specialty personal care brands specify these for differentiation in fragmented retail environments.
- Waterproof Labels:Laminated or topcoated constructions rated for immersion and condensation exposure. Beverage coolers and refrigerated logistics specify these where standard paper or uncoated films degrade.
Roll formats dominate automated infrastructure investment; custom shapes gain share in premium positioning strategies.
Application:
Functional purpose determines print durability requirements and information density specifications.
- Branding:High-graphic surface treatments emphasizing color fidelity and tactile finish. Cosmetics and specialty food segments specify these for shelf-impact competition in fragmented retail.
- Product Identification:Regulatory-compliant text and symbols for ingredient disclosure and hazard communication. REACH and California Proposition 65 rules shape adhesive and ink selection for European and American compliance.
- Barcoding:Machine-readable symbologies requiring thermal transfer or thermal print receptivity. Pharmaceutical serialization mandates in the United States and European Union are accelerating certified substrate demand.
- Shipping Labels:Adhesive constructions rated for temperature cycling and mechanical abrasion in logistics networks. E-commerce fulfillment centers specify these for automated sortation compatibility.
Barcoding applications are expanding most quickly on regulatory compulsion; branding retains margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in polyester label procurement intensity, with German converters prioritizing REACH-compliant adhesive systems while American buyers emphasize FDA serialization throughput. India and China are expanding coating capacity to serve pharmaceutical export corridors. Japan maintains specialized expertise in RFID-embedded constructions.
United States
FDA DSCSA unit-level serialization mandates drive certified polyester substrate demand through pharmaceutical packaging lines. California Proposition 65 disclosure rules disqualify legacy adhesive formulations from West Coast cosmetics contracts. Chicago and New Jersey industrial corridors host automated label applicator infrastructure serving craft beverage producers.
Germany
Food and beverage automation investments specify roll-format pressure-sensitive labels for throughput consistency in craft-scale operations. EU Green Deal extended producer responsibility frameworks reward converters offering recyclable polyester film alternatives. Bavarian and Baden-Württemberg coating facilities concentrate silicone adhesive formulation expertise for pharmaceutical track-and-trace applications.
India
CDSCO serialization requirements for export-bound generics create demand for FDA-compliant polyester label suppliers with local coating capabilities. Pharmaceutical contract manufacturing clusters in Maharashtra and Gujarat drive substrate qualification programs. Mumbai-Pune industrial corridor hosts emerging film extrusion operations targeting European pharmaceutical supply chains.
China
Electronics assembly lines absorb RFID-enabled polyester labels with embedded antennas for real-time inventory visibility. NMPA pharmaceutical traceability rules align packaging converters with international serialization standards. Yangtze River Delta manufacturing bases supply thermal transfer constructions for export-oriented contract manufacturers.
Japan
PMDA pharmaceutical packaging regulations enforce tamper-evident label constructions with archival barcode durability. METI industrial automation programs subsidize RFID integration in electronics assembly track-and-trace systems. Chubu and Kansai industrial regions concentrate specialized coating technician expertise for high-performance adhesive formulations.
Polyester Labels Market Competitive Landscape
German and Japanese producers anchor one tier; American and Canadian specialists hold differentiated positions in adhesive technology and pharmaceutical certification. Market structure consolidates around film coaters with backward integration into extrusion operations and converters with captive silicone formulation capabilities. Three archetypes dominate: integrated film manufacturers, specialized pharmaceutical-grade coaters, and RFID systems integrators. Competitive moves center on multi-certification qualification timelines and geographic expansion into Indian pharmaceutical export corridors.
Within the integrated film manufacturing tier, Avery Dennison Corporation and CCL Industries Inc. exemplify scale-driven positions spanning adhesive technology portfolios and backward integration into film extrusion. SATO Holdings Corporation occupies a specialized position representing RFID-enabled systems integration for track-and-trace applications. Among European-based fabricators, Tesa SE and Constantia Flexibles Group GmbH sit within pharmaceutical-grade coating archetypes, while Lintec Corporation and Brady Corporation anchor diversified industrial labeling positions across electronics and safety identification segments.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Lintec Corporation |
| Tesa SE |
| Brady Corporation |
| UPM-Kymmene Oyj |
| SATO Holdings Corporation |
| DuraMark Technologies Inc. |
| Constantia Flexibles Group GmbH |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in Germany and Japan anchor supply-side discipline through captive silicone formulation capabilities, translating certification scarcity into pricing power for pharmaceutical-grade polyester constructions while spot-market PET resin exposure compresses margins at commodity-oriented competitors.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard-grade pressure-sensitive labels, forcing European and North American producers toward premium-mid-economy pricing differentiation. Pharmaceutical serialization tiers command spreads based on FDA and EMA dual-certification status, while food and beverage procurement unbundling intensifies cost compression in roll-format segments. Craft-scale buyers in Germany and the United States exhibit highest price sensitivity; track-and-trace electronics manufacturers absorb premium RFID-embedded constructions with limited negotiation leverage.
Supply Chain Analysis
Multi-certification gating concentrates qualified coating capacity in Germany, Japan, and the United States, where FDA and EMA audit synchronization extends facility qualification timelines. PET resin feedstock draws from petroleum-based supply chains with crude-linked volatility, while silicone adhesive precursors hinge on specialized chemical intermediates. Tariff exposure on Chinese film extrusion equipment poses structural risk. Distribution runs through converter-direct relationships with pharmaceutical OEMs and regional distributor networks serving fragmented food and beverage craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bio-based polyester film substitution commanding Green Deal-linked premiums, while automation-driven throughput gains in coating operations compress unit costs for scaled producers.
For Market Incumbents: Deepen backward integration into film extrusion to secure PET resin supply amid energy price volatility, and accelerate EMA-FDA dual-certification investment ahead of Indian pharmaceutical export corridor expansion. Adhesive chemistry restrictions under REACH substance limitations threaten legacy formulation portfolios; converters must validate alternative chemistries under compressed timelines to defend pharmaceutical contract retention. For New Entrants and Emerging Players: Regional craft beverage distributors in Germany and the American Midwest offer partnership pathways into SKU-specific label procurement workflows displacing multinational sole-source arrangements. Private-label fragmentation in specialty coffee and craft brewing segments presents the most penetrable white-space, with direct-to-converter digital printing integration as the viable go-to-market angle against incumbent pre-printed inventory models. For Investors and Strategic Acquirers: Valuations sit cheapest among pharmaceutical-grade coaters lacking RFID systems integration, as electronics track-and-trace demand re-rates specialist capabilities. Five-to-ten year viability favors converters with captive silicone formulation and backward film extrusion control. Watch CDSCO enforcement intensity on Indian export-bound generics as the inflection signal for FDA-compliant coating capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Secures PET resin supply for German and American converters facing petroleum price volatility. |
| Dual-Certification Investment | EMA-FDA synchronization opens Indian pharmaceutical export corridors for qualified coaters. |
| Bio-Based Polyester Development | EU Green Deal extended producer responsibility frameworks reward recyclable film alternatives in France and Germany. |
| RFID Systems Integration | Embedded antenna capabilities capture electronics assembly track-and-trace demand in South Korea and China. |
| Hybrid Printing Technology Deployment | Thermal transfer-inkjet convergence targets lot-size-one economics in cosmetics and electronics short-run workflows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with label converter operations directors, pharmaceutical packaging procurement managers, food and beverage brand supply chain leads, and adhesive formulation R&D heads with secondary validation from FDA DSCSA guidance documents, EMA MDR implementation reports, ECHA REACH substance restriction updates, and customs trade flow data for PET film and coated labelstock. Bottom-up facility capacity modeling and top-down end-use demand aggregation provided cross-referencing discipline.
Historical reference periods anchored volume and value trajectories across the analysis window, with segmentation modeling across adhesion mechanism, end-use vertical, physical format, and functional application dimensions. CAGRs derived from fitted growth curves incorporating pharmaceutical serialization mandate phase-in schedules, food and beverage automation investment cycles, and electronics RFID adoption patterns. Forecast inputs included PET resin price volatility indices and coating technician labor availability by geography.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansion and extended producer responsibility framework implementation across European markets. Model outputs reflect documented assumptions on regulatory enforcement intensity and raw material cost trajectories. A model refresh is warranted upon material change in FDA DSCSA unit-level serialization deadline adherence or CDSCO export requirement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Water Dissolvable Labels Market
Labels
Direct Thermal Labels Market
Labels
Print Label Market
Labels
Self-Laminating Labels Market
Labels
North America Self-Adhesive Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
APAC on-Demand Color Labels Market
Labels
Integrated Labeling System Market
Labels
Eco-Friendly Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Waterproof and Weatherproof Label Market
Labels
In-Mold Labeling (IML) Market
Labels
Braille Labels Market
Labels
Wet Glue Labels Market
Labels
Global Industrial Labels Market