
 Global Tamper Evident Labels Market | 2026-2036
Global Tamper Evident Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tamper Evident Labels Market Outlook
Pharmaceutical buyer consolidation is recalibrating procurement leverage across the tamper evident label supply base. UPM Raflatac leverages its European adhesive R&D footprint to serve consolidated pharma contract manufacturers. Avery Dennison Corporation anchors North American demand through direct thermal and RFID-enabled security label portfolios. CCL Industries specializes in multi-layer bottle seal constructions for high-volume over-the-counter drug packaging.
Tamper evident labels are pressure-sensitive or heat-activated substrates engineered with frangible films, void patterns, or destructible adhesives that reveal irreversible visual evidence upon removal, typically specified to 0.05 mm thickness tolerances for pharmaceutical vial applications. Their primary purpose is to provide visible authentication of product integrity across supply chain handoffs. Security labels and bottle seals command the mature margin pool in pharmaceutical and food packaging, while RFID-enabled segments attract fastest-growing demand from electronics and logistics end users seeking item-level traceability. Pressure sensitive technology dominates unit volume, though direct thermal printing gains share in retail and warehousing applications requiring on-demand variable data encoding.
FDA drug supply chain security requirements, EU Falsified Medicines Directive serialization mandates, and ISO 21976 anti-counterfeiting standards collectively elevate minimum performance specifications for tamper evident packaging. China's NMPA and India's CDSCO have tightened import label compliance, reshaping supplier qualification timelines for export-oriented manufacturers. Stakeholders must monitor evolving national track-and-trace regulations to anticipate substrate and authentication technology refresh cycles.
Market Dynamics
Pharmaceutical serialization mandates across multiple jurisdictions are forcing substrate suppliers to recalibrate adhesive chemistry and authentication feature portfolios simultaneously. This regulatory compression is reshaping competitive positioning among converters serving export-oriented drug packaging lines.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Track-and-trace requirements for prescription drugs mandate unit-level tamper verification, expanding procurement volumes for void-pattern labels and destructible films across US pharmaceutical contract manufacturers.
- E-commerce logistics authentication:High-value parcel networks in Germany, Japan, and Brazil now require tamper proof tapes with irreversible visual evidence, creating dedicated demand streams from third-party fulfillment operators.
- Heat-activated frangible films:Advanced substrate engineering enables 0.05 mm thickness tolerances for pharmaceutical vial seals, supporting automated application speeds on high-throughput packaging lines serving export markets.
Market Restraints
- Petrochemical adhesive volatility:Acrylic and rubber-based pressure-sensitive formulations face input cost swings tied to crude derivatives, compressing converter margins during procurement cycles.
- Asia-Pacific substrate concentration:Specialty film and destructible paper production clusters in select East Asian manufacturing zones create geographic supply risk for European and North American label converters.
- Direct thermal printing substitution:Variable data encoding technologies for warehousing and retail applications displace pre-printed security labels in segments where authentication hierarchy permits lower-grade integrity verification.
Strategic Opportunities
- India CDSCO import compliance tightening:New label qualification timelines for pharmaceutical exports create service revenue potential for converters offering regulatory documentation and substrate certification packages.
- RFID-NFC convergence:Item-level traceability integration combining radio-frequency identification with near-field communication opens electronics and luxury goods segments beyond traditional pharmaceutical demand.
- EU Falsified Medicines Directive serialization:Remaining implementation phases for over-the-counter drug categories extend mandate coverage to high-volume analgesic and cough-cold packaging lines.
Industry Challenges
- ISO 21976 certification timelines:Anti-counterfeiting standard compliance requires extended laboratory validation for new adhesive-substrate combinations, delaying product launches by 8-14 months.
- Legacy serialization system integration:Pharmaceutical packers running established track-and-trace infrastructure face friction retrofitting new tamper evident formats without line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tamper Evident Labels Market |
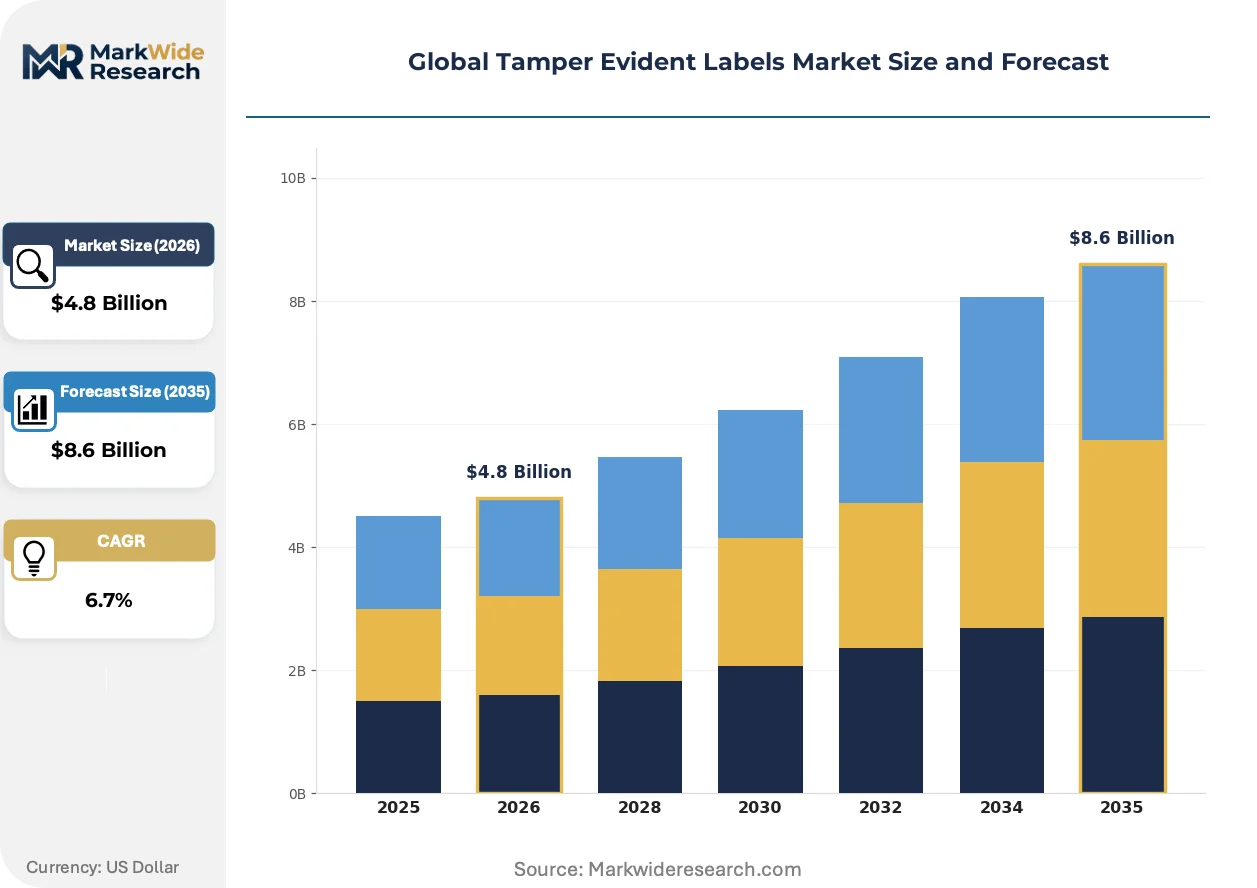
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Security Labels, Bottle Seals, Tamper Proof Tapes, Adhesive Stickers End User: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Technology: Pressure Sensitive, Direct Thermal, RFID, Barcodes Application: Packaging, Logistics, Retail, Warehousing |
| Companies Covered | UPM Raflatac, Brady Corporation, 3M, Tesa SE, Honeywell International, Avery Dennison Corporation, LINTEC Corporation, Essentra PLC, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tamper Evident Labels Market Strategic Shifts
Authentication technology is consolidating around multi-layer constructions that combine visual, physical, and digital verification in single substrate deployments. This convergence is compressing the addressable market for single-feature labels while expanding total solution value.
Multi-layer bottle seal constructions are consolidating market share among high-volume over-the-counter pharmaceutical packagers. These substrates integrate frangible films with holographic elements and micro-textured void patterns. Converters serving consolidated contract manufacturers in Europe and North America report accelerated qualification cycles for integrated solutions versus standalone pressure-sensitive alternatives.
EU Falsified Medicines Directive serialization mandates are extending compliance deadlines for specific therapeutic categories, creating phased procurement waves across German, French, and Italian pharmaceutical packaging clusters. The directive's data matrix and tamper verification requirements are elevating minimum performance specifications for destructible adhesives. Small-molecule generic manufacturers face the steepest compliance cost curves as they retrofit legacy bottle and blister lines.
Buyer concentration among top-tier pharmaceutical contract manufacturers is compressing supplier negotiation cycles and standardizing substrate specifications across multi-site procurement agreements. Direct thermal printing capabilities are displacing pre-printed security labels in retail pharmacy distribution where variable lot and expiry encoding takes priority over premium authentication. This pattern is most visible in North American warehousing networks serving institutional pharmacy chains.
Global Tamper Evident Labels Market Segmentation
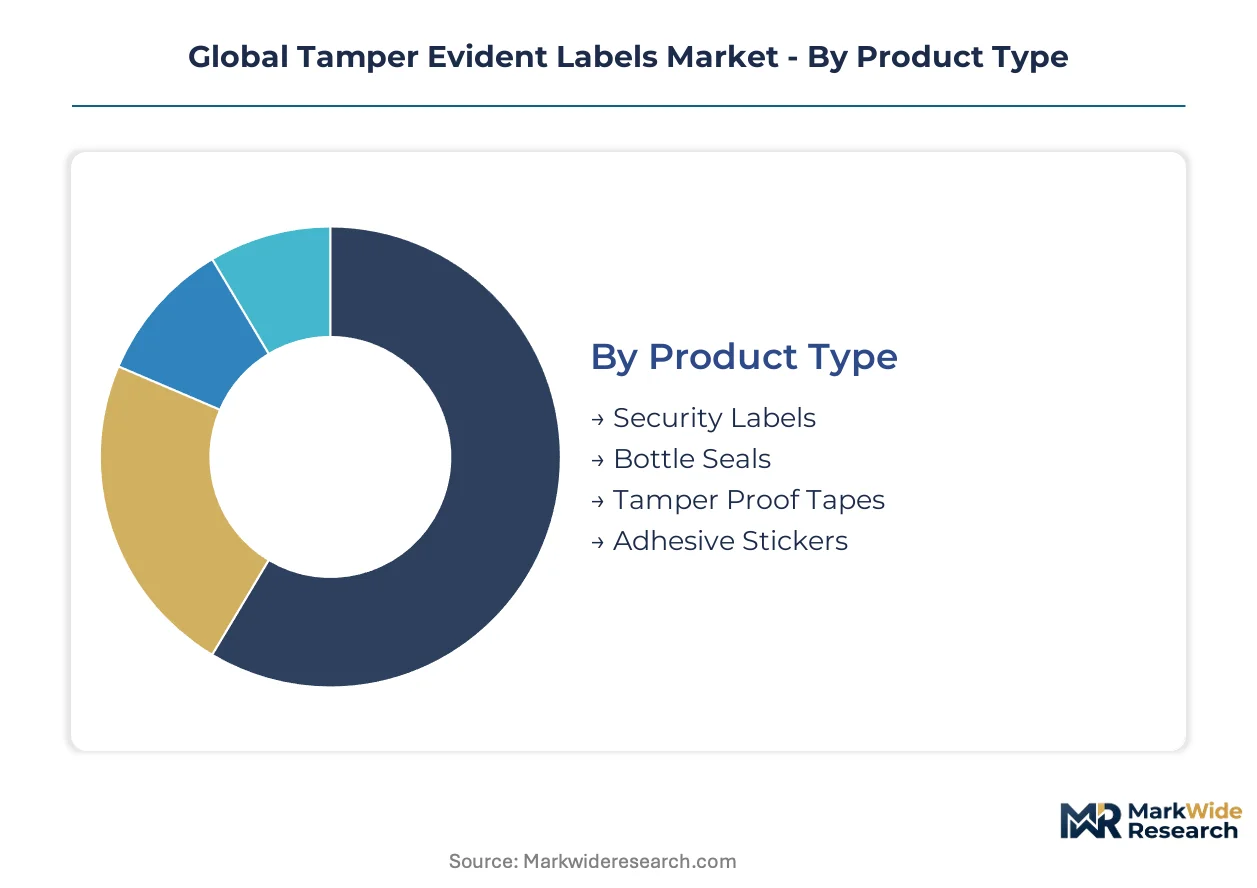
Segmentation in tamper evident labels reveals how substrate engineering, authentication intensity, and end-use compliance requirements partition procurement budgets. Each dimension carries distinct capital requirements and margin profiles that reshape supplier positioning.
Product Type:
Capital intensity varies sharply across product categories, with multi-layer constructions demanding precision coating lines and cleanroom validation that single-layer alternatives avoid.
- Security Labels:Multi-layer constructions integrate frangible films with holographic elements and micro-textured void patterns. Pharmaceutical contract manufacturers in Germany and the United States concentrate procurement for high-value prescription packaging, driven by FDA track-and-trace mandates and EU Falsified Medicines Directive serialization deadlines.
- Bottle Seals:Heat-activated substrates engineered to 0.05 mm thickness tolerances serve high-throughput pharmaceutical vial lines. Demand clusters among export-oriented generic drug packers in India facing tightened CDSCO import label compliance timelines.
- Tamper Proof Tapes:Pressure-sensitive acrylic formulations with irreversible visual evidence serve e-commerce logistics authentication requirements in Japan and Brazil.
- Adhesive Stickers:Standard pressure-sensitive constructions dominate unit volume in food and beverage applications where authentication hierarchy permits lower-grade integrity verification.
Security labels absorb the bulk of installed capacity; tamper proof tapes are expanding most quickly.
End User:
Regulatory burden intensity separates end-use segments, with prescription pharmaceutical mandates creating the steepest compliance cost curves.
- Pharmaceuticals:Serialization mandates across FDA, EMA, and NMPA jurisdictions force simultaneous recalibration of adhesive chemistry and authentication features. Small-molecule generic manufacturers face the steepest retrofit costs as they upgrade legacy bottle and blister lines.
- Electronics:Item-level traceability requirements from luxury goods and high-value component manufacturers are climbing the fastest as RFID-NFC convergence opens new authentication protocols.
- Food & Beverage:Brand protection and contamination anxiety drive procurement for visual verification in premium packaged goods segments.
- Consumer Goods:Cost-sensitive authentication for cosmetics and personal care products favors direct thermal printing over pre-printed security substrates.
Pharmaceuticals command the premium pricing tier; electronics represents the steepest expansion trajectory.
Technology:
Application equipment requirements and variable data capabilities segment technology choices across high-speed packaging lines versus on-demand encoding environments.
- Pressure Sensitive:Acrylic and rubber-based formulations dominate unit volume across pharmaceutical and food packaging lines, though petrochemical input volatility compresses converter margins during procurement cycles.
- RFID:Radio-frequency identification combined with near-field communication enables item-level traceability for electronics and logistics end users seeking authentication beyond visual verification alone.
- Direct Thermal:On-demand variable data encoding gains share in retail pharmacy distribution and warehousing networks where lot and expiry printing takes priority over premium authentication features.
- Barcodes:Legacy linear and 2D symbologies persist in cost-constrained segments where digital authentication hierarchy permits simpler integrity verification.
Pressure sensitive technology anchors current volume; RFID is gaining share fastest.
Application:
Line speed requirements and automation integration depth separate application environments, with pharmaceutical packaging demanding the most sophisticated substrate-handling systems.
- Packaging:Primary container sealing for pharmaceuticals and food products requires validated adhesive-substrate combinations meeting ISO 21976 anti-counterfeiting standards with 8-14 month laboratory validation timelines.
- Logistics:High-value parcel networks in Germany and Japan require tamper proof tapes with irreversible visual evidence, creating dedicated demand from third-party fulfillment operators.
- Retail:Variable data encoding for institutional pharmacy chains favors direct thermal printing over pre-printed security labels in North American warehousing networks.
- Warehousing:Inventory management applications prioritize scan reliability and cost efficiency over premium authentication features.
Packaging captures the majority of substrate value; logistics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical serialization mandates and e-commerce logistics authentication are concentrating demand in manufacturing clusters across Germany, Japan, the United States, India, and Brazil. Each market presents distinct regulatory timelines and substrate qualification requirements.
Germany
E-commerce fulfillment networks in Berlin and Hamburg drive procurement of tamper proof tapes for high-value parcel authentication. EU Falsified Medicines Directive serialization deadlines for remaining therapeutic categories extend mandate coverage to over-the-counter drug packaging lines. The Rhine-Ruhr pharmaceutical manufacturing corridor hosts contract packers retrofitting legacy bottle lines with heat-activated frangible films.
Japan
Third-party logistics operators in Tokyo and Osaka require irreversible visual evidence for premium electronics and luxury goods shipments. METI traceability guidelines for high-value consumer products elevate authentication specifications for pressure-sensitive substrates. The Chubu region around Nagoya concentrates electronics contract manufacturing where RFID-NFC convergence opens new label integration protocols.
United States
FDA Drug Supply Chain Security Act track-and-trace requirements mandate unit-level tamper verification across prescription drug packaging lines. Generic drug manufacturers in New Jersey and Pennsylvania face steep retrofit costs upgrading legacy bottle and blister equipment. The Research Triangle pharmaceutical cluster in North Carolina accelerates qualification cycles for multi-layer security constructions.
India
CDSCO import label compliance tightening creates extended qualification timelines for export-oriented generic drug packers. Small-molecule manufacturers in Hyderabad and Ahmedabad retrofit high-throughput vial lines with 0.05 mm thickness tolerance seals. Gujarat's pharmaceutical formulation belt concentrates contract packaging capacity serving regulated European and North American markets.
Brazil
E-commerce logistics networks in São Paulo and Rio de Janeiro now require tamper proof tapes for high-value parcel authentication. ANVISA pharmaceutical serialization regulations align with international track-and-trace standards, elevating substrate performance specifications. The São Paulo state industrial corridor hosts contract packers serving multinational pharmaceutical brands with export-compliant packaging lines.
Global Tamper Evident Labels Market Competitive Environment
European producers anchor the premium substrate tier; East Asian specialists hold scale positions in pressure-sensitive formulations. The vendor base stratifies across integrated adhesive-substrate converters, precision coating specialists, and RFID-embedded solution providers. Three archetypes dominate: multi-layer construction specialists serving pharmaceutical serialization mandates, direct thermal printing converters capturing retail pharmacy distribution, and RFID-NFC integrators targeting electronics traceability. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification timelines compress.
Among North American material science conglomerates, 3M and Avery Dennison Corporation occupy positions spanning adhesive chemistry through finished label architectures. UPM Raflatac anchors European adhesive R&D integration for pharmaceutical contract manufacturers. Tesa SE exemplifies the precision coating specialist archetype with German-engineered substrate validation protocols. These named entities represent the competitive density around multi-layer bottle seal constructions and void-pattern authentication technologies.
| Leading Market Players |
|---|
| UPM Raflatac |
| Brady Corporation |
| 3M |
| Tesa SE |
| Honeywell International |
| Avery Dennison Corporation |
| LINTEC Corporation |
| Essentra PLC |
| CCL Industries |
| Others |
Value Chain & Pricing Dynamics
Backward integration into adhesive chemistry and precision coating operations anchors supply positions for converters serving pharmaceutical serialization mandates, simultaneously insulating margin structures from petrochemical volatility and creating pricing power through substrate certification control.
Pricing Analysis
Volume concentrates in standard pressure-sensitive adhesive stickers for food and beverage applications where price differentiation hinges on volume scale and geographic delivery cost, while premium multi-layer security labels for pharmaceutical vials command 3-5x unit economics driven by ISO 21976 certification tiers and brand premium. Cost compression in the standard tier is intensifying because direct thermal printing substitutes erode pre-printed label demand. Generic drug packers exhibit highest price sensitivity due to thin margin structures, whereas luxury electronics brands prioritize authentication intensity over unit cost.
Supply Chain Analysis
Workforce availability constraints in East Asian manufacturing zones, particularly China's coastal provinces and South Korea's industrial corridors, tether specialty film production to concentrated substrate engineering clusters. Acrylic resin and destructible paper feedstock draw from petrochemical derivatives concentrated in China, Germany, and the United States. Single-source vulnerability persists for holographic film mastering equipment. Distribution runs through converter networks serving contract packers in Germany, Japan, and India with direct thermal printing capabilities displacing legacy pre-printed inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compression across FDA, EMA, and NMPA jurisdictions is forcing substrate qualification timelines that weaker converters cannot absorb, consolidating viable supply positions among capitalized multi-layer construction specialists.
For Market Incumbents: Hedge against direct thermal printing substitution by embedding RFID-NFC authentication layers into pharmaceutical bottle seal portfolios, and anchor capacity expansion in India's Gujarat pharmaceutical belt to capture CDSCO compliance service revenue from export-oriented generic packers facing retrofit cost pressure. For New Entrants and Emerging Players: The gap between premium multi-layer pharmaceutical seals and economy-grade adhesive stickers creates white-space capture opportunity in Brazil's e-commerce logistics authentication segment and Japan's third-party electronics fulfillment networks, with entry via tamper proof tape specialization avoiding ISO 21976 validation barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in precision coating specialists with validated pharmaceutical substrate portfolios and captive adhesive R&D integration. Long-term viability favors converters with regulatory documentation service capabilities spanning FDA, EMA, and NMPA filing support. The signal to watch is CDSCO import label compliance timeline extensions forcing acquisition of qualified substrate suppliers by export-oriented packers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Substrate Certification Investment | ISO 21976 validation accelerates qualification cycles for pharmaceutical contract manufacturers in Germany and the United States. |
| RFID-NFC Integration Partnership | Near-field communication convergence opens electronics traceability protocols for Chubu region contract manufacturers. |
| Backward Integration into Adhesive Chemistry | Captive acrylic formulation production insulates margins from petrochemical input volatility across procurement cycles. |
| Regulatory Documentation Service Expansion | CDSCO filing support creates sticky revenue streams from Indian export-oriented generic drug packers. |
| Direct Thermal Printing Capability Addition | On-demand variable data encoding captures North American retail pharmacy distribution share from pre-printed labels. |
Study Parameters
Independent corroboration across converter operations directors, pharmaceutical packaging engineers, and adhesive R&D specialists underwrites the qualitative findings, validated against customs trade data for pressure-sensitive substrate flows, FDA drug packaging guidance documents, and EMA serialization directive implementation reports, with bottom-up volume builds triangulated against top-down pharmaceutical packaging expenditure estimates.
Comparable historical reference periods spanning pre- and post-EU Falsified Medicines Directive implementation anchor the forecast window, with segmentation modeling across product type, end-use industry, authentication technology, and geographic regulatory cluster. CAGRs derive from regression analysis of procurement volume trajectories against mandate compliance deadlines, incorporating pharmaceutical line retrofit timelines and e-commerce parcel volume growth curves as industry-specific demand drivers.
Inputs from regulatory filing databases and converter capacity announcements were available through the study window; gaps in real-time pharmaceutical packer procurement contract terms introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding mandate enforcement consistency and substrate qualification timeline stability. Material deviation in FDA track-and-trace rulemaking or NMPA import label enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Wash Off Labels Market
Labels
Global Label Adhesive Market
Labels
Global Cryogenic Label Market
Labels
Direct Thermal Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Metallic Labels Market
Labels
Extended Text Labels Market
Labels
Shipping Label Market
Labels
United States Print Label Market
Labels
High Gloss Labels Market
Labels
Pressure Sensitive Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Sleeve Label Market
Labels
Self-Laminating Labels Market
Labels
Label Applicator Market
Labels
Repositionable Labels Market