
 Healthcare and Laboratory Labels Market | 2026-2036
Healthcare and Laboratory Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare and Laboratory Labels Market Insights
Multi-source procurement for thermal transfer ribbons and specialty adhesives is repositioning how contract label converters secure supply chains. Avery Dennison Corporation leverages its polymer science portfolio to dominate high-performance adhesive formulations for cryogenic storage. Brady Corporation anchors its position through deep specialization in laboratory identification systems that withstand autoclave and chemical exposure cycles.
Healthcare and laboratory labels are pressure-sensitive or shrink-sleeve substrates engineered to maintain legibility across sterilization, refrigeration, and chemical contact, typically incorporating thermal-transfer-receptive coatings or laser-markable top layers for variable data durability. Specimen labels and medication labels carry the highest structural growth momentum, as diagnostic laboratories and hospital pharmacies face escalating barcode granularity requirements for sample chain-of-custody and unit-dose verification. Polyester and polypropylene substrates command premium placement due to their resistance to moisture, solvents, and temperature cycling in clinical environments.
The FDA enforces Unique Device Identification and label legibility standards for medical devices, while the EU MDR mandates expanded label content and symbol harmonization across member states; both frameworks directly dictate substrate selection, print verification investments, and compliance documentation burdens for suppliers. ISO 15223-1 and IEC 62304 standards further constrain symbol design and software-controlled label production systems. Stakeholders must monitor regulatory divergence between FDA and EMA labeling requirements as a primary determinant of regional manufacturing footprint and product qualification costs.
Market Dynamics
Serialized track-and-trace mandates are compressing label qualification timelines while forcing converters to upgrade verification infrastructure, fundamentally altering how substrate specifications get locked into manufacturing contracts.
Growth Catalysts
- FDA Unique Device Identification:Medical device manufacturers must embed permanent machine-readable identifiers on device labels and packages, expanding demand for laser-markable films and thermal-transfer substrates that survive sterilization cycles.
- Diagnostic laboratory consolidation:Large reference laboratories and hospital networks are standardizing on high-density barcode formats for specimen tracking, pulling premium polyester labels into high-throughput automated workflows.
- Cryogenic storage expansion:Biobanking and cell therapy manufacturing require adhesive formulations that maintain tack at minus 196 degrees Celsius, opening specialized substrate development programs.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyester resin prices fluctuate with crude oil derivatives, squeezing converter margins on fixed-price hospital contracts.
- Specialty adhesive supply concentration:High-performance acrylic and silicone adhesive production clusters in Germany and the United States, creating geographic vulnerability for Asian label converters.
- Legacy thermal transfer ribbon incompatibility:New high-density barcode substrates often fail with existing ribbon formulations, forcing parallel hardware upgrades that delay infrastructure refresh decisions.
Strategic Opportunities
- Indian diagnostic network expansion:The country's national health mission is digitizing district hospital laboratories, creating first-mover advantage for converters establishing localized production.
- Radio-frequency identification convergence:Embedding passive RFID inlays within pressure-sensitive labels enables real-time specimen location tracking without line-of-sight scanning.
- EU MDR symbol harmonization:The expanded content requirements for medical device labels favor converters with automated multi-language print-and-verify systems capable of dynamic symbol insertion.
Industry Challenges
- Print verification engineering talent scarcity:Machine vision system integration for 100% inline barcode grading requires scarce automation specialists, extending commissioning timelines for new production lines.
- Multi-jurisdiction qualification burden:Labels serving both FDA and EMA markets must simultaneously satisfy divergent symbol size, contrast ratio, and durability test protocols, multiplying documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare and Laboratory Labels Market |
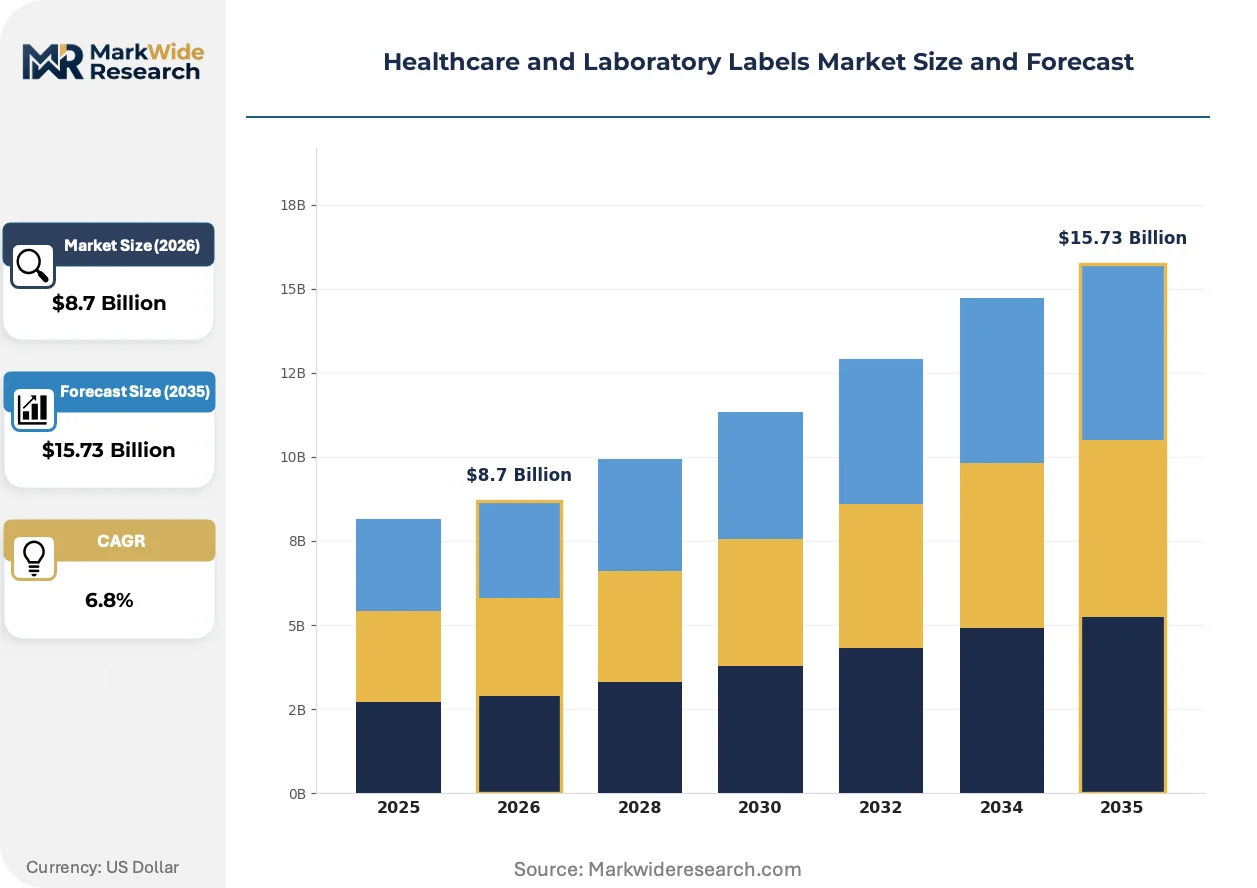
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Asset Labels, Chemical Labels, Specimen Labels, Medication Labels Application: Clinical Settings, Laboratory Use, Inventory Management, Patient Care Material: PVC, Paper, Polyester, Polypropylene Printing Technology: Thermal Transfer, Inkjet, Laser, Direct Thermal |
| Companies Covered | CCL Industries Inc., Zebra Technologies Corporation, Avery Dennison Corporation, Brady Corporation, SATO Holdings Corporation, 3M Company, Schreiner Group, Cardinal Health, Multi-Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare and Laboratory Labels Market Trends and Innovations
Digital printing architectures are collapsing minimum order quantities while enabling variable data density that serialized mandates demand, compressing the traditional offset-to-digital transition timeline in healthcare labeling.
Laser-markable coating technology is electrifying substrate development programs at specialty film manufacturers. These coatings enable permanent, abrasion-resistant variable data inscription without thermal transfer ribbons or ink. Contract manufacturers of implantable devices are adopting laser-markable labels at accelerated pace to eliminate consumable compatibility risks in cleanroom environments. This electrifying shift is compressing demand for traditional thermal transfer ribbon supply chains while expanding capital equipment markets for fiber laser marking systems.
EU MDR implementation timelines are forcing medical device label content expansion across European manufacturing footprints. The regulation mandates inclusion of device-specific safety and performance information alongside standardized symbols, increasing label surface area requirements by 30-40% for many product categories. Cardiovascular and orthopedic device manufacturers operating in Germany, Ireland, and Switzerland are responding by migrating from pressure-sensitive labels to extended-content booklet labels or multi-ply constructions.
Hospital pharmacy unit-dose repackaging is consolidating procurement authority into centralized pharmacy operations rather than decentralized nursing units. This concentration shifts volume toward converters capable of validated serialization, aggregation, and pedigree documentation for medication adherence packaging. The United States health system exhibits this pattern most acutely, with integrated delivery networks negotiating multi-year sole-source agreements that bundle label supply with compliance data services.
Healthcare and Laboratory Labels Market Segmentation
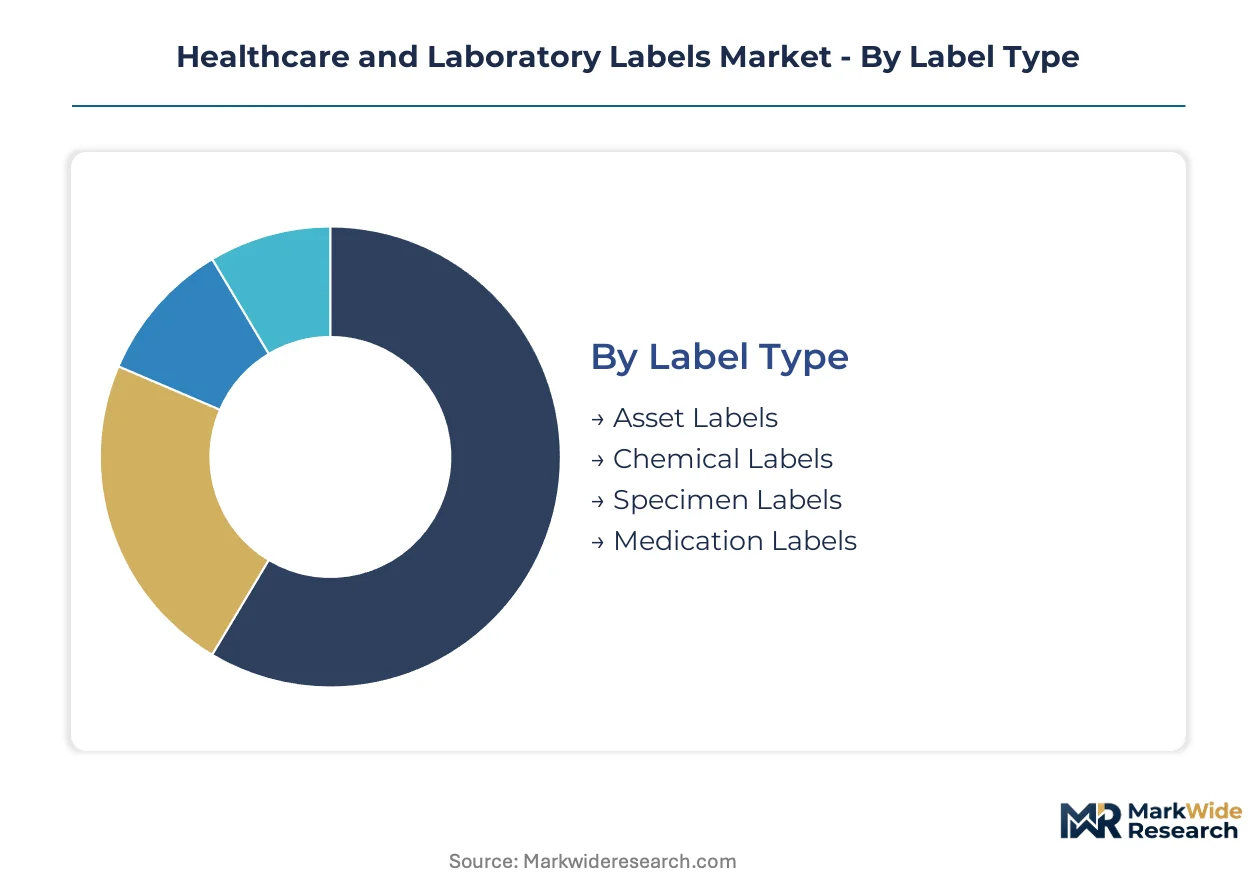
Label segmentation in healthcare and laboratory markets reflects divergent durability requirements across sterilization cycles, chemical exposure, and temperature extremes. Material selection and printing technology choices directly determine compliance eligibility for FDA Unique Device Identification and EU MDR mandates.
Label Type:
Standalone identification labels operate independently of device packaging, while embedded formats integrate directly with primary containers or instruments.
- Specimen Labels:Polyester or polypropylene substrates with cryogenic-grade adhesives maintain barcode legibility through freeze-thaw cycles in biobanking workflows. Diagnostic laboratory networks in Germany and the United States are standardizing high-density formats for automated specimen tracking systems.
- Medication Labels:Thermal-transfer-receptive coatings enable serialized unit-dose verification for hospital pharmacy repackaging operations. Centralized procurement by integrated delivery networks is compressing supplier qualification timelines for these applications.
- Asset Labels:Durable substrates track medical equipment through sterilization and maintenance cycles in hospital inventory systems.
- Chemical Labels:Solvent-resistant adhesives and overlaminates withstand reagent exposure in analytical laboratories and manufacturing cleanrooms.
Specimen labels lead volumes today; medication labels are gaining share fastest.
Application:
Cost tiering separates high-compliance clinical environments from lower-intensity inventory operations, with pricing scaling alongside validation documentation requirements.
- Laboratory Use:Cryogenic storage labels and chemical-resistant formats command premium positioning due to specialized adhesive development for minus 196 degrees Celsius conditions. Cell therapy manufacturing expansion in Switzerland and Singapore is accelerating substrate qualification programs.
- Clinical Settings:Sterilization-indicating labels and autoclave-resistant formats serve operating room and central sterile supply departments. EU MDR symbol harmonization is expanding surface area requirements for device labeling in cardiovascular and orthopedic applications.
- Patient Care:Wristband and bedside identification formats prioritize human-readable content alongside barcode durability through patient mobility.
- Inventory Management:Standard polyester and paper labels track consumables and equipment without exposure to extreme processing conditions.
Laboratory use commands the highest margins; clinical settings show the steepest expansion trajectory.
Material:
Supply concentration for specialty films and adhesives clusters in Germany and the United States, creating geographic sourcing vulnerability for Asian converters.
- Polyester:Biaxially oriented polyethylene terephthalate delivers dimensional stability and chemical resistance for thermal transfer printing in automated laboratory workflows. Reference laboratories in the United States are migrating from paper to polyester for high-throughput specimen processing.
- Polypropylene:Oriented polypropylene films offer moisture resistance and conformability to curved surfaces for vial and tube labeling in diagnostic applications.
- PVC:Flexible vinyl formulations serve short-duration applications with moderate chemical exposure requirements.
- Paper:Uncoated and coated paper stocks retain position in dry-environment inventory and documentation applications with limited durability demands.
Polyester dominates premium positioning; polypropylene is climbing the fastest on cost-performance optimization.
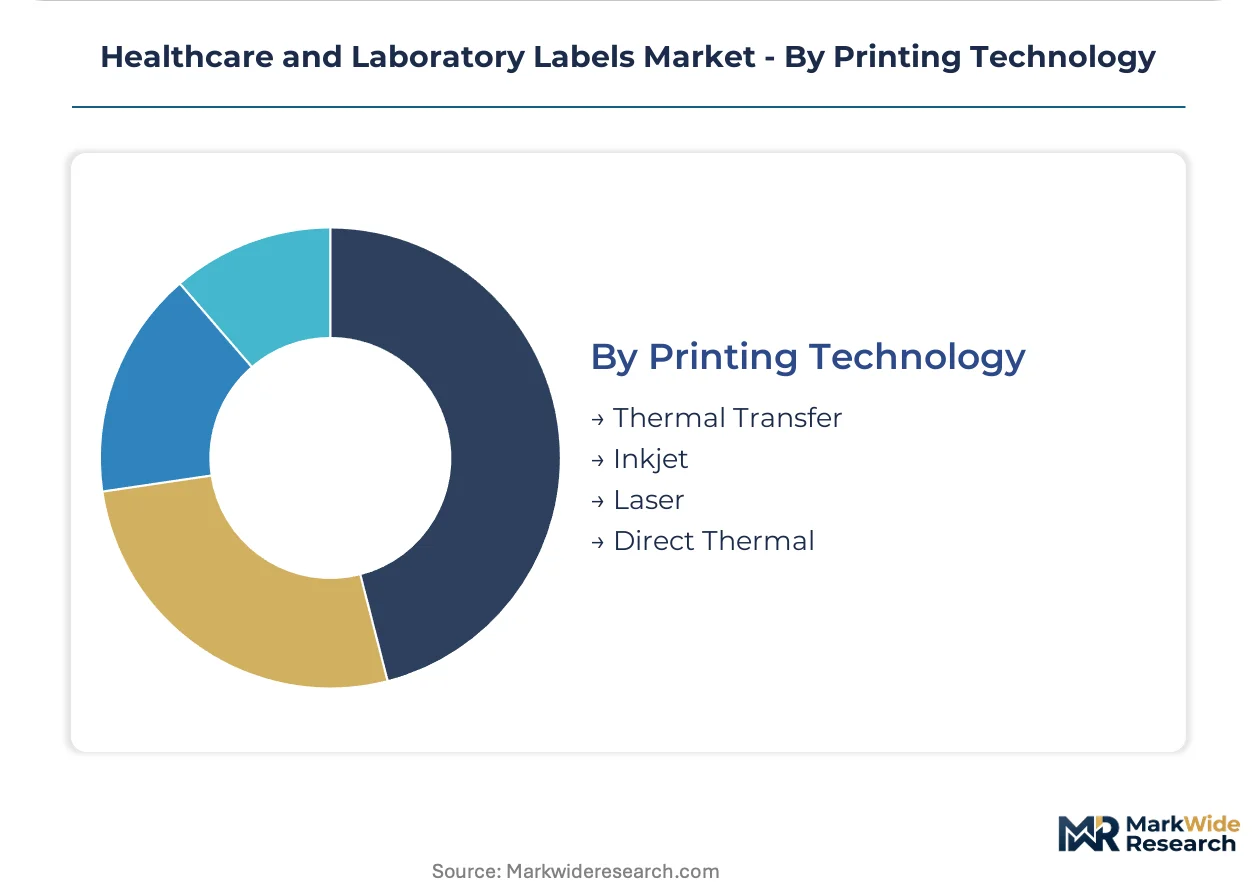
Printing Technology:
Customer type segmentation separates high-volume automated production from small-batch clinical customization, with technology choice locking in substrate and ribbon supply relationships.
- Thermal Transfer:Wax-resin and resin ribbon formulations produce abrasion-resistant images on polyester and polypropylene for long-term specimen and device identification. Legacy ribbon incompatibility with new high-density substrates is forcing parallel hardware upgrades in contract manufacturing.
- Laser:Markable coatings enable permanent variable data inscription without consumables, eliminating contamination risks in implantable device cleanrooms. Fiber laser system adoption is accelerating in cardiovascular device manufacturing.
- Inkjet:Piezoelectric and thermal inkjet systems serve short-run color labeling with lower capital requirements than laser or thermal transfer infrastructure.
- Direct Thermal:Chemically treated substrates produce images without ribbon, limited to short-duration applications where heat and light exposure remains controlled.
Thermal transfer retains installed base dominance; laser marking is expanding most quickly on consumable elimination benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's diagnostic laboratory networks and contract manufacturing clusters anchor the most intensive label infrastructure upgrades worldwide, driven by EU MDR serialization mandates and cryogenic biobanking expansion.
United States
Hospital pharmacy consolidation and integrated delivery network centralization are pulling premium polyester labels into high-throughput medication repackaging workflows. FDA Unique Device Identification enforcement compels cardiovascular and orthopedic device manufacturers in Minnesota and Massachusetts to migrate toward laser-markable substrates for permanent traceability. The Boston-Cambridge biotech corridor hosts accelerated qualification programs for cryogenic-grade adhesive formulations serving cell therapy manufacturing.
Germany
Diagnostic laboratory networks in Bavaria and North Rhine-Westphalia are standardizing high-density barcode formats for automated specimen tracking systems. EU MDR implementation timelines force medical device manufacturers in Baden-Württemberg to expand label surface area by 30-40% through booklet-label constructions. The country's specialty adhesive production clusters in Hesse create geographic sourcing concentration for acrylic and silicone formulations.
Switzerland
Cell therapy manufacturing expansion in Basel and Zurich accelerates substrate qualification programs for minus 196 degrees Celsius storage conditions. Swissmedic device registration requirements align with EU MDR symbol harmonization standards, compelling label content expansion for implantable device manufacturers. The Lake Geneva biomanufacturing corridor hosts concentrated demand for cleanroom-compatible laser-markable coatings.
China
NMPA medical device registration reforms are incrementally converging toward international traceability standards, stimulating domestic label converter investment in verification infrastructure. Diagnostic laboratory digitization under the national health mission creates procurement concentration in Shanghai and Beijing hospital networks. Yangtze River Delta contract manufacturers face pressure to qualify polyester substrates for export markets alongside domestic production.
India
The national health mission's district hospital laboratory digitization program creates first-mover positioning for converters establishing localized production capacity. CDSCO medical device rules are tightening label content requirements for imported and domestically manufactured devices alike. Maharashtra and Karnataka host emerging diagnostic network consolidation that pulls standard-format specimen labels into automated workflows.
Healthcare and Laboratory Labels Market Competitive Landscape
Global majors compete with regional champions across substrate formulation and verification system integration, producing a tiered structure where adhesive chemistry specialization separates premium positioning from commodity supply. Three archetypes dominate: polymer science conglomerates controlling high-performance adhesive platforms, identification systems specialists with deep automation integration capabilities, and regional converters leveraging proximity to diagnostic laboratory networks. Competitive moves concentrate on strategic partnerships for RFID inlay embedding and geographic expansion into Indian diagnostic network procurement.
Within the polymer science tier, Avery Dennison Corporation exemplifies formulation dominance for cryogenic storage applications, while Brady Corporation anchors laboratory identification specialization through autoclave and chemical exposure expertise. CCL Industries Inc. occupies a position spanning pharmaceutical serialization and medical device booklet-label constructions. These three entities represent distinct competitive vectors: adhesive formulation leadership, environmental durability specialization, and regulatory content complexity management.
| Leading Market Players |
|---|
| CCL Industries Inc. |
| Zebra Technologies Corporation |
| Avery Dennison Corporation |
| Brady Corporation |
| SATO Holdings Corporation |
| 3M Company |
| Schreiner Group |
| Cardinal Health |
| Multi-Color Corporation |
| Others |
Pricing and Supply Chain Analysis
Polypropylene resin price indices cascade through converter margins into three-tier pricing structures across premium, standard, and economy levels. Hospital pharmacy contracts with fixed-price terms compress converter profitability when petrochemical feedstock costs spike.
Pricing Analysis
Input-cost pass-through from acrylic and silicone adhesive formulations stratifies pricing across cryogenic-grade, sterilization-resistant, and inventory-grade tiers. Price differentiation hinges on FDA compliance certification and volume scale, with integrated delivery networks extracting steep discounts through multi-year sole-source agreements. Cost compression in standard polyester labels is intensifying because Asian converters compete aggressively on hospital consumables contracts. Contract manufacturing organizations exhibit the lowest price sensitivity, while district hospital laboratories in emerging markets remain highly cost-conscious.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from integrated delivery networks and reference laboratory chains, while distributor networks serve fragmented clinical settings. Specialty adhesive production clusters in Germany and the United States, with polyester film manufacturing concentrated in China and South Korea. Raw material dependencies encompass petrochemical resins, thermal transfer ribbon coatings, and laser-markable film substrates. Single-source vulnerability in high-performance acrylic adhesive supply creates geographic concentration risk for Asian label converters. Distribution runs through medical supply distributors, GPO contracts, and direct converter relationships with device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost differentials between FDA and EMA jurisdictions create geographic-arbitrage opportunities for converters optimizing manufacturing footprints. Labor cost spreads favor selective capacity placement in India for domestic diagnostic network supply.
For Market Incumbents: Deepen adhesive formulation specialization for minus 196 degrees Celsius cryogenic applications to defend against polymer science conglomerates entering from adjacent medical packaging markets. Expand verification infrastructure partnerships in Germany to capture EU MDR-driven label content expansion demand. Secure captive supply of thermal transfer ribbon formulations to insulate margins from petrochemical volatility.
For New Entrants and Emerging Players: District hospital laboratories in India's national health mission digitization program represent an underserved buyer archetype with limited incumbent presence. Establish localized production in Maharashtra or Karnataka to bypass import logistics costs and CDSCO registration timelines. Pursue specimen label contracts as the entry wedge, then expand into medication labels through pharmacy network relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where verification infrastructure investments exceed standalone converter cash flow generation capacity. The market favors five-to-ten-year positions in regional champions with adhesive chemistry specialization and hospital GPO contract relationships. Acquisition targets include mid-scale converters with EU MDR qualification documentation and established Basel or Zurich cell therapy manufacturing relationships. Watch laser-markable coating adoption rates in cardiovascular device manufacturing as the inflection signal for thermal transfer ribbon demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Adhesive Formulation Investment | Captures cell therapy manufacturing expansion in Switzerland and Singapore biomanufacturing corridors. |
| Multi-Language Print-and-Verify System Deployment | Addresses EU MDR symbol harmonization requirements for cardiovascular and orthopedic device labels. |
| RFID Inlay Embedding Partnership | Enables real-time specimen tracking for diagnostic laboratories without line-of-sight scanning infrastructure. |
| Indian Localized Production Establishment | Positions for national health mission district hospital laboratory digitization procurement concentration. |
| Laser Marking Equipment Integration | Eliminates thermal transfer ribbon compatibility risks in implantable device cleanroom environments. |
Research Methodology
Multiple input streams — primary interviews with label converter operations managers, hospital GPO contracts managers, and biomedical engineers, alongside secondary validation through FDA UDI guidance documents, EU MDR implementation timelines, and hospital procurement databases — were reconciled through bottom-up and top-down triangulation. Stakeholder interviews encompassed adhesive formulation chemists, thermal transfer ribbon manufacturers, diagnostic laboratory network procurement directors, and medical device regulatory affairs specialists. Secondary sources included SEC filings of listed label converters, ISO 15223-1 symbol harmonization documentation, and customs trade data for polyester and polypropylene film imports.
Historical volume trajectories were cross-referenced against expert panel inputs to construct projection frameworks across the analysis window. Segmentation dimensions modeled encompassed label type, application intensity tier, material grade, and printing technology platform. CAGRs were derived from growth rate reconciliation across end-use demand drivers and supply-side capacity expansion plans. Industry-specific forecast inputs incorporated EU MDR implementation phase timelines and FDA UDI enforcement escalation patterns.
Underlying measurement precision varies by segment; specimen and medication labels carry tighter precision than asset and inventory management categories due to more consolidated buyer structures. Forecasts reflect assumptions regarding regulatory implementation adherence, petrochemical price stability, and diagnostic laboratory automation adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Cryogenic Label Market
Labels
Wash Off Labels Market
Labels
Water Dissolvable Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
GCC Labels and Release Liners Market
Labels
Tags Market
Labels
Label Applicator Market
Labels
Global Label Adhesive Market
Labels
Ethical Label Market
Labels
Barcode Label Printer Market
Labels
BOPP Labels Market
Labels
Global Laminated Labels Market
Labels
Waterproof and Weatherproof Label Market
Labels
Holographic Scratch-Off Labels Market
Labels
Polyester Labels Market
Labels
Shrink Sleeve Labels Market